
 Global Stainless Steel Forgings Market | 2026-2036
Global Stainless Steel Forgings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stainless Steel Forgings Market Foresight
NORSOK M-650 is unwinding the competitive landscape for offshore-grade stainless steel forgings, disqualifying suppliers lacking third-party witness of qualification testing. Precision Castparts Corp. leverages its aerospace metallurgy heritage to sustain premium positioning across demanding alloy grades. Bharat Forge Limited anchors its expansion on India's domestic defense and energy infrastructure buildout. voestalpine AG differentiates through vertical control from melt shop to finished forging across European industrial corridors.
Stainless steel forgings are shaped metal components produced from austenitic, martensitic, duplex, or precipitation-hardening grades through compressive deformation above recrystallization temperature, delivering grain flow alignment and fatigue resistance critical for pressure-boundary and structural applications. Closed die forgings command the dominant share of value given their net-shape efficiency and material utilization in high-volume aerospace and energy production. Isothermal forging represents the fastest-advancing technology segment as turbine disk geometries grow more complex and alloy systems more temperature-sensitive. Ring forgings occupy concentrated margin pools in large-diameter pressure vessel and bearing applications where few producers maintain the requisite ring mill capacity.
ASME Boiler and Pressure Vessel Code Section VIII governs qualification pathways for pressure-retaining forgings in US power and petrochemical installations, while EU Pressure Equipment Directive 2014/68/EU mandates CE-marked conformity assessment for European supply. India's BIS certification under IS 6911 and IS 2002 shapes domestic sourcing requirements for stainless grades in critical infrastructure. Stakeholders must monitor how dual carbon mandates from China's MEE and Europe's F-Gas Regulation redirect alloy selection toward lean duplex and nitrogen-strengthened grades that reduce lifecycle emissions without sacrificing corrosion performance.
Market Dynamics
Isothermal forging is compressing cycle times for superalloy turbine disks while NORSOK M-650 qualification barriers are eliminating marginal suppliers from offshore energy contracts.
Growth Catalysts
- Defense aerospace procurement:Multi-year fighter jet and rotorcraft programs in India, the US, and Norway are sustaining order backlogs for high-strength martensitic and precipitation-hardening grades.
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is redirecting heat exchanger specifications toward nitrogen-strengthened austenitic forgings with lower lifecycle emissions.
- Closed die efficiency:Net-shape forming is reducing machining waste ratios below 15% in high-volume automotive and energy component runs.
Market Restraints
- Nickel and molybdenum price volatility:Alloy surcharges swing 20-40% quarterly, compressing margin visibility for long-delivery forging contracts.
- Ring mill capacity concentration:Only six operational ring mills worldwide can produce bearing-quality forgings above 4 meters diameter, creating single-source risk.
- ASME Section VIII compliance timelines:Third-party witness requirements extend qualification cycles 18-24 months for new pressure-boundary suppliers.
Strategic Opportunities
- India western industrial corridor:Pune and Vadodara clusters are consolidating defense and energy demand, enabling localized melt-to-forge investments.
- Lean duplex substitution:2101 and 2304 grades are penetrating coastal infrastructure and desalination applications at 30% lower alloy cost than 316L.
- Digital thread integration:Blockchain-tracked material certificates are reducing qualification friction for cross-border aerospace supply chains.
Industry Challenges
- Isothermal press operator scarcity:Temperature-window control within 25°C demands metallurgists with 10+ years titanium and nickel superalloy experience.
- Dual certification burden:Suppliers must maintain parallel NORSOK M-650 and ASME qualifications, doubling audit and witness costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stainless Steel Forgings Market |
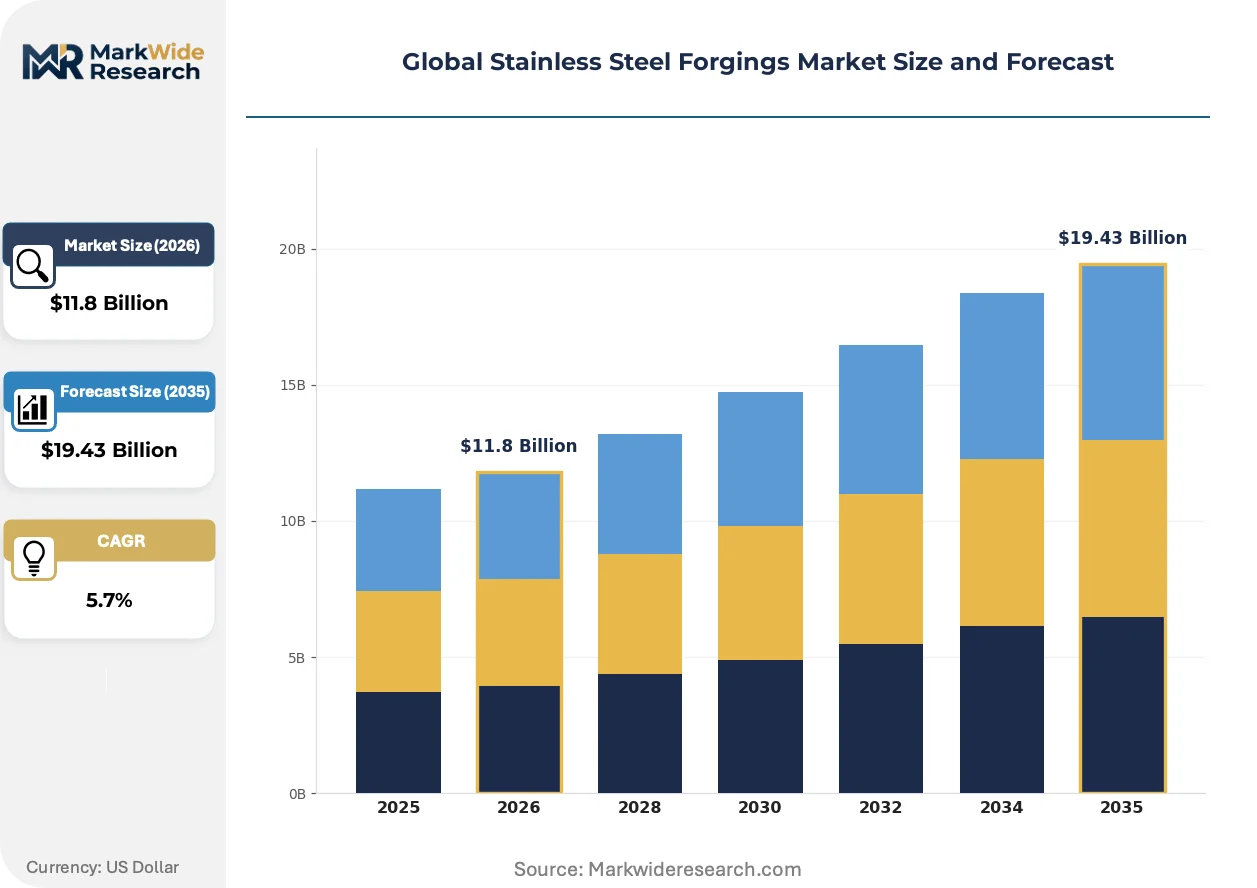
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Die Forgings, Closed Die Forgings, Ring Forgings, Impression Die Forgings Technology: Hot Forging, Cold Forging, Warm Forging, Isothermal Forging Application: Aerospace Components, Power Generation Equipment, Shipbuilding Parts, Heavy Machinery Elements End User Industry: Oilfield Equipments, Defense & Aerospace, Energy Sector, Machine Manufacturing |
| Companies Covered | Scot Forge Company, Precision Castparts Corp., Allegheny Technologies Incorporated, voestalpine AG, Aubert & Duval, Bharat Forge Limited, Howmet Aerospace Inc., ArcelorMittal S.A., Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stainless Steel Forgings Market Shifts & Advancements
Additive manufacturing is reshaping near-net-shape competition, while digital twin validation is compressing first-article approval cycles for complex geometries.
Electro-slag remelting (ESR) and vacuum arc remelting (VAR) tandem processing is supplanting single-melt practice for critical rotating components. Aerospace turbine OEMs now mandate triple-melt pedigree for disk applications above 700°C service. This metallurgical escalation is compressing the qualified supplier base to melt shops with captive remelt capacity.
China's MEE dual carbon mandates are tightening scrap traceability requirements for stainless production. Forced closure of induction furnaces without emissions controls is redirecting semi-finished supply toward electric arc melt shops with ISO 14064 verification. European importers are responding with supplier audits that verify renewable power shares in Chinese melt operations.
Consolidated procurement through integrated energy majors is displacing fragmented EPC contractor purchasing. TotalEnergies, Equinor, and Shell now specify forgings directly, bypassing traditional distributor channels. This concentration is most visible in Norwegian North Sea projects where NORSOK M-650 qualification is negotiated at corporate level rather than project level.
Global Stainless Steel Forgings Market Segmentation
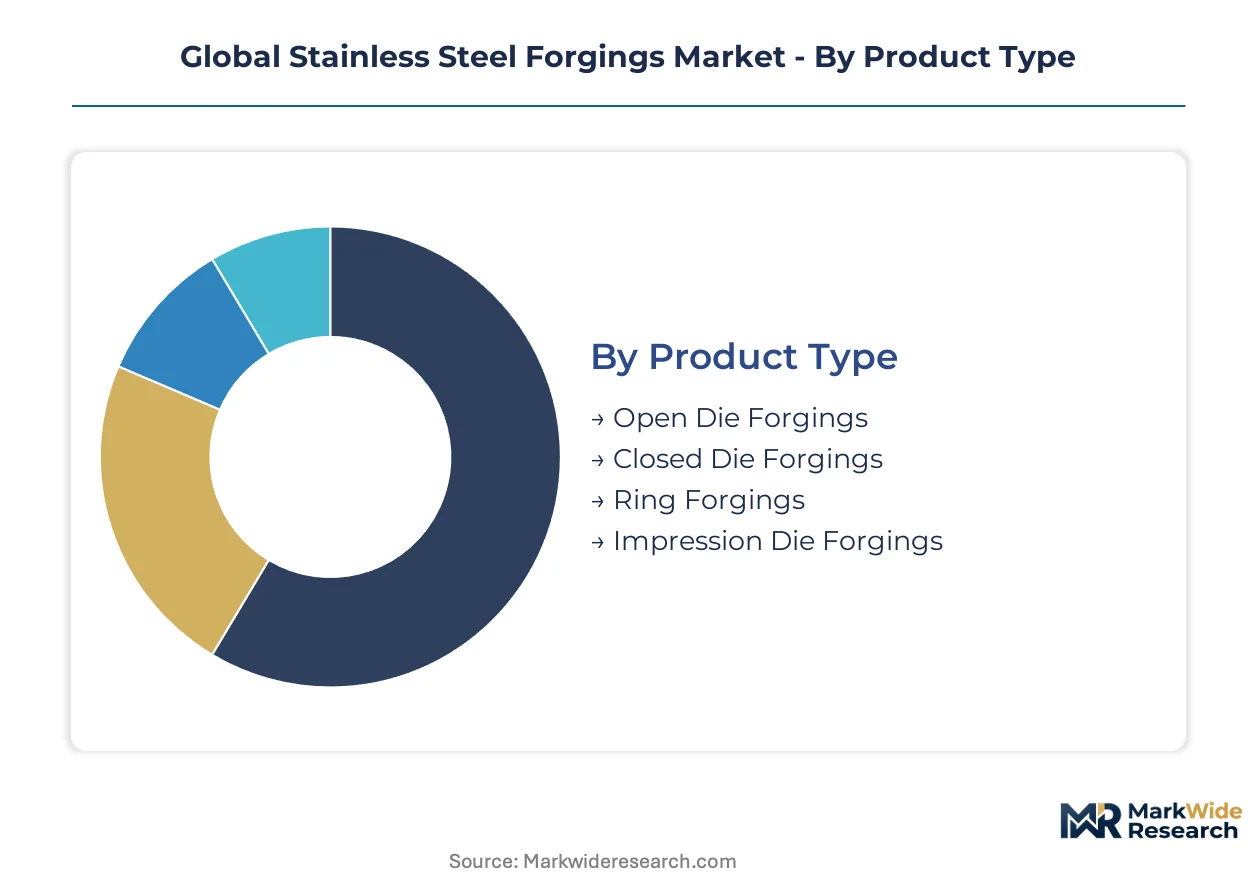
Stainless steel forgings exhibit divergent margin profiles across forming methods and thermal processing routes. Aerospace qualification barriers and offshore certification requirements create tiered pricing structures that reward metallurgical sophistication over commodity volume.
Product Type:
Margin pools concentrate in precision net-shape forming where material utilization and machining avoidance justify premium positioning.
- Closed Die Forgings:Compress austenitic and martensitic grades between shaped dies to achieve near-net geometries with grain flow optimized for fatigue-critical applications. Demand clusters in aerospace turbine disks and automotive transmission components where ASME and NADCAP qualifications filter supplier pools.
- Ring Forgings:Radial compression on ring mills produces seamless cylindrical sections for pressure vessels and bearing races above two meters diameter. Only six operational mills worldwide can deliver bearing-quality forgings beyond four meters, creating concentrated margin capture in Norwegian North Sea and Indian defense contracts.
- Open Die Forgings:Hammer or press forming between flat dies shapes large custom sections for shafts and bars. India's western industrial corridor around Pune anchors regional demand for defense crankshafts and power generation rotors.
- Impression Die Forgings:Partial die enclosure balances geometric complexity with tooling economy for medium-volume runs. Machine manufacturing in Germany and Japan sustains order flow for crankshafts and connecting rods.
The dominant share belongs to Closed Die Forgings, while Ring Forgings is closing the gap fastest.
Technology:
Cost tiers separate thermal processing routes by energy intensity, cycle duration, and operator skill requirements.
- Isothermal Forging:Maintains die and workpiece within 25°C across superalloy forming windows, enabling complex turbine disk geometries in titanium and nickel-based grades. Boeing and Safran procurement specifications now mandate this route for rotating components above 700°C service.
- Hot Forging:Deformation above recrystallization temperature remains the volume workhorse for austenitic stainless grades in automotive and general machinery. China's electric arc melt shops with ISO 14064 verification supply semi-finished feedstock to European forgers facing MEE dual carbon audit requirements.
- Cold Forging:Room-temperature deformation of annealed austenitic grades yields high surface finish and dimensional precision for fasteners and small automotive components. Energy consumption runs 40% below hot routes, attracting sustainability-focused procurement from European automotive OEMs.
- Warm Forging:Intermediate temperatures between cold and hot routes balance formability with dimensional control for medium-complexity geometries. Japanese machine tool builders specify warm-formed spindle components for hybrid machining centers.
Hot Forging retains volume leadership, though Isothermal Forging commands the steepest expansion trajectory.
Application:
Customer type differentiation separates specification-intensive aerospace from price-sensitive heavy machinery procurement.
- Aerospace Components:Turbine disks, compressor blades, and structural fittings demand triple-melt pedigree with ESR-VAR tandem processing. FAA and EASA airworthiness directives mandate material traceability through blockchain-tracked certificates.
- Power Generation Equipment:Steam turbine rotors, generator shafts, and nuclear pressure vessels require ASME Section VIII or PED 2014/68/EU compliance with third-party witness of qualification testing. India's BIS certification under IS 6911 shapes domestic sourcing for critical infrastructure.
- Shipbuilding Parts:Propeller shafts, rudder stocks, and deck hardware in duplex grades resist seawater corrosion. Norwegian yards enforce NORSOK M-650 qualification at corporate procurement level.
- Heavy Machinery Elements:Gears, shafts, and structural castings in standard austenitic grades serve construction and mining equipment with less stringent pedigree requirements.
Aerospace Components holds the premium position, while Power Generation Equipment is expanding most quickly.
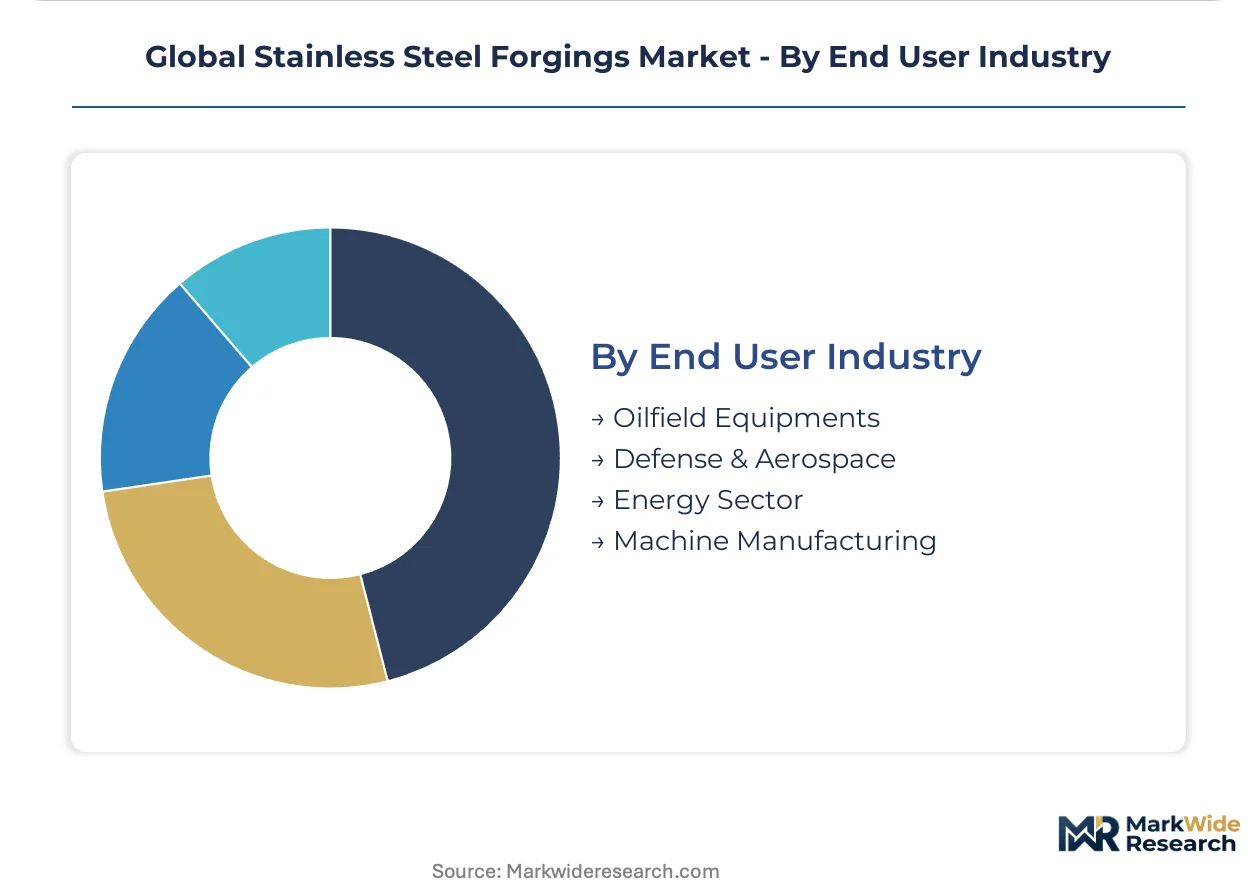
End User Industry:
Supply concentration varies by sector-specific certification burdens and procurement consolidation patterns.
- Defense & Aerospace:Multi-year fighter jet and rotorcraft programs in India, the US, and Norway sustain order backlogs for precipitation-hardening and martensitic grades. Bharat Forge and Precision Castparts anchor supply through captive melt-to-forge capabilities.
- Energy Sector:Integrated majors including TotalEnergies, Equinor, and Shell now specify forgings directly, bypassing traditional EPC channels. NORSOK M-650 and ASME dual certification requirements compress the qualified supplier base.
- Oilfield Equipments:Wellhead components, valves, and fracturing hardware in sour-service grades face nickel and molybdenum price volatility that swings alloy surcharges 20-40% quarterly.
- Machine Manufacturing:General industrial machinery procurement prioritizes delivery reliability and cost over pedigree depth, opening volume opportunities for Chinese and Indian mid-tier forgers.
Defense & Aerospace commands the dominant share, while Energy Sector is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel underwrites North American energy infrastructure demand for pressure-boundary forgings. India's western industrial corridor leverages the Jawaharlal Nehru Port Trust for European and Middle East export flows. Norway's Troll pipeline system anchors North Sea qualification requirements for sour-service grades.
United States
F-35 fighter jet production and rotorcraft programs sustain order backlogs for precipitation-hardening grades. FAA airworthiness directives mandate blockchain-tracked material certificates for rotating components. The Houston-Gulf Coast corridor concentrates forging demand for petrochemical pressure vessels and offshore wellhead equipment.
Germany
Machine tool builders and automotive transmission manufacturers specify warm-formed spindle components for hybrid machining centers. EU Pressure Equipment Directive 2014/68/EU mandates CE-marked conformity assessment for European supply. The Ruhr industrial basin anchors demand for large-diameter bearing races and generator shafts.
India
Domestic defense procurement and nuclear power infrastructure buildout drive martensitic and austenitic grade consumption. BIS certification under IS 6911 and IS 2002 shapes domestic sourcing requirements for stainless grades in critical infrastructure. Pune and Vadodara clusters consolidate melt-to-forge investments for western industrial corridor demand.
Norway
Equinor and Aker BP direct procurement for North Sea subsea and topside equipment bypasses traditional EPC channels. NORSOK M-650 qualification requirements disqualify suppliers lacking third-party witness of qualification testing. Stavanger and Bergen anchor the supplier ecosystem for offshore-grade duplex forgings in sour-service applications.
China
Electric arc melt shops with ISO 14064 verification supply semi-finished feedstock to European forgers facing MEE dual carbon audit requirements. Forced closure of induction furnaces without emissions controls redirects semi-finished supply toward verified melt operations. Jiangsu and Shandong provinces concentrate forging capacity for pressure equipment and general machinery exports.
Global Stainless Steel Forgings Market Competitive Landscape
Listed leaders compete with private specialists across qualification depth and vertical integration intensity. The supplier base stratifies around metallurgical sophistication rather than commodity scale, with triple-melt pedigree and captive remelt capacity filtering participation in aerospace and offshore energy tiers. Three archetypes dominate: integrated steel majors with melt-to-forge control, aerospace-focused specialists with NADCAP and ASME dual qualifications, and regional champions serving domestic defense and infrastructure procurement. Capacity expansion and strategic partnerships represent the dominant competitive moves as ring mill scarcity and isothermal press operator shortages constrain organic growth.
Among European integrated producers, voestalpine AG exemplifies the steel-major archetype with captive melt shop control through finished forging delivery. Bharat Forge Limited anchors the regional champion position serving India's domestic defense and energy infrastructure buildout. Precision Castparts Corp. occupies the aerospace-specialist tier, leveraging metallurgy heritage across demanding alloy grades. These three represent distinct strategic positioning vectors without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Scot Forge Company |
| Precision Castparts Corp. |
| Allegheny Technologies Incorporated |
| voestalpine AG |
| Aubert & Duval |
| Bharat Forge Limited |
| Howmet Aerospace Inc. |
| ArcelorMittal S.A. |
| Thyssenkrupp AG |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with integrated energy majors lock in both supply access and price visibility for offshore-grade duplex forgings, insulating qualified suppliers from nickel and molybdenum surcharge volatility while marginal producers absorb spot-market swings.
Pricing Analysis
Volume-discount tiering separates aerospace triple-melt pedigree from commodity-grade automotive runs, with NORSOK M-650 and ASME dual certification commanding 40-60% premiums over single-qualified supply. Price differentiation rests on metallurgical sophistication and captive remelt capacity rather than scale alone. Cost compression in standard austenitic grades is intensifying as Chinese electric arc melt shops with ISO 14064 verification expand semi-finished feedstock supply. Automotive transmission procurement shows highest price sensitivity, while defense aerospace programs prioritize qualification depth over unit cost.
Supply Chain Analysis
Inventory cycles for ring mill capacity stretch 18-24 months given only six operational mills worldwide capable of bearing-quality forgings above four meters diameter. Raw material sourcing draws from nickel laterite concentrates in Indonesia and the Philippines, ferrochrome from South Africa, and molybdenum from Chile and the United States. Single-source vulnerability concentrates in large-diameter pressure vessel applications where Norwegian North Sea projects specify corporate-level NORSOK M-650 qualification. Distribution runs through direct procurement by integrated energy majors bypassing traditional EPC distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stainless steel forgings market rewards service-attach models where material certification lifecycle management and blockchain-tracked pedigree verification expand faster than commodity forging volume, creating recurring-revenue streams alongside hardware sales.
For Market Incumbents: Secure captive remelt capacity through backward integration into ESR-VAR tandem processing, defending against aerospace turbine OEMs mandating triple-melt pedigree for rotating components above 700°C service. Deepen ring mill utilization through capacity reservation contracts with Indian defense procurement and Norwegian subsea projects, locking out competitors from scarce large-diameter forging capacity.
For New Entrants and Emerging Players: NORSOK M-650 fast-track qualification through third-party witness partnerships offers entry into Norwegian North Sea sour-service contracts where integrated majors bypass EPC channels. Target India's western industrial corridor around Pune and Vadodara for localized melt-to-forge investments serving domestic defense and nuclear infrastructure buildout, leveraging BIS certification under IS 6911 as a procurement wedge.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aerospace specialists with NADCAP and ASME dual qualifications, where material certificate lifecycle management and digital thread integration generate service-attach income streams. Acquisition candidates with captive isothermal press capacity and 10+ year operator tenure present durable moats against metallurgical escalation in turbine disk applications. Watch for F-35 production rate adjustments and India's nuclear power infrastructure tender awards as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Remelt Capacity | Captive ESR-VAR tandem processing secures triple-melt pedigree for aerospace turbine disk contracts. |
| NORSOK M-650 Fast-Track Qualification | Third-party witness partnerships unlock Norwegian North Sea sour-service procurement bypassing EPC channels. |
| Digital Thread Integration | Blockchain-tracked material certificates reduce qualification friction for cross-border aerospace supply chains. |
| Lean Duplex Grade Substitution | 2101 and 2304 grades penetrate coastal infrastructure at 30% lower alloy cost than 316L specifications. |
| Ring Mill Capacity Reservation | Long-term contracts with Indian defense and Norwegian energy projects lock out competitors from scarce large-diameter forging supply. |
Research Methodology
Desk research of ASME Boiler and Pressure Vessel Code filings, NORSOK M-650 qualification registries, and EU Pressure Equipment Directive conformity assessments preceded structured interviews with forging plant managers, procurement leads at aerospace turbine OEMs, technical metallurgy directors, and aftermarket service heads. Secondary validation drew from customs trade data, SEC 10-K filings of listed steel majors, and ISO certification databases. Bottom-up volume estimates across forming methods and thermal processing routes were triangulated against top-down value projections from regional industrial production indices.
Variance decomposition across product type, technology route, application intensity, and end-user industry concentration shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by current value contribution. Forecast inputs incorporated defense aerospace procurement pipeline visibility from India's Ministry of Defence and US Department of Defense disclosures, alongside nuclear power infrastructure buildout timelines from India's Department of Atomic Energy.
Decision-makers should treat outputs as directional under assumptions of sustained nickel and molybdenum price volatility within historical bands and continued NORSOK M-650 qualification tightening; material deviation in alloy surcharge swings or regulatory harmonization between ASME and EU PED would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Structural Power Composites Market