
 Global Hollow Fiber Filtration Market | 2026-2036
Global Hollow Fiber Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hollow Fiber Filtration Market Foresight
Asian membrane producers is realigning supply chains toward pharmaceutical-grade certification. Toray Industries leverages its polymer chemistry heritage to dominate high-performance polymeric membrane supply. DuPont sustains competitive position through backward integration into specialized fluoropolymer resins. Asahi Kasei anchors its filtration portfolio with hollow fiber modules engineered for bioprocessing purity standards.
Global hollow fiber filtration employs semipermeable capillary membranes with pore sizes typically ranging from 0.01 to 0.1 microns, fabricated through phase inversion or melt-spinning processes to achieve high surface-area-to-volume ratios for selective separation of particles, microorganisms, and macromolecules. Polymeric membranes occupy the largest installed base due to cost scalability and chemical versatility, while ceramic membranes command premium positioning in aggressive chemical processing environments where thermal stability and mechanical durability outweigh capital intensity. Cross-flow systems lead installation preferences in pharmaceutical processing for their fouling mitigation and continuous operation advantages, whereas submerged systems dominate municipal water utilities seeking lower energy footprints and simpler maintenance protocols.
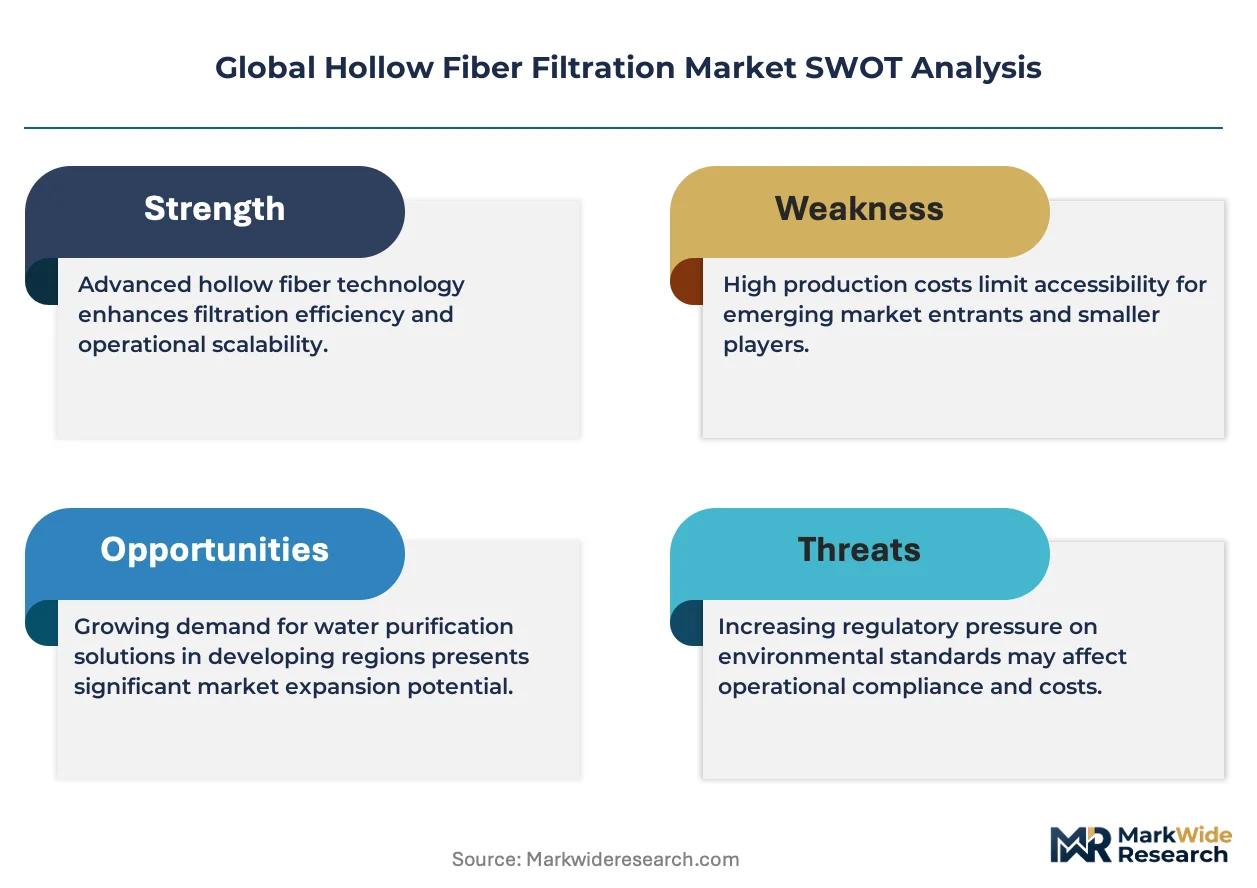
FDA validation guidelines, EU MDR requirements, and ISO 13485 quality management standards collectively govern sterile filtration deployment in biopharmaceutical manufacturing, with regulatory divergence between jurisdictions forcing manufacturers to maintain parallel certification portfolios. The EPA and REACH frameworks additionally constrain material selection in water and chemical processing applications through substance restriction lists and environmental release protocols. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables testing as regulatory agencies harmonize approaches to single-use system qualification.
Market Dynamics
Biopharmaceutical manufacturers are consolidating filtration operations around single-use architectures, forcing membrane suppliers to reconfigure production lines for disposable module formats rather than reusable stainless-steel systems.
Growth Catalysts
- EU MDR sterilization mandates:Medical device regulations now require validated sterile filtration for implantable biologics, compelling contract manufacturers to upgrade membrane infrastructure.
- mRNA platform proliferation:Vaccine producers are scaling lipid nanoparticle purification trains that depend on tangential flow filtration with hollow fiber cassettes.
- China biologics capacity buildout:Domestic CDMOs in Suzhou and Shanghai are importing pharmaceutical-grade membrane systems to replace imported bulk drug substances with local manufacturing.
Market Restraints
- Specialized polymer supply concentration:High-purity PVDF and PES resins for pharmaceutical membranes originate from a limited supplier base in Germany and Japan, exposing buyers to allocation risk.
- Ceramic membrane cost barriers:Alumina and zirconia hollow fibers require capital-intensive sintering furnaces that price out mid-scale bioprocessing facilities.
- FDA validation timeline friction:Extractables and leachables testing protocols for single-use systems extend qualification cycles by 12-18 months versus stainless-steel equivalents.
Strategic Opportunities
- India biosimilar manufacturing:CDSCO regulatory pathways for interchangeable biologics are attracting investment in Mumbai and Hyderabad filtration infrastructure.
- Cell therapy autologous processing:Patient-scale perfusion systems require miniaturized hollow fiber modules that incumbent suppliers have not optimized.
- Water reuse mandates:EPA effluent guidelines for pharmaceutical manufacturing are driving adoption of high-recovery membrane bioreactors in New Jersey and Puerto Rico facilities.
Industry Challenges
- Bioprocess engineering talent scarcity:Membrane system design requires hybrid expertise in polymer science and GMP manufacturing that universities are not producing at scale.
- Legacy equipment integration:Stainless-steel validation protocols from the 1990s conflict with single-use automation architectures, forcing costly parallel documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hollow Fiber Filtration Market |
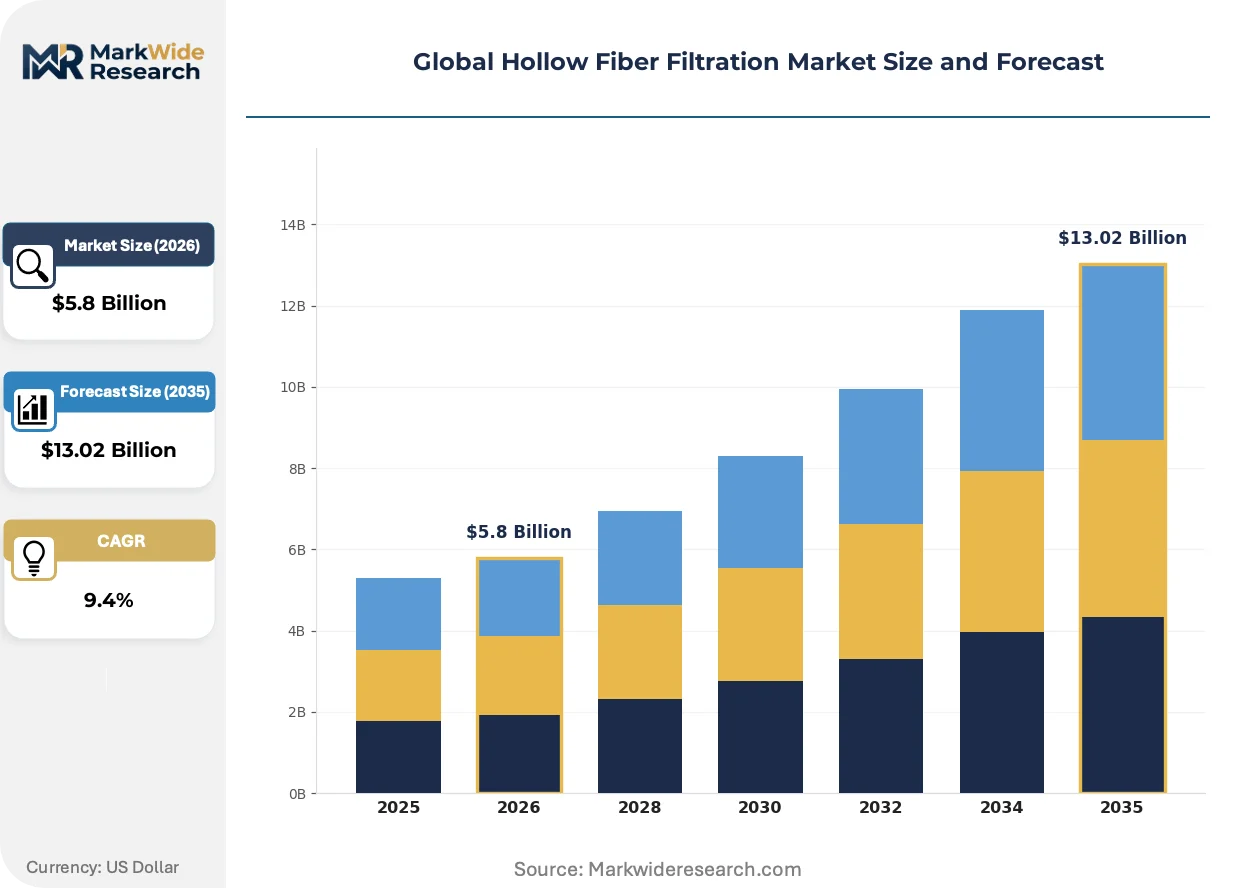
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Membranes, Ceramic Membranes, Stainless Steel Membranes, Composite Membranes Application: Water Purification, Wastewater Treatment, Pharmaceutical Processing, Food & Beverage Production, Chemical Processing End User: Municipal Water Utilities, Biopharmaceutical Manufacturers, Food Processing Units, Chemical Plants Installation Type: Submerged Systems, Side-Stream Systems, Dead-End Systems, Cross-Flow Systems |
| Companies Covered | Toray Industries, Inc., DuPont, Veolia, Asahi Kasei Corporation, Pall Corporation, Repligen Corporation, Danaher Corporation, Sartorius AG, Parker-Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hollow Fiber Filtration Market Shifts & Advancements
Membrane chemistry and module architecture are converging to address biopharmaceutical purity requirements while reducing facility footprint and validation burden.
Modified hydrophilic PVDF membranes with asymmetric pore structures are expanding into continuous bioprocessing applications where protein transmission and viral retention must coexist. Contract manufacturers in Massachusetts and North Carolina are deploying these cassettes in perfusion cell culture systems that operate for 60-day campaigns. The technology is expanding into downstream processing steps previously reserved for depth filtration and chromatography columns.
REACH substance restriction proposals for per- and polyfluoroalkyl substances are forcing membrane producers to reformulate fluoropolymer coatings used in aggressive solvent applications. ECHA consultations in 2023 signaled potential limits on PTFE and PVDF processing aids, compelling suppliers to accelerate bio-based alternatives. German chemical processors are piloting ceramic hollow fibers to preempt dependency on restricted polymer chemistries.
Biopharmaceutical procurement teams are unbundling membrane supply from equipment vendor lock-in, establishing direct qualification relationships with Toray and Asahi Kasei rather than accepting OEM-specified cartridges. Large molecule CDMOs in Switzerland and Singapore are building captive membrane testing laboratories to accelerate vendor qualification. This pattern is most visible in monoclonal antibody manufacturing where annual membrane consumption exceeds single-site validation capacity.
Global Hollow Fiber Filtration Market Segmentation
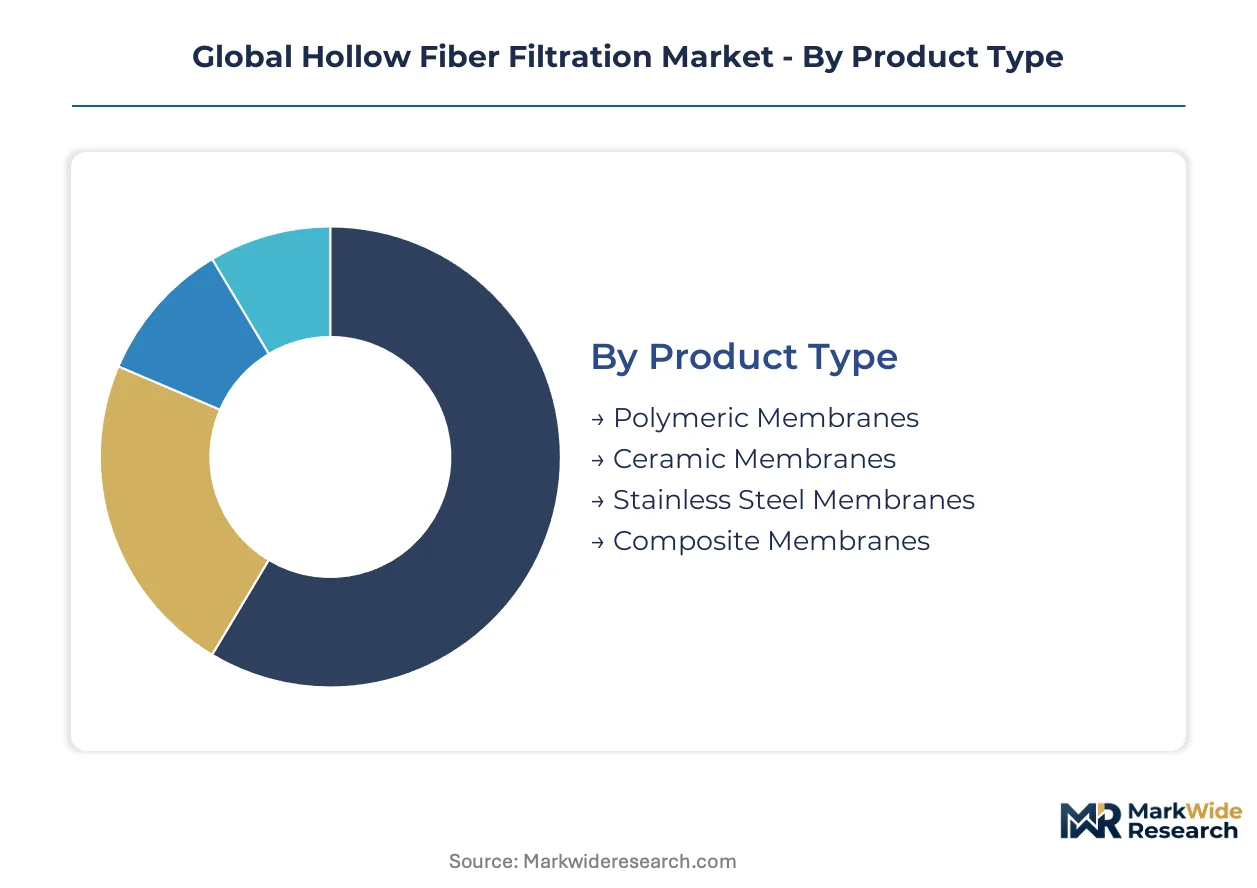
Hollow fiber filtration markets fragment across material chemistry, operational configuration, and regulatory exposure. Procurement teams select segments based on validation burden, chemical compatibility, and scale economics rather than performance specifications alone.
Product Type:
Integration depth varies sharply: polymeric membranes dominate standalone disposable systems, while ceramic and metallic formats embed into permanent infrastructure requiring multi-year amortization.
- Polymeric Membranes:PVDF and PES formulations achieve asymmetric pore structures through phase inversion spinning. Biopharmaceutical manufacturers in Massachusetts and North Carolina specify these for 60-day perfusion campaigns where protein transmission and viral retention must coexist.
- Ceramic Membranes:Alumina and zirconia hollow fibers withstand aggressive solvents and thermal cycling beyond polymer limits. German chemical processors pilot these to preempt REACH restrictions on fluoropolymer processing aids.
- Stainless Steel Membranes:Sintered metal fiber matrices deliver mechanical durability for high-pressure steam sterilization cycles.
- Composite Membranes:Hybrid polymer-ceramic architectures balance cost scalability with chemical resistance for mid-tier pharmaceutical applications.
Volume placements concentrate in polymeric membranes; the faster expansion belongs to ceramic alternatives.
Application:
Margin structures diverge by validation intensity: pharmaceutical and food applications command qualification premiums, while water and chemical processing compete on throughput economics.
- Water Purification:Municipal utilities deploy submerged hollow fiber modules for low-energy drinking water production. EPA effluent guidelines in New Jersey and Puerto Rico drive membrane bioreactor adoption for high-recovery pharmaceutical manufacturing discharge.
- Pharmaceutical Processing:Tangential flow filtration with hollow fiber cassettes purifies lipid nanoparticles for mRNA platforms. FDA extractables testing extends qualification cycles 12-18 months versus stainless-steel equivalents.
- Wastewater Treatment:Industrial facilities recover process water through side-stream configurations.
- Food & Beverage Production:Dairy and beverage processors deploy sanitary-grade modules for cold sterilization.
- Chemical Processing:Solvent-resistant membranes enable closed-loop solvent recovery in specialty chemical manufacturing.
Revenue concentration sits with pharmaceutical processing; water purification delivers the steepest volume expansion trajectory.
End User:
Customer scale determines procurement modality: municipal utilities favor multi-year service contracts, while biopharmaceutical buyers unbundle membrane supply from OEM equipment vendors.
- Biopharmaceutical Manufacturers:CDMOs in Switzerland and Singapore build captive membrane testing laboratories to accelerate direct qualification with Asian polymer suppliers. Single-use architectures now dominate filtration operations, forcing production line reconfiguration toward disposable module formats.
- Municipal Water Utilities:Submerged systems with lower energy footprints and simpler maintenance protocols serve distributed treatment networks. Chinese cities expanding domestic biologics capacity import pharmaceutical-grade systems to replace bulk drug substance imports.
- Food Processing Units:Dairy and beverage operators specify hygienic design modules for CIP/SIP compliance.
- Chemical Plants:Aggressive process streams drive specification of thermally stable membrane materials.
Procurement value aggregates with biopharmaceutical manufacturers; municipal utilities represent the broadest installed base expansion.
Installation Type:
Operational philosophy separates continuous from batch paradigms: cross-flow and side-stream systems enable extended campaigns, while submerged and dead-end configurations optimize capital efficiency.
- Cross-Flow Systems:Tangential flow geometry mitigates fouling through continuous retentate recirculation. Massachusetts contract manufacturers deploy these in perfusion cell culture for monoclonal antibody production exceeding annual single-site membrane validation capacity.
- Submerged Systems:Direct immersion in bioreactor vessels eliminates pumping infrastructure. Municipal utilities in Germany and China select these for energy-constrained treatment facilities.
- Side-Stream Systems:External loop configurations enable modular capacity expansion without vessel modification.
- Dead-End Systems:Simple batch filtration suits low-volume, high-value product recovery.
Installed capacity clusters in cross-flow architectures; submerged systems are climbing the fastest in water utility deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processors anchor polymer feedstock supply for pharmaceutical-grade membranes, while biopharmaceutical manufacturing concentrates in the United States, Switzerland, and China. Regulatory divergence between FDA, EMA, and NMPA jurisdictions forces parallel certification portfolios.
United States
Massachusetts and North Carolina contract manufacturers deploy perfusion cell culture systems for 60-day monoclonal antibody campaigns. FDA extractables and leachables testing protocols extend single-use system qualification cycles by 12-18 months versus stainless-steel equivalents. Large molecule CDMOs in Greater Boston build captive membrane testing laboratories to accelerate direct supplier qualification.
Germany
High-purity PVDF and PES resin production concentrates in specialized chemical clusters along the Rhine corridor. ECHA consultations on per- and polyfluoroalkyl substance restrictions compel membrane producers to reformulate fluoropolymer coatings. German chemical processors pilot ceramic hollow fiber systems to preempt dependency on restricted polymer chemistries.
China
Domestic CDMOs in Suzhou and Shanghai import pharmaceutical-grade membrane systems to replace bulk drug substance imports with local manufacturing. NMPA quality guidelines for biologics manufacturing tighten validation requirements for sterile filtration infrastructure. Chinese cities expanding domestic biologics capacity drive submerged system adoption for energy-constrained treatment facilities.
Switzerland
Large molecule CDMOs establish direct qualification relationships with Asian polymer suppliers rather than accepting OEM-specified cartridges. Swissmedic pharmacopeial standards for extractables testing harmonize with FDA approaches to single-use system qualification. Basel-region biopharmaceutical clusters unbundle membrane supply from equipment vendor lock-in.
India
CDSCO regulatory pathways for interchangeable biologics attract investment in Mumbai and Hyderabad filtration infrastructure. Biosimilar manufacturers specify sanitary-grade modules for CIP/SIP compliance in patient-scale perfusion systems. Indian procurement teams establish qualification relationships with membrane suppliers to reduce validation burden on autologous cell therapy processing.
Global Hollow Fiber Filtration Market Competitive Landscape
Global majors compete with regional champions across polymer chemistry expertise and pharmaceutical certification depth. The supplier base organizes around three tiers: integrated resin-to-membrane producers, specialized module fabricators, and equipment-integrated filtration system vendors. Two strategic archetypes dominate competitive positioning—backward-integrated polymer specialists and application-focused bioprocessing partners. Capacity expansion in pharmaceutical-grade spinning lines and strategic partnerships for ceramic sintering technology represent the dominant competitive moves.
Among integrated Japanese producers, Toray Industries and Asahi Kasei occupy positions anchored by polymer chemistry heritage and pharmaceutical-grade certification depth. DuPont sustains competitive positioning through in-house production of specialized fluoropolymer resins. These three exemplify the resin-to-membrane integration archetype that biopharmaceutical procurement teams increasingly favor for direct qualification relationships.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| DuPont |
| Veolia |
| Asahi Kasei Corporation |
| Pall Corporation |
| Repligen Corporation |
| Danaher Corporation |
| Sartorius AG |
| Parker-Hannifin Corp |
| Others |
Supply & Pricing Matrix
Specialized fluoropolymer resin indices from German and Japanese chemical clusters cascade through three distinct pricing tiers in hollow fiber filtration, with pharmaceutical-grade PVDF and PES commanding qualification premiums while ceramic alternatives extract thermal stability premiums from chemical processors preempting REACH restrictions.
Pricing Analysis
Service-bundling unbundling distinguishes competitive positioning: equipment-integrated vendors bundle validation support and change-out services into long-term contracts, while direct membrane suppliers compete on unbundled cartridge pricing with separate qualification consulting. Three-tier pricing structure across pharmaceutical-grade certified, industrial-standard, and economy unvalidated modules separates segments by FDA and EMA certification depth. Cost compression in industrial water applications is intensifying because municipal utilities consolidate procurement into multi-year service contracts. CDMOs in biopharmaceutical manufacturing exhibit lowest price sensitivity due to validation switching costs, while chemical processors in solvent recovery applications drive hardest unit-cost negotiations.
Supply Chain Analysis
Domestic-content mandates from China's NMPA biologics manufacturing guidelines are reshaping sourcing patterns, compelling foreign membrane suppliers to establish local spinning operations or cede share to indigenous producers. High-purity polymer resin supply concentrates in Germany, Japan, and the United States, with specialty PVDF and PES formulations drawing from limited chemical clusters along the Rhine corridor and Osaka industrial zones. Single-source vulnerability permeates pharmaceutical-grade membrane supply, where FDA master file documentation ties buyers to qualified resin lots for 12-18 month validation cycles. Distribution runs through three channels: direct qualification relationships with large CDMOs, OEM equipment vendor bundling for mid-tier facilities, and distributor networks serving municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with polymer chemistry heritage and captive resin production emerging as the decisive upstream lever separating integrated suppliers from module assemblers exposed to raw material allocation risk.
For Market Incumbents: Anchor market position through backward integration into specialized fluoropolymer resin production, eliminating dependency on German and Japanese chemical suppliers for pharmaceutical-grade feedstock. Expand spinning capacity in Massachusetts and North Carolina to capture perfusion cell culture demand from contract manufacturers operating 60-day monoclonal antibody campaigns. Defend against Asian membrane producers by accelerating extractables and leachables testing protocols to compress customer qualification timelines.
For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical-grade certified membranes and economy industrial modules creates entry space for mid-tier composite formulations targeting biosimilar manufacturers in India and cell therapy autologous processing. Target CDSCO regulatory pathways in Mumbai and Hyderabad, where biosimilar manufacturing investment outpaces qualified membrane supply. Pursue direct qualification relationships with midsize CDMOs bypassing OEM vendor lock-in through captive membrane testing laboratory partnerships.
For Investors and Strategic Acquirers: The window for entry favors ceramic membrane specialists with sintering furnace assets and pharmaceutical certification pathways, as REACH substance restrictions on fluoropolymers accelerate material substitution demand. Long-term viability hinges on regulatory harmonization across FDA, EMA, and NMPA jurisdictions enabling single qualification portfolios. Monitor ECHA consultation outcomes on per- and polyfluoroalkyl substance limits as the inflection signal for ceramic hollow fiber adoption velocity in aggressive solvent applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of pharmaceutical-grade PVDF eliminates allocation risk from German chemical clusters. |
| Ceramic Sintering Capacity Expansion | Alumina and zirconia hollow fiber assets preempt REACH-driven substitution away from fluoropolymer chemistries. |
| Captive Membrane Testing Laboratories | Direct qualification relationships with Toray and Asahi Kasei accelerate CDMO vendor selection timelines. |
| Single-Use Module Format Reconfiguration | Disposable architectures displace stainless-steel validation protocols in 60-day perfusion campaigns. |
| Regional Spinning Line Localization | Chinese domestic-content mandates from NMPA guidelines force manufacturing footprint expansion in Suzhou and Shanghai. |
Research Methodology
Independent corroboration across regulatory filings, customs trade data, and pharmaceutical manufacturing capacity announcements underwrites the qualitative findings in this study. Primary interviews with membrane system design engineers, GMP manufacturing directors, bioprocess engineering consultants, and procurement leads at large molecule CDMOs combined with secondary validation from FDA master file databases, EMA submission records, SEC 10-K disclosures from integrated chemical producers, and NMPA biologics manufacturing guidelines. Bottom-up membrane consumption modeling by end-use facility and top-down polymer resin demand analysis triangulate volume estimates.
Comparable-period anchoring to historical pharmaceutical manufacturing capacity buildouts and municipal water utility infrastructure investment cycles established the forecast window baseline. Segmentation modeling across material chemistry, operational configuration, regulatory exposure cluster, and end-user scale archetype generated disaggregated projections throughout the forecast period. CAGRs derived from regression analysis against biopharmaceutical manufacturing output indices and water reuse mandate implementation timelines, with cross-referencing to polymer resin price elasticity assumptions and ceramic membrane substitution elasticity parameters.
Inputs from regulatory agency consultation documents and pharmaceutical manufacturing trade associations were available through the study window; gaps in real-time CDMO procurement transaction data introduce uncertainty bands around quarterly demand inflection points. Forecasts reflect assumptions regarding REACH substance restriction implementation velocity and NMPA domestic manufacturing incentive continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Coolant Filtration Systems Market
Filters
Chloramine Filter Market
Filters
United States Activated Carbon Market
Filters
Global Filter Press Market
Filters
Filter Media Market
Filters
Global Gas Phase Filtration Market
Filters
Europe Industrial Air Filtration Market
Filters
Filters and Particle Monitoring Market
Filters
Ceramic Filters Market
Filters
US Baghouse Filters Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Canada Filtration and Separation Market
Filters
Compact Filters Market
Filters
GCC Industrial Air Filtration Market
Filters
Sintered Metal Filters Market
Filters
Activated Carbon Market