
 Global Sterile Filtration Market | 2026-2036
Global Sterile Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sterile Filtration Market Foresight
Market Context
The capital-intensity divergence between membrane foundry owners and assembly-only suppliers is redrawing competitive tiers in sterile filtration. Merck KGaA leverages integrated polymer synthesis and membrane casting operations to sustain margin capture across the value chain. Danaher Corporation anchors its position through Pall Corporation's bioprocess filtration dominance, while Sartorius AG specializes in single-use systems for cell-culture applications.
Technical Definition and Structural Segments
Sterile filtration encompasses membrane-based separation processes using pore sizes typically rated at 0.22 micrometers or smaller to achieve bioburden reduction and sterility assurance in liquid and gas streams. These systems employ polyethersulfone, polyvinylidene fluoride, or regenerated cellulose matrices in pleated or flat-sheet configurations, serving primarily to protect downstream bioprocessing steps from microbial contamination. Membrane filters command the largest value share due to their irreplaceable role in final-fill pharmaceutical operations, while capsule filters represent the fastest-expanding format as biotech enterprises shift toward disposable, pre-sterilized assemblies to eliminate cleaning validation burdens. Depth filters occupy a mature, volume-driven position in prefiltration trains upstream of sterilizing-grade membranes.
Regulatory Framework and Outlook
The FDA's sterilizing filtration guidance, EMA's Annex 1 revision on aseptic processing, and ISO 13408 standards collectively dictate validation protocols, integrity test requirements, and change-control documentation that filter manufacturers must support. These frameworks elevate barrier-to-entry costs for new suppliers while creating recurring revenue streams for incumbents through regulatory compliance services and validation support packages. Stakeholders must monitor how the EU AI Act and evolving FDA digital guidance intersect with automated integrity-test data management systems.
Market Dynamics
Single-use filtration systems are compressing capital deployment cycles for biopharmaceutical manufacturers while EMA's Annex 1 revision tightens validation documentation burdens on filter suppliers.
Growth Catalysts
- EMA Annex 1 Revision:The updated aseptic processing guidelines mandate enhanced filter integrity testing protocols, creating recurring demand for validation support services and automated testing equipment.
- Cell-culture intensification:Rising titers in monoclonal antibody production generate larger harvest volumes requiring higher-capacity sterile filtration trains.
- Germany supplier ecosystem density:Concentrated membrane manufacturing expertise in Göttingen and Darmstadt accelerates regional innovation cycles and shortens procurement lead times for European biotech sponsors.
Market Restraints
- Polymer feedstock volatility:Specialized grades of polyethersulfone and polyvinylidene fluoride face supply constraints from petrochemical value chain disruptions, compressing margin stability for membrane casters.
- Validation timeline extension:FDA's sterilizing filtration guidance requires extensive bacterial challenge testing and extractables studies, extending new product qualification periods to 18-24 months.
- Depth filter substitution in prefiltration:Advanced charged-depth media capture sub-micron particulates with lower pressure drop, reducing sterilizing-grade membrane surface area requirements in some applications.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO's streamlined biosimilar approval pathways and production-linked incentive schemes attract contract manufacturing investment requiring localized sterile filtration supply.
- Continuous bioprocessing adoption:Perfusion cell-culture systems demand real-time sterile filtration with enhanced throughput consistency, favoring membrane formats with automated integrity monitoring.
- EU AI Act intersection:Automated filter integrity test data management systems face new algorithmic transparency requirements, creating first-mover advantage for suppliers with embedded compliance architectures.
Industry Challenges
- Polymer science talent scarcity:Membrane casting and surface modification expertise concentrates among aging specialist workforces in Germany and Switzerland, constraining capacity expansion.
- Legacy stainless-steel integration:Hybrid facilities combining single-use filtration with existing fixed equipment face validation complexity at connection points and sampling interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sterile Filtration Market |
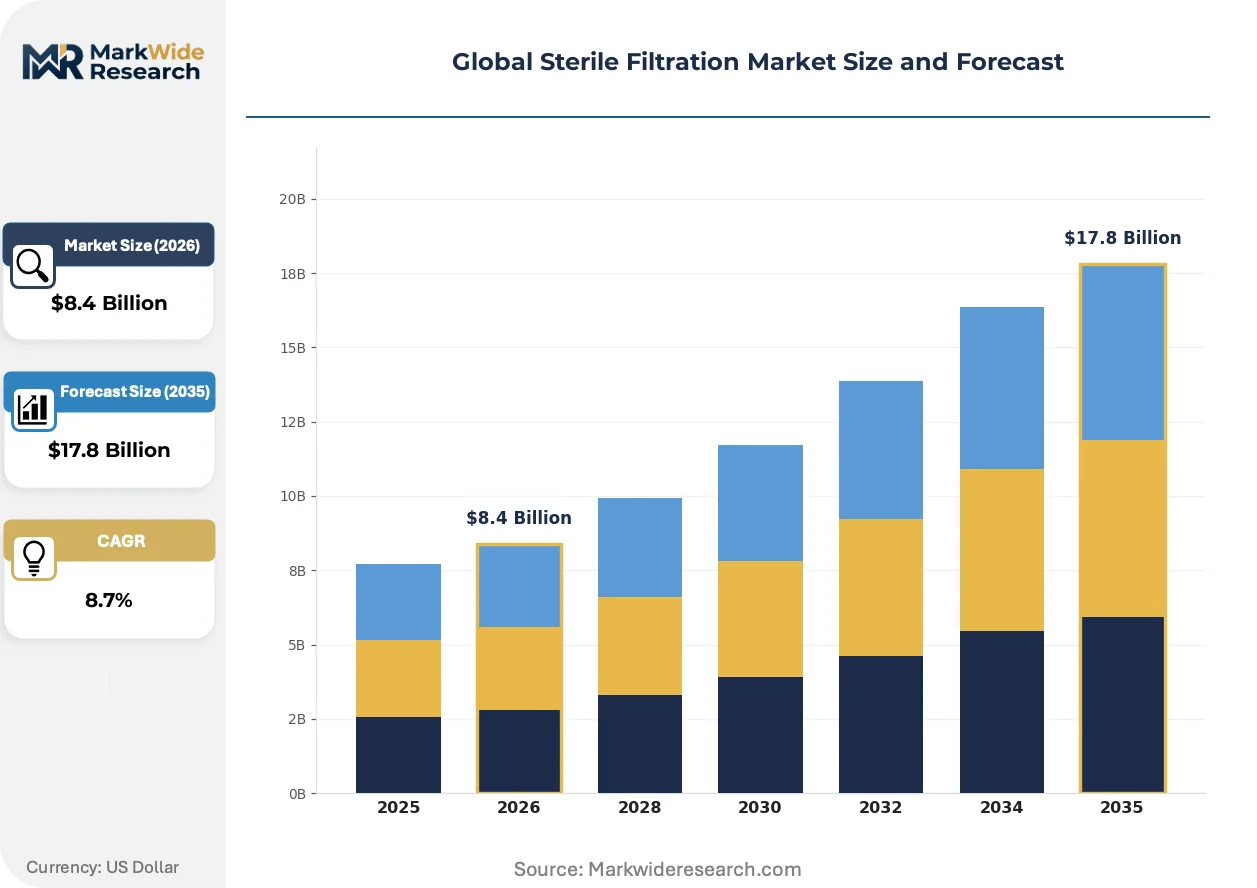
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Depth Filters, Cartridge Filters, Capsule Filters, Pleated Filters Application: Pharmaceutical Solutions, Biotechnological Processing, Food & Beverage Purification, Laboratory Filtration, Cosmetic Manufacturing End User: Pharma Companies, Biotech Enterprises, Food Producers, Cosmetic Manufacturers, Research Institutes Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis, Prefiltration |
| Companies Covered | Sartorius AG, Merck KGaA, Danaher Corporation, 3M Purification, Thermo Fisher Scientific, Pall Corporation, GE Healthcare, Parker Hannifin, Donaldson Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sterile Filtration Market Shifts & Advancements
Membrane chemistry advances and regulatory digitization are restructuring how sterile filtration performance is validated, monitored, and guaranteed across biopharmaceutical supply chains.
Hydrophilic polyvinylidene fluoride surface modifications are displacing traditional polyethersulfone matrices in high-protein-concentration applications. Contract manufacturers handling antibody-drug conjugates and bispecific proteins adopt these membranes at accelerating rates to minimize protein binding and yield loss. The shift is displacing established material specifications in sponsor-supplier technical agreements and forcing membrane foundries to dual-source polymer supply chains.
REACH restrictions on per- and polyfluoroalkyl substances are compelling membrane manufacturers to reformulate wetting agents and surface treatments used in hydrophobic PVDF production. The industrial consequence is a 12-18 month reformulation cycle for affected product lines as suppliers validate alternative chemistries. European biopharma sponsors face the most immediate compliance pressure, with ECHA substance evaluation timelines driving accelerated qualification of replacement membranes.
Consolidated procurement through single-source bioprocess platform agreements is compressing supplier diversity in sterile filtration purchasing. Large biotech enterprises now bundle filter procurement with bioreactor and chromatography system contracts, marginalizing standalone filter vendors. This concentration is most visible in Massachusetts and California, where top-ten biopharma sponsors have reduced qualified sterile filtration suppliers by 40% over five years.
Global Sterile Filtration Market Segmentation
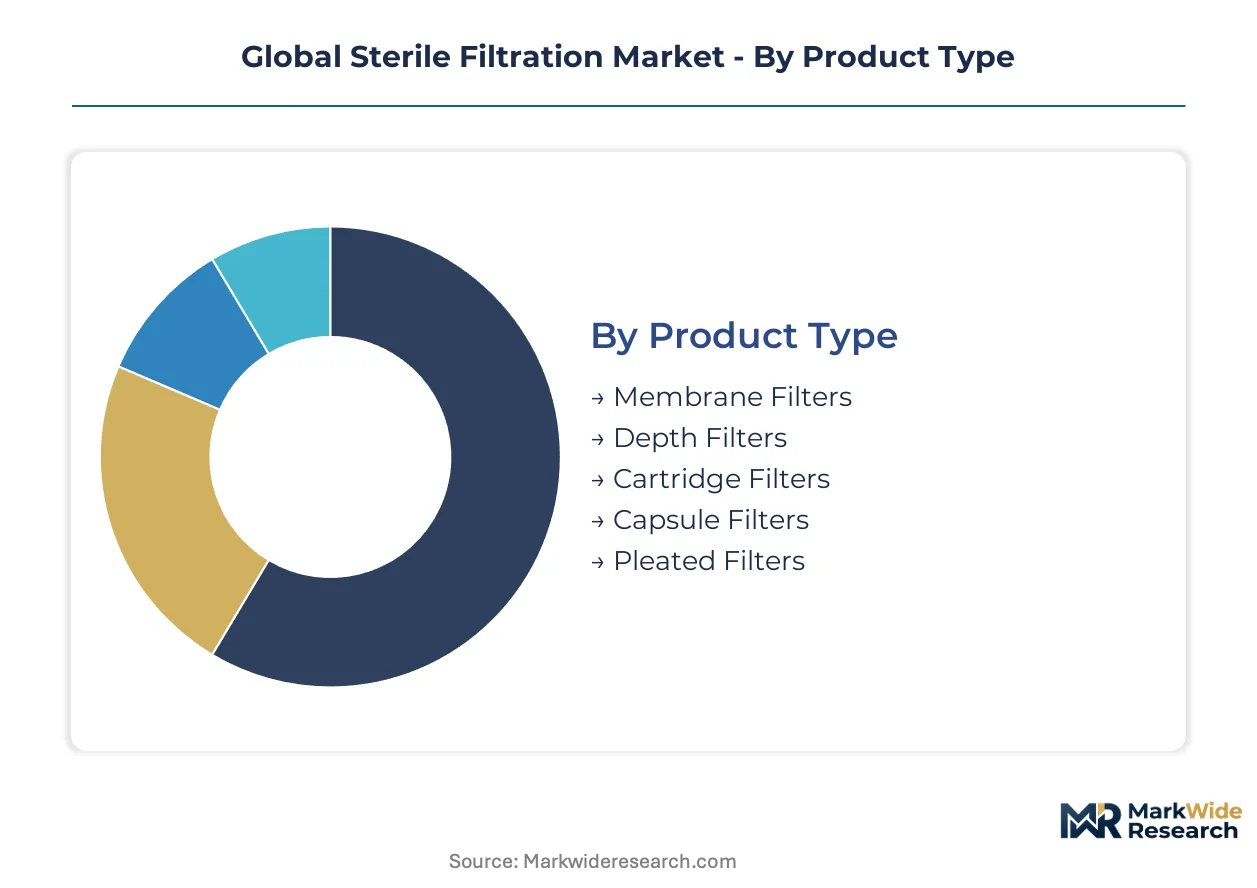
Sterile filtration procurement patterns diverge sharply between capital-intensive bioprocessing installations and high-volume consumable replacement cycles. Segmentation reveals how membrane chemistry, application stringency, and end-user scale reshape supplier engagement models across pharmaceutical and industrial verticals.
Product Type:
Membrane foundries in Germany and Switzerland export sterilizing-grade formats worldwide, while cartridge and capsule assembly operations cluster near major biopharma manufacturing hubs in Massachusetts, California, and Singapore.
- Membrane Filters:Polyethersulfone and polyvinylidene fluoride matrices cast in 0.22-micron ratings serve as the irreplaceable final barrier in parenteral drug filling lines. Demand concentrates in German production networks serving European pharma sponsors, where EMA Annex 1 compliance documentation requirements sustain premium pricing for validated membrane lots.
- Capsule Filters:Pre-sterilized, disposable assemblies eliminate steam-in-place validation burdens for single-use bioprocessing facilities. North American biotech enterprises in Massachusetts and California drive fastest adoption as they retrofit legacy stainless-steel trains for flexible, multi-product campaigns.
- Depth Filters:Charged cellulose and diatomaceous earth media capture colloidal aggregates upstream of sterilizing membranes in harvest clarification trains.
- Cartridge Filters:Stainless-steel-housed pleated elements persist in large-volume parenteral manufacturing where batch sizes exceed single-use economic thresholds.
- Pleated Filters:High-surface-area configurations address viscosity-limited applications in protein-concentrated antibody formulations.
Membrane filters command the established base. The steepest expansion runs through capsule filters.
Application:
Cost tiers separate GMP-validated pharmaceutical applications from technical-grade food and cosmetic uses, with biotechnological processing occupying a mid-tier position on contamination-risk sensitivity.
- Pharmaceutical Solutions:Sterile filtration of parenteral drugs, vaccines, and ophthalmic preparations demands FDA-validated bacterial retention testing and extractables documentation. German and Swiss sponsors maintain the most stringent supplier qualification protocols, extending membrane validation timelines to 18-24 months.
- Biotechnological Processing:Cell-culture harvest, perfusion media exchange, and final formulation steps require continuous sterile filtration with automated integrity monitoring. Singapore and South Korean biologics manufacturers are expanding capacity fastest, sourcing pre-validated capsule assemblies to compress facility startup schedules.
- Food & Beverage Purification:Aseptic packaging lines for dairy and ready-to-drink beverages employ sterilizing-grade filtration at lower documentation intensity than pharma applications.
- Laboratory Filtration:Small-scale membrane discs and syringe filters support analytical method development and quality control sampling across research sites.
- Cosmetic Manufacturing:Preservative-free skincare and ophthalmic cosmetic formulations adopt pharma-grade filtration protocols without equivalent regulatory validation burdens.
Pharmaceutical solutions anchor revenue concentration. Biotechnological processing climbs the fastest as perfusion intensification spreads.
End User:
Customer scale determines procurement leverage, with top-ten biopharma sponsors consolidating supplier panels while mid-tier biotech enterprises retain multi-source strategies for supply security.
- Pharma Companies:Large-scale parenteral manufacturers in Germany, Switzerland, and the United States negotiate multi-year platform agreements bundling filtration with bioreactor and chromatography procurement. These sponsors drive standardization of membrane specifications across their global manufacturing networks.
- Biotech Enterprises:Emerging biologics developers prioritize operational flexibility over capital efficiency, adopting single-use capsule filters to enable rapid product changeovers in multi-tenant contract manufacturing facilities.
- Food Producers:Aseptic dairy and beverage processors in France and Italy source sterilizing-grade filtration for extended-shelf-life packaging lines.
- Cosmetic Manufacturers:Premium skincare formulators in South Korea and France adopt sterile filtration for preservative-free product positioning.
- Research Institutes:Academic and government laboratories consume membrane discs and syringe filters for method development and small-scale purification.
Pharma companies dominate procurement volume. Biotech enterprises gain share fastest on CDMO capacity expansion.
Technology:
Application maturity separates established microfiltration from emerging continuous processing formats, with nanofiltration and reverse osmosis occupying specialized positions in formulation concentration and buffer preparation.
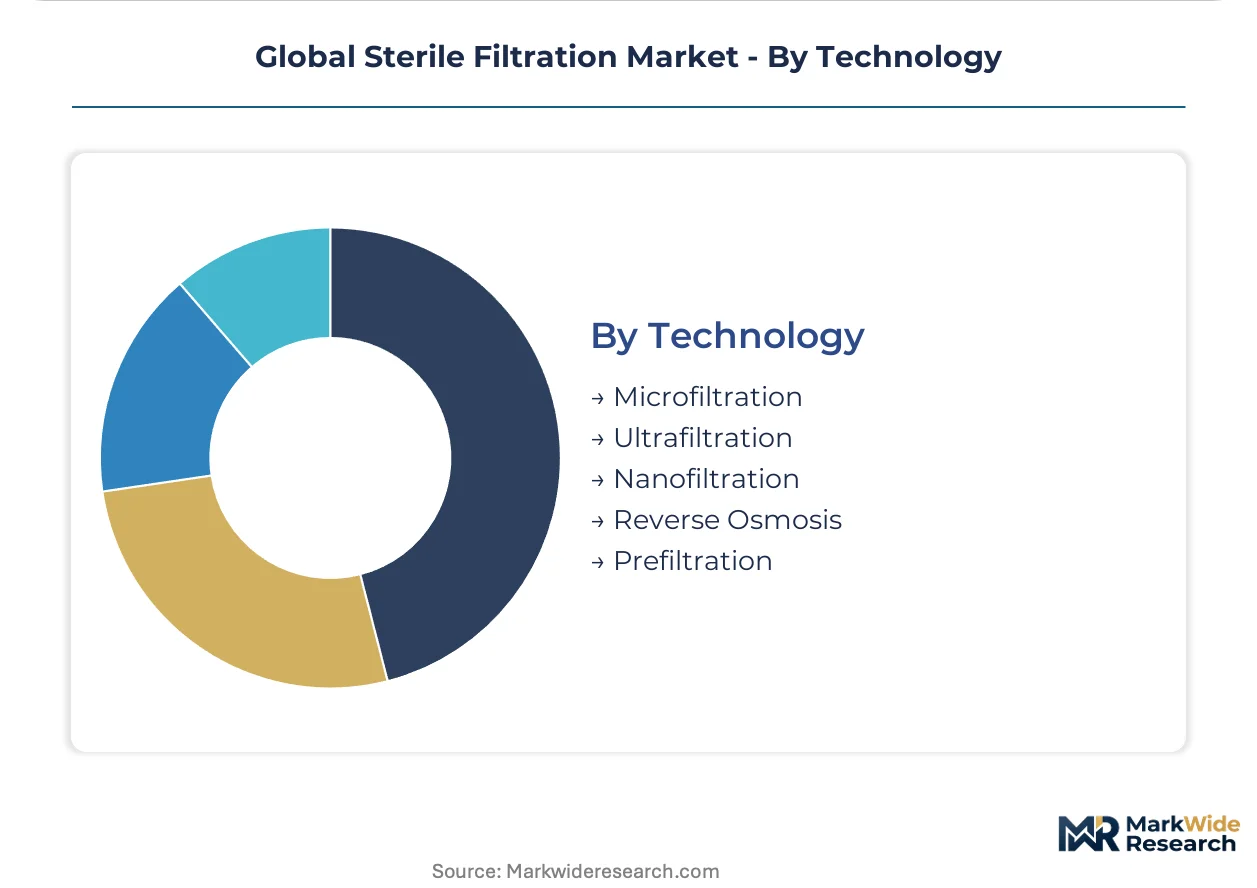
- Microfiltration:0.22-micron and 0.1-micron rated membranes constitute the core sterilizing-grade technology for bioburden reduction. German membrane foundries in Göttingen and Darmstadt concentrate casting expertise, exporting validated lots to biopharma sponsors worldwide.
- Prefiltration:Depth and nominal-rated membranes protect sterilizing-grade elements from particulate fouling in high-solid-load harvest streams. Demand tracks cell-culture titer intensification, with 5-10 gram-per-liter antibody titers generating proportionally larger aggregate burdens upstream.
- Ultrafiltration:Tangential-flow membrane cassettes concentrate and diafilter protein solutions prior to sterile filtration.
- Nanofiltration:Tight-molecular-weight-cutoff membranes remove endotoxins and small-molecule contaminants in specialized parenteral applications.
- Reverse Osmosis:Water-for-injection and pure steam generation systems employ RO as pretreatment to distillation.
Microfiltration holds the revenue base. Prefiltration expands most quickly on harvest volume intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German membrane foundries while contract manufacturers in India and Singapore compete on procurement cost. This asymmetry shapes where sterile filtration value accumulates versus where volume scales fastest.
United States
Massachusetts and California biotech clusters drive single-use capsule filter adoption for flexible multi-product manufacturing. FDA sterilizing filtration guidance mandates 18-24 month validation timelines that favor incumbent suppliers with established compliance dossiers. Greater Boston hosts the densest concentration of contract development organizations retrofitting legacy stainless-steel facilities.
Germany
Sartorius AG and Merck KGaA anchor membrane casting operations in Göttingen and Darmstadt that supply validated lots worldwide. EMA Annex 1 revision tightens integrity testing documentation, creating recurring revenue streams for German suppliers through validation support services. The supplier ecosystem density shortens procurement lead times for European biopharma sponsors.
India
CDSCO streamlined biosimilar approvals and production-linked incentive schemes attract contract manufacturing investment requiring localized sterile filtration supply. Hyderabad and Bengaluru biologics parks expand perfusion cell-culture capacity demanding real-time sterile filtration with automated integrity monitoring. Domestic membrane assembly operations cluster near these manufacturing hubs to compress logistics costs.
Singapore
Tuas Biomedical Park and one-north biotech precincts source pre-validated capsule assemblies to compress facility startup schedules. The national pharmaceutical regulator aligns with FDA and EMA standards, enabling dual-qualification strategies for export-oriented manufacturers. Jurong Island chemical infrastructure supports wetting agent and surface treatment supply chains for membrane production.
Switzerland
Basel and Zürich pharmaceutical sponsors maintain the most stringent supplier qualification protocols, extending membrane validation timelines beyond standard industry practice. Swissmedic oversight converges with EMA Annex 1 requirements, reinforcing premium pricing for validated membrane lots. The specialized polymer science workforce concentrates aging expertise that constrains rapid capacity expansion.
Global Sterile Filtration Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated membrane foundries with captive polymer synthesis operations capture margin across the value chain, while assembly-only suppliers compete on procurement efficiency and regional logistics. Three archetypes dominate: vertically integrated material-science specialists, platform-integrated bioprocess conglomerates, and regional contract assembly providers. Consolidation proceeds through bioprocess platform bundling and membrane chemistry licensing arrangements rather than horizontal mergers.
Within the integrated specialist tier, Sartorius AG and Merck KGaA exemplify the German membrane-science archetype with polymer casting and surface modification capabilities concentrated in Central Europe. Danaher Corporation occupies a position representing the platform-integrated conglomerate model, anchoring competitive positioning through bioprocess filtration dominance acquired via Pall Corporation. These three entities collectively illustrate how technology depth and portfolio breadth constitute alternative pathways to pricing power in sterile filtration supply.
| Leading Market Players |
|---|
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| 3M Purification |
| Thermo Fisher Scientific |
| Pall Corporation |
| GE Healthcare |
| Parker Hannifin |
| Donaldson Company |
| Others |
Supply & Pricing Matrix
Membrane foundry utilization rates above 85% in German manufacturing clusters compress supply elasticity and sustain premium pricing for validated polymer lots. This capacity tightness elevates price floors for sterilizing-grade formats while forcing biopharma sponsors into longer-term offtake commitments to secure allocation.
Pricing Analysis
Configured-to-order membrane specifications command 40-60% premiums over standard catalog offerings due to extractables documentation and bacterial challenge testing burdens. Pricing stratifies across GMP-validated, technical-grade, and research-use tiers, with FDA-tier certification driving the widest spreads. Cost compression in standard capsule formats is intensifying because contract manufacturers in India and Singapore replicate validated assembly protocols. Emerging biotech enterprises exhibit highest price sensitivity, while large pharma sponsors absorb premiums for supply security.
Supply Chain Analysis
Inventory buffers for specialized polyethersulfone and polyvinylidene fluoride resins stretch to 16-20 weeks, exposing membrane casters to petrochemical value chain disruptions. Polymer synthesis concentrates in Germany, Switzerland, and the United States, with surface modification chemistry drawing from Jurong Island chemical infrastructure in Singapore. Single-source vulnerability runs through German membrane foundries supplying EMA-validated lots. Distribution runs through authorized distributor networks serving regional biopharma clusters rather than direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterile filtration market is recovering from pandemic-era capacity overbuild as cell-culture intensification restarts capital deployment cycles for bioprocessing equipment.
For Market Incumbents: Compound regulatory compliance service revenue by embedding automated integrity-test data management into platform offerings, countering emerging entrants with stripped-down validation support. Deepen backward integration into polymer synthesis to defend margin capture against commodity resin price volatility. Prioritize capacity addition in Singapore to serve CDMO expansion without trans-Atlantic logistics exposure. For New Entrants and Emerging Players: Differentiate on rapid-customization capabilities for antibody-drug conjugate applications requiring specialized hydrophilic PVDF surface chemistries. Penetrate the India biologics manufacturing corridor where CDSCO-aligned sponsors seek localized validation support. Pursue white-label assembly partnerships with established membrane foundries rather than greenfield casting investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among validation-support service providers with embedded FDA and EMA compliance architectures. Long-term viability hinges on exposure to continuous bioprocessing adoption rather than batch-filtration replacement cycles. Target acquisition profiles center on membrane surface-modification specialists with proprietary hydrophilic coating IP. Watch perfusion cell-culture capacity announcements as the inflection signal for real-time filtration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Service Bundling | EMA Annex 1 revision mandates enhanced documentation, creating recurring revenue streams for incumbents. |
| Polymer Synthesis Backward Integration | Captive resin production insulates margin capture from petrochemical feedstock volatility. |
| Single-Use Platform Standardization | Biotech sponsors in Massachusetts and California prioritize flexible multi-product manufacturing configurations. |
| Localized Assembly in India | CDSCO production-linked incentives attract contract manufacturing requiring regional sterile filtration supply. |
| Automated Integrity Test Data Management | EU AI Act algorithmic transparency requirements favor suppliers with embedded compliance architectures. |
Research Methodology
Cross-validation between primary interviews with membrane casting engineers and secondary validation through FDA 483 observations and EMA inspection reports anchors the qualitative findings. The research program combined discussions with regulatory affairs leads at biopharma sponsors, procurement managers at CDMOs, and polymer scientists at membrane foundries, triangulated against customs data for sterilizing-grade filter imports, SEC filings from bioprocess equipment suppliers, and ISO 13408 standard revision drafts. Bottom-up demand modeling from individual biologics manufacturing facilities converged with top-down market sizing from supplier revenue disclosures.
Sensitivity analysis across polymer feedstock cost scenarios and cell-culture titer intensification rates shapes the projection framework. The analytical model segments by membrane chemistry, application stringency, and end-user scale, with additional dimensioning by regional regulatory cluster. CAGRs derive from capacity expansion announcements, sponsor pipeline disclosures, and filtration train sizing norms across the modeling period. Continuous bioprocessing adoption curves and REACH substance restriction timelines constitute key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained biologics capacity expansion or polymer supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding EMA Annex 1 implementation pace and FDA sterilizing filtration guidance enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global High Temperature Filters Market
Filters
Color Filter Glass Market
Filters
Drum Filters Market
Filters
Global Depth Filtration Market
Filters
Fiberglass Filters Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Europe Activated Carbon Market
Filters
Global Lamella Clarifier Market
Filters
GCC Industrial Air Filtration Market
Filters
Round Plate Filter Press Market
Filters
Filters and Particle Monitoring Market
Filters
Global Liquid Filtration Market
Filters
Respirator Cartridges and Filters Market
Filters
Industrial Filtration Market
Filters
Chloramine Filter Market
Filters
Homopolymer Acrylic Filter Bags Market