
 Global Filter Market | 2026-2036
Global Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Filter Market Analysis
China is narrowing its gap with Western filter producers through expanded PTFE membrane and nanofiber capacity builds in Jiangsu and Zhejiang provinces. MANN+HUMMEL Group leverages vertical integration into nonwoven media to control cost and quality across automotive air and oil filter lines. Parker Hannifin Corporation anchors its position through hydraulic and pneumatic filtration systems for aerospace and mobile equipment. Donaldson Company, Inc. specializes in industrial dust collection and engine intake systems for mining and agriculture.
A filter is a porous or semi-permeable device that separates particulates, contaminants, or specific substances from fluids or gases, typically constructed from cellulose, synthetic fibers, ceramics, or polymeric membranes with defined pore ratings from 0.1 to 100 microns. Its primary industrial purpose is to protect equipment, ensure process purity, and comply with environmental or health-based emission and exposure limits. Air filter and membrane technology segments lead value generation, with membrane systems commanding premium pricing in pharmaceutical and semiconductor water treatment. Activated carbon technology competes on adsorption capacity for VOC and chlorine removal in municipal and residential applications.
EPA, EU MDR, and China's MEE enforce tightening particulate and purity standards that elevate replacement frequencies and specification thresholds across automotive, medical, and industrial filter categories. REACH and RoHS restrict certain chemical treatments in filter media, pushing manufacturers toward fluorine-free and bio-based alternatives. Stakeholders must monitor regulatory divergence between the US, Europe, and China, as divergent certification timelines will fragment product platforms and complicate scale economics.
Market Dynamics
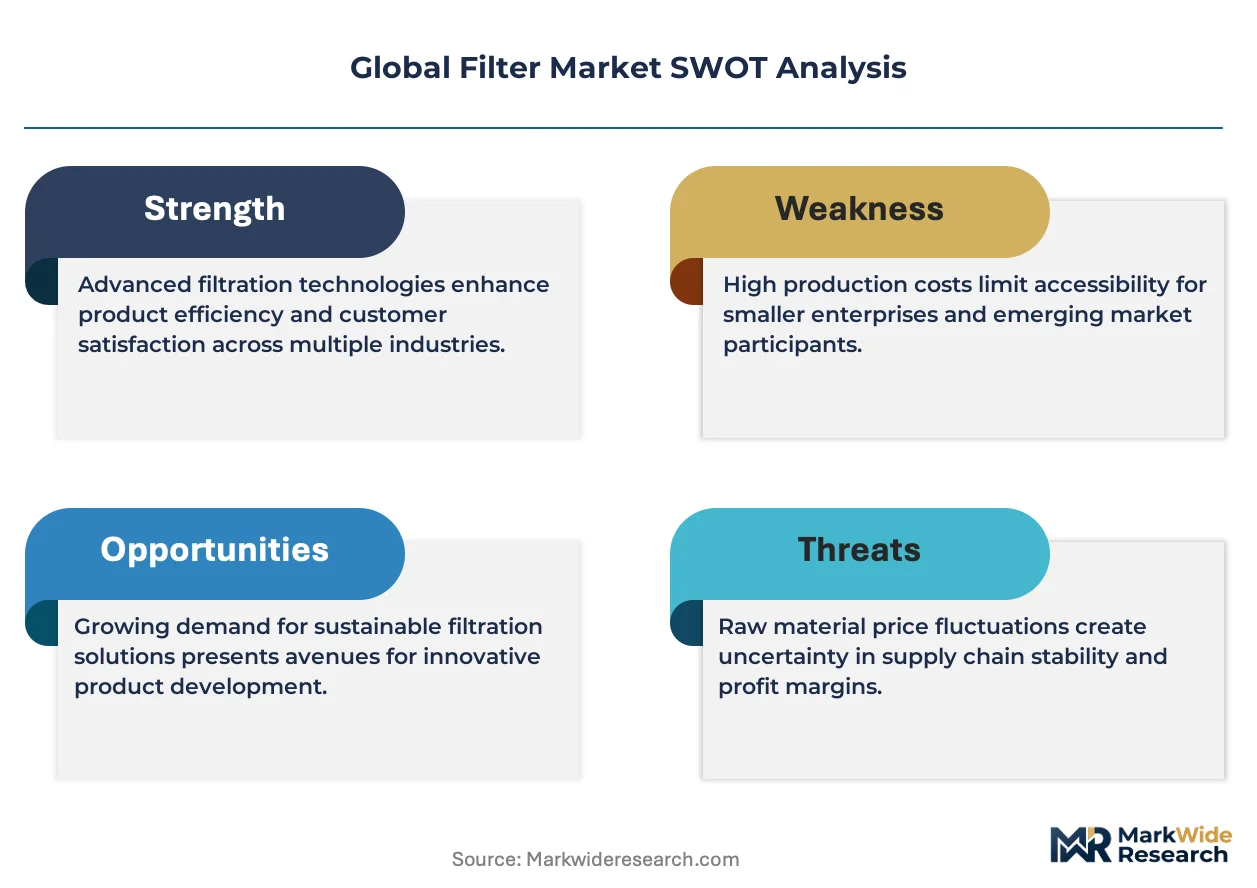
Membrane filtration technology is collapsing cost-performance thresholds across pharmaceutical and semiconductor water treatment, compressing replacement cycles and elevating specification requirements as EPA and EU MDR mandates tighten simultaneously.
Growth Catalysts
- EU MDR Purity Mandates:Medical device manufacturers in Germany and France are accelerating membrane filter procurement to meet sterility assurance level requirements for implantable devices and diagnostic equipment.
- Automotive Electrification:Battery cell producers in South Korea and Japan are deploying PTFE membrane systems for electrolyte filtration and dry room air handling to prevent contamination.
- EPA Emission Controls:Chemical processors across Texas and Louisiana are retrofitting activated carbon and HEPA systems to capture VOCs and particulates under tightened National Ambient Air Quality Standards.
Market Restraints
- Fluoropolymer Feedstock Concentration:PTFE resin supply concentrates among Chinese and Japanese chemical conglomerates, exposing membrane producers to price volatility and export license risk.
- REACH Chemical Restrictions:ECHA's evolving substance of very high concern listings are forcing reformulation of filter media coatings and adhesives, extending R&D timelines.
- Technical Limitation in Nanofiber Durability:Electrospun synthetic media face mechanical degradation under high-temperature pulse-cleaning regimes, limiting deployment in heavy industrial dust collection.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO's phased implementation of Good Manufacturing Practice harmonization with WHO standards is creating demand for validated sterile filtration systems in Hyderabad and Ahmedabad clusters.
- Hydrogen Economy Infrastructure:Proton exchange membrane electrolysis and fuel cell manufacturing in Germany and Japan require ultra-high purity gas filtration for hydrogen dehumidification and particulate removal.
- Fluorine-Free Media Innovation:Bio-based cellulose and polylactic acid nanofiber development responds to F-Gas Regulation phase-down and customer sustainability procurement criteria.
Industry Challenges
- Cross-Contamination Control Expertise:Filter producers lack sufficient process engineers trained in isolator technology and aseptic processing for biopharmaceutical applications.
- Dual Certification Complexity:Simultaneous FDA 510(k) and EU MDR conformity assessment timelines for medical filtration products extend market entry by 18-24 months.
- Legacy Equipment Retrofit Integration:Pneumatic and hydraulic filtration upgrades in aging aerospace manufacturing facilities face physical space constraints and incompatible control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Filter Market |
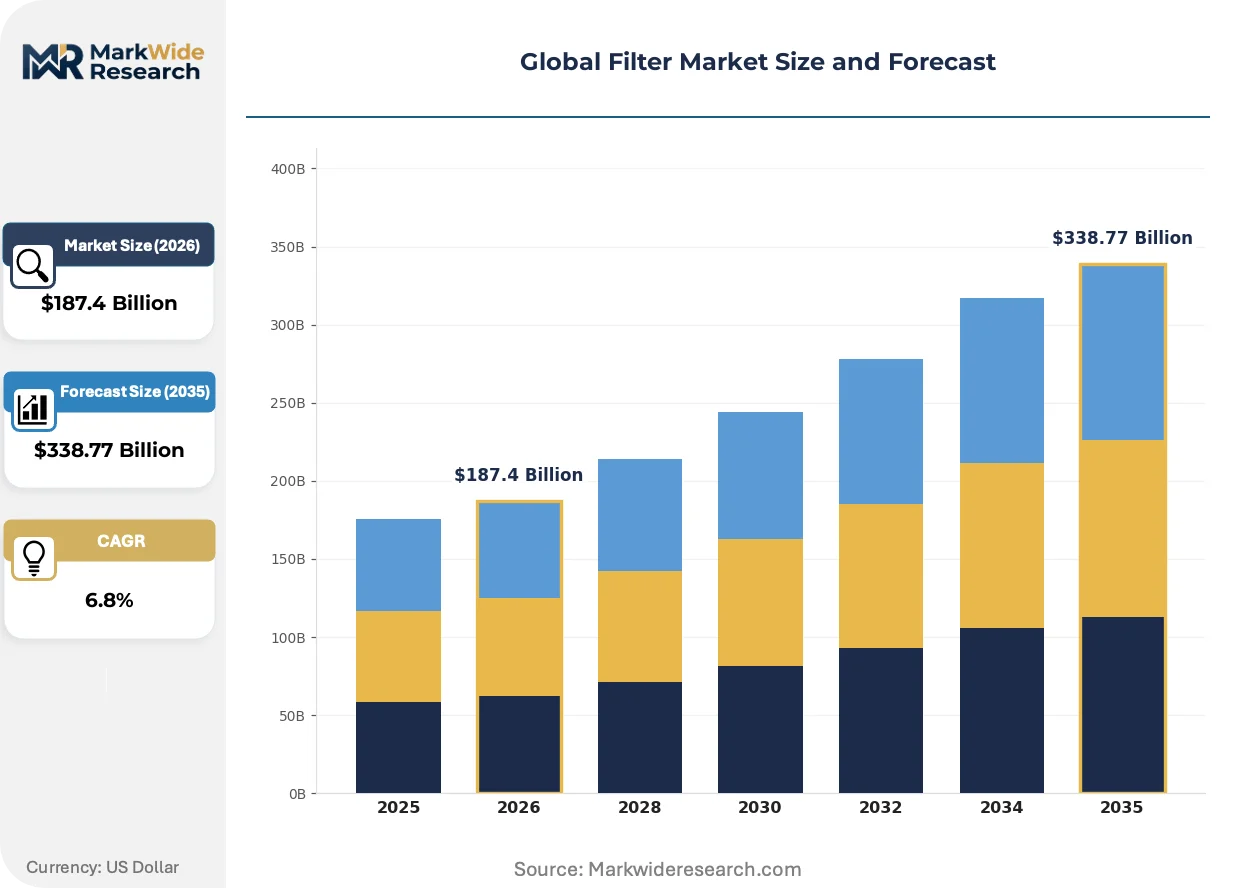
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filter, Water Filter, Oil Filter, Fuel Filter Technology: Activated Carbon, Ceramic, Membrane, Reverse Osmosis End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | MANN+HUMMEL Group, Parker Hannifin Corporation, Donaldson Company, Inc., 3M Company, Freudenberg Filtration Technologies, Camfil, Eaton Corporation plc, Filtration Group Corporation, Pentair plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Filter Market Emerging Trajectories
Digital pore structure modeling and additive manufacturing are compressing prototyping cycles while regulatory fragmentation between EPA, ECHA, and China's MEE is forcing platform diversification.
Graphene oxide composite membranes are collapsing the permeability-selectivity tradeoff that has constrained polymeric filtration for decades. Semiconductor fabs in Taiwan and South Korea are piloting these materials for sub-10 nanometer process water. The technology is collapsing incumbent ceramic membrane pricing power in high-purity applications.
REACH restriction proposals on per- and polyfluoroalkyl substances are accelerating fluorine-free filter media development across European automotive and food processing supply chains. MANN+HUMMEL and Donaldson are reformulating air intake and cabin filter lines to maintain EU market access. The F-Gas Regulation phase-down is compressing PTFE membrane cost advantages versus bio-based alternatives.
Equipment-as-a-service contracting is displacing capital purchase models in municipal water treatment. French and German utilities now procure membrane bioreactor capacity through availability-based agreements with Suez and Veolia. This shift transfers operational risk to OEMs and locks in long-term consumables revenue streams.
Global Filter Market Segmentation
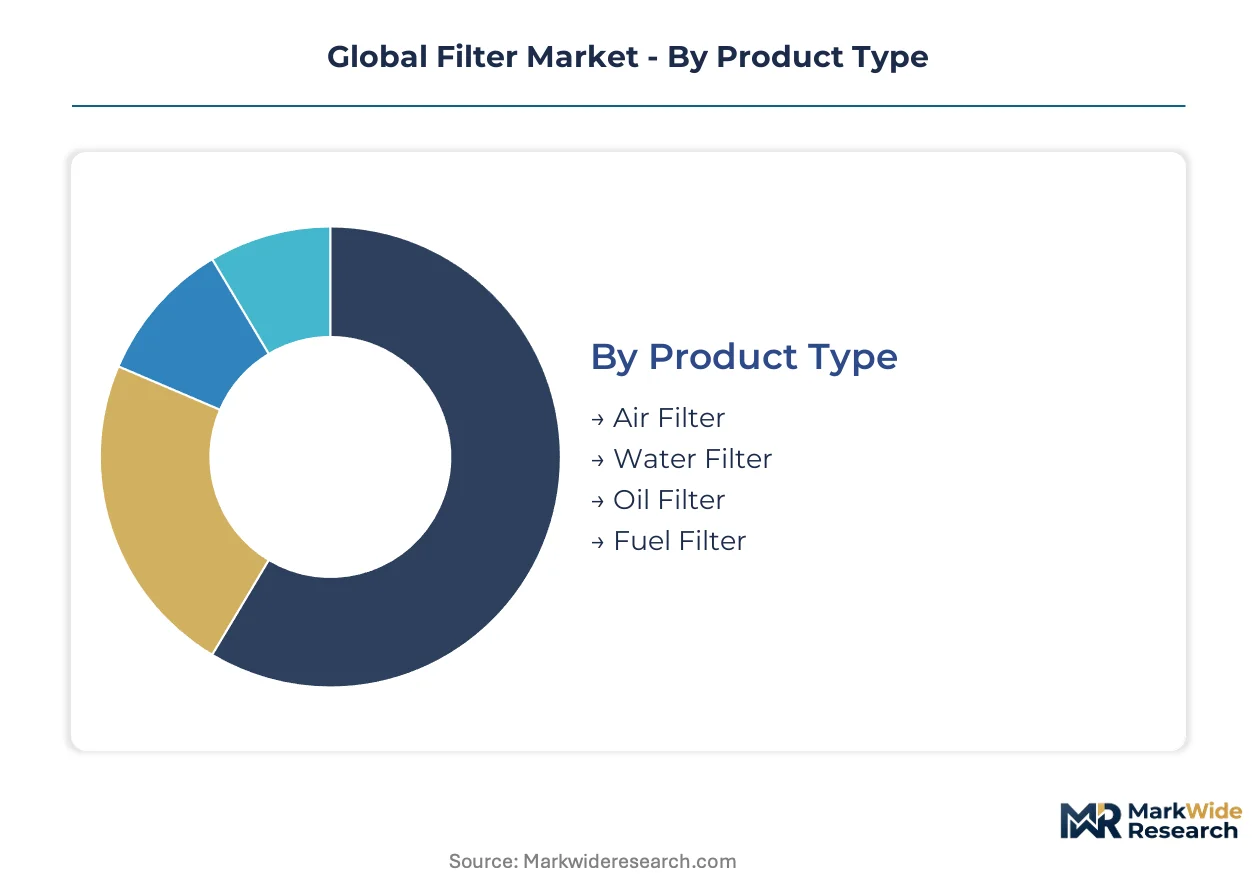
Filter procurement cycles vary dramatically across product categories, with automotive air and oil filters turning over every 12-18 months while industrial membrane systems operate on 5-7 year replacement horizons. Understanding these velocity differentials helps suppliers align inventory, service contracts, and R&D pipelines to segment-specific cash flow patterns.
Product Type:
Replacement frequency separates high-velocity consumables from capital-intensive industrial installations, with automotive and residential segments driving recurring revenue streams.
- Air Filter:Constructed from pleated cellulose or synthetic nonwoven media with MERV 8-16 efficiency ratings. Automotive OEMs in Germany and fleet operators in the US Midwest anchor procurement for engine intake and cabin applications, with EPA particulate standards elevating specification thresholds.
- Water Filter:Deploys activated carbon blocks, ion exchange resins, or polymeric membranes rated 0.1-5 microns. Municipal utilities in France and semiconductor fabs in Taiwan concentrate demand for high-purity process water, driven by EU Drinking Water Directive and EPA Safe Drinking Water Act compliance.
- Oil Filter:Full-flow and bypass configurations using cellulose or glass fiber media for lubricant contamination control.
- Fuel Filter:Diesel and gasoline filtration systems protecting injection systems from particulate and water contamination.
Air filters anchor the volume base while membrane-based water filtration gains share at the steepest rate.
Technology:
Cost tiers stratify sharply, with activated carbon commanding economy positioning and ceramic membranes capturing premium pricing in pharmaceutical validation protocols.
- Membrane:Thin-film composite polyamide or polysulfone barriers with defined molecular weight cutoffs for selective separation. Biopharmaceutical manufacturers in Switzerland and battery cell producers in South Korea drive specification intensity, with FDA process validation requirements extending qualification timelines.
- Activated Carbon:Granular or extruded carbonaceous media with high surface area for adsorption of organics and chlorine. Municipal water treatment facilities in Germany and VOC abatement systems across Texas chemical plants sustain procurement volumes, constrained by feedstock price volatility in coconut shell and coal base materials.
- Ceramic:Alumina or zirconia porous structures with thermal stability for high-temperature industrial processes.
- Reverse Osmosis:Spiral-wound or hollow-fiber configurations producing permeate quality below 10 ppm total dissolved solids.
Activated carbon sustains the broadest installed base while membrane technology climbs the fastest on semiconductor and pharmaceutical purity demands.
End User:
Customer type determines margin structure, with industrial accounts accepting total cost-of-ownership pricing and residential segments remaining price-sensitive at point-of-sale.
- Industrial:Process filtration for chemical, pharmaceutical, and food and beverage manufacturing with validated sterility assurance. Hydrogen electrolysis projects in Japan and Germany are emerging as high-specification demand centers, with ISO 8573 compressed air quality standards mandating sub-micron particulate removal.
- Automotive:OEM and aftermarket replacement cycles tied to vehicle mileage accumulation and electrification transitions. Internal combustion engine filter demand concentrates in India and Brazil production hubs, while battery electric vehicle thermal management systems create new filtration requirements.
- Residential:Point-of-use and point-of-entry systems for drinking water and HVAC applications.
- Commercial:Building-scale air handling and foodservice water treatment with standardized maintenance intervals.
Industrial end users contribute the highest absolute value per installation while automotive replacement volumes dominate unit shipment counts.
Distribution Channel:
Supply concentration varies by channel, with direct sales capturing complex industrial specifications and online retail fragmenting price discovery for standardized consumables.
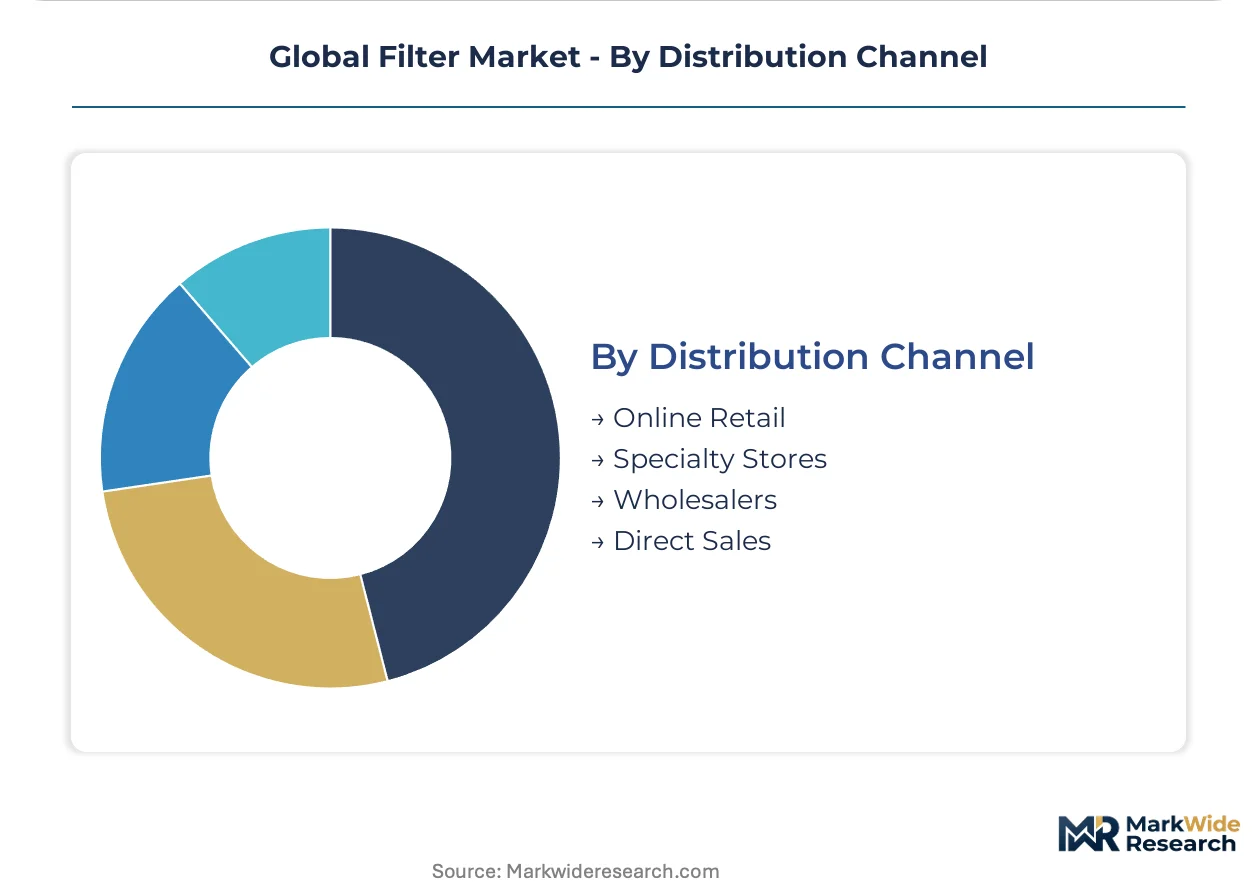
- Direct Sales:Engineer-to-order relationships for membrane systems and validated pharmaceutical filtration trains. Suez and Veolia in France leverage long-term availability contracts with municipal utilities, transferring operational risk from end users to OEM service organizations.
- Wholesalers:Industrial distributors stocking standardized air, oil, and fuel filters for maintenance repair operations. Würth and Granger serve German and US manufacturing clusters respectively, with just-in-time delivery contracts aligning with plant shutdown schedules.
- Specialty Stores:Branded retail environments for residential water and air purification systems.
- Online Retail:E-commerce platforms for replacement cartridge subscriptions and aftermarket automotive components.
Direct sales lock in the longest contract tenures while online retail expands most quickly on residential subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA mandates in the United States establish the regulatory baseline that other jurisdictions reference when tightening their own purity standards. Filter procurement patterns concentrate where automotive OEMs, chemical processors, and semiconductor fabs cluster under strict environmental enforcement.
United States
Chemical processors along the Gulf Coast retrofit activated carbon and HEPA systems to capture VOCs under tightened National Ambient Air Quality Standards. EPA enforcement elevates replacement frequencies for industrial dust collection. Houston and Louisiana petrochemical corridors anchor membrane and carbon filter procurement volumes.
Germany
Automotive OEMs in Stuttgart and Munich drive membrane and activated carbon filter procurement for powertrain and cabin applications. EU MDR sterility assurance requirements accelerate medical-grade membrane adoption for implantable device manufacturing. The country's hydrogen electrolysis projects in North Rhine-Westphalia demand ultra-high purity gas filtration systems.
China
MEE particulate standards tighten across Jiangsu and Zhejiang province manufacturing clusters. Domestic PTFE membrane and nanofiber capacity expansion narrows the technology gap with Western producers. Shanghai and Suzhou semiconductor fabs pilot graphene oxide composite membranes for sub-10 nanometer process water.
Japan
Battery cell producers deploy PTFE membrane systems for electrolyte filtration and dry room air handling. METI industrial policy supports hydrogen economy infrastructure development requiring validated sterile filtration. Osaka and Nagoya automotive suppliers transition thermal management filtration for electrified powertrains.
India
CDSCO phased GMP harmonization with WHO standards creates demand for validated sterile filtration in Hyderabad and Ahmedabad pharmaceutical clusters. Domestic automotive production hubs in Maharashtra and Tamil Nadu sustain oil and fuel filter replacement volumes. Municipal water treatment procurement concentrates in Delhi-NCR and Gujarat industrial corridors.
Global Filter Market Vendor Landscape
Capability concentration sits with specialized membrane and pharmaceutical-grade producers; scale advantage sits with diversified industrial conglomerates serving automotive and aerospace verticals. The vendor base stratifies across three tiers: integrated material-to-system suppliers, component specialists, and regional fabricators. Strategic differentiation runs through backward integration into nonwoven media, captive resin production, and validated pharmaceutical process expertise. Competitive moves center on fluorine-free media reformulation and equipment-as-a-service contracting for municipal water treatment.
Among Germany-based integrated suppliers, MANN+HUMMEL Group and Freudenberg Filtration Technologies exemplify the material-to-system archetype through in-house nonwoven production. Parker Hannifin Corporation anchors the diversified industrial tier with hydraulic and pneumatic filtration systems. These three represent distinct competitive positioning: European vertical integration, American industrial diversification, and specialized membrane technology depth respectively.
| Leading Market Players |
|---|
| MANN+HUMMEL Group |
| Parker Hannifin Corporation |
| Donaldson Company, Inc. |
| 3M Company |
| Freudenberg Filtration Technologies |
| Camfil |
| Eaton Corporation plc |
| Filtration Group Corporation |
| Pentair plc |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors carry PTFE resin and activated carbon feedstock from Jiangsu province manufacturers to European automotive OEMs, with container rate volatility compressing margins on membrane exports while amplifying price spreads between Asian contract manufacturers and German system integrators.
Pricing Analysis
Geographic price spreads between Chinese membrane producers and European pharmaceutical-grade suppliers exceed three-to-one on validated sterile filtration trains. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated membrane systems from industrial process units and commodity automotive consumables. Cost compression in standard-grade activated carbon reflects coconut shell feedstock volatility from Southeast Asian suppliers. Residential point-of-use buyers exhibit highest price sensitivity, while biopharmaceutical manufacturers accept total cost-of-ownership premiums for validated sterility assurance.
Supply Chain Analysis
Contract manufacturing for PTFE membrane casting concentrates among Jiangsu and Zhejiang specialty chemical processors, with Freudenberg and MANN+HUMMEL maintaining captive nonwoven production in Germany. Raw material sourcing draws from Chinese fluoropolymer resin, German cellulose pulp, and Malaysian coconut shell carbon. Single-source vulnerability runs through Japanese PTFE resin suppliers subject to export license protocols. Distribution runs through direct engineer-to-order channels for pharmaceutical systems and industrial distributors for automotive aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between EPA, ECHA, and China's MEE is fragmenting product platforms and creating specialist niches for region-specific certification expertise.
For Market Incumbents: Pre-empt fluorine-free media substitution by accelerating bio-based cellulose and polylactic acid nanofiber R&D before REACH restrictions harden on per- and polyfluoroalkyl substances. Secure backward integration into regional nonwoven production to defend margin position against Chinese membrane cost convergence. Lock in equipment-as-a-service contracts with French and German municipal utilities to capture long-term consumables revenue. For New Entrants and Emerging Players: Build out validated sterile filtration capability for India's CDSCO-GMP harmonization wave in Hyderabad and Ahmedabad pharmaceutical clusters. Target hydrogen electrolysis gas filtration in Germany and Japan where ISO 8573 compressed air mandates create specification barriers incumbents have underdeveloped. Lead with fluorine-free media credentials to differentiate in European automotive supply chains facing F-Gas Regulation phase-down. For Investors and Strategic Acquirers: Specialized membrane technology developers with pharmaceutical process validation expertise represent the most defensible acquisition archetype against commoditization pressure. Long-term viability hinges on positioning upstream of hydrogen economy infrastructure buildouts and semiconductor fab capacity expansion. Monitor ECHA substance of very high concern listings as inflection signal for fluoropolymer-dependent business model risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Media Reformulation | REACH restrictions on PFAS compounds in European automotive and food processing supply chains. |
| Equipment-as-a-Service Contracting | Suez and Veolia availability agreements with French and German municipal utilities transfer operational risk. |
| Pharmaceutical Validation Investment | FDA 510(k) and EU MDR dual certification extends competitive moats in implantable device filtration. |
| Hydrogen Economy Filtration Development | German and Japanese electrolysis projects demand ultra-high purity gas systems under ISO 8573. |
| Regional Nonwoven Capacity Expansion | Captive media production in Germany insulates MANN+HUMMEL from Chinese PTFE membrane cost convergence. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across membrane system procurement, automotive filter manufacturing, and municipal water treatment operations. Primary interviews captured plant engineers at Texas chemical processors, regulatory affairs leads at German medical device manufacturers, and procurement directors at South Korean battery cell producers. Secondary validation drew from EPA enforcement databases, ECHA restriction proposals, CDSCO GMP circulars, and customs trade records for PTFE resin and activated carbon. Bottom-up segment sizing triangulated against top-down macroeconomic calibration.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-use industry, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume forecasts incorporating semiconductor fab capacity pipelines, hydrogen electrolysis project development, and automotive electrification transition rates. Industry-specific inputs included pharmaceutical sterility assurance validation timelines and REACH chemical restriction phase-in schedules.
Sensitivities concentrate around ECHA PFAS restriction finalization, Chinese PTFE export license protocols, and hydrogen infrastructure deployment pace. Forecasts reflect documented assumptions on regulatory harmonization and feedstock price stability. Quarterly review of ECHA substance listings, MEE enforcement intensity, and CDSCO GMP inspection schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Hydraulic Filters Market
Filters
Global Industrial Filters Market
Filters
Canada Filtration and Separation Market
Filters
Color Filter Glass Market
Filters
Intake Filter Media Market
Filters
Fabric Filters Market
Filters
String Wound Filter Materials Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Chloramine Filter Market
Filters
Coolant Filtration Systems Market
Filters
Europe Activated Carbon Market
Filters
Air Filtration Media Market
Filters
Industrial Filter Paper Market
Filters
Global Filter Press Market
Filters
Zeolite Adsorbents Market