
 Respirator Cartridges and Filters Market | 2026-2036
Respirator Cartridges and Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Respirator Cartridges and Filters Market Insights
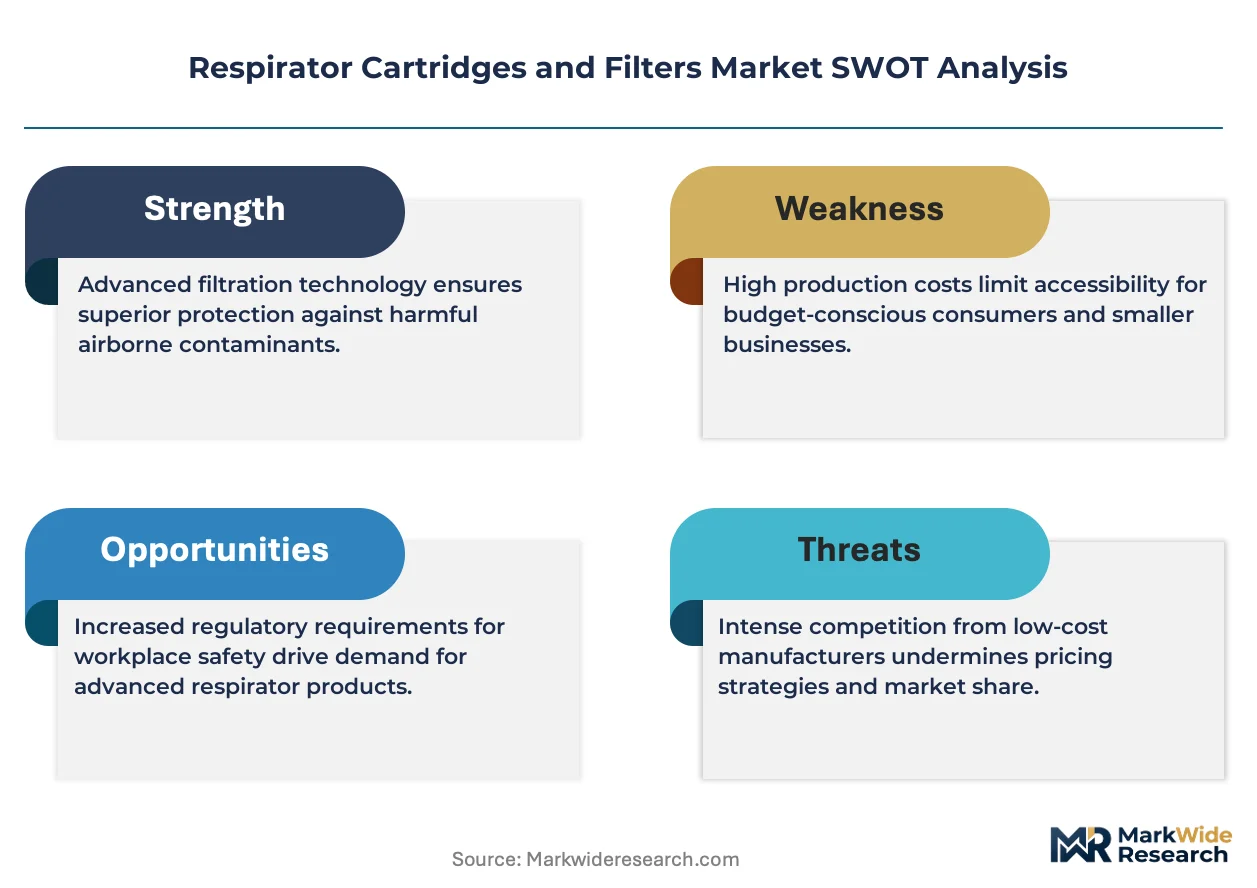
NIOSH 42 CFR 84 certification is rotating as the decisive gate for market participation, with non-compliant suppliers losing federal and industrial procurement eligibility. 3M leverages its dual strength in filter media chemistry and distribution infrastructure to sustain dominance across healthcare and heavy manufacturing channels. MSA Safety anchors its position through integrated head protection platforms that bundle cartridges with full-face respirator systems. Honeywell competes via advanced polymer membrane R&D, differentiating its portfolio in chemical processing environments where gas-specific sorption matters.
Respirator cartridges and filters are replaceable air-purifying elements engineered to remove particulates, gases, or vapors through mechanical filtration, activated carbon adsorption, or catalytic conversion, with efficiency ratings tied to NIOSH P100, N95, or OSHA substance-specific classifications. Cartridges containing activated carbon dominate current volume due to broad-spectrum organic vapor protection, while HEPA filters command premium positioning in healthcare and pharmaceutical cleanrooms where sub-micron biological containment is mandatory. Combination units represent the fastest-growing configuration as end users seek reduced inventory complexity and faster donning protocols across multi-hazard construction and chemical processing sites.
OSHA enforces workplace exposure limits that mandate cartridge change schedules and fit testing, while NIOSH certifies minimum filtration efficiency through 42 CFR 84, and the FDA regulates surgical N95 respirators under 21 CFR 878.4040 for healthcare settings. This regulatory triad elevates compliance costs for new entrants but locks in recurring revenue for certified incumbents through mandated replacement cycles and audit-driven inventory turnover. Stakeholders must monitor emerging substance-specific rulemakings and state-level infectious disease preparedness mandates that could abruptly expand addressable demand beyond traditional industrial footprints.
Market Dynamics
OSHA's tightened permissible exposure limits for silica and hexavalent chromium are forcing accelerated cartridge replacement cycles and mandatory fit-test documentation, converting compliance from episodic cost to recurring operational rhythm across construction and manufacturing facilities.
Growth Catalysts
- NIOSH 42 CFR 84 certification mandates:Federal procurement standards now disqualify non-certified suppliers from hospital system and defense contracts, locking certified incumbents into long-term supply relationships with mandated replacement schedules.
- Healthcare infectious disease preparedness:Hospital consolidation into multi-facility systems drives bulk purchasing of N95 and P100 configurations for pandemic stockpiling and routine airborne isolation protocols.
- Activated carbon chemistry advances:Impregnated carbon formulations now target specific chemical families, expanding addressable hazards beyond organic vapors to include ammonia, mercury, and formaldehyde in semiconductor cleanrooms.
Market Restraints
- Filter media supply concentration:High-efficiency meltblown polypropylene for N95-grade filtration concentrates among specialized chemical processors, creating input vulnerability during resin price spikes.
- Regulatory friction from dual jurisdiction:Surgical N95 respirators fall under FDA 21 CFR 878.4040 and NIOSH 42 CFR 84 simultaneously, doubling certification timelines and testing costs for new entrants.
- Substitution by powered air-purifying respirators:Battery-driven PAPR systems eliminate fit-test dependency and reduce facial seal failure rates in high-exertion foundry and demolition environments.
Strategic Opportunities
- Underpenetrated chemical processing clusters:Gulf Coast petrochemical corridors show cartridge inventory management gaps where predictive analytics could automate change-out scheduling based on real-time exposure monitoring.
- Combination cartridge standardization:Multi-hazard units integrating particulate filtration with gas/vapor adsorption reduce SKUs and donning time, appealing to construction contractors facing rotating chemical exposures.
- State-level infectious disease mandates:California and New York are expanding respiratory protection program requirements beyond federal minimums, creating premium demand for documented compliance solutions.
Industry Challenges
- Fit-tester certification scarcity:Qualified technicians for quantitative fit testing using PortaCount protocols remain concentrated in metropolitan industrial hygiene consultancies, creating service bottlenecks in rural manufacturing zones.
- Legacy inventory incompatibility:Cartridge-to-facepiece thread standards vary across 3M Bayonet, Honeywell Standard, and MSA Snap-in systems, forcing end users into single-vendor lock-in or adapter complexity.
- HEPA filter integrity testing burden:Pharmaceutical cleanrooms require annual in-situ aerosol challenge testing, adding operational overhead that compressed lead times struggle to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respirator Cartridges and Filters Market |
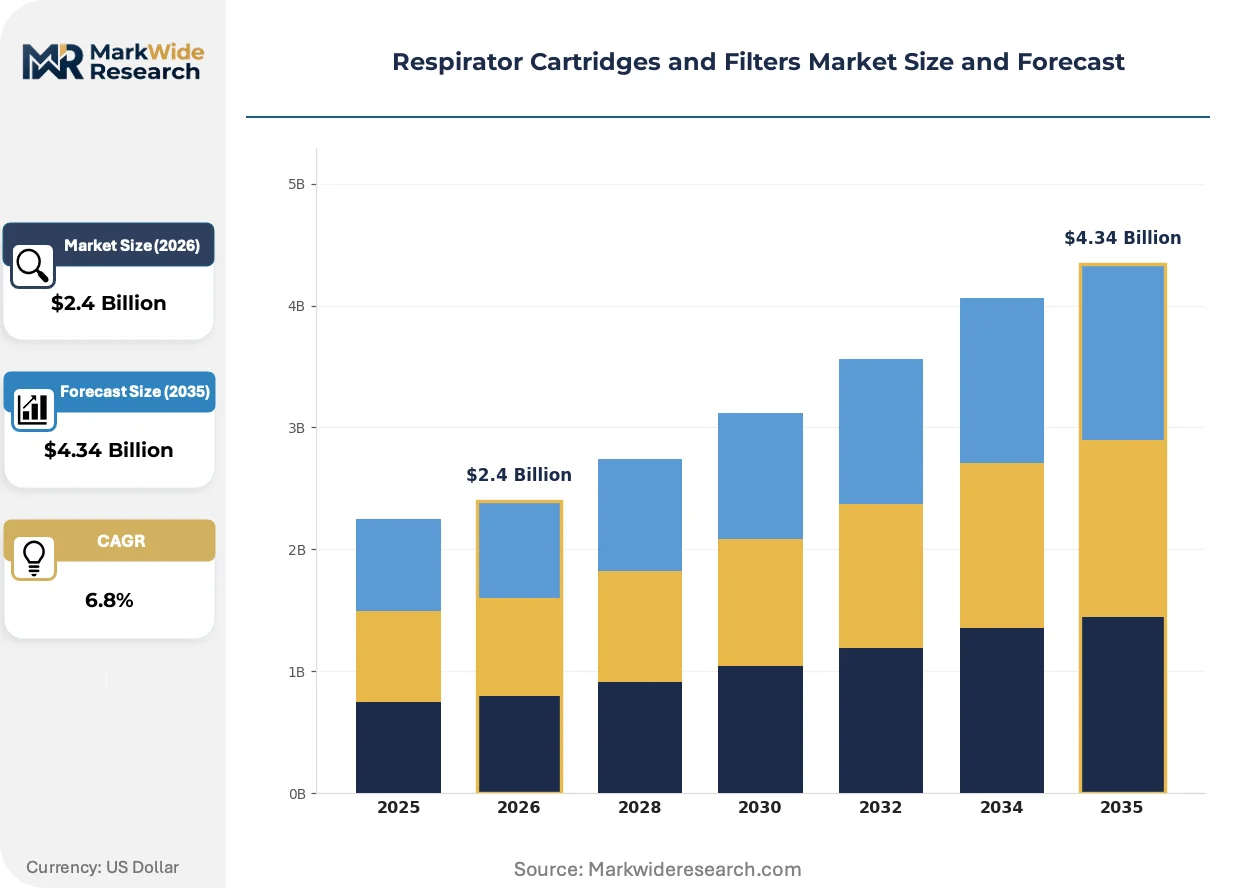
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartridges, Filters, Combination Units, Gas Masks Application: Construction, Healthcare, Manufacturing, Chemical Processing End User: Industrial Workers, Medical Professionals, Maintenance Staff, Emergency Responders Material: Activated Carbon, HEPA, Polymer Membranes, Metal |
| Companies Covered | 3M, MSA Safety, Honeywell, Moldex, Sundstrom Safety, Cole-Parmer, Bullard, Air Systems International, Dräger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respirator Cartridges and Filters Market Trends and Innovations
Electrospun nanofiber media and connected exposure sensors are decomposing the traditional cartridge as a passive commodity, repositioning respiratory protection as an integrated environmental monitoring system with predictive maintenance capabilities.
Electrospun polyurethane nanofiber webs with sub-micron fiber diameters are achieving N99-equivalent efficiency at 40% lower breathing resistance than meltblown polypropylene. Pharmaceutical cleanroom operators in Massachusetts and North Carolina are piloting these configurations for extended-wear pharmaceutical manufacturing. The technology is decomposing the trade-off between filtration efficiency and user comfort that has historically driven non-compliance in high-exertion settings.
REACH Annex XVII restrictions on chromium VI compounds in leather tanning and metal finishing are expanding the addressable market for specialized cartridges targeting hexavalent chromium across EU manufacturing zones. German chemical processors must now document respiratory protection adequacy through mandatory workplace exposure assessments. The regulation is accelerating demand for cartridge configurations with documented service life under specific concentration-time profiles rather than generic change schedules.
Hospital system group purchasing organizations are consolidating cartridge procurement into multi-year sole-source agreements with compliance auditing provisions, displacing fragmented spot purchasing through industrial distributors. This concentration is most visible in Texas and Florida where Catholic health systems and for-profit chains dominate bed capacity. The shift is compressing vendor margins while rewarding suppliers with integrated fit-testing services and electronic inventory management platforms.
Respirator Cartridges and Filters Market Segmentation
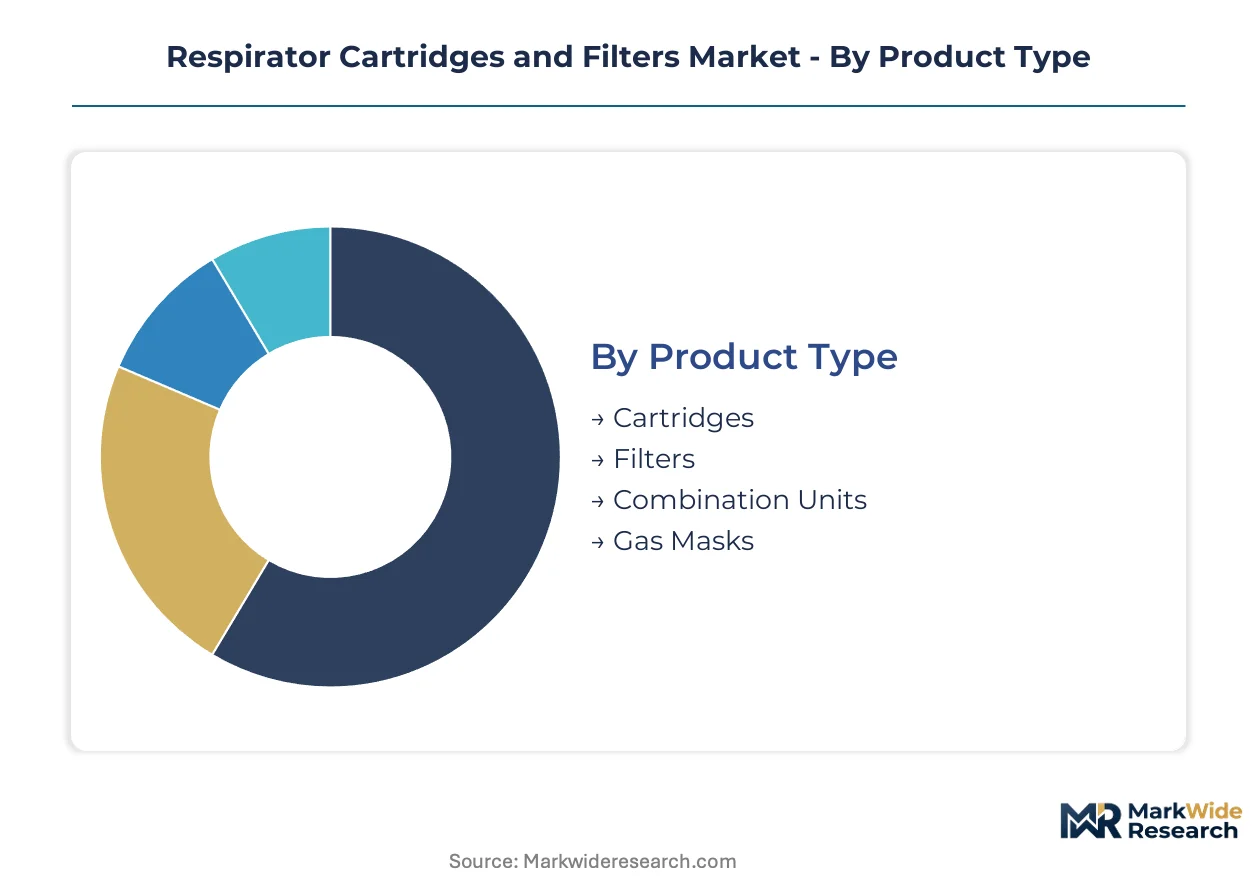
Respirator cartridge and filter procurement channels diverge sharply by segment, with industrial distributors dominating high-volume cartridge replacement while healthcare group purchasing organizations concentrate N95 and P100 orders into sole-source contracts. Understanding these channel dynamics shapes go-to-market strategy and margin capture across the value chain.
Product Type:
Channel concentration varies dramatically across product configurations, with industrial supply houses capturing recurring cartridge volume while safety equipment specialists handle complex gas mask system integration.
- Cartridges:Replaceable canisters containing activated carbon or specialized sorbent media for organic vapors, acid gases, and ammonia. Demand clusters in Texas and Louisiana petrochemical corridors where OSHA mandates drive scheduled replacement programs at refineries and chemical plants.
- Filters:Particulate-removing elements rated N95 through P100 for mechanical filtration of dust, mists, and biological aerosols. Hospital systems in Florida and California bulk-purchase these configurations for airborne isolation protocols and pandemic stockpiles, with Catholic health networks consolidating procurement into multi-year agreements.
- Combination Units:Integrated cartridges combining particulate filtration with gas/vapor adsorption in single-donning configurations. These reduce inventory complexity for construction contractors facing rotating chemical exposures across demolition and remediation sites.
- Gas Masks:Full-face respirator systems with threaded cartridge interfaces for military and emergency response applications. Federal defense contracts and municipal hazmat teams drive procurement through specialized safety distributors with NIOSH certification documentation capabilities.
Cartridges dominate installed base volume. Combination units are where expansion concentrates fastest as multi-hazard environments proliferate.
Application:
Cost-tier stratification separates premium healthcare and semiconductor cleanroom specifications from standard industrial configurations, with price multiples reaching 4-5x for documented compliance solutions in regulated environments.
- Construction:Silica exposure during concrete cutting and demolition drives demand for P100 filters and organic vapor cartridges. OSHA's tightened permissible exposure limits for respirable crystalline silica are accelerating replacement cycles and fit-test documentation requirements across union and non-union contractors.
- Healthcare:N95 and surgical respirator demand concentrates in hospital systems with mandated respiratory protection programs for tuberculosis, influenza, and emerging infectious diseases. Texas and Florida for-profit chains are consolidating procurement through group purchasing organizations with compliance auditing provisions.
- Manufacturing:Metal fabrication and foundry operations require cartridges targeting hexavalent chromium and welding fumes. MSA Safety and Honeywell compete through integrated head protection platforms bundling cartridges with welding helmets and full-face systems.
- Chemical Processing:Semiconductor cleanrooms and pharmaceutical manufacturing demand HEPA and activated carbon configurations with documented service life under specific concentration-time profiles. Massachusetts and North Carolina facilities pilot electrospun nanofiber media for extended-wear applications with lower breathing resistance.
Healthcare commands premium pricing tiers. Chemical processing shows the steepest expansion trajectory as cleanroom standards tighten and biologics manufacturing scales.
End User:
Customer-type segmentation reveals diverging procurement sophistication, with industrial safety managers optimizing total cost of ownership while medical facility administrators prioritize liability reduction and audit documentation.
- Industrial Workers:Manufacturing and construction personnel requiring scheduled cartridge replacement under OSHA respiratory protection standards. Fit-tester certification scarcity in rural manufacturing zones creates service bottlenecks that metropolitan industrial hygiene consultancies exploit.
- Medical Professionals:Physicians, nurses, and technicians in airborne isolation and surgical settings. NIOSH 42 CFR 84 and FDA 21 CFR 878.4040 dual jurisdiction doubles certification costs, locking certified incumbents into long-term hospital supply relationships.
- Maintenance Staff:Facility and equipment repair personnel facing intermittent chemical exposure across diverse tasks. These users favor combination cartridges reducing SKU complexity and donning time variability.
- Emergency Responders:Fire departments, hazmat teams, and disaster relief personnel requiring CBRN-rated gas masks with standardized cartridge interfaces. Federal procurement standards disqualify non-NIOSH-certified suppliers from defense and homeland security contracts.
Industrial workers represent the deepest installed base. Emergency responders are gaining share fastest as CBRN preparedness mandates expand.
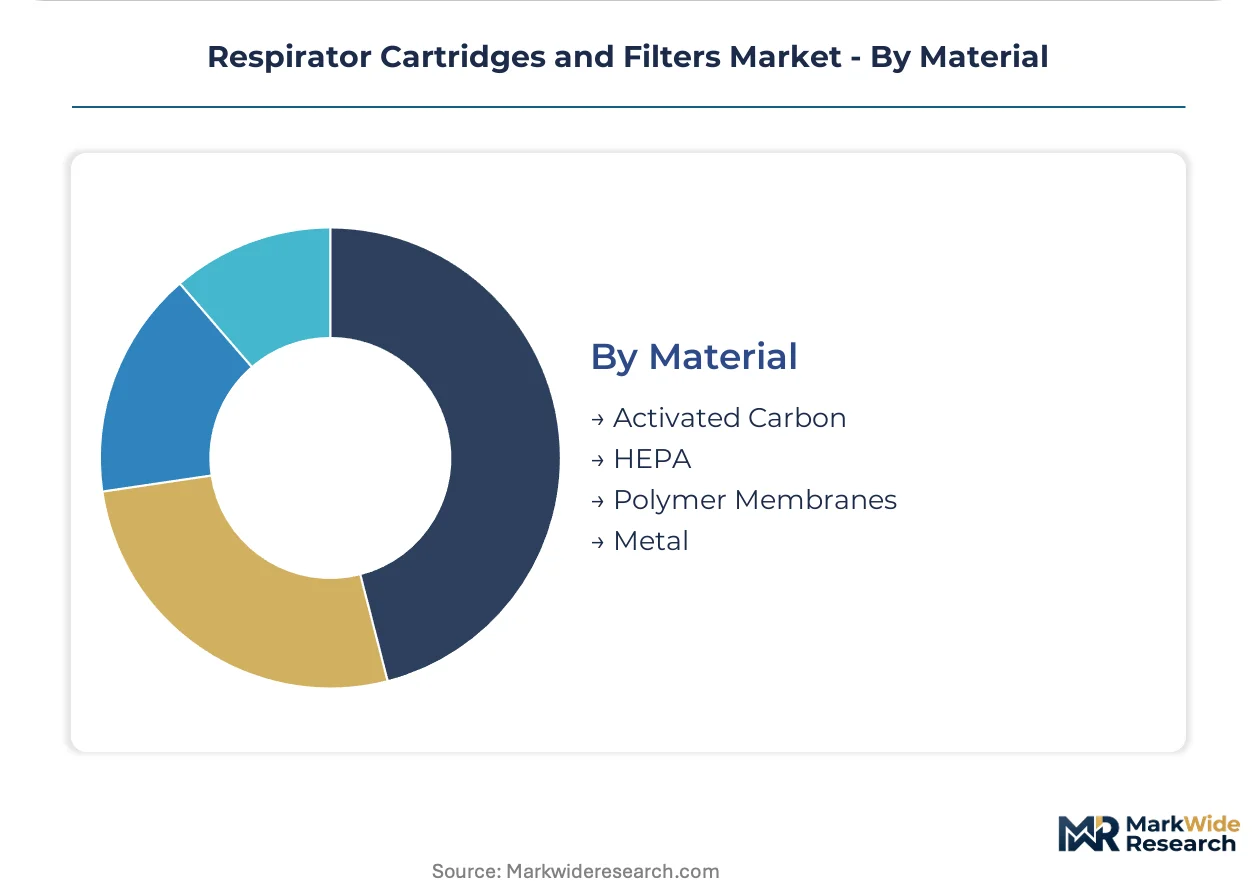
Material:
Supply concentration in high-efficiency meltblown polypropylene creates input vulnerability, with specialized chemical processors controlling N95-grade filtration media and resin price spikes transmitting directly to cartridge manufacturing costs.
- Activated Carbon:Impregnated carbon formulations dominate current volume through broad-spectrum organic vapor protection. Advances in impregnation chemistry now target ammonia, mercury, and formaldehyde in semiconductor cleanrooms, expanding addressable hazards beyond traditional organic vapors.
- HEPA:High-efficiency particulate air filters achieving 99.97% retention at 0.3 microns for pharmaceutical cleanrooms and healthcare isolation. Annual in-situ aerosol challenge testing requirements add operational overhead that compressed lead times struggle to accommodate.
- Polymer Membranes:Advanced polymer materials for chemical-specific sorption in processing environments. Honeywell competes through R&D investment in membrane selectivity for aggressive chemical families.
- Metal:Catalytic and structural components for specialized gas conversion applications. Limited volume concentrates in military and aerospace specifications requiring extreme temperature and chemical resistance.
Activated carbon dominates current material tonnage. Polymer membranes are climbing the fastest as chemical-specific selectivity requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement standards and tightening exposure limits are redrawing geographic demand patterns, with certified suppliers capturing procurement concentration in industrial corridors and consolidated hospital systems.
United States
OSHA's updated permissible exposure limits for silica and hexavalent chromium mandate accelerated cartridge replacement cycles across construction and manufacturing. Federal procurement standards disqualify non-NIOSH-certified suppliers from defense contracts and hospital system purchasing. Texas and Louisiana petrochemical corridors drive scheduled replacement programs at refineries and chemical plants.
Germany
REACH Annex XVII restrictions on chromium VI compounds expand demand for specialized cartridges in leather tanning and metal finishing. German chemical processors must document respiratory protection adequacy through mandatory workplace exposure assessments. The Ruhr industrial region and Bavarian manufacturing clusters show accelerating demand for cartridge configurations with documented service life under specific concentration-time profiles.
China
GB standards for occupational exposure limits are tightening enforcement across electronics manufacturing and semiconductor fabrication. The country's national workplace safety regulator is expanding respiratory protection program requirements in coastal industrial zones. Yangtze River Delta and Pearl River Delta electronics corridors pilot advanced polymer membrane configurations for cleanroom applications.
Japan
METI industrial safety guidelines emphasize predictive maintenance integration for respiratory protection systems in automotive and precision manufacturing. JIS standards for filtration efficiency create certification barriers for imported cartridge suppliers. Kanto and Kansai manufacturing belts concentrate demand for combination cartridges reducing inventory complexity across multi-hazard assembly environments.
India
Factory Act amendments and state-level occupational health mandates are expanding respiratory protection coverage in textile processing and metal fabrication. BIS certification requirements for personal protective equipment create compliance thresholds for cartridge suppliers. Gujarat and Maharashtra industrial corridors show procurement consolidation as multinational manufacturers implement global respiratory protection standards.
Respirator Cartridges and Filters Market Competitive Landscape
Listed leaders compete with private specialists across certification and distribution infrastructure, with NIOSH 42 CFR 84 compliance serving as the decisive gate for federal and industrial procurement eligibility. The market structure concentrates around dual-capability players combining filter media chemistry with distribution scale. Three archetypes dominate: integrated safety conglomerates with full-face respirator platforms, specialized cartridge manufacturers with gas-specific sorption expertise, and industrial distributors with compliance documentation capabilities. Competitive moves center on sole-source contract capture through integrated fit-testing services and predictive analytics platforms for automated change-out scheduling.
Within the integrated safety tier, 3M and MSA Safety exemplify archetypes leveraging dual strength in filter media and distribution infrastructure. Honeywell occupies a position representing advanced polymer membrane research investment. These three anchors illustrate how certification-backed incumbents lock in recurring revenue through mandated replacement cycles and audit-driven inventory turnover across healthcare and heavy manufacturing channels.
| Leading Market Players |
|---|
| 3M |
| MSA Safety |
| Honeywell |
| Moldex |
| Sundstrom Safety |
| Cole-Parmer |
| Bullard |
| Air Systems International |
| Dräger |
| Others |
Pricing and Supply Chain Analysis
High-volume meltblown polypropylene capacity utilization among specialized chemical processors in the United States, Germany, and China establishes minimum efficient scale thresholds that filter media suppliers must clear to serve NIOSH-certified cartridge manufacturers, concentrating upstream bargaining power and embedding cost floors that transmit through to hospital system procurement contracts and industrial distributor pricing schedules.
Pricing Analysis
Certification level (NIOSH 42 CFR 84/FDA 21 CFR 878.4040 dual-grade) creates the primary spread between premium healthcare configurations and standard industrial cartridges, with three-tier pricing structure separating documented compliance solutions from generic change schedules and spot-market spot purchasing. Price differentiation rests on after-sales service bundling—fit-testing protocols and electronic inventory management platforms command 15-25% premiums in Texas and Florida hospital systems. Cost compression in standard industrial tiers is intensifying because resin price spikes transmit directly through concentrated meltblown supply. Construction contractors show highest price sensitivity, while pharmaceutical cleanroom operators prioritize liability reduction over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate healthcare procurement, with Texas and Florida hospital systems maintaining 90-180 day N95 and P100 inventories for pandemic preparedness, while industrial distributors run just-in-time cartridge replenishment for manufacturing clients. Supply concentrates in the United States, Germany, and China for high-efficiency meltblown polypropylene, activated carbon impregnation, and advanced polymer membrane substrates. Raw material dependencies center on specialized polypropylene resins, coconut-shell activated carbon, and electrospun nanofiber precursors. Single-source vulnerability in meltblown media creates exposure during petrochemical feedstock disruptions. Distribution runs through industrial supply houses for recurring cartridge volume and safety equipment specialists for complex gas mask system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powered air-purifying respirator (PAPR) substitution threatens cartridge-based system incumbents, as battery-driven platforms eliminate fit-test dependency and reduce facial seal failure rates in high-exertion foundry and demolition environments.
For Market Incumbents: Fortify cartridge-to-facepiece compatibility positions by backward integration into filter media production or exclusive supply agreements with specialized meltblown processors, defending against PAPR displacement in foundry applications where exertion-driven seal failures concentrate. Anchor sole-source hospital system contracts through integrated fit-testing services and predictive analytics platforms that automate change-out scheduling based on real-time exposure monitoring, locking in recurring revenue against spot-market competitors. For New Entrants and Emerging Players: Lead with electrospun nanofiber media configurations targeting pharmaceutical cleanroom extended-wear applications in Massachusetts and North Carolina, where breathing resistance reduction commands premium positioning against incumbent meltblown suppliers. Target Gulf Coast petrochemical corridors with predictive inventory management solutions that address documented service life requirements under specific concentration-time profiles, a white space where incumbent distributors lack analytics capabilities. For Investors and Strategic Acquirers: Niche cartridge manufacturers with gas-specific sorption expertise and established NIOSH certification documentation capabilities present acquisition targets with durable competitive moats, as dual-jurisdiction FDA/NIOSH approval timelines deter new entrant replication. Long-term viability hinges on respiratory protection program mandate expansion beyond federal minimums, with state-level infectious disease preparedness legislation serving as the inflection signal to monitor for addressable demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | Dual FDA/NIOSH approval unlocks hospital system and defense procurement eligibility. |
| Backward Integration into Filter Media | Captive meltblown supply insulates margin compression from resin price volatility. |
| Predictive Analytics Platform Launch | Automated change-out scheduling addresses Gulf Coast petrochemical inventory gaps. |
| Electrospun Nanofiber R&D Partnership | Extended-wear configurations target Massachusetts pharmaceutical cleanroom pilots. |
| Hospital System Sole-Source Contract | Multi-year agreements with compliance auditing displace fragmented distributor purchasing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OSHA regulatory filings, NIOSH certification databases, hospital procurement records, and industrial distributor trade data, combining interviews with respiratory protection program managers, industrial hygiene consultants, GPO contracts directors, and filter media procurement leads with bottom-up and top-down triangulation across product configuration, application vertical, and geographic demand clusters.
Segmentation dimensions modeled include product type (cartridge, filter, combination unit, gas mask), application (construction, healthcare, manufacturing, chemical processing), end user archetype (industrial worker, medical professional, maintenance staff, emergency responder), and material substrate (activated carbon, HEPA, polymer membrane, metal), with CAGRs derived from regression analysis against OSHA enforcement expenditure, hospital bed capacity expansion, and petrochemical capacity utilization across the projection horizon. Industry-specific forecast inputs incorporate silica and hexavalent chromium exposure limit tightening schedules and state-level infectious disease mandate legislative tracking.
The analysis sits within stated boundaries; outcomes outside sustained NIOSH certification integrity, resin supply stability, and healthcare capital expenditure continuity would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement intensity and substitution technology adoption curves. Revision becomes warranted when PAPR battery cost-performance thresholds cross deployment inflection points in high-exertion industrial segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global High Temperature Filters Market
Filters
Air Filtration Media Market
Filters
Hydraulic Filters Market
Filters
Europe Activated Carbon Market
Filters
High Purity Chemical Filters Market
Filters
Industrial Filtration Market
Filters
Filters and Particle Monitoring Market
Filters
Global Gas Phase Filtration Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Chloramine Filter Market
Filters
Ceramic Filters Market
Filters
Fabric Filters Market
Filters
Coolant Filtration Systems Market
Filters
Zeolite Adsorbents Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Fabric Filter System Market