
 Fiberglass Filters Market | 2026-2036
Fiberglass Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Filters Market Analysis
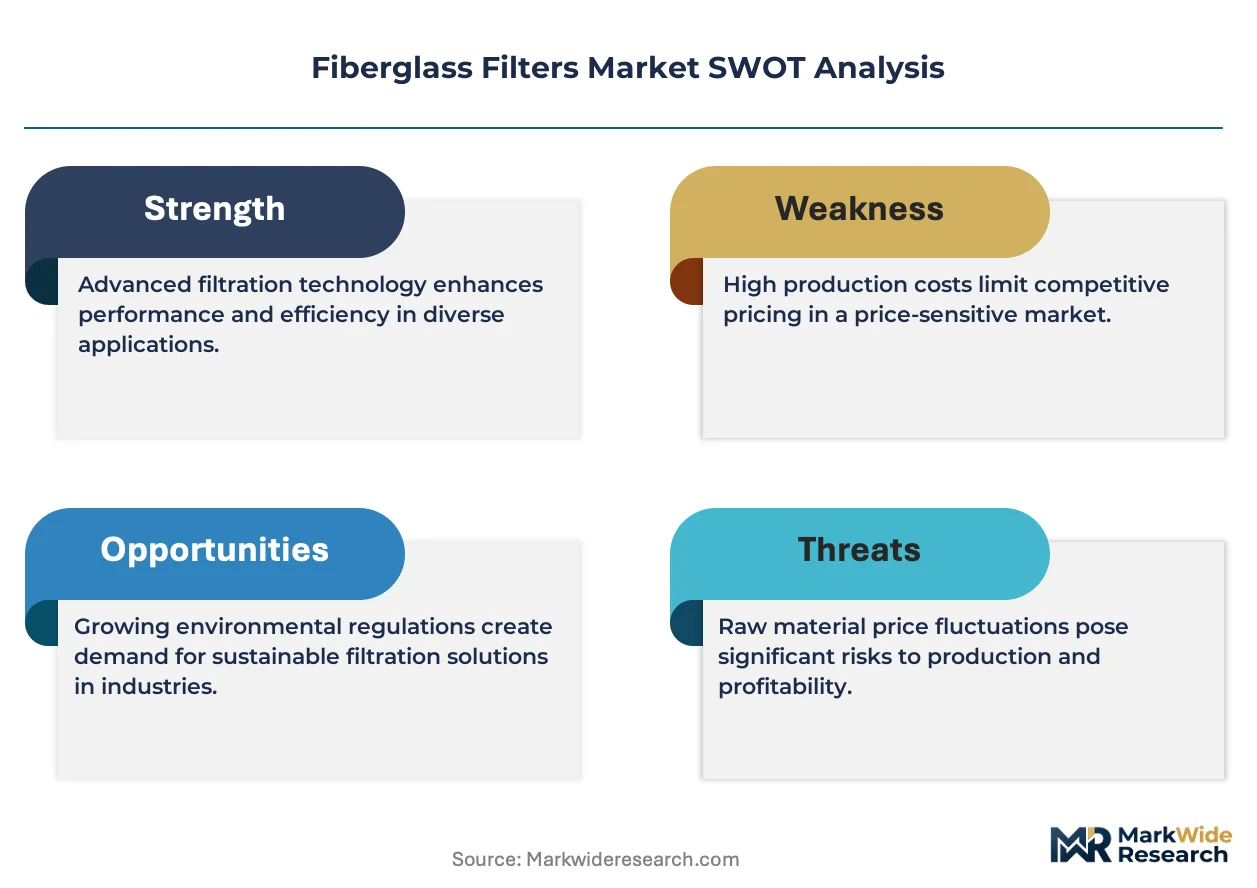
Data center operators and pharmaceutical cleanroom managers are bifurcating demand for fiberglass filters away from generic HVAC contractors. Camfil AB leverages its vertical integration into glass fiber media production to control supply quality from raw material to finished HEPA assembly. Freudenberg Group anchors its position through synthetic fiber R&D that extends filter lifecycles in high-humidity industrial environments. Donaldson Company competes on manufacturing scale across North American automotive and aerospace channels.
Fiberglass filters are depth-loading air and liquid filtration media constructed from borosilicate or E-glass microfibers bonded with synthetic resin, typically rated between MERV 11 and HEPA efficiency depending on fiber diameter and packing density. Their primary purpose is capturing sub-micron particulate in critical airflow systems without the electrostatic charge degradation that affects synthetic media over time. HEPA filters occupy the premium tier where margin pools concentrate in pharmaceutical and aerospace validation workflows, while pre-filters represent the high-volume replacement cycle that sustains aftermarket revenue. Activated carbon composite configurations are gaining fastest in water treatment and food processing where VOC and chlorine removal requirements now accompany particulate control.
EPA National Ambient Air Quality Standards and OSHA ventilation requirements in the United States shape minimum efficiency thresholds for commercial and industrial installations. ISO 16890 test protocols and EN 1822 classification in Europe determine product access and competitive positioning across export markets. China's GB/T 14295 and GB/T 13554 standards govern domestic filtration performance labeling. Stakeholders must monitor how regional efficiency test method divergence affects cross-border product certification costs and portfolio rationalization.
Market Dynamics
Pharmaceutical cleanrooms and data center operators are bifurcating procurement away from generic HVAC contractors toward direct relationships with validated filter manufacturers, compressing distributor margins while rewarding backward integration into glass fiber media production.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightened particulate thresholds in the United States force commercial facilities toward higher-efficiency MERV 13+ replacements, accelerating upgrade cycles in aging building stock.
- Semiconductor fabrication expansion:Taiwan and South Korea are adding cleanroom capacity that requires HEPA-grade fiberglass assemblies with documented fiber release certificates.
- Activated carbon composite configurations:Water treatment plants in the Yangtze River Delta are specifying combined particulate-VOC removal media for chlorine and industrial solvent capture.
Market Restraints
- Borosilicate glass fiber input volatility:Energy-intensive melting operations concentrate in China's Shandong province, exposing cost structures to regional power rationing and emission quota enforcement.
- Polypropylene melt-blown substitution:Synthetic depth media with electrostatic charging achieves comparable initial efficiency at 40-60% lower unit cost in non-critical HVAC pre-filter positions.
- EN 1822 test protocol divergence:European HEPA classification requirements for oil aerosol penetration testing create certification friction for manufacturers optimized to US IEST-RP-CC001 sodium flame methods.
Strategic Opportunities
- India's pharmaceutical manufacturing corridors:CDSCO inspection readiness requirements for export-oriented API facilities are mandating validated HEPA installations with documented filter integrity testing protocols.
- Data center liquid cooling integration:Immersion and direct-to-chip thermal management is creating demand for fiberglass media rated for dielectric fluid filtration alongside traditional air handling.
- EU F-Gas Regulation phase-down:Refrigerant containment standards are expanding leak detection and recovery system specifications that incorporate activated carbon composite filters for halogenated compound capture.
Industry Challenges
- HEPA assembly technician certification:Validated cleanroom filter production requires operators trained to ISO 14644-1 contamination control protocols, with qualified labor pools concentrated in Germany and Japan.
- Legacy pneumatic conveying retrofit:Food processing facilities with existing fiberglass dust collection infrastructure face integration complexity when upgrading to NFPA 68 explosion protection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Filters Market |
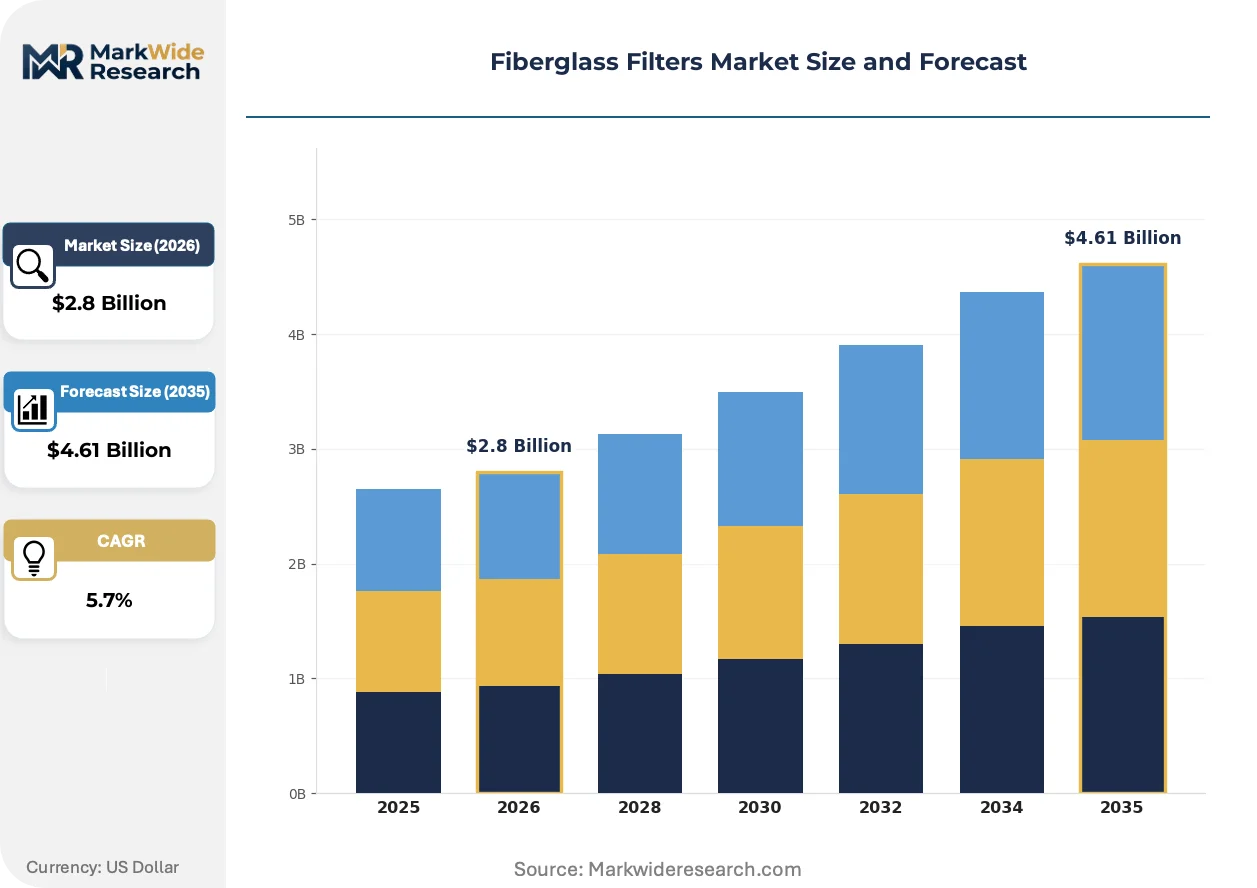
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Pre-Filters, High-Efficiency Filters, Activated Carbon Filters End User: Industrial Facilities, Commercial Buildings, HVAC Systems, Automotive Industry Application: Aerospace, Water Treatment, Pharmaceutical, Food Processing Material: Glass Fiber, Synthetic Fiber, Polyester, Polypropylene |
| Companies Covered | Camfil AB, Freudenberg Group, Donaldson Company, Inc., Troy Filters Ltd., Anya Filter Media, Parker Hannifin Corporation, Filtration Group Corporation, Smith Filters Manufacturer, MANN+HUMMEL International GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Filters Market Emerging Trajectories
Nanofiber surface loading technologies and IoT-enabled pressure differential monitoring are compressing traditional replacement cycles while enabling predictive maintenance business models in critical airflow infrastructure.
Electrospun nanofiber layers laminated onto traditional fiberglass substrates is decomposing the historical depth-loading paradigm by capturing sub-micron particulate at the media surface rather than throughout the matrix. Pharmaceutical aseptic filling operations are specifying these configurations for reduced pressure drop and extended service intervals. The technology is decomposing aftermarket revenue pools tied to scheduled replacement cycles by enabling condition-based maintenance contracts.
REACH restrictions on formaldehyde-based resin binders are forcing reformulation of fiberglass bonding chemistry across European supply chains. Manufacturers are migrating to acrylic and epoxy alternatives with comparable tensile strength but modified curing temperature profiles. Medical device sterilization facilities in Ireland and the Netherlands are absorbing 15-20% energy cost increases from modified production lines while awaiting ECHA substance authorization decisions.
Direct procurement contracts between end-users and filter manufacturers are displacing traditional HVAC distributor channels in data center and pharmaceutical verticals. Buyers are unbundling installation from media supply to capture validation documentation and traceability requirements. This channel compression is most visible in Northern Virginia's hyperscale data center cluster and Singapore's biomedical manufacturing hub.
Fiberglass Filters Market Segmentation
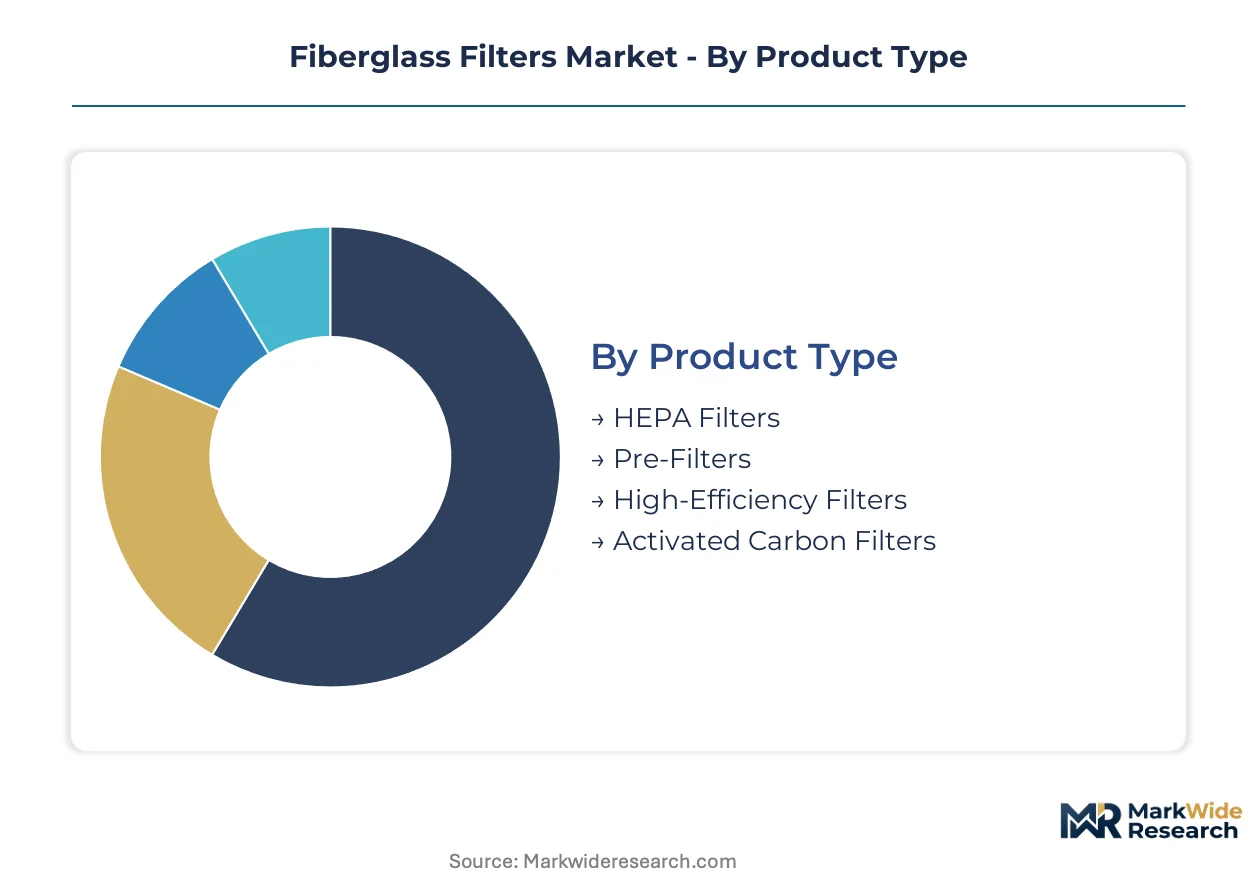
Segmentation in fiberglass filters reveals how procurement channels, certification requirements, and replacement cycles fragment across use cases. Channel strategy must align with whether buyers prioritize validation documentation, volume pricing, or technical service support.
Product Type:
Channel mix varies sharply by product tier—HEPA assemblies flow through direct manufacturer relationships, while pre-filters move via HVAC distributors and maintenance contractors.
- HEPA Filters:Constructed from borosilicate microfibers packed to 99.97% efficiency at 0.3 microns per IEST-RP-CC001 protocols. Pharmaceutical aseptic suites and semiconductor cleanrooms in Taiwan and South Korea require fiber release certificates and documented integrity testing, compressing distributor margins.
- Pre-Filters:Depth-loading media rated MERV 8-11 protects downstream HEPA stages in commercial HVAC and industrial dust collection. Aging building stock in the United States drives replacement volume through mechanical service contractors.
- High-Efficiency Filters:MERV 13-16 configurations bridge mid-tier commercial and light industrial applications.
- Activated Carbon Filters:Composite particulate-VOC media gains specification in water treatment and food processing for chlorine and solvent capture.
By volume, Pre-Filters leads. By growth pace, Activated Carbon Filters is ahead.
End User:
Cost tier segmentation separates specification-driven buyers from price-sensitive volume purchasers.
- Industrial Facilities:Heavy-process manufacturing in China's Yangtze River Delta and Germany's Ruhr region specifies validated media with pressure differential monitoring. NFPA 68 explosion protection retrofits complicate legacy pneumatic conveying upgrades.
- Commercial Buildings:EPA National Ambient Air Quality Standards push MERV 13+ upgrades in U.S. office and retail stock. Property managers balance filtration performance against fan energy penalties.
- HVAC Systems:Original equipment and aftermarket replacement cycles differ in procurement authority—OEMs specify at design, facility managers optimize running cost.
- Automotive Industry:Paint spray booths and powertrain cleanrooms require controlled fiber release specifications.
Industrial Facilities command premium pricing. Commercial Buildings shows steepest expansion trajectory.
Application:
Application segmentation maps to regulatory intensity and validation burden.
- Pharmaceutical:Aseptic filling and API manufacturing under FDA and EMA oversight demands HEPA with documented fiber release, particle shedding, and integrity test protocols. CDSCO inspection readiness in India is tightening comparable requirements for export facilities.
- Aerospace:Cabin air and fuel system filtration must meet FAA and EASA flame resistance and outgassing specifications.
- Water Treatment:Municipal and industrial plants in the Yangtze River Delta specify combined particulate and VOC removal.
- Food Processing:NFPA 68 explosion protection standards complicate retrofit of legacy dust collection infrastructure.
Pharmaceutical dominates margin pools. Water Treatment is climbing the fastest.
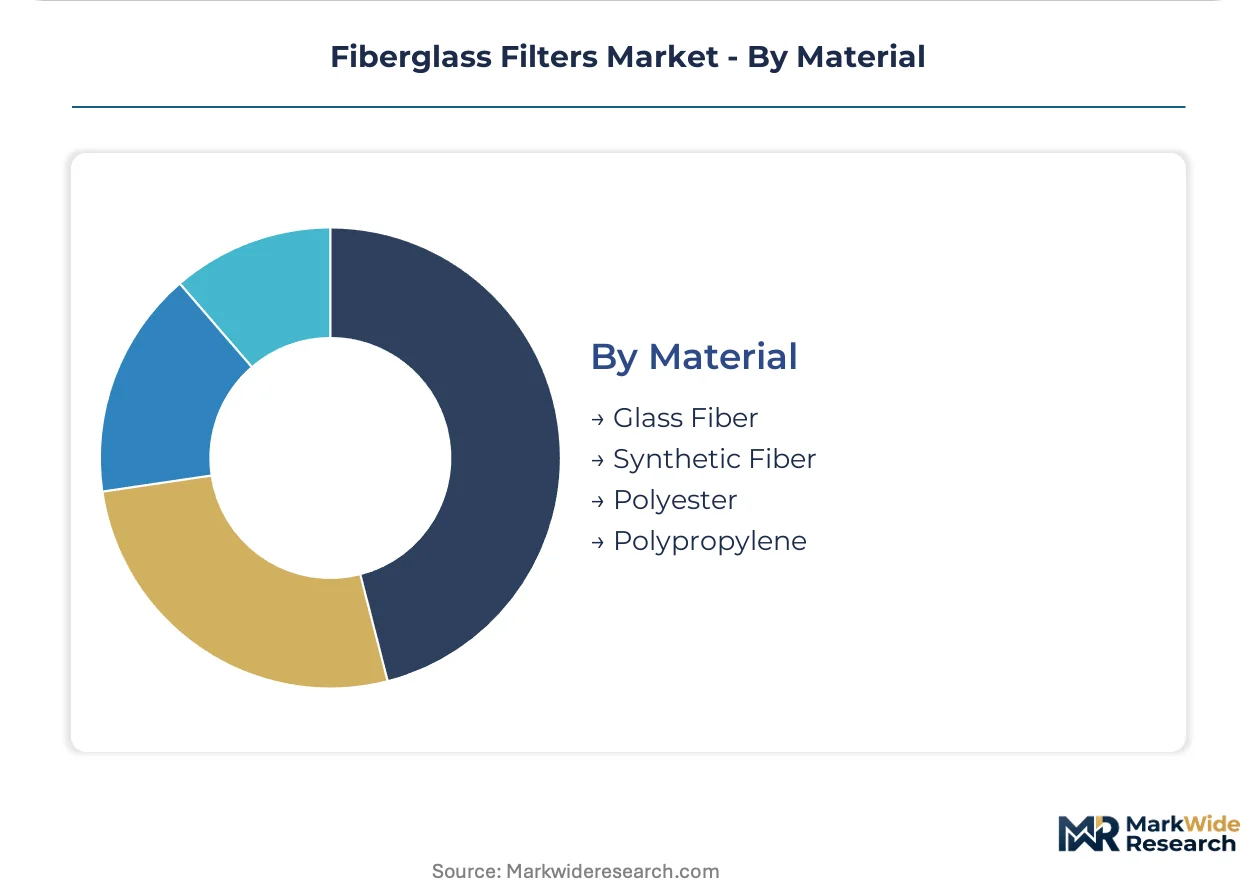
Material:
Supply concentration and input cost volatility differentiate material segments.
- Glass Fiber:Borosilicate and E-glass microfibers bonded with synthetic resin form the core of depth-loading HEPA and high-efficiency media. Energy-intensive melting operations concentrate in China's Shandong province, exposing cost structures to regional power rationing.
- Synthetic Fiber:Polypropylene melt-blown media with electrostatic charging achieves comparable initial efficiency at lower unit cost in non-critical HVAC positions.
- Polyester:Spunbond and needlefelt configurations serve liquid filtration and coarse particulate applications.
- Polypropylene:Chemical resistance drives specification in corrosive process streams and aggressive pH environments.
Glass Fiber anchors revenue by volume. Synthetic Fiber is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical cleanroom operators and data center managers in the United States, Germany, China, India, and South Korea are consolidating procurement relationships with validated filter manufacturers, bypassing traditional HVAC distribution channels to secure traceability documentation and fiber release certifications.
United States
Hyperscale data center construction in Northern Virginia and pharmaceutical manufacturing in Massachusetts and North Carolina drive HEPA specification. EPA National Ambient Air Quality Standards and OSHA ventilation requirements mandate MERV 13+ efficiency in commercial retrofits. The Southeast industrial corridor absorbs activated carbon composite filters for water treatment upgrades.
Germany
Automotive paint spray booths in Baden-Württemberg and pharmaceutical aseptic suites in Hesse anchor premium filter demand. REACH restrictions on formaldehyde-based resin binders force bonding chemistry reformulation across domestic supply chains. The Ruhr region's heavy-process manufacturing specifies validated media with pressure differential monitoring systems.
China
Semiconductor fabrication expansion in Shanghai and the Yangtze River Delta manufacturing cluster requires HEPA-grade assemblies with documented fiber release certificates. GB/T 14295 and GB/T 13554 standards govern domestic filtration performance labeling. Shandong province's energy-intensive glass fiber melting operations face regional power rationing exposure.
India
Export-oriented API facilities in Maharashtra and Gujarat mandate validated HEPA installations under CDSCO inspection readiness protocols. The country's national pharmaceutical regulator tightens comparable requirements for facilities supplying regulated markets. Karnataka's emerging biotech corridor attracts direct procurement contracts from multinational filter manufacturers.
South Korea
Memory chip cleanroom capacity additions near Seoul and Busan specify HEPA-grade fiberglass assemblies with sodium flame test documentation. The national industrial standards body aligns domestic protocols with international semiconductor equipment specifications. Daegu's automotive component manufacturing integrates controlled fiber release specifications for paint process filtration.
Fiberglass Filters Market Vendor Landscape
Player mix skews toward integrated media producers and specialized cleanroom validation specialists. The vendor base concentrates around three strategic tiers: multinational filtration conglomerates with captive glass fiber supply, mid-scale regional fabricators serving HVAC aftermarket channels, and nanofiber technology licensors compressing traditional replacement cycles. Dominant competitive moves include backward integration into borosilicate microfiber production and direct procurement contract capture in pharmaceutical and data center verticals.
Within the integrated multinational tier, Camfil AB and Freudenberg Group exemplify archetypes anchored in upstream media control and synthetic fiber R&D respectively. Donaldson Company occupies a position representing manufacturing scale concentration across North American industrial channels. These three entities anchor competitive positioning without exhaustive market coverage, as Troy Filters Ltd., Anya Filter Media, and Parker Hannifin Corporation populate adjacent specialization tiers serving validation-critical and volume-driven segments.
| Leading Market Players |
|---|
| Camfil AB |
| Freudenberg Group |
| Donaldson Company, Inc. |
| Troy Filters Ltd. |
| Anya Filter Media |
| Parker Hannifin Corporation |
| Filtration Group Corporation |
| Smith Filters Manufacturer |
| MANN+HUMMEL International GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Polypropylene melt-blown substitution in non-critical HVAC pre-filter positions simultaneously redraws supply geography toward synthetic fiber producers and compresses pricing economics for commodity-grade fiberglass media. This material shift fragments procurement authority between cost-driven facility managers and specification-driven cleanroom operators.
Pricing Analysis
Cost-plus contracts with borosilicate glass fiber indexation dominate HEPA-grade procurement, insulating validated manufacturers from raw material volatility while exposing pre-filter distributors to spot-market compression. Pricing stratifies across pharmaceutical validation tiers, industrial MERV 13+ retrofits, and commodity HVAC replacements. Cost compression in standard-efficiency segments intensifies because polypropylene alternatives achieve comparable initial efficiency at 40-60% lower unit cost. Facility managers in commercial buildings exhibit acute price sensitivity, whereas pharmaceutical cleanroom operators prioritize fiber release documentation over unit economics.
Supply Chain Analysis
Inventory lead times for HEPA-grade borosilicate microfiber extend disproportionately during Shandong province power rationing episodes, forcing manufacturers to pre-position safety stock ahead of emission quota enforcement periods. Supply concentrates in China's Shandong province for glass fiber melting, Germany's Baden-Württemberg for HEPA assembly technician certification, and the United States for pharmaceutical validation workflows. The supply chain rests on energy-intensive melting operations, synthetic resin binders subject to REACH restrictions, and specialized pleating equipment. Single-source vulnerability in Shandong's power-dependent production creates regional disruption risk. Distribution runs through direct manufacturer relationships for HEPA and HVAC distributors for pre-filters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiberglass filters market sits in early-cycle expansion as EPA and OSHA mandates force MERV 13+ upgrades across aging U.S. commercial building stock, accelerating replacement velocity beyond historical baselines.
For Market Incumbents: Secure backward integration into borosilicate microfiber production to insulate margin structures from Shandong power rationing volatility. Expand HEPA assembly capacity in Germany and Japan where ISO 14644-1 certified technician pools concentrate, defending against emerging entrants lacking contamination control credentials. Capture direct procurement contracts in Northern Virginia data centers and Singapore biomedical hubs before channel compression eliminates distributor intermediaries entirely. For New Entrants and Emerging Players: Predictive maintenance service layers represent the most penetrable gap where incumbents under-serve, particularly IoT-enabled pressure differential monitoring for industrial facilities in China's Yangtze River Delta. Target India's pharmaceutical manufacturing corridors where CDSCO inspection readiness requirements outpace validated filter supply. Enter through nanofiber surface loading technology licensing to bypass capital-intensive glass fiber melting infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional HVAC distributors facing margin compression from direct procurement trends. Five-to-ten year viability hinges on portfolio exposure to validation-critical segments versus commodity replacement cycles. Watch for EN 1822 and IEST-RP-CC001 test protocol harmonization as an inflection indicator for cross-border certification cost rationalization and consolidation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Melting | Captive borosilicate supply from Shandong province insulates HEPA manufacturers from regional power rationing exposure. |
| Direct Procurement Contract Capture | Bypassing HVAC distributors in Northern Virginia data centers secures validation documentation and traceability premiums. |
| Nanofiber Surface Loading Technology Licensing | Electrospun layers enable condition-based maintenance contracts that compress traditional scheduled replacement cycles. |
| HEPA Assembly Capacity Expansion in Germany | Proximity to ISO 14644-1 certified technician pools addresses qualified labor scarcity in validated cleanroom filter production. |
| Activated Carbon Composite Formulation Development | Combined particulate-VOC media captures water treatment and food processing specifications in the Yangtze River Delta. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical cleanroom operators, data center facility managers, HVAC maintenance contractors, and glass fiber media procurement leads, then refined against secondary validation from EPA enforcement databases, OSHA ventilation compliance records, SEC 10-K filings of listed filtration manufacturers, and Chinese customs trade statistics for borosilicate fiber imports. Bottom-up demand modeling across end-use segments was triangulated with top-down market sizing from industry association capacity surveys.
Variance decomposition across product tiers, application intensity, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level replacement cycle analysis, efficiency upgrade penetration curves, and validated cleanroom capacity expansion pipelines. Modeled inputs included semiconductor fabrication cleanroom additions in Taiwan and South Korea, pharmaceutical API facility inspections under India's CDSCO protocols, and EPA National Ambient Air Quality Standards enforcement trajectories.
Underlying assumptions cover sustained EPA and OSHA mandate enforcement, continued semiconductor capital expenditure in East Asia, and stable borosilicate glass fiber supply from Shandong province, with deviation risk concentrated in power rationing severity, REACH binder authorization delays, and polypropylene substitution acceleration in non-critical HVAC positions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Filter Coatings Market
Filters
Global Gas Phase Filtration Market
Filters
Aerospace Filter Market
Filters
Single-Use Filtration Assemblies Market
Filters
Global Liquid Filtration Market
Filters
Filter Paper Market
Filters
String Wound Filter Materials Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Residential Filters Market
Filters
Global Filter Market
Filters
Color Filter Glass Market
Filters
Europe Activated Carbon Market
Filters
Filtering Centrifuges Market
Filters
Global Depth Filtration Market
Filters
North America Gas Filtration Media Market