
 Global Hemostasis Diagnostics Market | 2026-2036
Global Hemostasis Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemostasis Diagnostics Market Intelligence
China's expansion of domestic diagnostic manufacturing capacity is reshaping competitive positioning for established market participants. Siemens Healthineers leverages its extensive R&D in automation to maintain a technological edge in coagulation analyzers. At the same time, Diagnostica Stago sustains its market presence through deep specialization in thrombosis and hemostasis reagents. Werfen focuses on integrated solutions for hospital laboratories, securing a strong foothold in key European markets.
Hemostasis diagnostics encompass a range of laboratory tests and devices used to evaluate the blood's clotting cascade. These systems measure key parameters like prothrombin time (PT) and fibrinogen levels to assess coagulation function. Their primary purpose is to diagnose and monitor bleeding disorders and guide anticoagulant therapy. While coagulation analyzers for diagnostic laboratories remain the largest product segment, point-of-care devices represent the fastest-growing category due to their rapid turnaround times in surgical and emergency settings.
Regulatory frameworks from the U.S. FDA, the European Union's MDR for CE marking, and China's NMPA govern market access for hemostasis diagnostic devices. These agencies mandate stringent performance validation and clinical evidence, directly influencing product design and development timelines. The critical decision for healthcare systems now revolves around balancing the cost-efficiency of centralized laboratory testing against the clinical benefits of decentralized point-of-care diagnostics.
Market Dynamics
The central structural force in the hemostasis diagnostics market is the clinical and economic tension between centralized, high-throughput laboratory systems and decentralized point-of-care testing. This dynamic influences purchasing decisions, product development, and regulatory focus across all geographies.
Growth Catalysts
- Regulatory Streamlining:Expedited clearance pathways from agencies like the U.S. FDA and revised frameworks such as the EU's MDR are lowering barriers for innovative point-of-care devices, accelerating their market entry.
- Healthcare Infrastructure Expansion:Substantial government investment in new hospital construction and laboratory modernization, particularly in China, creates direct demand for a full spectrum of coagulation analyzers and reagents.
- Rising Anticoagulant Use:An increasing patient population on long-term anticoagulant therapies for conditions like atrial fibrillation necessitates more frequent and accessible monitoring, directly spurring demand for PT/INR testing.
Market Restraints
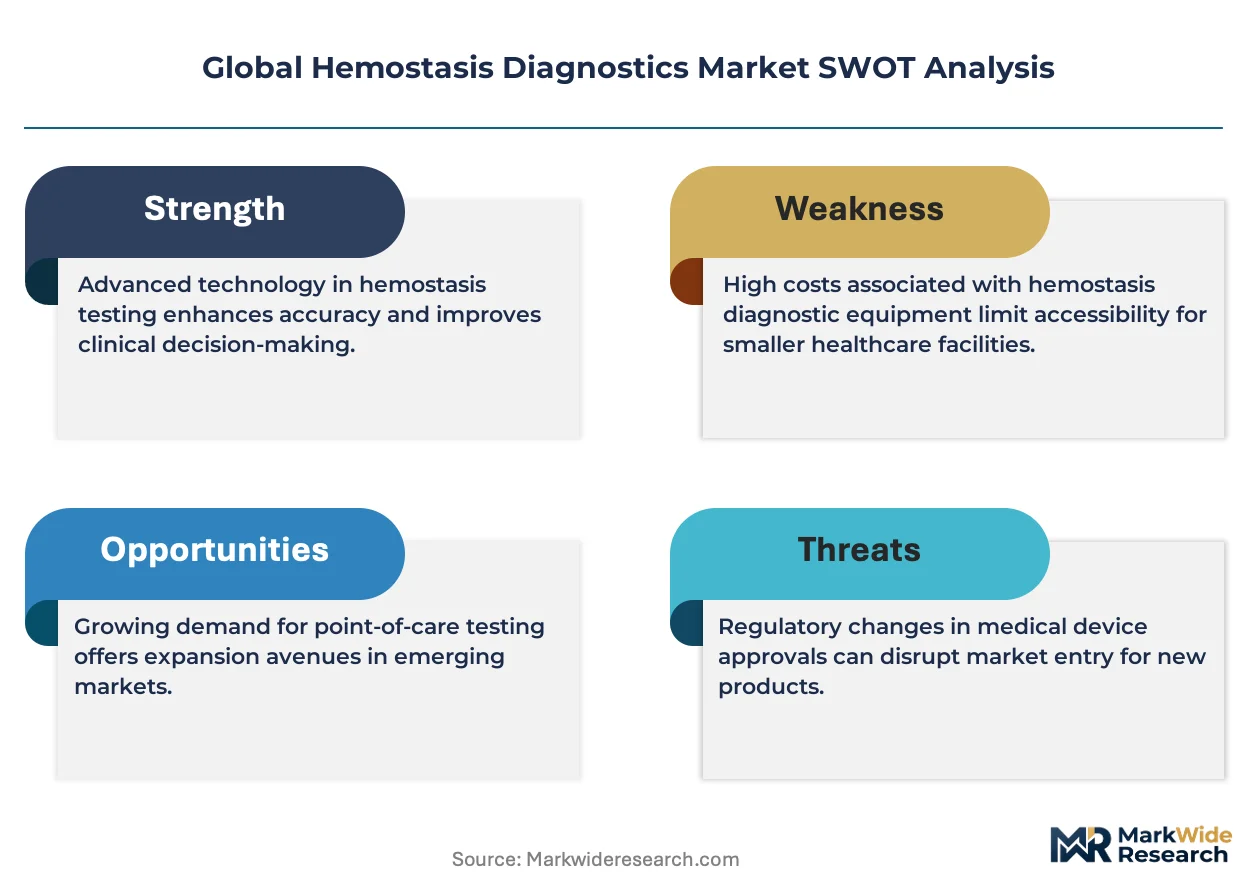
- High Capital Costs:The significant initial investment required for fully automated, high-throughput coagulation analyzers acts as a major barrier for smaller clinics and laboratories with constrained budgets.
- Reimbursement Inconsistencies:Disparities in reimbursement codes and payment levels for point-of-care hemostasis tests across different national and private insurance systems can deter adoption by healthcare providers.
- Assay Standardization Challenges:A lack of complete standardization for results between different manufacturers' instruments and reagent lots, especially for specialized tests, complicates clinical interpretation and limits interchangeability.
Strategic Opportunities
- Telehealth Platform Integration:Developing POC devices with digital connectivity allows for remote monitoring of patients on anticoagulant therapy, creating a new service model integrated with virtual care platforms.
- Surgical and Trauma Applications:There is a significant opportunity for viscoelastic testing systems that provide a holistic view of clot formation in real-time to guide transfusions in operating rooms and trauma centers.
- Biomarker Expansion:Incorporating novel biomarkers of platelet function and fibrinolysis into routine hemostasis testing panels can provide deeper diagnostic insights beyond traditional clotting time measurements.
Industry Challenges
- Data Interoperability:Ensuring seamless integration of test results from diverse laboratory and point-of-care analyzers into hospital information systems and electronic health records remains a complex technical hurdle.
- Skilled Personnel Shortages:A lack of trained laboratory technologists qualified to perform complex coagulation testing and maintain sophisticated instrumentation can create operational bottlenecks in diagnostic services.
- Compliance with Evolving Regulations:Adhering to the increasingly stringent clinical evidence and post-market surveillance requirements of bodies like the EU MDR and China's NMPA demands significant resource investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemostasis Diagnostics Market |
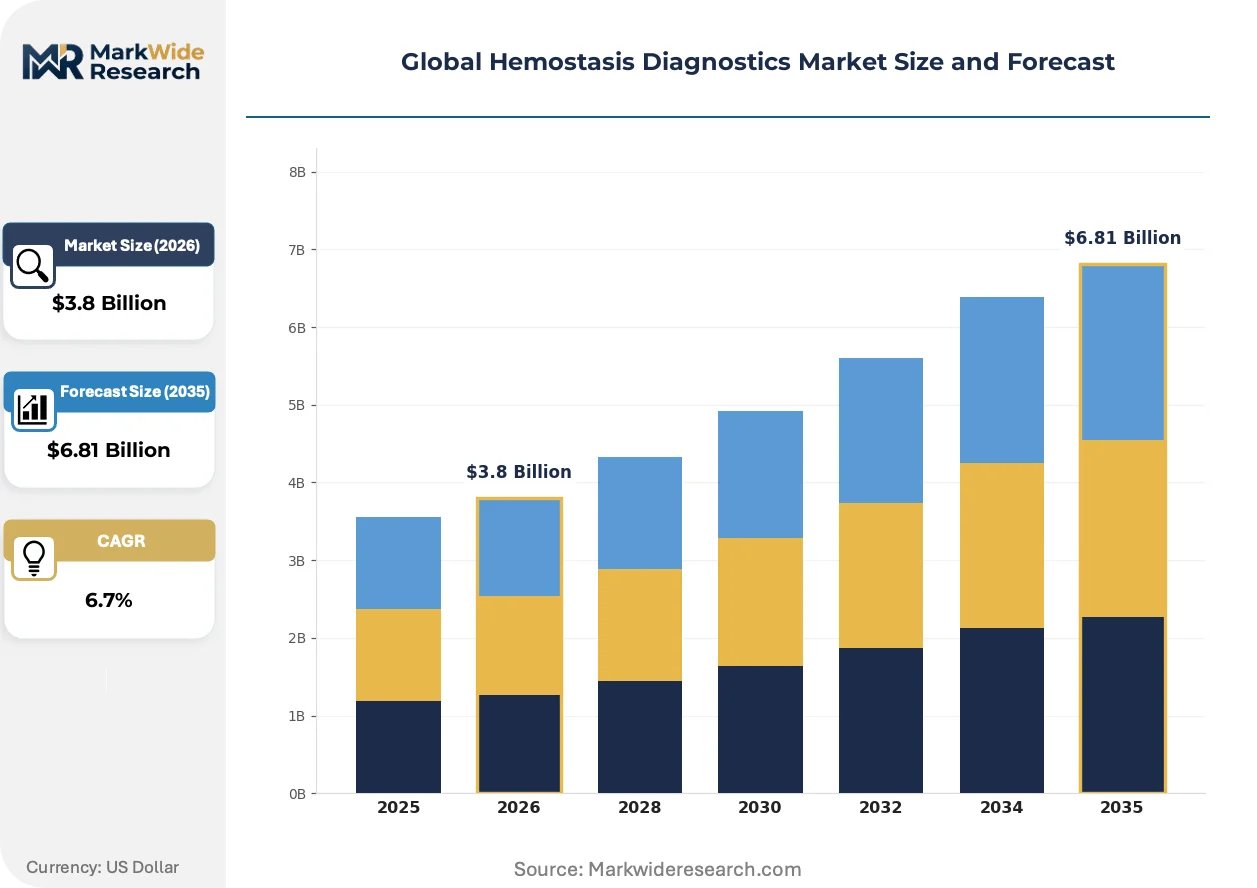
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulation Analyzers, Platelet Function Analyzers, Hemostasis Reagents, Point-of-Care Devices Technology: Optical, Electromechanical, Chromogenic, Immunoturbidimetric, Fluorescence, Electrochemical Application: Bleeding Disorder Diagnosis, Thrombosis Monitoring, Surgery Screening, Anticoagulant Therapy Monitoring End User: Diagnostic Laboratories, Blood Banks, Pharmaceutical Firms, Academic Research Centers |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers, Sysmex Corporation, Abbott Laboratories, Thermo Fisher Scientific, Danaher Corporation, Diagnostica Stago, Werfen, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemostasis Diagnostics Market Strategic Shifts & Innovations
The evolution of hemostasis diagnostics is defined by automation, miniaturization, and data integration. These forces are pushing testing capabilities out of the central lab and closer to the patient, changing clinical workflows and vendor value propositions.
Microfluidic technology is the core enabler for modern point-of-care hemostasis devices, allowing for complex assays on a single, disposable cartridge with a small blood sample. Emergency departments and surgical suites are rapidly adopting these platforms for their speed and ease of use. This on-site capability is rendering obsolete the reliance on central labs for urgent coagulation status checks.
Implementation of the European Union's Medical Device Regulation (MDR) has intensified scrutiny on clinical performance and risk management. This regulation mandates more extensive clinical evidence and proactive post-market surveillance for all devices seeking or holding a CE mark. Manufacturers of coagulation analyzers and reagents are most impacted, investing heavily to update technical files and clinical data to ensure compliance.
Consolidation among healthcare providers is driving a shift from transactional equipment purchases to long-term, managed service contracts for laboratory diagnostics. This model disrupts the traditional sales channel by bundling instruments, reagents, software, and maintenance into a single operational expense. The trend is most visible in large hospital networks across North America and Europe aiming to standardize testing and control costs.
Global Hemostasis Diagnostics Market Segmentation
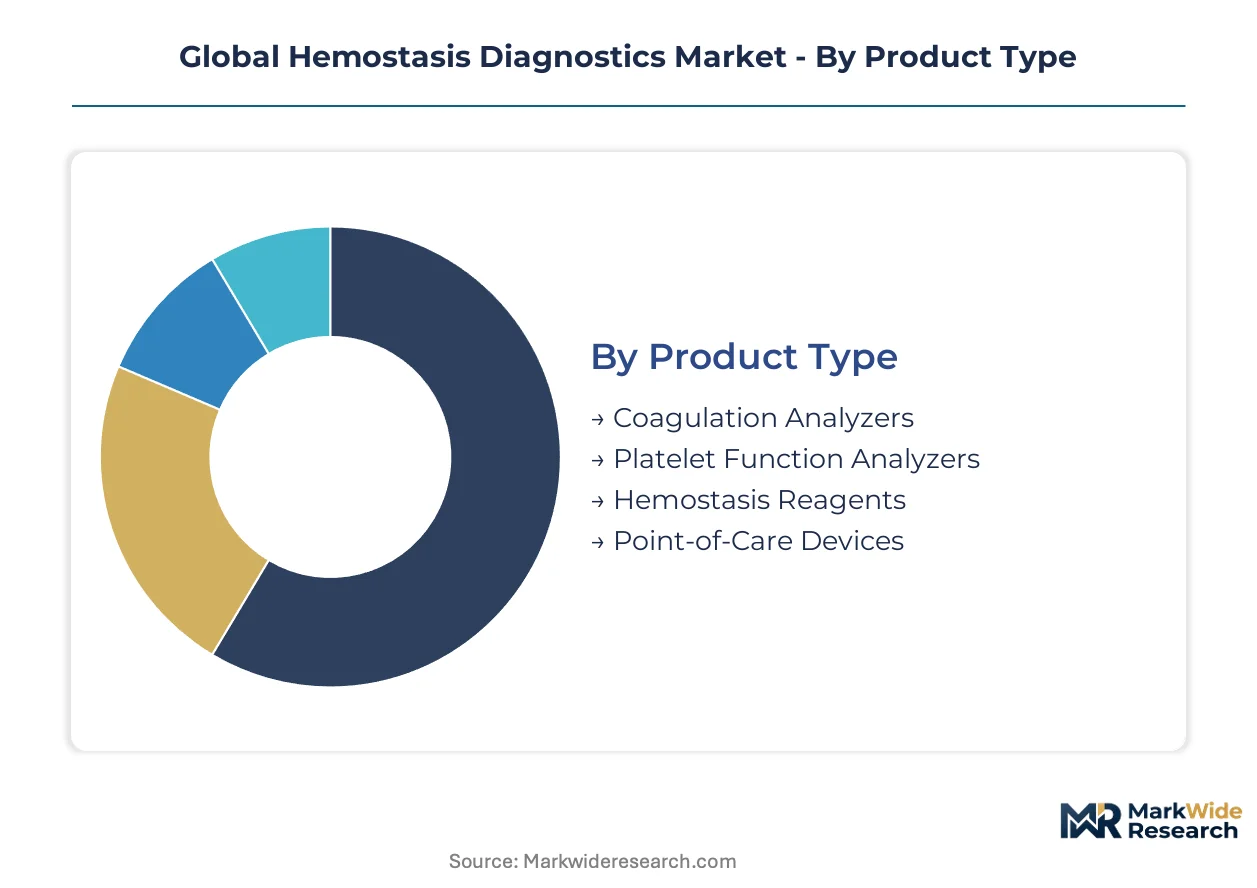
The hemostasis diagnostics market segmentation provides a granular view of product innovation, technological adoption, and end-user requirements. This detailed breakdown helps stakeholders understand where investment is concentrating and how clinical needs are driving specific solution development across different market verticals.
Product Type:
The product type segmentation reveals a market with both mature laboratory instruments and rapidly emerging decentralized testing solutions.
- Coagulation Analyzers:These sophisticated instruments automate the measurement of clotting times and factor activities, providing high-throughput testing capabilities for central diagnostic laboratories. Demand for these systems remains robust in established healthcare infrastructures across Europe and North America, driven by the need for comprehensive coagulation panels.
- Point-of-Care Devices:Compact, portable devices designed for rapid hemostasis testing outside traditional laboratory settings, typically utilizing microfluidic technology. Adoption is accelerating in emergency departments and surgical suites globally, where immediate results directly influence critical patient management decisions.
- Hemostasis Reagents:These consumables, including thromboplastin and activated partial thromboplastin time (aPTT) reagents, are essential for conducting various coagulation assays on both automated analyzers and manual methods.
- Platelet Function Analyzers:Specialized instruments assess platelet aggregation and adhesion, providing critical insights for diagnosing platelet disorders and monitoring antiplatelet therapies.
Coagulation Analyzers retains volume leadership; Point-of-Care Devices holds the steepest expansion curve.
Technology:
Technology differentiation in hemostasis diagnostics directly correlates with the precision and speed required for various clinical applications.
- Optical:This technology measures changes in light transmission or absorption as a clot forms, offering a non-invasive method for detecting coagulation endpoints. Optical systems are widely integrated into automated coagulation analyzers, particularly in diagnostic laboratories in Germany and Japan, for their reliability and precision.
- Electromechanical:Utilizing mechanical detection of clot formation, such as a steel ball moving within a plasma sample, this technology provides robust and reliable results. Electromechanical methods are a staple in many hospital laboratories worldwide, favored for their resilience in diverse sample conditions and consistent performance.
- Chromogenic:These assays use synthetic substrates that release a colored product upon cleavage by specific coagulation factors, allowing for quantitative measurement of enzyme activity.
- Immunoturbidimetric:This method detects antigen-antibody reactions by measuring changes in turbidity, commonly used for quantifying specific proteins like D-dimer or fibrinogen.
- Fluorescence:Employing fluorescent dyes to detect enzymatic activity or molecular interactions, this technology offers high sensitivity for specialized hemostasis assays.
- Electrochemical:This technology measures electrical signals generated during enzymatic reactions, providing rapid and precise results, especially in miniaturized point-of-care devices.
Optical methods see significant adoption for routine coagulation assays, while electrochemical approaches offer rapid results in point-of-care settings.
Application:
Understanding application segments allows providers to tailor diagnostic solutions to specific patient needs and clinical workflows.
- Anticoagulant Therapy Monitoring:This application involves regular testing of patients on anticoagulant medications, such as warfarin or direct oral anticoagulants, to ensure therapeutic efficacy and prevent complications. Demand is particularly high in countries with aging populations, like Italy and France, due to the prevalence of cardiovascular conditions requiring long-term therapy.
- Bleeding Disorder Diagnosis:This segment focuses on identifying and characterizing inherited or acquired conditions that impair normal blood clotting, such as hemophilia or von Willebrand disease. Specialized diagnostic laboratories in the United States and Canada rely on comprehensive hemostasis panels for accurate diagnosis and patient management.
- Thrombosis Monitoring:This application involves assessing a patient's risk of developing blood clots or monitoring the effectiveness of antithrombotic therapies.
- Surgery Screening:Pre-operative hemostasis testing evaluates a patient's clotting ability before surgical procedures, minimizing the risk of excessive bleeding or thrombotic events during and after surgery.
Anticoagulant Therapy Monitoring drives consistent demand across primary care, whereas Surgery Screening is experiencing growth due to increasing elective procedures.
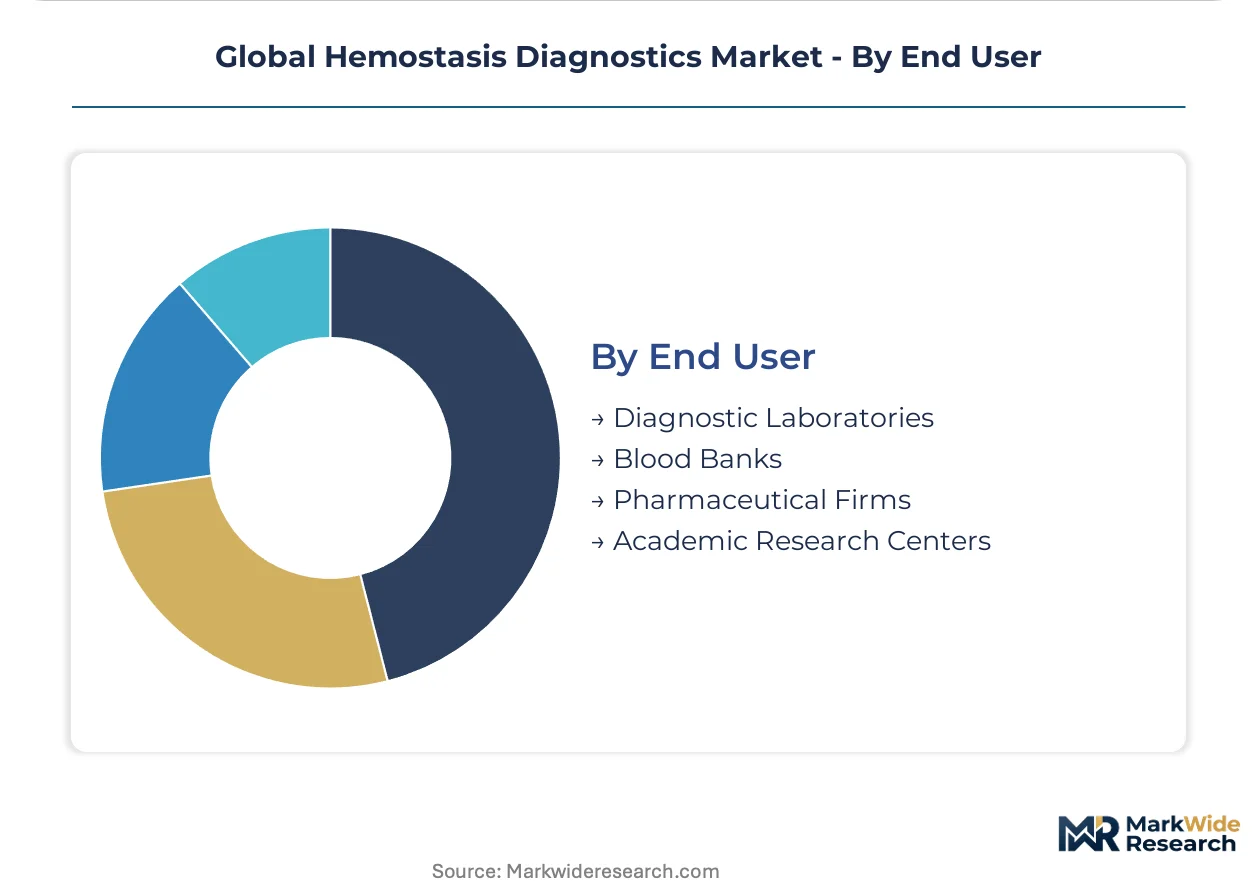
End User:
The end-user landscape reflects varying operational scales and budget considerations for hemostasis testing.
- Diagnostic Laboratories:These centralized facilities perform a high volume of hemostasis tests, utilizing automated coagulation analyzers and a broad range of reagents for routine and specialized assays. Significant investments in laboratory modernization, particularly in China and India, are expanding the capacity and demand within this segment.
- Pharmaceutical Firms:These companies utilize hemostasis diagnostics primarily for drug discovery, development, and clinical trials, evaluating the effects of new compounds on the coagulation cascade. Research and development activities, especially in the United States and Switzerland, drive demand for highly specialized and precise testing platforms.
- Blood Banks:These facilities conduct hemostasis testing to screen donors for clotting abnormalities and to ensure the quality and safety of blood products for transfusion.
- Academic Research Centers:These institutions engage in fundamental and translational research related to hemostasis and thrombosis, requiring advanced diagnostic tools for scientific investigations.
Diagnostic Laboratories remain the primary volume driver for automated systems, while Pharmaceutical Firms represent a niche but high-value segment for specialized assays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expansion of domestic diagnostic manufacturing capacity influences competitive positioning across the hemostasis diagnostics market. This market sees varied demand patterns and regulatory landscapes across key global geographies, influencing product development and market access strategies for manufacturers. Different national healthcare priorities and infrastructure levels shape regional growth trajectories.
China
China's substantial government investment in hospital infrastructure directly drives demand for coagulation analyzers and reagents. The NMPA's stringent market access requirements influence product design and development timelines for diagnostic devices. Major diagnostic manufacturing hubs in the Yangtze River Delta are expanding capacity for hemostasis products.
United States
The United States experiences consistent demand from a growing patient population on long-term anticoagulant therapies. The U.S. FDA's expedited clearance pathways for point-of-care devices are accelerating market entry for innovative solutions. Research institutions in Greater Boston actively drive biomarker expansion in hemostasis diagnostics.
Germany
Germany maintains robust demand for sophisticated coagulation analyzers within its established healthcare infrastructure and diagnostic laboratories. The EU MDR mandates extensive clinical evidence and post-market surveillance for all devices seeking a CE mark. Major medical technology clusters in Bavaria focus on R&D for optical hemostasis systems.
Japan
Japan's aging population necessitates frequent hemostasis monitoring, sustaining demand for routine coagulation assays and advanced diagnostic tools. The PMDA ensures stringent performance validation for market access of diagnostic devices. Industrial clusters around Kanto, including Tokyo, are centers for optical technology integration in hemostasis diagnostics.
Italy
Italy presents significant demand for anticoagulant therapy monitoring due to a high prevalence of cardiovascular conditions among its aging population. Compliance with the EU MDR requires manufacturers to update technical files and clinical data for market presence. Medical device companies in Lombardy are actively developing integrated solutions for hospital laboratories.
Global Hemostasis Diagnostics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the hemostasis diagnostics market. This market exhibits a tiered structure, with a few large entities offering comprehensive solutions alongside numerous specialized reagent and device manufacturers. R&D-focused innovators drive technological advancements, while integrated solution providers aim for broader hospital laboratory penetration. Companies pursue strategic partnerships and geographic expansion to solidify market positions.
Specialists in thrombosis and hemostasis reagents, Diagnostica Stago, exemplify a focused market strategy. Siemens Healthineers, a German-based company, represents a major platform integrator leveraging extensive R&D in automation for coagulation analyzers. Werfen, a Spanish-headquartered entity, occupies a position as a provider of integrated solutions for hospital laboratories. These companies, through their distinct approaches, collectively address diverse clinical needs across various healthcare settings.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Sysmex Corporation |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Diagnostica Stago |
| Werfen |
| Nihon Kohden Corporation |
| Others |
Cost & Logistics Intelligence
Major diagnostic manufacturing hubs in China's Yangtze River Delta, expanding capacity for hemostasis products, exert significant influence over global pricing for certain reagent categories. This concentration of production capability shapes competitive dynamics for market participants.
Pricing Analysis
The European Union's MDR dictates the pricing tier structure for hemostasis diagnostic devices entering European markets, requiring significant investment in compliance. Pricing stratifies across premium, standard, and economy tiers, driven by instrument sophistication, certification level, and bundled service agreements. Cost compression is intensifying for routine assays due to healthcare provider consolidation and demand for managed service contracts. Smaller clinics and laboratories, facing high capital costs, represent the most price-sensitive buyer segment, while pharmaceutical firms prioritize specialized assay precision over cost for R&D.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often support the procurement of complex hemostasis diagnostic systems for hospital laboratories. Geographic supply concentration centers on China for manufacturing capacity, Germany for advanced R&D, and Japan for optical technology components, creating dependencies on specific technology hubs. The supply chain relies on specialized reagents, microfluidic cartridges, and precision optical sensors. Regulatory restrictions from the NMPA and EU MDR present a structural risk, influencing component sourcing and market access, while distribution runs through direct sales teams and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemostasis diagnostics market reflects a significant shift in buyer power, driven by consolidation among healthcare providers seeking standardized testing and cost controls. This dynamic influences strategic responses across all market participants.
For Market Incumbents: Insulate core coagulation analyzer revenue streams by deepening R&D in automation and offering comprehensive managed service contracts. This counters the threat of rapid point-of-care device adoption and consolidates long-term customer relationships. Invest in data interoperability solutions to seamlessly integrate central lab results with electronic health records. Reinforce specialization in high-value reagents to maintain distinct competitive advantages.
For New Entrants and Emerging Players: Pursue white-space opportunities in point-of-care hemostasis devices, particularly those with microfluidic technology for rapid results in emergency settings. Target the growing demand for remote anticoagulant therapy monitoring by integrating devices with telehealth platforms. Focus on ease-of-use and digital connectivity as primary go-to-market angles. Capitalize on expedited regulatory pathways for innovative point-of-care solutions.
For Investors and Strategic Acquirers: Long-term, this sits as an essential healthcare infrastructure play because of the non-discretionary nature of hemostasis diagnostics and recurring reagent demand. Identify acquisition targets among specialized reagent manufacturers or innovative point-of-care device developers with strong intellectual property in microfluidics. A critical signal to watch is the sustained acceleration of point-of-care device adoption in surgical and emergency settings, indicating a fundamental shift in testing paradigms.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Automation R&D | Siemens Healthineers leverages R&D to maintain a technological edge in coagulation analyzers. |
| Develop Integrated Point-of-Care Platforms | These platforms meet demand from emergency departments and surgical suites for rapid hemostasis testing. |
| Expand Hemostasis Reagent Specialization | Diagnostica Stago sustains its market presence through deep specialization in thrombosis and hemostasis reagents. |
| Pursue Telehealth Integration for POC Devices | This creates a new service model for remote monitoring of patients on anticoagulant therapy. |
| Strengthen Compliance with Evolving Regulations | Adhering to EU MDR and NMPA requirements demands significant resource investment from manufacturers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase, complementing extensive secondary validation. Interviews included diagnostic laboratory managers, hospital purchasing officers, pharmaceutical R&D leads, and clinicians. Secondary data sources comprised regulatory filings from the U.S. FDA, EU MDR guidance, China NMPA publications, and industry reports. This approach ensured robust bottom-up and top-down triangulation of market data.
Forecast models were calibrated using a multi-variate regression analysis, projecting market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and geographic region. Compound annual growth rates were derived from historical trends and anticipated shifts. Key industry-specific inputs included the patient population on anticoagulant therapy and new hospital construction investments.
Sensitivities concentrate around shifts in regulatory frameworks and the pace of healthcare infrastructure expansion. Forecasts reflect assumptions regarding technological adoption and skilled personnel availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Microdialysis Market