
 In-Vitro Diagnostics (IVD) Packaging Market | 2026-2036
In-Vitro Diagnostics (IVD) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Diagnostics (IVD) Packaging Market Foresight
Point-of-care testing networks is redrawing procurement priorities across the IVD packaging value chain. Amcor plc leverages its multi-layer film expertise to supply barrier pouches for lateral-flow and molecular diagnostic kits. Greiner Holding AG anchors European vial and tube production through automated injection-blow molding platforms serving high-throughput laboratories. Thermo Fisher Scientific Incorporated extends its integrated diagnostics ecosystem into proprietary container formats, competing on specification tightness rather than commodity volume.
In-vitro diagnostics packaging encompasses primary and secondary containment systems engineered to maintain sterility, prevent moisture ingress, and preserve reagent stability across temperature ranges from refrigerated to frozen storage. These packages typically employ cyclic olefin polymers, borosilicate glass, or aluminum-laminate composites with measured oxygen transmission rates below specified thresholds to safeguard assay integrity during shelf life and transport. Pouches and vials lead volume consumption, with pouches capturing growth from point-of-care and home-testing expansion where unit-dose flexibility matters, while glass vials retain premium positioning for lyophilized and light-sensitive reagents where inert contact surfaces command margin premiums. Plastic dominates material tonnage through cost-scalable injection and thermoforming processes, though composite structures are gaining specification share in cold-chain molecular diagnostics where thermal insulation and mechanical protection must coexist.
FDA quality system regulations and EU MDR requirements for IVD device constituents are elevating extractables-leachables documentation and biocompatibility testing burdens on packaging suppliers. ISO 13485 certification has become a baseline market-access credential, with notified bodies scrutinizing supply chain continuity plans for single-source polymer grades. Stakeholders must monitor how EPA and ECHA restrictions on per- and polyfluoroalkyl substances reshape barrier-coating options for plastic primary containers, as fluoropolymer alternatives redraw material qualification timelines and qualification costs across the supplier base.
Market Dynamics
Automated testing lines in clinical laboratories are compressing turnaround-time requirements and forcing packaging suppliers to synchronize container formats with robotic handling systems. This integration imperative is restructuring procurement relationships around specification tightness rather than unit cost.
Growth Catalysts
- EU MDR traceability mandates:Sterilization validation protocols now require batch-level polymer documentation, pulling investment into track-and-trace infrastructure across German and French supply bases.
- Point-of-care network expansion:Decentralized testing sites in India and Brazil are generating pull for unit-dose pouch formats that accommodate temperature excursions during last-mile distribution.
- Cyclic olefin polymer adoption:High-barrier COC vials are displacing borosilicate glass in molecular diagnostics where breakage risk and weight reduction justify material conversion costs.
Market Restraints
- Fluoropolymer coating restrictions:EPA and ECHA limitations on PFAS barrier treatments are forcing reformulation of oxygen-barrier films, extending qualification timelines by 18-24 months.
- Specialty polymer concentration:Single-source dependence on Japanese and German resin grades for optical clarity creates vulnerability to force-majeure disruptions.
- Glass-to-plastic substitution ceiling:Lyophilized reagents and light-sensitive assays retain glass mandates due to extractables-leachables thresholds that COC and COP cannot yet satisfy.
Strategic Opportunities
- Home-testing kit standardization:Unregulated direct-to-consumer channels in Southeast Asia present white-space for pre-validated pouch formats that bridge clinical and consumer use cases.
- Cold-chain molecular diagnostics:Composite insulated shippers combining vacuum panels with phase-change materials are capturing specification share in PCR sample transport.
- ISO 13485 certification arbitrage:Notified body capacity constraints in Southern Europe create first-mover advantage for suppliers pre-certifying against 2026 MDR transition deadlines.
Industry Challenges
- Extractables-leachables analytical capacity:ISO 10993 biocompatibility documentation requires mass spectrometry expertise that contract labs in Eastern Europe cannot yet scale.
- Legacy molding asset retrofit:Converting injection-blow platforms from PET to COC processing demands screw-and-barrel modifications that compress margin at sub-10 million unit volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Diagnostics (IVD) Packaging Market |
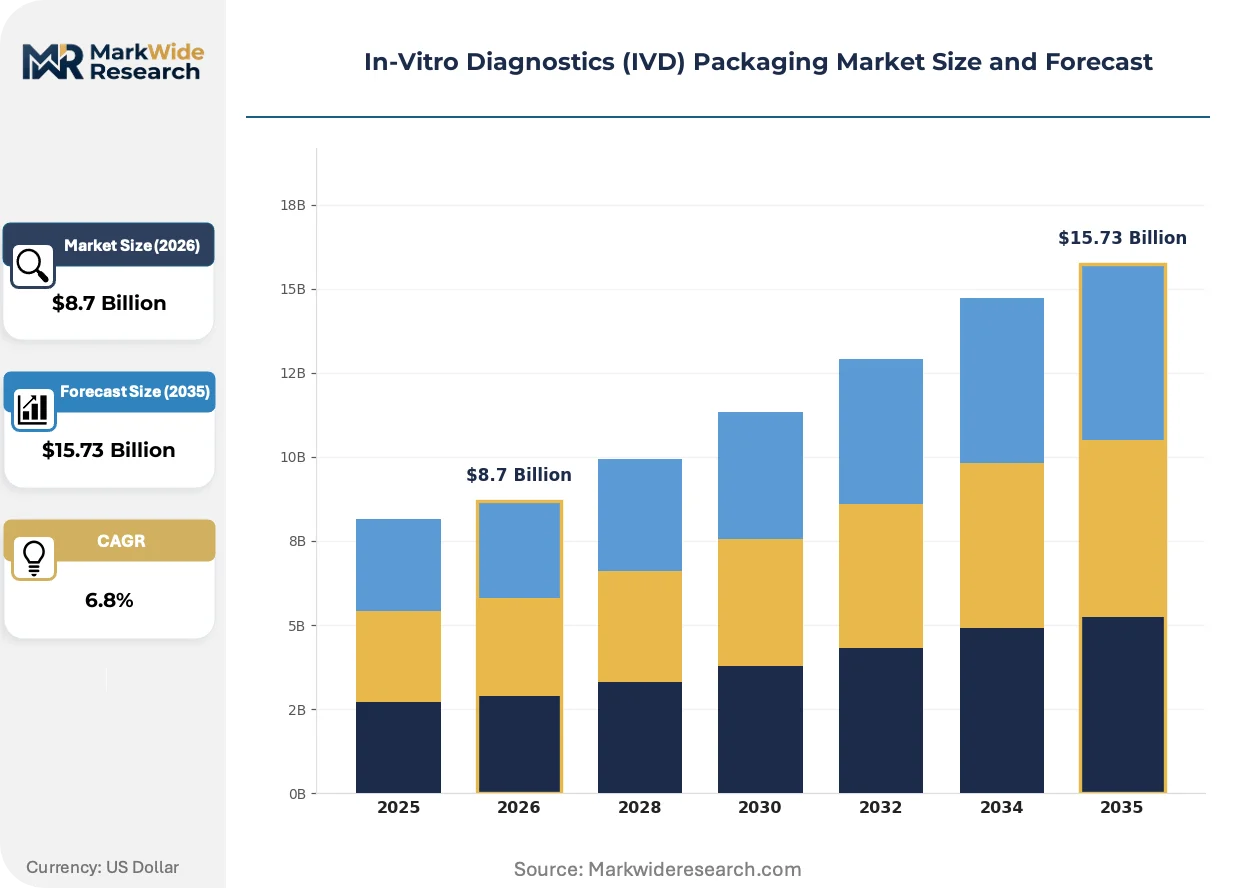
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Pouches, Bottles, Vials, Ampoules Material: Plastic, Glass, Aluminum, Composite End User: Hospitals, Laboratories, Clinics, Home Care Distribution Channel: Direct Sales, Online, Retail, Wholesalers |
| Companies Covered | Corning Incorporated, Greiner Holding AG, Amcor plc, SGD Pharma, Stevanato Group, AptarGroup Incorporated, DWK Life Sciences, COMAR, Thermo Fisher Scientific Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Diagnostics (IVD) Packaging Market Shifts & Advancements
Barrier engineering and regulatory compliance documentation are converging to redefine supplier selection criteria. Packaging specifications now embed sterilization validation data as a standard deliverable rather than a custom add-on.
Multi-layer aluminum-laminate pouches with embedded desiccant layers are miniaturizing oxygen transmission specifications below 0.01 cc/m²/day for molecular diagnostic kits. High-throughput laboratories in Germany and the Netherlands are specifying these formats for automated decapping workflows. The technology is miniaturizing the acceptable shelf-life variance window from ±15% to ±5%, compressing supplier quality tolerance bands.
REACH restrictions on per- and polyfluoroalkyl substances are forcing coating suppliers to qualify silicon oxide and aluminum oxide vapor-deposited alternatives. Barrier performance degradation of 20-30% versus legacy fluoropolymer treatments is pushing redesign toward thicker base films or secondary nitrogen flushing. Cold-chain IVD shippers for PCR reagents are absorbing the highest compliance burden, with Nordic and Benelux distributors advancing specification requirements fastest.
Centralized laboratory networks are consolidating procurement decisions through diagnostic platform OEMs rather than independent purchasing. Thermo Fisher and Roche are unbundling container specifications from instrument supply agreements, creating direct supplier relationships previously mediated by distributors. This disintermediation is most advanced in German and Swiss laboratory networks, where platform standardization rates exceed 80%.
In-Vitro Diagnostics (IVD) Packaging Market Segmentation
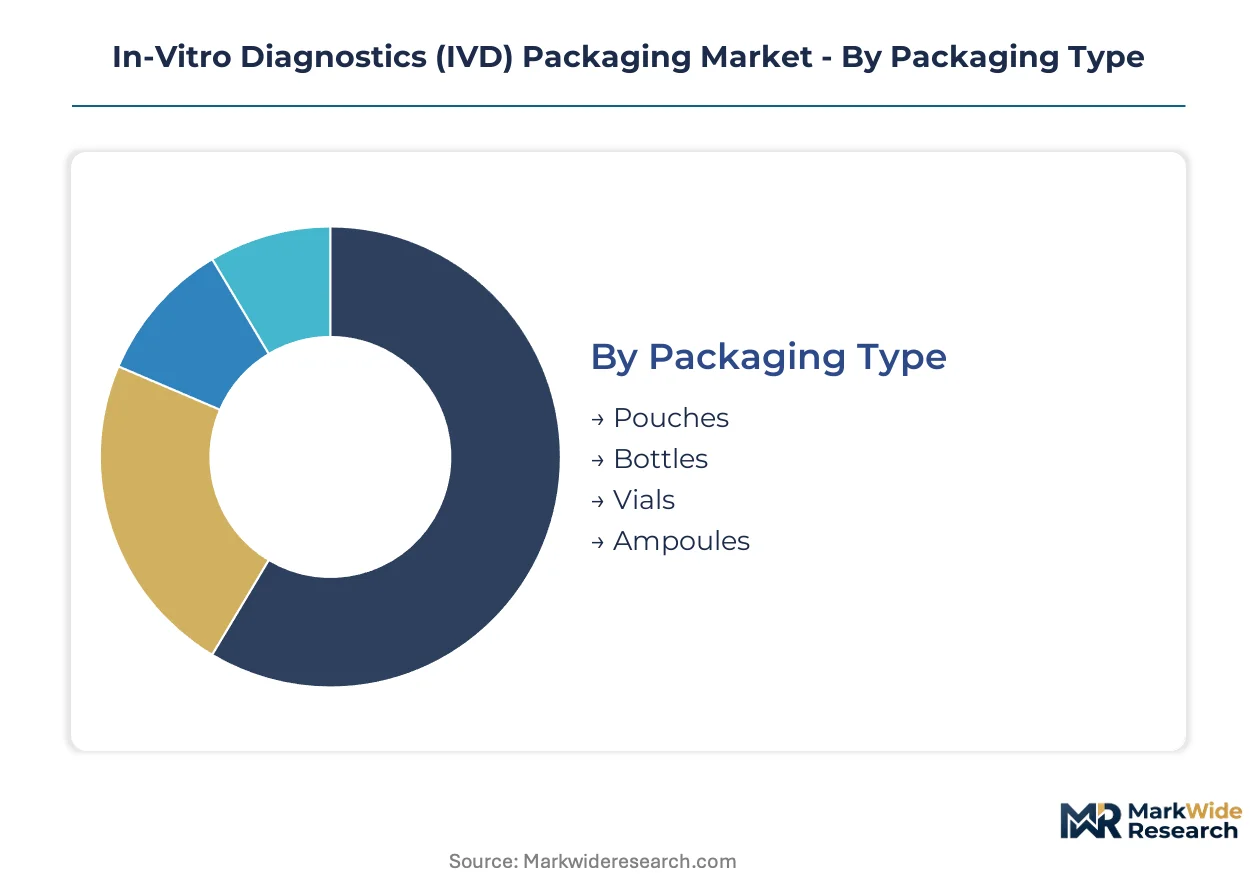
IVD packaging specifications diverge sharply across testing environments, from automated clinical lines demanding robotic handling compatibility to home-testing kits prioritizing unit-dose convenience. Material selection and format geometry must simultaneously satisfy barrier performance, regulatory documentation burdens, and total cost-to-serve economics.
Packaging Type:
Margin pools concentrate in formats serving molecular diagnostics and lyophilized reagents where barrier precision commands specification premiums.
- Pouches:Multi-layer aluminum-laminate structures with embedded desiccant layers achieve oxygen transmission below 0.01 cc/m²/day. Point-of-care networks in India and Brazil are pulling these formats for temperature-resilient last-mile distribution.
- Vials:Cyclic olefin polymer and borosilicate glass variants maintain inert contact surfaces for light-sensitive and lyophilized assays. German centralized laboratory networks specify these for automated decapping workflows on high-throughput lines.
- Bottles:Injection-blow molded containers serve bulk reagent storage with cost-scalable throughput.
- Ampoules:Single-dose glass formats retain niche positioning for emergency diagnostics and field-deployable assays.
Vials hold installed capacity. Pouches are rotating up the share rankings.
Material:
Cost tiers separate commodity tonnage from qualification-intensive specialty grades.
- Plastic:Cyclic olefin copolymers and cyclic olefin polymers displace glass where weight reduction and breakage risk mitigation justify conversion costs. Japanese and German resin grades dominate optical clarity specifications.
- Glass:Borosilicate formats retain premium positioning for extractables-leachables thresholds that thermoplastics cannot yet satisfy. Lyophilized reagent mandates in Swiss and German laboratories sustain demand.
- Aluminum:Laminate foil layers provide moisture and oxygen barriers in pouch constructions.
- Composite:Vacuum-insulated panels combined with phase-change materials serve cold-chain PCR transport requirements.
Glass commands specification premiums. Plastic dominates unit economics.
End User:
Application requirements dictate validation depth and documentation burden.
- Laboratories:Automated testing lines in Germany and the Netherlands compress turnaround-time requirements and synchronize container formats with robotic handling systems.
- Home Care:Direct-to-consumer channels in Southeast Asia generate pull for pre-validated pouch formats bridging clinical and consumer use cases.
- Hospitals:Acute-care settings prioritize rapid-result compatibility with existing diagnostic platforms.
- Clinics:Decentralized testing sites balance cost constraints against regulatory compliance thresholds.
Laboratories anchor volume concentration. Home Care is expanding most quickly.
Distribution Channel:
Customer type determines relationship structure and specification ownership.
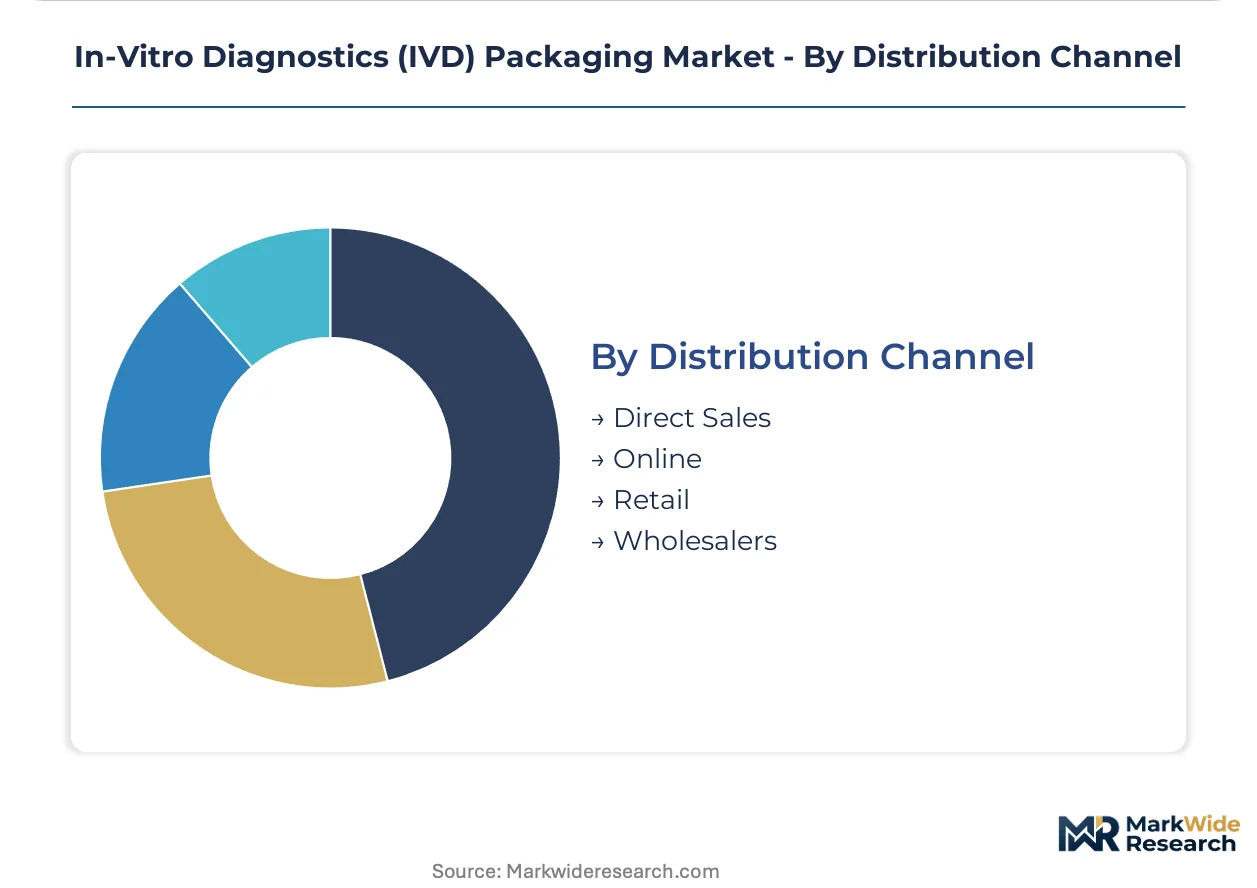
- Direct Sales:Platform OEMs including Thermo Fisher and Roche unbundle container specifications from instrument supply agreements, creating direct supplier relationships previously mediated by distributors.
- Wholesalers:Independent purchasing persists in fragmented laboratory networks where platform standardization remains incomplete.
- Online:Digital procurement channels gain traction in mid-sized clinical settings seeking transparent pricing.
- Retail:Pharmacy and consumer-facing channels serve home-testing kit distribution.
Direct Sales concentrates margin capture. Online is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centralized laboratory networks and contract manufacturing clusters concentrate procurement decisions in specific metropolitan regions. Platform OEMs unbundle container specifications from instrument agreements, reshaping supplier relationships. Regulatory divergence across jurisdictions creates compliance arbitrage opportunities for pre-certified suppliers.
Germany
Automated testing lines in centralized laboratory networks drive demand for robotic-handling-compatible vial formats. EU MDR traceability mandates require batch-level polymer documentation, elevating track-and-trace infrastructure investments. The Rhine-Main and Rhine-Ruhr clusters host diagnostic consumables contract manufacturers scaling COC vial production capacity.
United States
FDA quality system regulations tighten extractables-leachables documentation burdens for primary container suppliers. Point-of-care network expansion generates pull for unit-dose pouch formats accommodating temperature excursions. The Research Triangle and Greater Boston corridors concentrate molecular diagnostics platform developers unbundling packaging specifications.
India
Decentralized testing sites in tier-2 and tier-3 cities generate demand for temperature-resilient last-mile distribution formats. CDSCO medical device rules align with ISO 13485 certification requirements for import market access. The Mumbai-Pune and Bengaluru-Chennai industrial corridors scale pouch converting capacity for regional diagnostic kit assemblers.
Japan
PMDA pharmaceutical and medical device regulations enforce stringent biocompatibility testing protocols for primary containers. Single-source dependence on domestic resin grades for optical clarity specifications creates supply continuity planning imperatives. The Osaka-Kobe and Nagoya manufacturing belts anchor cyclic olefin polymer compounding and precision molding operations.
Brazil
ANVISA medical device registration requirements extend sterilization validation timelines for imported packaging components. Point-of-care network expansion in the Southeast and Northeast regions pulls pre-validated pouch formats for tropical distribution conditions. The São Paulo state industrial belt concentrates diagnostic reagent filling and kit assembly operations serving Mercosur markets.
In-Vitro Diagnostics (IVD) Packaging Market Competitive Landscape
Player mix skews toward diversified materials conglomerates with medical-grade polymer processing capabilities and specialized glass primary container manufacturers. Tiering separates specification-tight premium suppliers from cost-scalable commodity producers. Archetypes include integrated diagnostics ecosystem extenders, barrier film specialists, and precision molding contract manufacturers. Dominant competitive moves encompass direct specification relationships with platform OEMs and MDR pre-certification capacity investments.
Among diversified packaging conglomerates, Amcor plc and Greiner Holding AG occupy positions spanning barrier film and precision molding domains. Thermo Fisher Scientific Incorporated exemplifies the integrated diagnostics ecosystem archetype, extending proprietary container formats alongside instrument platforms. These three entities represent distinct competitive vectors: materials science depth, automated manufacturing scale, and vertical specification control through platform integration.
| Leading Market Players |
|---|
| Corning Incorporated |
| Greiner Holding AG |
| Amcor plc |
| SGD Pharma |
| Stevanato Group |
| AptarGroup Incorporated |
| DWK Life Sciences |
| COMAR |
| Thermo Fisher Scientific Incorporated |
| Others |
Supply & Pricing Matrix
EU MDR batch-level polymer documentation gates both supplier qualification and price differentiation simultaneously, forcing packaging converters to absorb track-and-trace infrastructure costs that stratify tier access. ISO 13485 certification creates a two-speed market where pre-certified German and Swiss suppliers command specification premiums while uncertified competitors face margin compression from extended qualification timelines.
Pricing Analysis
Glass-to-plastic conversion pricing gaps separate legacy borosilicate vial premiums from emerging cyclic olefin polymer alternatives, with next-generation vapor-deposited barrier coatings occupying a transitional price band. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with automated laboratory procurement in Germany and the Netherlands showing lowest price sensitivity while Indian point-of-care distributors drive cost compression in pouch formats. Pricing pressure stems from fluoropolymer coating restrictions forcing reformulation investments, with home-testing kit assemblers in Southeast Asia representing the most price-sensitive buyer segment.
Supply Chain Analysis
Specialty resin concentration in Japan and Germany creates chokepoint vulnerability for optical-grade cyclic olefin polymer specifications. Raw material dependencies on aluminum-laminate foil substrates, desiccant inserts, and phase-change materials for cold-chain applications compound geographic concentration risk. Single-source vulnerability on Japanese resin grades for molecular diagnostic clarity requirements intersects with tariff exposure on Chinese aluminum foil conversions. Distribution runs through diagnostic platform OEMs unbundling specifications in German and Swiss networks, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care network expansion and EU MDR traceability mandates are disrupting procurement relationships faster than incumbent capacity can adapt, creating asymmetric opportunity for pre-certified specialists.
For Market Incumbents: Compound barrier film expertise into integrated cold-chain solutions for PCR transport, defending against composite shipper specialists entering from adjacent pharmaceutical logistics. Deepen backward integration into cyclic olefin polymer compounding to secure resin continuity against Japanese supply disruptions. Prioritize ISO 13485 certification arbitrage in Southern Europe where notified body capacity constraints delay competitor market access. For New Entrants and Emerging Players: Differentiate on temperature-resilient pouch formats for India's tier-2 and tier-3 decentralized testing sites, where last-mile distribution failures create specification gaps that clinical-grade suppliers ignore. Target Southeast Asia's unregulated direct-to-consumer channels with pre-validated formats bridging clinical and home use cases. Pursue contract manufacturing relationships with regional diagnostic kit assemblers in the Mumbai-Pune corridor as the primary go-to-market angle. For Investors and Strategic Acquirers: EU MDR 2026 transition deadlines reshape the acquisition landscape toward pre-certified precision molding assets with existing notified body relationships. Five-to-ten year viability favors suppliers with captive polymer qualification capabilities and platform OEM direct relationships rather than distributor-dependent volume players. Monitor EPA and ECHA PFAS restriction implementation velocity as the signal indicating which barrier-coating technology investments will strand versus appreciate.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Pre-Certification Investment | Notified body capacity constraints in Southern Europe create first-mover qualification advantages for compliant suppliers. |
| Backward Integration into COC Compounding | Captive resin supply secures optical clarity specifications against Japanese force-majeure disruptions. |
| Cold-Chain Composite Shipper Development | Vacuum panel and phase-change material integration captures PCR transport specification share from pharmaceutical logistics entrants. |
| Platform OEM Direct Relationship | Thermo Fisher and Roche unbundling container specifications from instrument agreements disintermediates traditional distribution. |
| Fluoropolymer-Free Barrier Qualification | Silicon oxide and aluminum oxide vapor-deposited alternatives future-proof coating portfolios against EPA and ECHA restrictions. |
Research Methodology
The analysis maps primary container formats, barrier film constructions, and secondary packaging systems, each validated through procurement managers at centralized laboratory networks, diagnostic platform OEM supply chain directors, and contract manufacturing executives. Primary interviews with packaging converters in the Rhine-Main and Rhine-Ruhr clusters, CDSCO regulatory consultants in Mumbai-Pune, and GPO contracts managers in German hospital systems combined with secondary validation from FDA 510(k) filings, EUDAMED device registrations, ISO 13485 certification databases, and customs trade data for cyclic olefin polymer imports. Bottom-up unit volume modeling and top-down market sizing triangulated through cross-referencing end-user procurement patterns with supplier capacity disclosures.
Consistency checks validated volume and value outputs against external benchmarks including diagnostic instrument installation base growth, point-of-care network expansion rates, and laboratory automation capital expenditure trends across the analysis window. Segmentation dimensions modeled encompass packaging type, material grade tier, end-use environment, and distribution channel structure. CAGRs derived from regression analysis of historical procurement data against instrument platform deployment curves, with molecular diagnostics cold-chain requirements and home-testing kit standardization serving as industry-specific demand drivers.
Material uncertainties — regulatory restriction timelines on PFAS barrier treatments, force-majeure disruptions in Japanese resin supply, and platform OEM unbundling velocity — sit outside the modeled envelope. Forecasts reflect assumptions about MDR implementation consistency and laboratory automation adoption rates that regulatory enforcement variability or capital expenditure pauses could revise. Practitioners should keep alternative scenarios live as EPA and ECHA restriction implementation evolves and point-of-care network penetration in tropical markets accelerates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
D-Dimer Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
Creatinine Test Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Elisa Tests Market