
 Hemostasis Testing Systems Market | 2026-2036
Hemostasis Testing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hemostasis Testing Systems Market Foresight
Reagent subscription and preventive maintenance contracts is rebalancing how capital equipment vendors monetize installed bases in coagulation diagnostics. Siemens Healthineers leverages its broad assay menu to lock in multi-year consumable commitments across integrated delivery networks. Sysmex Corporation anchors its position in Asia through dedicated hematology-hemostasis workflow bundles. Werfen specializes in niche coagulation parameters that command premium pricing in academic medical centers.
Hemostasis testing systems comprise analytical instruments, reagents, and quality-control materials that measure clotting cascade function through optical, mechanical, or electrochemical detection principles, typically reporting parameters such as prothrombin time, activated partial thromboplastin time, and fibrinogen concentration within minutes to guide transfusion and anticoagulant therapy decisions. Coagulation analyzers occupy the largest installed base due to their essential role in pre-surgical screening protocols across hospitals and reference laboratories. Microfluidics represents the fastest-expanding technology segment as manufacturers miniaturize multi-parameter panels onto disposable cartridges for near-patient deployment. Platelet function testers command concentrated margins in cardiac surgery and antiplatelet therapy monitoring despite smaller unit volumes.
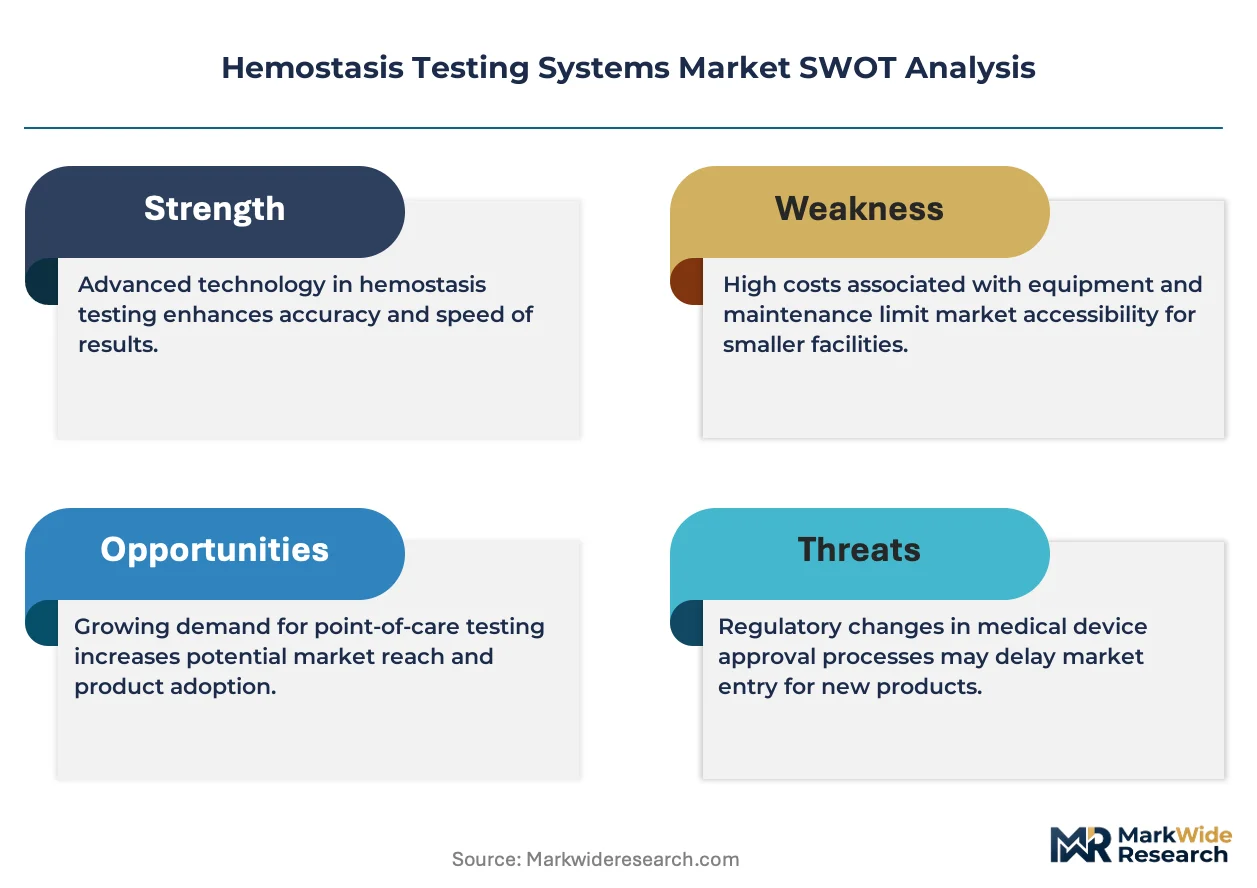
FDA premarket notification requirements under 21 CFR Part 864 govern analytical performance claims for coagulation devices sold in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked hemostasis systems entering European markets. ISO 15189 accreditation drives laboratory purchasing criteria for standardized quality management in diagnostic testing workflows. Stakeholders must monitor how decentralized testing expansion reshapes service revenue models and regulatory compliance burdens across distributed care sites.
Market Dynamics
Microfluidics is compressing test turnaround from hours to minutes across perioperative workflows, forcing incumbents to defend installed bases through consumable lock-in strategies rather than capital sales alone.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:Stricter clinical evidence standards for CE-marked systems are filtering out marginal competitors and consolidating procurement toward validated high-throughput platforms in German hospital networks.
- Cardiac surgery volumes:Rising procedural complexity in valve replacement and ECMO support is expanding routine platelet function monitoring into standard preoperative protocols.
- Optical detection methods:Multi-wavelength turbidimetry is displacing mechanical clot detection in mid-tier analyzers, lowering maintenance burdens and extending service intervals.
Market Restraints
- Reagent supply concentration:Lyophilized coagulation controls and calibrators depend on a narrow base of European specialty chemical suppliers, exposing laboratories to batch-to-batch variability and extended lead times.
- ISO 15189 accreditation costs:Documented traceability requirements for every assay lot number impose recurring audit burdens that disproportionately strain smaller independent laboratories.
- Point-of-care substitution ceiling:Microfluidic cartridge costs per test remain three to five times higher than central laboratory reagents, limiting expansion beyond surgical suites into routine screening.
Strategic Opportunities
- Decentralized testing in India:Tier-two and tier-three cities lack centralized coagulation infrastructure, creating whitespace for cartridge-based platforms in district hospitals managing snakebite envenomation and postpartum hemorrhage.
- Hematology-hemostasis workflow convergence:Integrated pre-analytical modules that combine complete blood count with coagulation screening are capturing premium positioning in Japanese reference laboratories.
- FDA breakthrough device designation pathway:Novel hemostasis biomarkers for trauma-induced coagulopathy can accelerate market access through prioritized review timelines and earlier payer engagement.
Industry Challenges
- Specialized field service engineering:Combined optical-mechanical analyzers require technicians trained across fluidics, photometry, and quality control software, creating recruitment bottlenecks in secondary markets.
- Laboratory information system interoperability:Middleware integration between point-of-care devices and hospital electronic health records demands custom HL7 mapping that delays deployment by four to eight months.
- Anticoagulant therapy complexity:Direct oral anticoagulant reversal protocols require rapid turnaround that strains staffing models in overnight and weekend coverage periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemostasis Testing Systems Market |
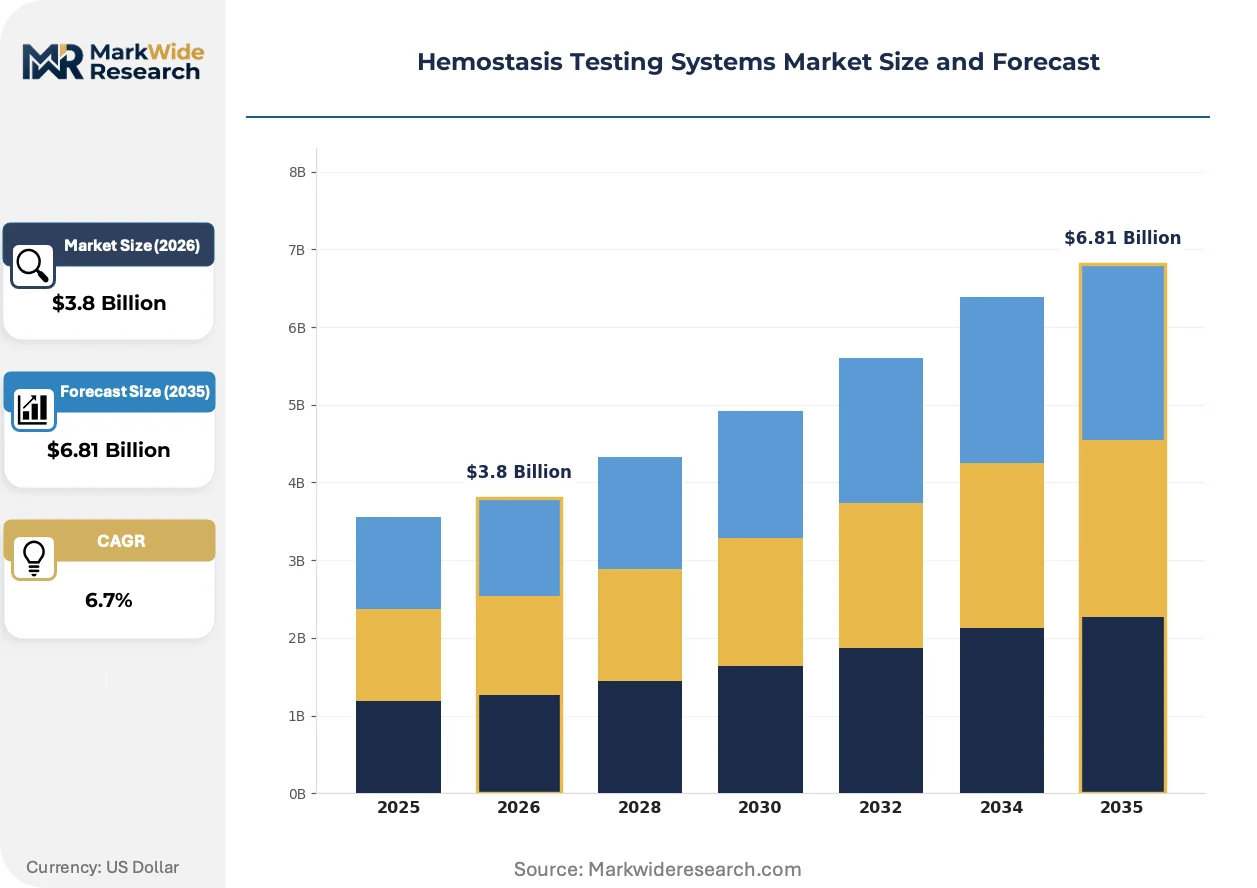
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulation Analyzers, Platelet Function Testers, Prothrombin Time Testers, Thrombin Inhibitors Technology: Optical Detection, Mechanical Detection, Electromagnetic Detection, Microfluidics End User: Hospitals, Diagnostic Laboratories, Blood Banks, Homecare Settings Application: Surgical Procedures, Anticoagulation Monitoring, Trauma Care, Disease Management |
| Companies Covered | Siemens Healthineers, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Sysmex Corporation, Danaher Corporation, Werfen, Thermo Fisher Scientific, Diagnostica Stago, Helena Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemostasis Testing Systems Market Shifts & Advancements
Detection methodology, regulatory evidence requirements, and procurement contracting are simultaneously evolving, compressing product lifecycles and reshaping how vendors capture value across the testing continuum.
Electrochemical impedance sensing is electrifying clot formation monitoring by eliminating optical interference from lipemic or icteric samples. Academic medical centers in the United States are piloting these sensors in trauma bays where sample quality is unpredictable. The technology is electrifying competitive positioning by enabling valid results on specimens that would fail optical methods, expanding addressable test volume.
REACH substance restrictions on phthalate plasticizers are forcing reagent manufacturers to reformulate cartridge housings and tubing sets ahead of 2025 authorization deadlines. The industrial consequence is accelerated qualification timelines for alternative polymer suppliers and redundant inventory buffers during transition periods. European IVD manufacturers are responding by consolidating molding contracts with suppliers holding pre-validated bio-compatible resin portfolios.
Subscription-based reagent contracts are displacing transactional purchasing in United States integrated delivery networks, bundling analyzer placement with minimum annual consumable commitments. The channel being disrupted is independent distributor resale; direct manufacturer contracting is capturing procurement relationships. This shift is most visible in Florida and Texas health systems where laboratory consolidation has concentrated buying power across fifteen to twenty hospital campuses.
Hemostasis Testing Systems Market Segmentation
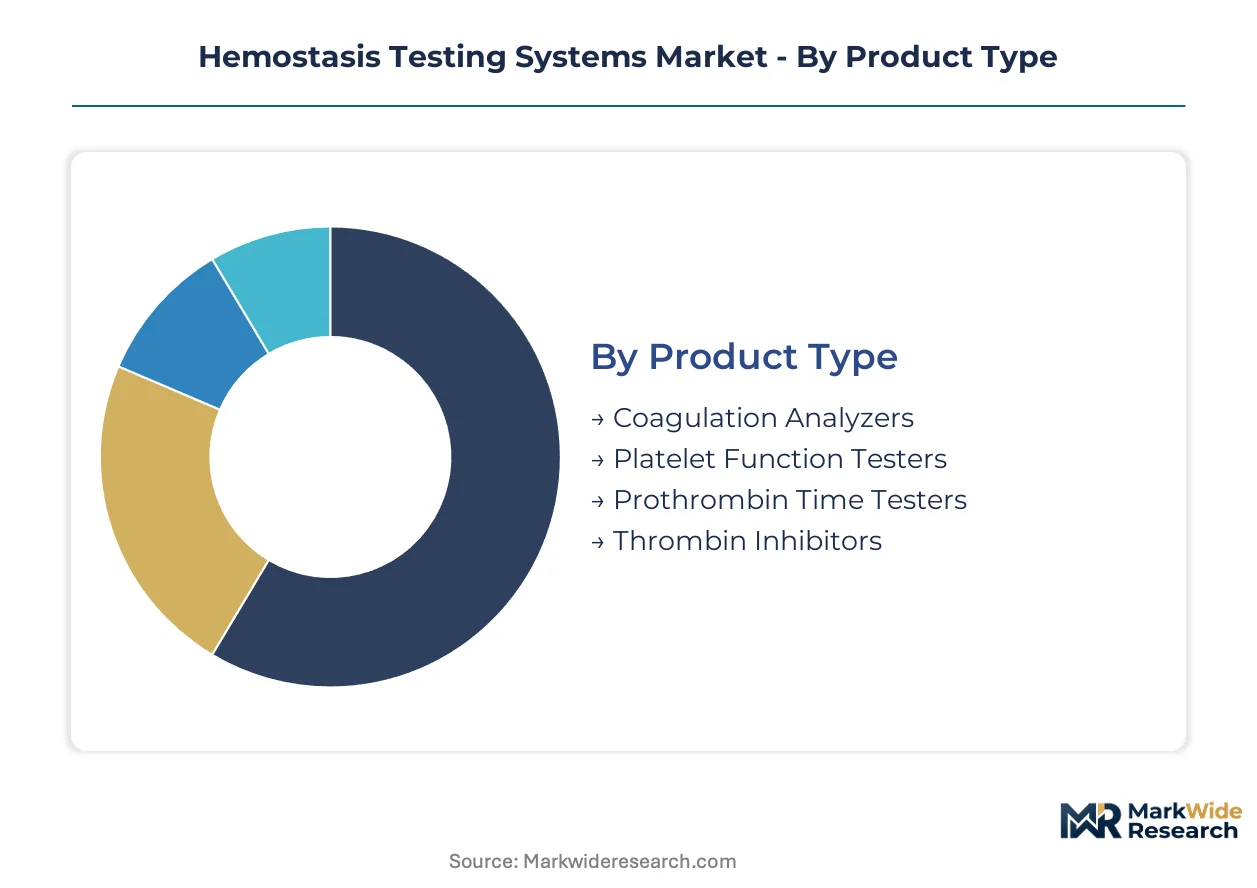
Segmentation in hemostasis testing systems reveals how clinical workflow requirements pull technology development in divergent directions. Standalone high-throughput platforms serve centralized laboratories while embedded cartridge systems penetrate surgical suites and emergency departments.
Product Type:
Integration depth varies sharply across product categories, with some instruments designed for dedicated laboratory benches and others engineered for seamless embedding within broader diagnostic workflows.
- Coagulation Analyzers:Multi-parameter instruments process PT, aPTT, fibrinogen, and D-dimer through automated sample handling with throughput ranging from 60 to 400 tests hourly. Hospital laboratories in the United States prioritize these for pre-surgical screening protocols where batch efficiency determines staffing economics.
- Platelet Function Testers:Specialized devices measure aggregation responses to agonists like ADP, collagen, and arachidonic acid using impedance or optical methods. Cardiac surgery centers in Germany embed these into ECMO and valve replacement protocols where antiplatelet therapy optimization reduces bleeding complications.
- Prothrombin Time Testers:Compact single-parameter devices dominate anticoagulation clinic workflows with simplified operation for warfarin monitoring.
- Thrombin Inhibitors:Assay-specific analyzers support direct oral anticoagulant reversal protocols in trauma settings.
Coagulation analyzers lead volumes today; platelet function testers are gaining share fastest.
Technology:
Detection methodology selection hinges on sample quality tolerance, maintenance infrastructure, and the clinical consequence of analytical error in specific use environments.
- Optical Detection:Turbidimetric and chromogenic methods dominate installed bases through multi-wavelength systems that discriminate clot formation from sample interference. Mid-tier laboratories in Japan favor these for reduced mechanical complexity and extended service intervals.
- Microfluidics:Cartridge-based platforms miniaturize reagent reservoirs, reaction chambers, and detection optics onto disposable substrates for near-patient deployment. District hospitals in India adopt these where centralized laboratory infrastructure remains underdeveloped and snakebite envenomation demands rapid coagulation assessment.
- Mechanical Detection:Steel ball or cup oscillation methods persist in reference laboratories seeking traceability to classical coagulation principles.
- Electromagnetic Detection:Impedance-based sensing enables valid results on lipemic or icteric specimens that compromise optical methods.
Optical detection anchors the largest installed base; microfluidics shows the steepest expansion trajectory.
End User:
Site-of-care economics and regulatory compliance burdens segment demand across institutional settings with divergent capital availability and technical staffing.
- Hospitals:Integrated delivery networks consolidate purchasing across fifteen to twenty campuses, negotiating multi-year reagent subscriptions that bundle analyzer placement with minimum annual consumable commitments. Surgical volume concentration in Florida and Texas health systems drives point-of-care platform expansion into perioperative suites.
- Diagnostic Laboratories:Centralized reference facilities in Germany process high sample volumes through automated pre-analytical modules combining complete blood count with coagulation screening. ISO 15189 accreditation requirements filter procurement toward validated platforms with documented traceability.
- Blood Banks:Transfusion services require rapid turnaround for donor screening and component therapy preparation.
- Homecare Settings:Patient self-monitoring of anticoagulation remains constrained by reimbursement limitations and quality assurance challenges.
Hospital laboratories command the dominant revenue share; diagnostic laboratories are expanding fastest in emerging markets.
Application:
Clinical urgency and therapeutic decision windows determine whether testing occurs in centralized facilities or at the point of care.
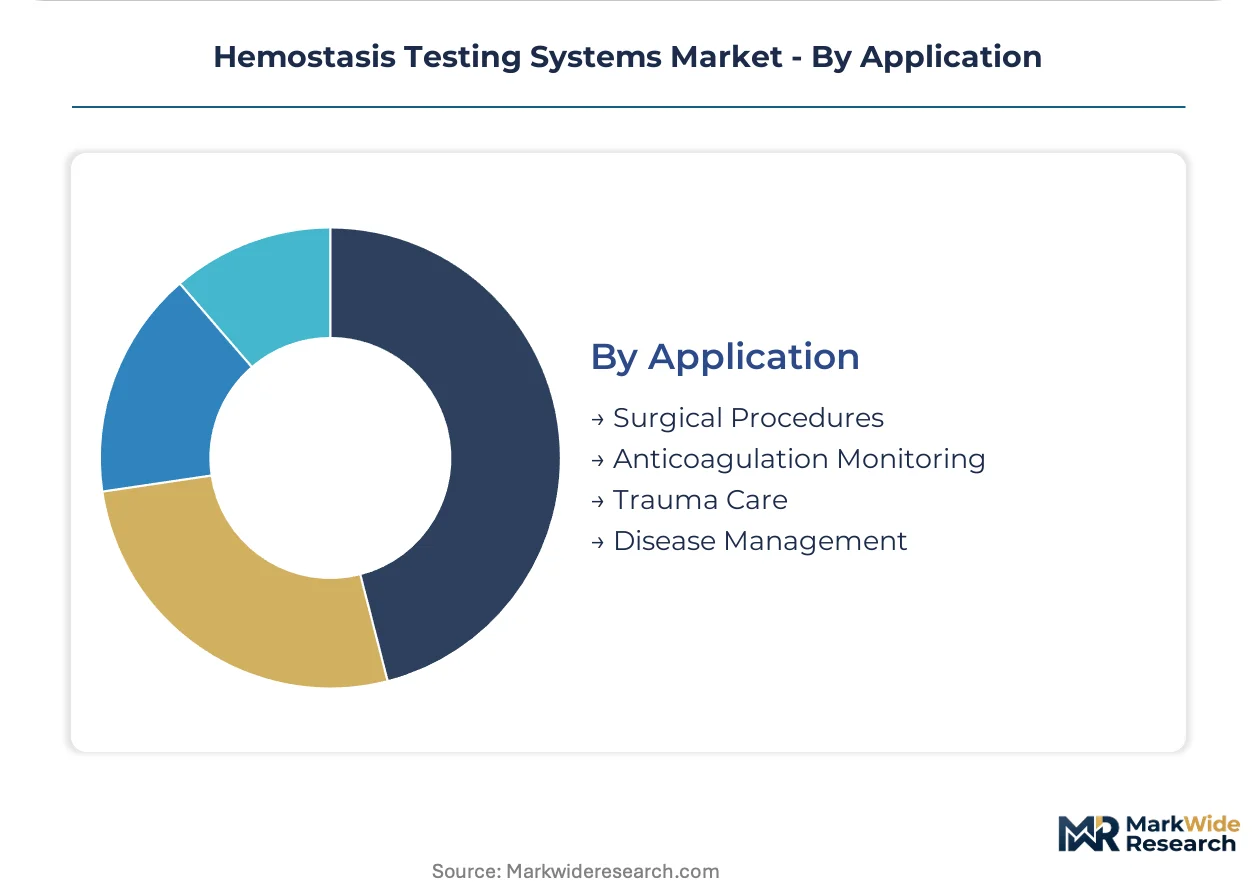
- Surgical Procedures:Preoperative screening and intraoperative transfusion guidance demand turnaround times incompatible with central laboratory logistics. United States hospital networks deploy cartridge-based platforms directly into operating suites to reduce surgical delays and blood product utilization.
- Trauma Care:Massive hemorrhage protocols require immediate coagulation assessment for targeted component therapy. Academic medical centers pilot electrochemical impedance sensors in trauma bays where sample quality unpredictability would invalidate optical methods.
- Anticoagulation Monitoring:Routine warfarin and direct oral anticoagulant surveillance sustains high test frequency in outpatient settings.
- Disease Management:Chronic conditions including liver dysfunction and disseminated intravascular coagulation require longitudinal monitoring.
Surgical applications generate the highest test volume; trauma care is climbing the fastest as emergency department infrastructure modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in procurement architecture, with German hospital networks favoring centralized laboratory consolidation while United States integrated delivery networks push point-of-care decentralization into surgical suites.
United States
FDA premarket notification pathways under 21 CFR Part 864 govern analytical performance claims for coagulation devices entering commercial distribution. Hospital networks in Florida and Texas concentrate surgical volume across fifteen to twenty campuses, negotiating multi-year reagent subscriptions that bundle analyzer placement with minimum annual consumable commitments. Academic medical centers in Boston and Baltimore pilot electrochemical impedance sensors in trauma bays where sample quality unpredictability would invalidate optical methods.
Germany
The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked hemostasis systems, filtering procurement toward validated high-throughput platforms. Centralized laboratory networks in North Rhine-Westphalia and Bavaria drive replacement cycles for automated coagulation systems with documented traceability under ISO 15189 accreditation. REACH substance restrictions on phthalate plasticizers are forcing reagent manufacturers to reformulate cartridge housings ahead of authorization deadlines.
Japan
METI industrial policy supports domestic manufacturing of diagnostic instruments through standardized quality management frameworks. Reference laboratories in Tokyo and Osaka capture premium positioning through integrated pre-analytical modules combining complete blood count with coagulation screening. Mid-tier laboratories in Nagoya favor multi-wavelength turbidimetry systems for reduced mechanical complexity and extended service intervals.
India
The CDSCO regulates in vitro diagnostic device import and manufacture under the Medical Devices Rules, with district hospitals in tier-two and tier-three cities lacking centralized coagulation infrastructure. Snakebite envenomation and postpartum hemorrhage management in Maharashtra and Karnataka create whitespace for cartridge-based platforms. State government health programs in Tamil Nadu and Telangana are expanding point-of-care deployment into district hospital networks.
China
NMPA registration requirements for Class II and Class III in vitro diagnostic devices mandate clinical trials conducted at domestic sites for initial approval. Yangtze River Delta hospital clusters in Shanghai and Jiangsu province are modernizing perioperative infrastructure to support rising surgical procedural volume. Domestic manufacturers in the Pearl River Delta are developing microfluidic cartridge platforms to substitute imported central laboratory analyzers.
Hemostasis Testing Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system vendors capturing recurring consumable revenue while component suppliers serve aftermarket refurbishment demand. The vendor landscape organizes into three tiers: multinational diagnostics conglomerates with broad assay menus, mid-scale specialists in niche coagulation parameters, and regional equipment fabricators serving price-sensitive procurement. Consolidation pressure is intensifying as reagent subscription contracts lock integrated delivery networks into multi-year commitments. Technology licensing agreements and strategic partnerships dominate competitive moves as manufacturers seek to fill portfolio gaps without organic development timelines.
Among diversified diagnostics conglomerates, Siemens Healthineers and Sysmex Corporation exemplify contrasting geographic anchoring strategies, with one leveraging European installed base density and the other capturing Asian workflow integration through hematology-hemostasis bundles. Werfen occupies a specialist position commanding premium positioning in academic medical centers. These three entities represent the archetype spectrum from broad-menu platform consolidation to parameter-specific clinical differentiation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Sysmex Corporation |
| Danaher Corporation |
| Werfen |
| Thermo Fisher Scientific |
| Diagnostica Stago |
| Helena Laboratories |
| Others |
Supply & Pricing Matrix
Lyophilized coagulation controls and calibrators from European specialty chemical suppliers cascade through three pricing tiers before reaching hospital laboratories and reference facilities. Procurement managers in German hospital networks negotiate multi-year reagent subscriptions that bundle analyzer placement with minimum annual consumable commitments, compressing margins for independent distributors.
Pricing Analysis
Capacity additions in China are reshaping price floors for microfluidic cartridge substrates, pressuring legacy optical analyzer margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated trauma biomarkers from ISO 15189-accredited reference platforms and unvalidated point-of-care devices. Cost compression in mid-tier analyzers is intensifying because multi-wavelength turbidimetry lowers maintenance burdens and extends service intervals. Independent laboratories in tier-two Indian cities exhibit highest price sensitivity, while academic medical centers in Boston and Baltimore demonstrate lowest sensitivity due to premium positioning for niche coagulation parameters.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for reagent cold-chain logistics. Manufacturing concentration in Germany, the United States, and China draws from lyophilized protein controls, optical-grade polymers, and electrochemical sensor substrates. Single-source vulnerability concentrates in European specialty chemical suppliers for coagulation calibrators, exposing laboratories to batch-to-batch variability. Distribution runs through direct manufacturer contracting with integrated delivery networks, displacing independent distributor resale in Florida and Texas health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemostasis testing systems market compounds steadily through recurring reagent subscription revenue that locks integrated delivery networks into multi-year consumable commitments.
For Market Incumbents: Anticipate microfluidic substitution threats by deepening consumable lock-in through hematology-hemostasis workflow bundles. Sysmex Corporation's Asian strategy demonstrates how integrated pre-analytical modules capture premium positioning. Siemens Healthineers leverages broad assay menus to defend against emerging cartridge-based platforms. Prioritize backward integration into lyophilized control manufacturing to reduce European supplier concentration risk. For New Entrants and Emerging Players: Begin with district hospital networks in Maharashtra and Karnataka where snakebite envenomation and postpartum hemorrhage create urgent demand for rapid coagulation assessment. CDSCO regulatory pathways for Class II IVD devices remain less congested than FDA 510(k) queues. Partner with state government health programs in Tamil Nadu and Telangana to secure anchor procurement contracts before scaling to tier-one cities. For Investors and Strategic Acquirers: Consolidation pressure builds where reagent subscription contracts have concentrated integrated delivery network purchasing across fifteen to twenty hospital campuses. Target specialists in niche coagulation parameters commanding premium pricing in academic medical centers. Electrochemical impedance sensing adoption in trauma bays signals inflection toward sample-quality-tolerant detection methodologies.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Subscription Contracting | Direct manufacturer relationships with IDNs displace independent distributor channels in Florida and Texas. |
| Hematology-Hemostasis Bundle Development | Integrated pre-analytical modules combining CBC with coagulation screening capture Japanese reference laboratory premiums. |
| Microfluidic Cartridge Scale-Up | Domestic manufacturing in the Pearl River Delta substitutes imported central laboratory analyzers for Chinese hospital procurement. |
| Electrochemical Sensor Pilot Programs | Academic medical centers in Boston and Baltimore validate impedance-based detection for lipemic trauma specimens. |
| REACH-Compliant Polymer Qualification | European IVD manufacturers consolidate molding contracts with bio-compatible resin suppliers ahead of 2025 deadlines. |
Research Methodology
Bottom-up hospital laboratory modeling reconciled against top-down reagent manufacturer tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and point-of-care coordinators informed demand-side assumptions. Secondary validation drew from FDA 510(k) filings, CDSCO Medical Devices Rules notifications, EMA IVDR technical documentation, and hospital procurement databases. Trade data for lyophilized coagulation controls and optical-grade polymers anchored supply-side calibration.
Historical trendline analysis across detection methodology segments established baseline growth patterns. Segmentation dimensions modeled include product type, technology platform, end-user setting, and application urgency. CAGRs were derived through regression analysis against surgical procedural volume trajectories and anticoagulant therapy monitoring frequency. Forecast inputs incorporated EU IVDR implementation timelines and NMPA Class III clinical trial requirements.
Several conditions sit outside the modeled scope, including pandemic-related surgical deferral patterns and abrupt reimbursement code revisions for point-of-care testing. Forecasts reflect assumptions about regulatory pathway stability and reagent supplier consolidation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Pneumonia Testing Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Diagnostic Shipper Market
Testing Services
Europe Newborn Screening Market
Testing Services
Urodynamic Testing Market
Testing Services
Global GMP Testing Service Market
Testing Services
Platelet Function Testing Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Medical Device Testing Services Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Global Anti Thrombin III Testing Market