
 Cancer Tissue Diagnostics Market | 2026-2036
Cancer Tissue Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Tissue Diagnostics Market Analysis
China is tilting toward domestic production of automated staining platforms and molecular assay systems. Roche Diagnostics leverages its vertically integrated reagent-instrument ecosystem to sustain installed-base loyalty across clinical laboratories. Danaher Corporation anchors its position through Beckman Coulter's diagnostic workflow automation and Leica Biosystems' histopathology specialization. Thermo Fisher Scientific competes by extending its ion semiconductor sequencing into solid tumor profiling applications.
Cancer tissue diagnostics encompasses the histopathological and molecular analysis of biopsy specimens to identify malignant cellular morphology, protein expression, and nucleic acid alterations guiding therapeutic selection. Immunohistochemistry staining protocols typically employ formalin-fixed paraffin-embedded sections with chromogenic or fluorescent detection of biomarkers such as PD-L1, HER2, and mismatch repair proteins. The technology dimension shows immunohistochemistry occupying the largest revenue share due to its entrenched reimbursement and pathologist familiarity, while in situ hybridization gains fastest expansion from rising demand for gene fusion and amplification detection in precision oncology. End-user concentration favors diagnostic laboratories capturing high-throughput reference testing volume, whereas pathology clinics retain margin-rich specialized consultative services.
The FDA regulates cancer tissue diagnostics as in vitro diagnostic devices under premarket approval and 510(k) pathways, with companion diagnostics requiring simultaneous drug approval coordination that shapes development timelines and commercial partnerships. The Clinical Laboratory Improvement Amendments program governs laboratory-developed test quality standards, while the Centers for Medicare and Medicaid Services reimbursement determinations directly influence test menu economics and adoption velocity. Stakeholders must monitor evolving payer evidence requirements for molecular profiling coverage as health technology assessment bodies tighten linkage between biomarker demonstration and patient outcome improvement.
Market Dynamics
The FDA's companion diagnostics framework is forcing synchronized drug-test development timelines that reshape partnership structures between pharmaceutical sponsors and diagnostic developers. Hospital laboratories are building in-house molecular pathology capabilities to capture margin from outsourced reference testing.
Growth Catalysts
- Integrated Delivery Network Consolidation:Large United States health systems are centralizing diagnostic procurement under single laboratory information management systems, creating volume concentration that favors high-throughput platform vendors.
- PD-L1 Testing Mandates:The FDA's expanding list of immuno-oncology therapies with companion diagnostic requirements is institutionalizing immunohistochemistry staining protocols in community pathology settings.
- Automated Staining Platforms:China-based manufacturers are scaling domestic production of slide processing systems, reducing capital equipment import dependency and accelerating platform refresh cycles in tier-two hospitals.
Market Restraints
- Reagent Supply Concentration:Chromogenic detection chemistry for immunohistochemistry relies on a narrow base of European and United States specialty chemical suppliers, creating vulnerability to import logistics disruptions.
- Pathologist Workforce Constraints:The United States faces sustained shortfalls in board-certified anatomic pathologists, extending turnaround times for complex molecular profiling cases beyond clinically acceptable windows.
- Formaldehyde Fixation Artifacts:Standard formalin-fixed paraffin-embedded processing degrades nucleic acid integrity, limiting RNA-based assay sensitivity and requiring costly alternative fixation protocols.
Strategic Opportunities
- Digital Pathology Integration:Whole-slide imaging combined with artificial intelligence algorithms is creating remote diagnostic consultation capabilities that penetrate underserved rural United States markets.
- Plasma-Based Liquid Biopsy Convergence:Circulating tumor DNA testing is collapsing the boundary between tissue and blood-based oncology diagnostics, enabling sequential monitoring applications that tissue biopsy cannot address.
- Indian Reference Laboratory Expansion:The country's national cancer grid is accrediting regional molecular pathology centers to reduce patient travel burdens for biomarker testing, opening capital equipment placement opportunities.
Industry Challenges
- Laboratory-Developed Test Validation Burden:The FDA's proposed rulemaking to regulate LDTs as medical devices is forcing academic medical centers to reassay thousands of historical clinical validity studies.
- Interoperability Friction:Proprietary data formats from competing digital pathology scanners are blocking seamless case transfer between health systems, complicating multi-site clinical trial enrollment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Tissue Diagnostics Market |
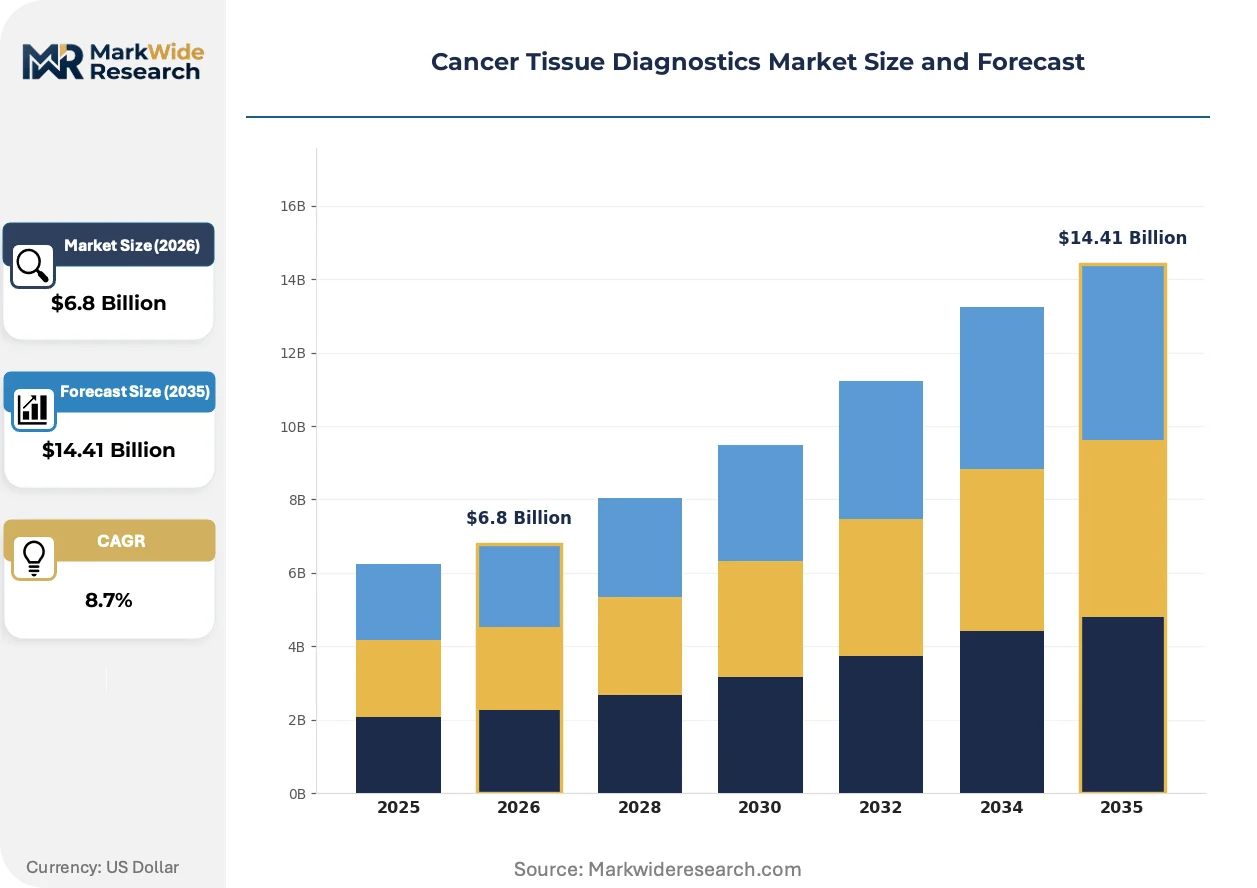
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stains, Reagents, Antibodies, Instruments Technology: Immunohistochemistry, In Situ Hybridization, Flow Cytometry, PCR End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pathology Clinics Application: Research, Clinical Diagnostics, Biomarker Discovery, Drug Development |
| Companies Covered | Roche Diagnostics, Danaher Corporation, Thermo Fisher Scientific, Abbott Laboratories, Agilent Technologies, Hologic, Bio-Rad Laboratories, bioMérieux, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Tissue Diagnostics Market Emerging Trajectories
Multiplexed spatial biology platforms are compressing the traditional sequential staining workflow into single-section analyses, fundamentally altering laboratory capital allocation and staffing models. These converging capabilities are redrawing competitive boundaries between histopathology specialists and genomics platform vendors.
Next-generation sequencing-based solid tumor profiling is collapsing the distinction between single-gene companion diagnostics and broad molecular characterization panels. Community oncology practices in the United States are adopting hybrid capture-based assays at accelerating pace, compressing reimbursement negotiations around test value demonstration. This technology shift is enabling therapy selection for rare driver mutations that immunohistochemistry cannot resolve.
The European Union's In Vitro Diagnostic Regulation is mandating notified body certification for all cancer tissue diagnostic devices previously self-certified under the IVD Directive. Manufacturers are restructuring quality management systems to meet post-market surveillance requirements, with medium-sized histopathology reagent vendors facing disproportionate compliance cost burdens. The MDR transition timeline is compressing product registration strategies for companies with limited European notified body relationships.
Hospital laboratories are unbundling after-sales service contracts from capital equipment purchases, negotiating discrete maintenance agreements with third-party field service organizations. This procurement pattern shift is disrupting the traditional reagent rental model that locked laboratories into single-vendor ecosystems. The United States academic medical center segment is most visibly advancing this disaggregation, separating instrument placement decisions from long-term consumable supply commitments.
Cancer Tissue Diagnostics Market Segmentation
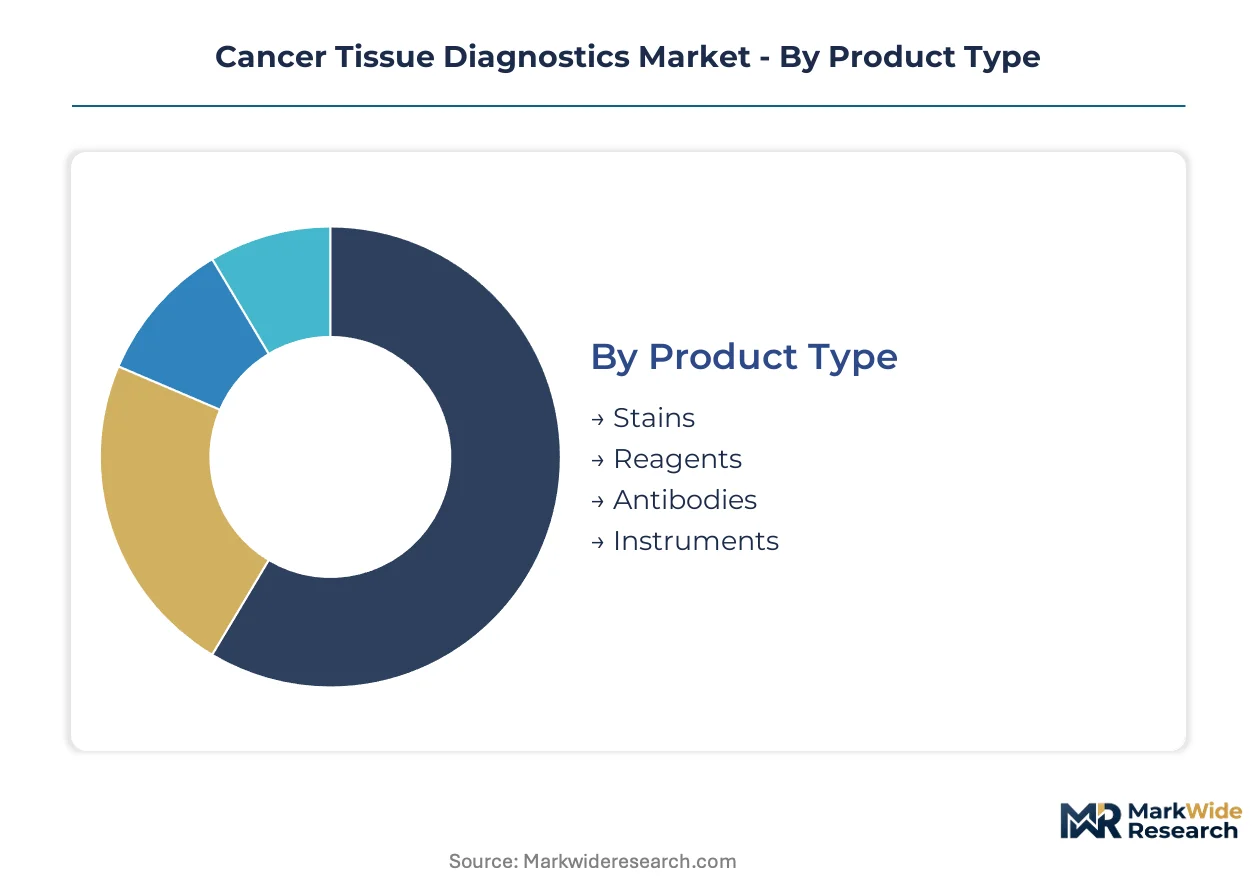
Cancer tissue diagnostics fragments across four intersecting dimensions that determine procurement patterns, margin structures, and technology adoption curves. Product type and technology choices lock laboratories into multi-year reagent-instrument ecosystems, while end-user concentration and application specificity dictate workflow automation requirements.
Product Type:
Use-case spectrum spans routine histopathological staining to precision molecular detection, with capital intensity and consumable pull-through varying dramatically across the four categories.
- Instruments:Automated staining platforms and digital slide scanners anchor laboratory infrastructure, with five-to-seven-year depreciation cycles locking sites into vendor ecosystems. Demand concentrates in United States academic medical centers pursuing high-throughput immunohistochemistry standardization, pressured by PD-L1 companion diagnostic volume mandates.
- Antibodies:Primary and secondary antibody reagents constitute the highest-margin recurring revenue stream, with clone specificity determining diagnostic accuracy for biomarkers like HER2 and mismatch repair proteins. Diagnostic laboratories in Germany and France prioritize CE-IVD certified antibody panels to satisfy EUDAMED traceability requirements.
- Stains:Hematoxylin and eosin formulations remain the volume foundation for morphological assessment, with premium specialty stains commanding price premiums for connective tissue and microorganism identification.
- Reagents:Chromogenic detection chemistry and buffer systems complete assay workflows, with supply concentration in European specialty chemical manufacturers creating procurement vulnerability.
Established volume favors Stains; emerging adoption favors Instruments.
Technology:
Cost tier stratification separates entrenched chromogenic methods from capital-intensive molecular platforms, with reimbursement codes reinforcing incumbent positions.
- Immunohistochemistry:Chromogenic protein detection on formalin-fixed paraffin-embedded sections dominates clinical practice, entrenched by pathologist familiarity and established CPT reimbursement. Hospital laboratories in the United States deploy automated platforms to manage PD-L1, ER/PR, and mismatch repair protein testing volume.
- In Situ Hybridization:Fluorescent and chromogenic nucleic acid detection resolves gene amplification and chromosomal rearrangements beyond protein expression limits. Diagnostic laboratories in Japan adopt dual-color break-apart probes for ALK and ROS1 fusion detection in non-small cell lung carcinoma.
- PCR:Targeted nucleic acid amplification enables actionable mutation detection with faster turnaround than sequencing alternatives.
- Flow Cytometry:Suspension-based immunophenotyping retains dominance for hematologic malignancy classification.
Reimbursement stability anchors Immunohistochemistry; biomarker complexity is driving fastest expansion in In Situ Hybridization.
End User:
Customer type determines capital availability, test menu breadth, and regulatory compliance burden across four institutional categories.
- Diagnostic Laboratories:High-throughput reference facilities capture centralized testing from health system networks, with automated platforms processing thousands of immunohistochemistry slides daily. Integrated delivery networks in the United States consolidate send-out volume under single laboratory information management systems.
- Hospitals:In-house molecular pathology capabilities are expanding to retain margin from outsourced oncology testing, with academic medical centers leading NGS-based solid tumor profiling adoption. China's tier-two hospitals accelerate automated staining platform procurement from domestic manufacturers.
- Pathology Clinics:Specialized consultative practices retain margin-rich complex case interpretation.
- Research Institutes:Exploratory biomarker discovery drives demand for multiplexed spatial biology platforms.
Volume concentration favors Diagnostic Laboratories; margin retention favors Pathology Clinics.
Application:
Maturity gradient separates regulated clinical diagnostics from exploratory research phases, with evidence requirements determining commercial timelines.
- Clinical Diagnostics:FDA-cleared and CE-marked assays for therapy selection constitute the revenue core, with companion diagnostic co-development agreements shaping pharmaceutical partnerships. United States community oncology practices adopt hybrid capture-based NGS panels for rare driver mutation identification.
- Biomarker Discovery:Exploratory tissue profiling generates intellectual property for diagnostic-therapeutic pairing, with pharmaceutical sponsors funding retrospective clinical trial analyses. European academic consortia leverage multiplexed spatial transcriptomics for tumor microenvironment characterization.
- Drug Development:Clinical trial enrollment stratification and pharmacodynamic monitoring create contracted testing demand.
- Research:Mechanistic studies and assay development support pipeline expansion.
Regulated revenue anchors Clinical Diagnostics; pipeline optionality expands fastest in Biomarker Discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and major cargo airports at Memphis and Louisville enable rapid specimen transport from community hospitals to centralized reference laboratories, underwriting the country's dominance in high-throughput diagnostic processing.
United States
Integrated delivery networks in Texas and the Southeast are consolidating oncology testing under single laboratory information management systems. The FDA's companion diagnostics framework mandates synchronized drug-test approvals for PD-L1 and HER2 assays. The Boston-Cambridge corridor anchors pharmaceutical-diagnostic co-development partnerships, with academic medical centers driving next-generation sequencing adoption.
China
Domestic manufacturers of automated staining platforms are scaling production to serve tier-two hospitals in Sichuan and Shandong provinces. The NMPA's streamlined Class III device review pathways are accelerating molecular assay registrations. The Yangtze River Delta cluster around Shanghai concentrates reagent manufacturing and instrument assembly operations.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are expanding in-house molecular pathology capabilities to retain margin from outsourced testing. The EU's Medical Device Regulation is mandating notified body certification for immunohistochemistry devices previously self-certified. The Heidelberg-Mannheim corridor hosts specialized antibody production facilities serving European diagnostic laboratories.
Japan
Reference laboratories in Tokyo and Osaka are adopting dual-color break-apart fluorescence in situ hybridization probes for ALK and ROS1 fusion detection. The PMDA's orphan drug framework accelerates companion diagnostic approvals for rare oncology indications. The Kobe biomedical cluster concentrates digital pathology scanner development and artificial intelligence algorithm training.
India
The national cancer grid is accrediting regional molecular pathology centers in Maharashtra and Tamil Nadu to reduce patient travel burdens for biomarker testing. The CDSCO's streamlined import licensing for diagnostic instruments is accelerating capital equipment placement in tier-two cities. The Delhi-NCR corridor anchors reference laboratory networks serving northern oncology centers.
Cancer Tissue Diagnostics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and antibody supply. The vendor base stratifies into three layers: multinational conglomerates with vertically integrated reagent-instrument ecosystems, mid-cap histopathology specialists with regional manufacturing footprints, and niche antibody clone developers serving research and clinical markets. Consolidation pressure concentrates in the middle tier as quality management system costs rise under European regulatory transitions. Strategic moves center on unbundling after-sales service contracts from capital placements and negotiating discrete maintenance agreements with third-party field service organizations.
Among Swiss and American conglomerates, Roche Diagnostics and Danaher Corporation exemplify the integrated platform archetype through captive reagent supply and automated workflow ecosystems. Thermo Fisher Scientific occupies a position spanning sequencing instrumentation and molecular assay development, representing the genomics convergence vector. These three anchors illustrate how scale-driven players are compressing the traditional distinction between histopathology specialists and molecular platform vendors.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Agilent Technologies |
| Hologic |
| Bio-Rad Laboratories |
| bioMérieux |
| QIAGEN |
| Others |
Supply Flow & Price Mechanics
The Memphis-Louisville air freight corridor anchors rapid specimen transport for United States reference laboratories, with its cost dynamics amplifying pricing power for concentrated chromogenic reagent suppliers while forcing tiered service differentiation among platform vendors competing for integrated delivery network contracts.
Pricing Analysis
Volume-discount tiering separates premium automated staining platforms with bundled service contracts from standard capital purchases and economy-tier manual workflow alternatives. Price differentiation hinges on FDA companion diagnostic certification status and after-sales service bundling depth. Cost compression in the economy tier is intensifying as Chinese domestic manufacturers expand automated platform production. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, while tier-two community hospitals face acute budget constraints.
Supply Chain Analysis
Chromogenic detection chemistry feedstock production concentrates in Germany, Switzerland, and the United States, with European specialty chemical manufacturers supplying hematoxylin formulations and DAB substrates. Antibody clone development rests on hybridoma facilities in the United States and Japan, while paraffin embedding materials draw from petroleum refining byproduct streams. Single-source vulnerability persists for rare earth elements in fluorescent detection systems. Distribution runs through regional diagnostic distributors holding cold-chain logistics capabilities for temperature-sensitive reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cancer tissue diagnostics market is approaching a platform-economics inflection as proprietary digital pathology data formats fragment interoperability, creating ecosystem lock-in risks that reshape vendor consolidation incentives and buyer procurement strategies.
For Market Incumbents: Insulate installed-base loyalty by deepening captive antibody supply agreements and preemptively unbundling service contracts before third-party field service organizations capture maintenance revenue. The FDA's proposed laboratory-developed test regulation poses immediate compliance cost threats to academic medical center customers, creating urgency for validation support services that cement long-term reagent commitments.
For New Entrants and Emerging Players: Build out spatial biology and multiplexed staining capabilities to capture research institute demand outpacing incumbent platform refresh cycles. India's national cancer grid accreditation program offers the most penetrable geographic entry point, with regional molecular pathology centers in Maharashtra and Tamil Nadu seeking capital equipment partnerships that bypass established vendor ecosystems.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap histopathology specialists facing disproportionate European Medical Device Regulation compliance burdens relative to their quality management system scale. Long-term viability favors platform-agnostic reagent developers with CE-IVD antibody portfolios transferable across automated staining systems. Watch for plasma-based liquid biopsy convergence signals as tissue testing volume displacement indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA's synchronized approval framework mandates pharmaceutical-diagnostic alignment for PD-L1 and HER2 therapy selection. |
| Digital Pathology Platform Integration | Whole-slide imaging with AI algorithms penetrates underserved rural United States markets through remote consultation capabilities. |
| Domestic Manufacturing Scale-Up | China's NMPA streamlined pathways accelerate molecular assay registrations for tier-two hospital procurement. |
| Reagent Rental Model Disaggregation | United States academic medical centers separate instrument placement from consumable supply commitments, disrupting traditional vendor lock-in. |
| Spatial Biology Capability Acquisition | Multiplexed transcriptomics platforms compress sequential staining workflows, altering laboratory capital allocation models. |
Methodological Framework
A spread of perspectives from pathologists, hospital laboratory directors, diagnostic platform engineers, and pharmaceutical biomarker strategists converged on the working assumptions driving this analysis. Primary interviews with GPO contracts managers and biomedical procurement officers combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, and EUDAMED device registrations. Bottom-up test volume modeling and top-down market sizing triangulated across technology and end-user segments.
Demand-supply-balance framing anchored the projection framework across the analysis window, with segmentation dimensions spanning product type, technology platform, end-user institution category, and clinical versus research application. CAGRs derived from instrument placement cycles, reagent pull-through rates, and companion diagnostic approval velocity. Forecast inputs incorporated pathologist workforce supply constraints and European regulatory transition timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic platform manufacturers or liquid biopsy entrants would shift outcomes beyond modeled ranges. Cross-checking against hospital capital expenditure surveys and pharmaceutical companion diagnostic partnership announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
HIV Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
FISH Probe Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
Global Companion Animal Diagnostics Market
Diagnostics
Australia in-Vitro Diagnostics Market