
 Microdialysis Market | 2026-2036
Microdialysis Market Size, Share, and Industry Trends Forecast 2026-2036
Microdialysis Market Outlook
Buyer concentration among academic medical centers and large hospital networks is repositioning procurement dynamics toward bundled long-term supply contracts. Medtronic Plc leverages its established neurosurgical device infrastructure to sustain catheter placement volumes across major health systems. M Dialysis AB anchors European demand through specialized probe manufacturing with direct hospital partnerships. Harvard Bioscience Inc. competes in research-grade instrumentation, differentiating through customizable flow parameters for preclinical protocols.
Microdialysis employs semipermeable membrane probes typically 0.5–1.0 mm in diameter with molecular weight cutoffs ranging from 6 to 100 kDa, enabling continuous extracellular fluid sampling from living tissue for biochemical analysis. Catheters and probes command the core product demand as hospitals replace consumables on fixed schedules tied to infection control protocols. Neuroscience applications lead clinical deployment, while drug development segments in pharmaceutical laboratories represent the fastest-growing demand pool due to pharmacokinetic study expansion. High-Performance Liquid Chromatography integration with microdialysis sampling sustains premium positioning in metabolite quantification workflows.
FDA 510(k) pathways govern brain tissue monitoring device commercialization in the United States, while the EU MDR requires renewed clinical evidence for legacy probe systems sold in Europe. Japan's PMDA maintains distinct biocompatibility testing standards that extend registration timelines for foreign manufacturers. ISO 10993 biological evaluation protocols shape material selection for membrane polymers across all regulated markets. Stakeholders must monitor evolving notified body capacity in Europe and alignment between FDA breakthrough device designations and actual reimbursement coding decisions.
Market Dynamics
Academic medical centers in the United States, Germany, and Japan are consolidating procurement around bundled long-term supply contracts for neurocritical care monitoring, compressing vendor margins while locking in catheter placement volumes across major health systems.
Growth Catalysts
- FDA 510(k) Pathways:Streamlined clearance mechanisms for brain tissue monitoring devices accelerate commercialization timelines for manufacturers targeting United States hospital networks.
- Pharmacokinetic Study Expansion:Pharmaceutical laboratories in North America and Western Europe are scaling microdialysis deployment for drug development workflows.
- EU MDR Clinical Evidence Requirements:Stricter mandates for legacy probe systems are driving replacement demand as hospitals upgrade to compliant membrane technologies.
Market Restraints
- Biocompatibility Testing Costs:ISO 10993 biological evaluation protocols impose material selection constraints and extend development cycles for membrane polymer suppliers.
- Notified Body Capacity Bottlenecks:European certification backlogs delay product launches as manufacturers queue for EU MDR conformity assessments.
- High-Performance Liquid Chromatography Integration Complexity:Specialized metabolite quantification workflows require capital-intensive equipment that limits adoption in smaller hospital laboratories.
Strategic Opportunities
- Japan PMDA Registration Alignment:Foreign manufacturers can capture tertiary hospital demand by adapting membrane systems to distinct Japanese biocompatibility testing standards.
- Preclinical Protocol Customization:Research-grade instrumentation with adjustable flow parameters addresses unmet demand in pharmaceutical toxicology studies.
- Continuous Glucose Monitoring Convergence:Integration of microdialysis sampling with wearable sensor platforms opens metabolic monitoring applications beyond neuroscience.
Industry Challenges
- Specialized Probe Manufacturing Talent:European manufacturers face shortages of engineers skilled in semipermeable membrane fabrication at sub-millimeter precision scales.
- Infection Control Protocol Compliance:Fixed catheter replacement schedules tied to hospital accreditation standards strain supply chain forecasting accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microdialysis Market |
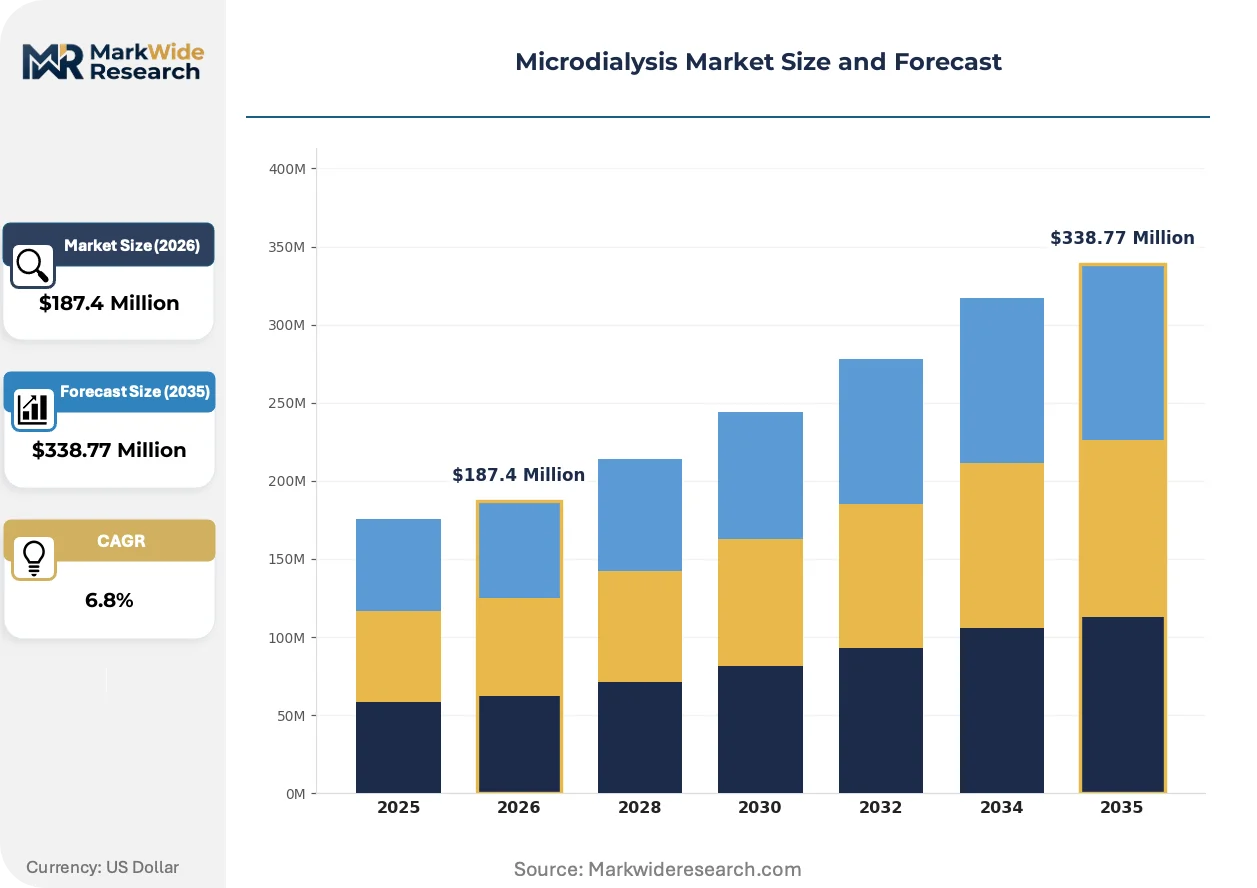
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Syringes, Pumps, Probes Application: Neuroscience, Drug Development, Clinical Diagnostics, Metabolic Studies End User: Research Institutions, Hospitals, Pharmaceutical Companies, Laboratories Technology: Microdialysis, Continuous Sampling, In Vivo Monitoring, High-Performance Liquid Chromatography |
| Companies Covered | Charles River Laboratories International Inc., Medtronic Plc, M Dialysis AB, Bioanalytical Systems Inc., Amuza Inc., Harvard Bioscience Inc., Instech Laboratories Inc., Thermo Fisher Scientific Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microdialysis Market Strategic Shifts
Probe miniaturization and membrane material science are compressing the boundary between clinical diagnostics and real-time therapeutic monitoring, with workflow integration emerging as the primary competitive differentiator.
Polycarbonate-polyether membrane technology is consolidating analytical performance across neuroscience and metabolic monitoring applications. Academic medical centers in Germany and Japan are adopting these materials at accelerated replacement cycles. The technology is consolidating vendor market positions by enabling dual-use catheter platforms that serve both research and clinical endpoints.
EU MDR renewed clinical evidence requirements are reshaping legacy product maintenance costs for probe manufacturers selling into European hospital networks. Industrial consequence includes mandatory post-market surveillance investments that favor larger device portfolios. Neurocritical care segments in France and Italy are responding by consolidating supplier relationships to reduce compliance overhead.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchases, forcing probe manufacturers to price consumables and technical support separately. Major health systems in the United States are driving this shift through value-analysis committees. The pattern is most visible in tertiary hospital networks where bundled contracts previously locked in multi-year vendor relationships.
Microdialysis Market Segmentation
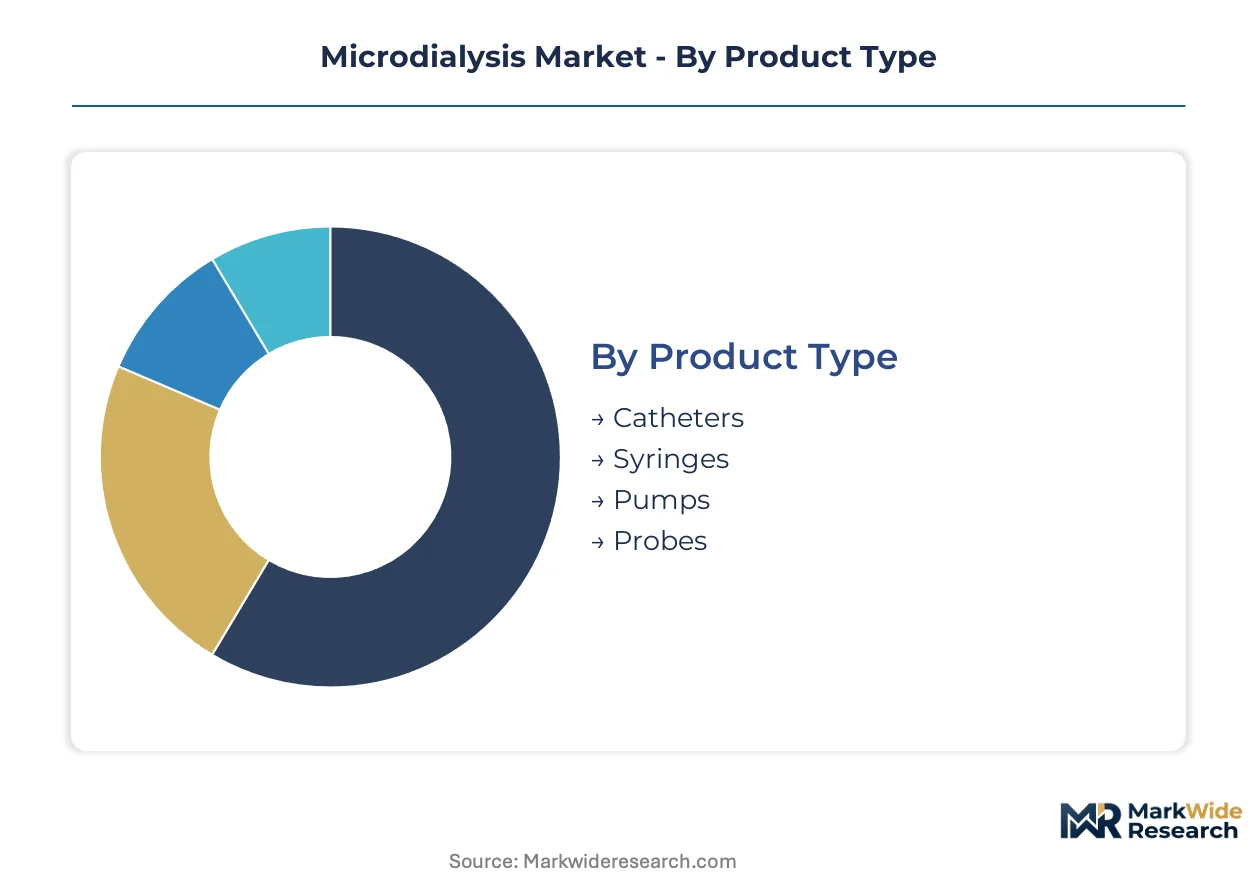
Microdialysis market segmentation reflects distinct procurement patterns across consumable hardware, analytical workflows, and institutional settings. Technology specifications and regulatory compliance requirements drive category-specific purchasing decisions, with neuroscience applications commanding premium membrane configurations while pharmaceutical workflows prioritize throughput scalability.
Product Type:
Membrane diameter and molecular weight cutoff specifications define performance tiers across the consumable hardware spectrum.
- Catheters:Semi-permeable membrane tubes with 0.5–1.0 mm diameters enable continuous extracellular fluid extraction in neurocritical care settings. Academic medical centers in the United States and Germany concentrate replacement demand through fixed infection control schedules.
- Probes:Specialized insertion assemblies with sub-millimeter precision membranes anchor European manufacturing expertise. Direct hospital partnerships in Sweden and Switzerland lock in multi-year supply volumes for neurosurgical applications.
- Syringes:Calibrated infusion systems maintain flow rate stability across preclinical protocols.
- Pumps:Programmable perfusion drivers support adjustable flow parameters for research-grade instrumentation.
Catheters lead on scale; probes lead on momentum.
Application:
Clinical endpoints versus research objectives determine membrane material selection and analytical integration requirements.
- Neuroscience:Brain tissue monitoring for traumatic injury and stroke management deploys 6–20 kDa cutoff membranes for neurotransmitter recovery. Tertiary hospital networks across North America and Western Europe sustain the dominant demand concentration.
- Drug Development:Pharmacokinetic studies in pharmaceutical laboratories require high-throughput sampling configurations. North American contract research organizations are expanding microdialysis deployment fastest for preclinical toxicology workflows.
- Clinical Diagnostics:Metabolite quantification for glucose and lactate monitoring serves intensive care units.
- Metabolic Studies:Continuous tissue sampling supports diabetes and obesity research protocols.
Neuroscience dominates current revenue; drug development climbs the fastest.
End User:
Procurement authority and budget structures fragment demand across institutional categories with distinct compliance obligations.
- Hospitals:Academic medical centers in Japan, Germany, and the United States bundle long-term supply contracts for neurocritical care monitoring. Value-analysis committees unbundle after-sales service from equipment purchases.
- Pharmaceutical Companies:Toxicology and pharmacokinetic divisions scale microdialysis infrastructure for compound screening pipelines. Western European headquarters concentrate contract research outsourcing.
- Research Institutions:University laboratories prioritize customizable flow parameters for protocol flexibility.
- Laboratories:Independent testing facilities serve regional hospital networks with specialized metabolite analysis.
Hospitals anchor volume commitment; pharmaceutical companies drive steepest expansion trajectory.
Technology:
Analytical integration depth separates premium positioning from basic sampling configurations.
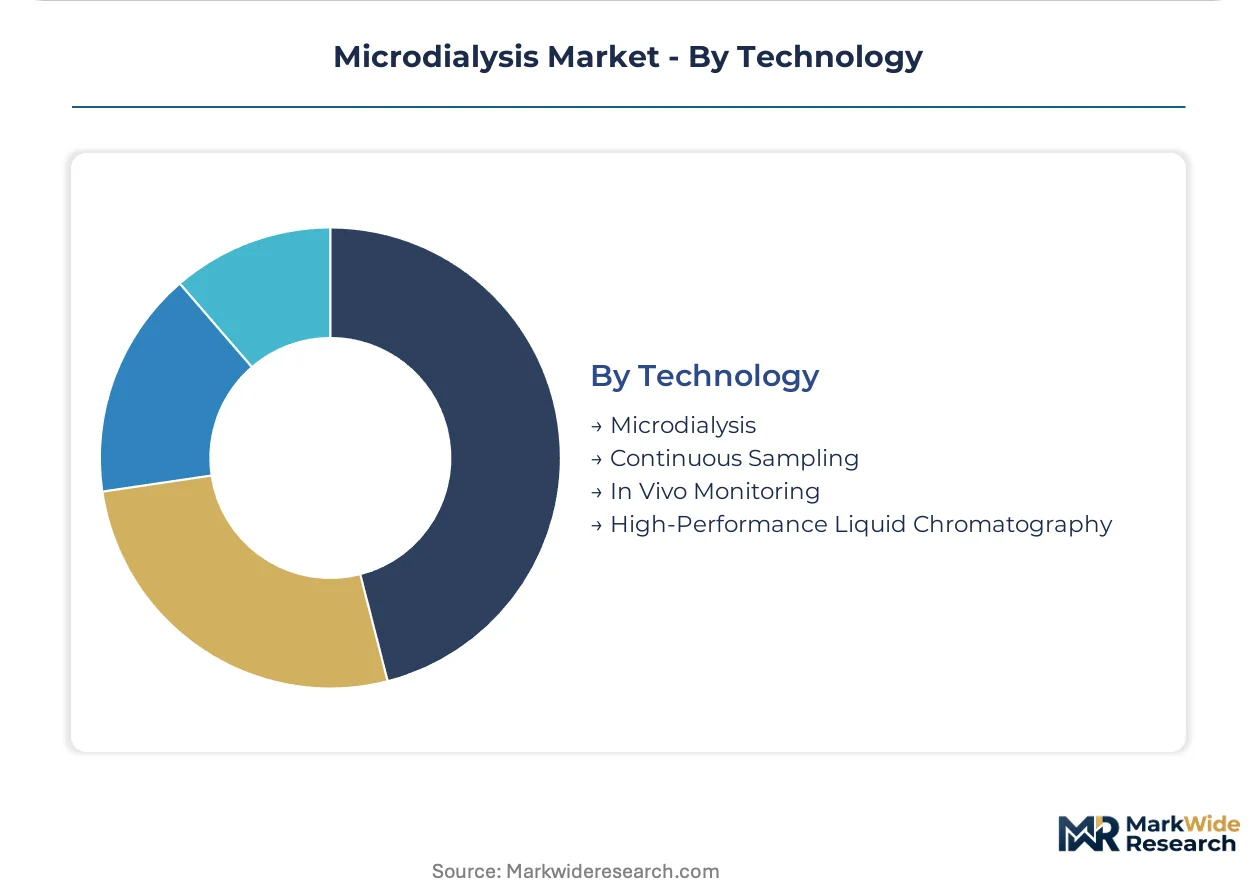
- Microdialysis:Core semi-permeable membrane technology with 6–100 kDa molecular weight cutoffs enables extracellular fluid extraction. ISO 10993 biocompatibility protocols constrain material selection across all regulated markets.
- High-Performance Liquid Chromatography:Chromatographic separation coupled with microdialysis sampling sustains premium metabolite quantification workflows. Capital intensity limits adoption to major hospital laboratories and pharmaceutical central facilities.
- Continuous Sampling:Automated perfusion systems reduce manual intervention for extended monitoring protocols.
- In Vivo Monitoring:Real-time tissue analysis supports therapeutic decision-making in surgical settings.
Microdialysis claims installed base dominance; HPLC integration gains share fastest among new capital deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineers in semipermeable membrane fabrication anchor production capacity across Germany, Sweden, and Switzerland. Academic medical centers in the United States, Germany, and Japan concentrate clinical demand through bundled procurement contracts.
United States
Academic medical centers in Boston and Baltimore drive neurocritical care monitoring adoption through fixed infection control replacement schedules. FDA 510(k) clearance pathways streamline brain tissue monitoring device commercialization for domestic hospital networks. The Greater Boston cluster anchors research-grade instrumentation demand through preclinical protocol customization.
Germany
Tertiary hospital networks in Munich and Heidelberg consolidate supplier relationships to reduce EU MDR compliance overhead. Stricter clinical evidence requirements for legacy probe systems drive replacement demand toward compliant membrane technologies. The Baden-Württemberg manufacturing belt concentrates specialized probe fabrication expertise.
Japan
PMDA biocompatibility testing standards extend registration timelines for foreign manufacturers seeking tertiary hospital access. Tokyo and Osaka academic medical centers bundle long-term supply contracts for neurosurgical applications. The Kanto region anchors domestic membrane polymer development aligned with distinct national standards.
Sweden
Direct hospital partnerships lock in multi-year probe supply volumes across Nordic neurosurgical networks. EU MDR notified body capacity bottlenecks delay product launches despite strong manufacturing expertise. The Uppsala-Stockholm corridor concentrates precision membrane fabrication at sub-millimeter scales.
Switzerland
Swissmedic maintains alignment with EU MDR while preserving distinct quality system requirements for implantable devices. Basel and Zurich hospital networks prioritize dual-use catheter platforms serving research and clinical endpoints. The Swiss-German border region anchors polycarbonate-polyether membrane technology adoption.
Microdialysis Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the microdialysis landscape. The vendor base organizes into three tiers: diversified medical device conglomerates with neurosurgical infrastructure, European probe manufacturing specialists with direct hospital partnerships, and research-grade instrumentation providers serving pharmaceutical laboratories. Strategic moves concentrate on portfolio diversification into continuous glucose monitoring convergence and backward integration into membrane polymer supply.
Among diversified medical device conglomerates, Medtronic Plc occupies a position exemplifying neurosurgical infrastructure leverage across major health systems. European specialists in precision probe manufacturing include M Dialysis AB, which anchors demand through direct hospital partnerships in Sweden and Switzerland. Harvard Bioscience Inc. represents the research-grade instrumentation archetype, with customizable flow parameters addressing pharmaceutical toxicology study expansion.
| Leading Market Players |
|---|
| Charles River Laboratories International Inc. |
| Medtronic Plc |
| M Dialysis AB |
| Bioanalytical Systems Inc. |
| Amuza Inc. |
| Harvard Bioscience Inc. |
| Instech Laboratories Inc. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Family-owned precision manufacturing specialists in Sweden and Switzerland anchor membrane probe production, translating captive polymer formulation expertise into pricing discipline that resists commoditization pressures from larger diversified device conglomerates.
Pricing Analysis
Bundled long-term supply contracts for catheter replacement schedules are unbundling into separate equipment and service components. Price differentiation separates premium polycarbonate-polyether membrane platforms from standard polyethersulfone configurations, with ISO 10993 biocompatibility certification tiers commanding 15-25% uplifts. Cost compression in standard probe tiers is intensifying as academic medical centers consolidate vendor relationships. Pharmaceutical laboratories exhibit the lowest price sensitivity due to protocol-specific customization requirements, while smaller regional hospitals face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Germany, Sweden, and Switzerland maintain hub-and-spoke patterns serving tertiary hospital networks across Western Europe. Membrane polymer supply rests on polycarbonate and polyether raw material streams sourced from BASF and Covestro production facilities in Ludwigshafen. Single-source vulnerability concentrates in sub-millimeter precision extrusion equipment manufactured by German specialists. Distribution runs through direct hospital partnerships for probe assemblies, while consumable catheters flow through medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance cost differentials between established European manufacturers and foreign entrants create geographic-arbitrage opportunities for probe sourcing from Sweden and Switzerland into price-sensitive Southern European hospital networks.
For Market Incumbents: Deploy backward integration into membrane polymer supply to defend margin position against emerging Asian entrants with lower biocompatibility testing cost structures. Lock in multi-year catheter replacement contracts with academic medical centers before EU MDR post-market surveillance investments inflate overhead. Prioritize polycarbonate-polyether platform consolidation to reduce SKU complexity. For New Entrants and Emerging Players: Continuous glucose monitoring convergence represents the most penetrable white-space target, with metabolic monitoring applications outside neuroscience showing minimal incumbent saturation. Preclinical protocol customization for North American contract research organizations offers lower regulatory barriers than clinical device clearance. Lead with adjustable flow parameter instrumentation to differentiate from standardized clinical platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among European probe manufacturing specialists with direct hospital partnerships but limited portfolio diversification beyond neurocritical care. Five-to-ten year viability hinges on successful continuous monitoring platform expansion beyond brain tissue applications. Monitor FDA breakthrough device designation alignment with actual CMS reimbursement coding decisions as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in multi-year catheter placement volumes across major academic medical center networks. |
| FDA Submission | Accelerates commercialization timelines for brain tissue monitoring devices in United States networks. |
| CE Marking Pathway | Enables compliant membrane technology replacement sales across EU MDR-affected European hospital systems. |
| Backward Integration | Captures membrane polymer supply margins and reduces ISO 10993 biocompatibility testing cost exposure. |
| Software Companion Development | Integrates real-time metabolite quantification with existing High-Performance Liquid Chromatography workflows. |
Study Parameters
Direct dialogue with neurocritical care intensivists, biomedical engineers, hospital procurement committee members, and pharmaceutical toxicology directors grounded qualitative findings in operational realities. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body capacity reports, PMDA biocompatibility guidance documents, and hospital GPO contract filings. Bottom-up probe placement volume estimates triangulated against top-down market size assessments across the analysis window.
Bottom-up modeling segmented demand by membrane molecular weight cutoff tier, application endpoint, and end-user institutional category. Top-down validation applied healthcare capital equipment spending patterns and neurocritical care bed expansion trajectories. CAGRs were derived from installed base replacement cycles, pharmacokinetic study pipeline expansion rates, and regulatory approval velocity differentials across FDA, EMA, and PMDA jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity recovery, PMDA registration timeline volatility, and continuous glucose monitoring platform convergence timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Immunoassay Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Sperm Count Test Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Veterinary Chemistry Analyzers Market