
 Rapid Plasma Reagin Test Market | 2026-2036
Rapid Plasma Reagin Test Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Plasma Reagin Test Market Outlook
Hospital procurement of rapid plasma reagin tests is pivoting toward point-of-care platforms that cut turnaround times for syphilis screening. Thermo Fisher Scientific leverages its diagnostic reagent manufacturing scale to supply high-volume hospital systems with standardized RPR card tests. Bio-Rad Laboratories sustains competitive positioning through specialized quality control materials that laboratories require for assay validation. Abbott Laboratories dominates the automated analyzer segment with integrated immunoassay systems that consolidate RPR testing within broader serology workflows.
The rapid plasma reagin test is a non-treponemal flocculation assay that detects antibodies against cardiolipin-lecithin-cholesterol antigen, typically performed on serum or plasma samples with visual agglutination readout or photometric measurement for quantitative results. Card tests retain the largest volume share in resource-limited settings where refrigeration-free storage and minimal equipment requirements prove decisive. Automated analyzers represent the fastest-expanding delivery mode as laboratories pursue throughput gains and reduced manual interpretation variability. Microtiter tests anchor margin pools in blood bank reference laboratories that demand batch processing efficiency and documented traceability for donor screening compliance.
The FDA enforces Current Good Manufacturing Practice standards for in vitro diagnostic devices including RPR reagents, while the Clinical Laboratory Improvement Amendments mandate proficiency testing that shapes laboratory purchasing decisions. The Centers for Medicare and Medicaid Services reimbursement policies directly influence whether hospitals absorb RPR testing internally or outsource to diagnostic laboratories. Stakeholders must monitor evolving CLIA complexity categorization for point-of-care RPR platforms, as reclassification would either expand deployment to non-laboratory settings or restrict access to credentialed personnel.

Market Dynamics
Point-of-care platform migration is compressing traditional laboratory workflows as hospitals prioritize same-day syphilis screening turnaround over batch-processing efficiency.
Growth Catalysts
- CLIA Complexity Reclassification:FDA review of point-of-care RPR platform categorization would expand deployment to urgent care clinics and community health centers currently restricted from moderate-complexity testing.
- Integrated Health Network Consolidation:Large hospital systems in the United States are standardizing serology protocols across acquired affiliates, driving volume commitments to single-source reagent suppliers.
- Cardiolipin Antigen Stabilization:Refrigeration-free lyophilized reagent formulations are extending shelf life and reducing cold-chain infrastructure requirements for rural screening programs.
Market Restraints
- Reimbursement Compression:CMS fee schedule adjustments for serological testing are narrowing margins on automated RPR assays performed in hospital laboratories.
- Treponemal Test Substitution:Chemiluminescence immunoassays for treponemal-specific antibodies are capturing screening volumes in high-throughput reference laboratories.
- Proficiency Testing Burden:CLIA-mandated external quality assessment programs impose recurring costs on smaller diagnostic laboratories operating near minimum volume thresholds.
Strategic Opportunities
- Telehealth-Linked Home Collection:Dried blood spot self-collection kits paired with remote result delivery are opening screening access to populations avoiding traditional clinical settings.
- Blood Bank Automation Integration:Donor screening protocols are creating demand for RPR modules compatible with existing immunohematology analyzer footprints.
- PLI Scheme Manufacturing:India's production-linked incentive framework for medical devices is attracting contract manufacturing investment for card test export production.
Industry Challenges
- Visual Interpretation Standardization:Manual agglutination reading variability requires continuous technologist training and inter-laboratory correlation studies.
- Analyzer Interface Fragmentation:Middleware connectivity gaps between point-of-care RPR devices and laboratory information systems are delaying result documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Plasma Reagin Test Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card Test, Microtiter Test, Automated Analyzer, Rapid Test Kit End User: Hospitals, Diagnostic Labs, Blood Banks, Research Institutions Delivery Mode: Point-of-Care Testing, Laboratory Testing, Home Testing, Mobile Clinics Application: Syphilis Screening, Blood Donation Screening, Epidemiological Studies, Clinical Diagnosis |
| Companies Covered | Thermo Fisher Scientific, Becton Dickinson, Bio-Rad Laboratories, Novacyt, Siemens Healthineers, Cardinal Health, Abbott Laboratories, Arlington Scientific, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Plasma Reagin Test Market Strategic Shifts
Digital result capture and machine-read agglutination are displacing subjective visual interpretation as quality benchmarks tighten across screening networks.
Multiplexed serology cartridges that combine RPR with treponemal-specific antibodies on single-test platforms are rewriting laboratory workflow economics. Large reference laboratories in the United States are piloting these consolidated panels to reduce sample splitting and repeat venipuncture. The technology is compressing the traditional two-test algorithm into one instrument run, threatening standalone RPR reagent volumes.
EU MDR technical documentation requirements for in vitro diagnostic devices are extending conformity assessment timelines for European market entry. Manufacturers must now submit clinical performance data for legacy card tests previously grandfathered under the IVDD framework. Small-to-mid reagent producers are responding by prioritizing FDA 510(k) clearance pathways over CE marking investments.
Bundled procurement contracts that wrap RPR reagents with analyzer placement and maintenance are displacing transactional reagent purchasing in integrated delivery networks. Group purchasing organizations are consolidating laboratory spend across member hospitals, squeezing independent distributors from the supply chain. This concentration is most visible in the southeastern United States, where hospital system mergers have reduced qualified vendor pools by half.
Rapid Plasma Reagin Test Market Segmentation
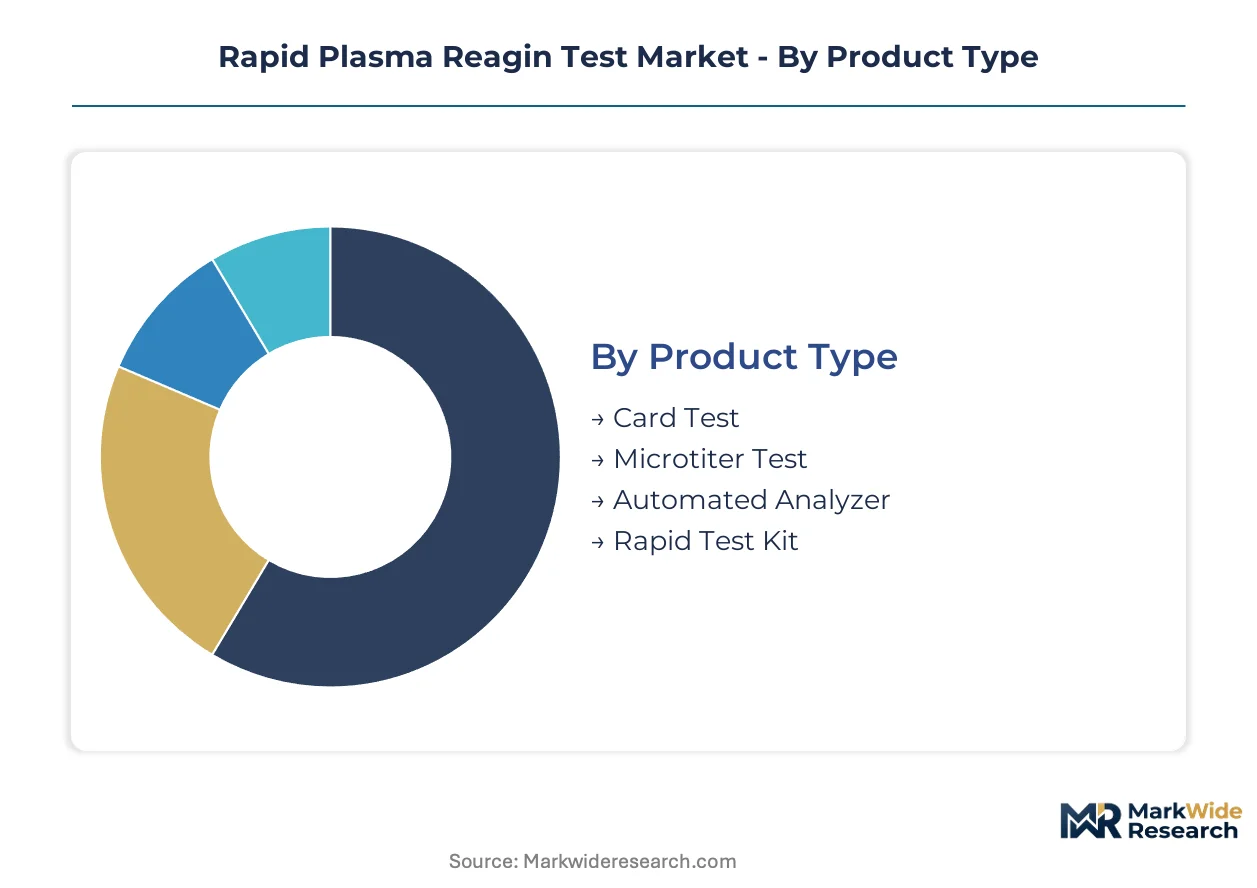
Segmentation in the RPR test market determines procurement pathways, with product format dictating whether facilities qualify for CLIA-waived point-of-care deployment or must maintain moderate-complexity laboratory certification. End-user concentration shapes volume commitments and reagent contracting structures across integrated health networks.
Product Type:
FDA 510(k) clearance requirements vary sharply by product format, with automated analyzers demanding extensive clinical performance documentation while card tests navigate streamlined premarket notification pathways. CE marking under EU MDR imposes parallel technical file burdens that disproportionately affect smaller reagent manufacturers.
- Card Test:Visual agglutination assays on coated cards require no refrigeration and deploy in resource-limited settings where cold-chain infrastructure is absent. Demand concentrates in federally qualified health centers across the United States, driven by CDC-funded syphilis elimination grants requiring frontline screening expansion.
- Automated Analyzer:Photometric measurement systems integrate with laboratory information systems for quantitative titer reporting and automated result flagging. High-throughput hospital laboratories in Texas and Florida are standardizing on these platforms to consolidate serology workflows and reduce manual interpretation errors.
- Microtiter Test:Batch-processing formats with documented traceability serve blood bank reference laboratories requiring donor screening compliance records.
- Rapid Test Kit:Single-use devices with minimal equipment requirements target urgent care clinics seeking same-day turnaround without laboratory infrastructure.
Leading the category by volume: Card Test. Growing fastest: Automated Analyzer.
End User:
Procurement authority and reimbursement pathways diverge across end-user categories, with hospitals capturing in-house testing margins while diagnostic laboratories compete on CMS fee schedule alignment.
- Diagnostic Labs:Independent and hospital-affiliated laboratories process high-volume RPR panels under capitated contracts with managed care organizations. California and New York laboratories dominate regional reference testing, leveraging CLIA proficiency testing networks to validate assay performance across multiple instrument platforms.
- Blood Banks:American Red Cross and independent blood centers mandate FDA-compliant donor screening protocols with full traceability documentation. These facilities require batch processing efficiency and automated result archiving to satisfy AABB accreditation standards.
- Hospitals:Inpatient and emergency departments prioritize point-of-care platforms for immediate clinical decision-making.
- Research Institutions:Academic medical centers utilize RPR assays for epidemiological cohort studies and vaccine trial serosurveillance.
Diagnostic Labs command the largest procurement volumes. Blood Banks maintain the most stringent quality requirements.
Delivery Mode:
CLIA complexity categorization creates regulatory boundaries between delivery modes, with waived testing restricted to FDA-cleared platforms while moderate-complexity testing requires credentialed personnel oversight.
- Point-of-Care Testing:CLIA-waived platforms deploy in urgent care clinics and community health centers without on-site laboratory personnel. Mississippi and Alabama health departments are expanding these programs to address congenital syphilis clusters in underserved counties.
- Laboratory Testing:Moderate-complexity processing in hospital and reference laboratories ensures quantitative titer accuracy for treatment monitoring. These facilities capture reimbursement premiums under CMS fee schedules for technically demanding assays.
- Home Testing:Dried blood spot collection kits paired with telehealth result delivery reach populations avoiding traditional clinical settings.
- Mobile Clinics:Refrigeration-free card tests enable screening in temporary outreach settings serving homeless and migrant populations.
Laboratory Testing generates the highest revenue per test. Point-of-Care Testing is climbing the fastest as CLIA-waived platforms proliferate.
Application:
Application-specific performance requirements influence product selection, with blood donation screening demanding highest sensitivity while clinical diagnosis prioritizes quantitative titer precision.
- Syphilis Screening:Frontline detection programs in sexual health clinics and prenatal care settings drive the majority of RPR test consumption. Los Angeles County and Miami-Dade health departments have scaled screening to address rising primary and secondary syphilis case rates.
- Blood Donation Screening:FDA-mandated serological testing of allogeneic blood donations requires validated assays with documented analytical sensitivity. Blood establishments must maintain continuous proficiency testing participation and instrument calibration records.
- Clinical Diagnosis:Quantitative titer monitoring guides treatment response assessment in infectious disease specialist practices.
- Epidemiological Studies:Population-level serosurveillance supports public health surveillance and outbreak investigation protocols.
Syphilis Screening anchors the largest test volume. Blood Donation Screening maintains the most rigorous regulatory oversight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of RPR reagents concentrates in the United States and Western Europe, while diagnostic consumption spreads across emerging health systems seeking frontline syphilis screening infrastructure. Cold-chain logistics and CLIA complexity regulations shape where production versus testing volumes accumulate.
United States
CDC-funded syphilis elimination grants drive card test deployment in federally qualified health centers across Mississippi and Alabama. FDA enforces Current Good Manufacturing Practice standards for all in vitro diagnostic reagents entering the market. Los Angeles County and Miami-Dade health departments have scaled screening programs to address congenital syphilis clusters in underserved urban corridors.
Germany
EU MDR technical documentation requirements extend conformity assessment timelines for legacy card tests previously grandfathered under IVDD. Blood bank reference laboratories in Bavaria and North Rhine-Westphalia demand batch processing efficiency with full traceability documentation for donor screening compliance. Siemens Healthineers anchors analyzer manufacturing in the Erlangen medical technology cluster.
India
The PLI scheme production-linked incentive framework attracts contract manufacturing investment for card test export production targeting African and Southeast Asian markets. CDSCO regulates in vitro diagnostic device import and domestic manufacturing under the Medical Devices Rules. Diagnostic laboratories in Maharashtra and Karnataka process high-volume RPR panels for both clinical diagnosis and blood donation screening protocols.
Brazil
ANVISA regulates serological assay registration with clinical performance documentation requirements that parallel FDA 510(k) pathways. Blood centers in São Paulo and Minas Gerais maintain AABB-aligned donor screening protocols with continuous proficiency testing participation. Public health laboratories address rising primary and secondary syphilis case rates through expanded prenatal screening mandates.
Japan
PMDA oversees in vitro diagnostic approval with emphasis on analytical sensitivity validation for blood donation screening applications. Reference laboratories in the Kanto region around Tokyo consolidate serology workflows within automated immunoassay systems. The aging population drives demand for integrated diagnostic networks that reduce manual interpretation variability in hospital laboratory settings.
Rapid Plasma Reagin Test Market Competitive Environment
Top-tier vendors anchor the automated analyzer segment, while mid-scale reagent specialists concentrate on card test and quality control material production. Thermo Fisher Scientific, Bio-Rad Laboratories, and Abbott Laboratories occupy distinct competitive positions across instrument, reagent, and integrated system categories. Strategic moves center on bundled procurement contracts that wrap reagents with analyzer placement, and geographic expansion through contract manufacturing partnerships in India.
Among diversified laboratory conglomerates, Thermo Fisher Scientific exemplifies scale-driven reagent manufacturing, while Bio-Rad Laboratories represents specialized quality control material production. Abbott Laboratories anchors the automated analyzer segment with integrated immunoassay systems. These three companies collectively illustrate how competitive positioning fragments across instrument, consumable, and workflow integration archetypes rather than consolidating around single-product dominance.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton Dickinson |
| Bio-Rad Laboratories |
| Novacyt |
| Siemens Healthineers |
| Cardinal Health |
| Abbott Laboratories |
| Arlington Scientific |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive cardiolipin antigen production in the United States and Germany anchors both supply security and pricing power for tier-one reagent manufacturers. Thermo Fisher Scientific and Bio-Rad Laboratories leverage in-house antigen synthesis to command premium positioning while insulating margins from raw material volatility.
Pricing Analysis
Short lead-time premiums apply to lyophilized card test orders from federally qualified health centers facing CDC grant deadlines, while spot inventory discounts move through distributor channels clearing near-expiry reagent stock. Contract-based long-term offtake dominates hospital system procurement, with price differentiation hinging on CLIA complexity tier and analyzer integration depth. CMS reimbursement compression is intensifying because diagnostic laboratories absorb margin erosion rather than pass through to hospital clients. Federally qualified health centers exhibit highest price sensitivity; blood banks demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Cardiolipin antigen supply rests on specialty chemical producers concentrated in the United States, Germany, and Japan. Raw material dependencies span purified bovine heart cardiolipin, synthetic lecithin derivatives, and stabilized cholesterol emulsions. Single-source vulnerability concentrates in bovine-derived biological inputs subject to USDA veterinary inspection protocols. Distribution runs through GPO-negotiated contracts directly to integrated delivery networks, bypassing independent distributors in consolidated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
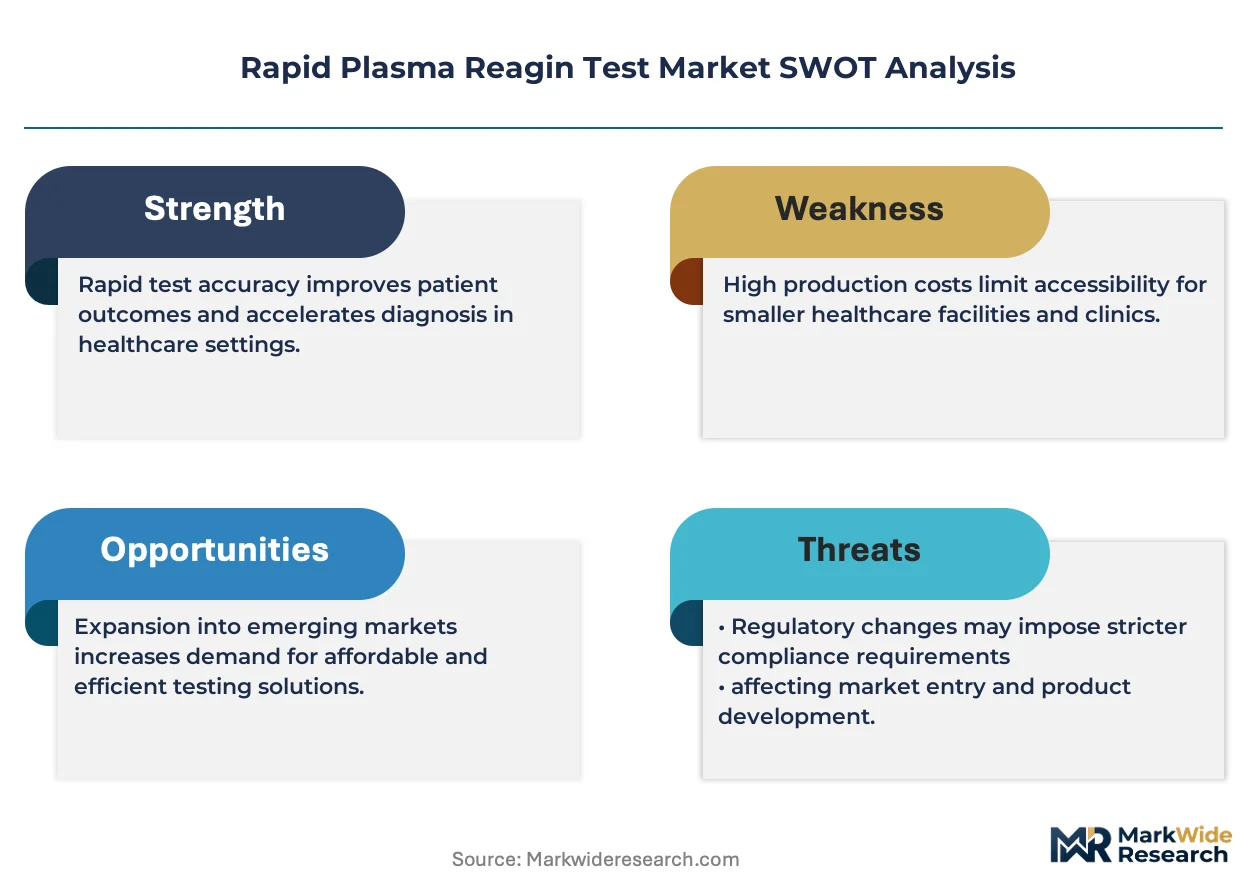
The rapid plasma reagin test market sits in a technology-transition phase as multiplexed serology cartridges displace standalone RPR workflows in high-throughput reference laboratories.
For Market Incumbents: Anticipate treponemal test substitution by embedding RPR modules within broader immunoassay platforms rather than defending standalone reagent volumes. Pursue backward integration into cardiolipin antigen production to secure input cost control against biological raw material volatility. CLIA complexity reclassification poses immediate channel risk if point-of-care platforms shift to waived status and attract new entrants. For New Entrants and Emerging Players: Launch via telehealth-linked home collection models targeting populations avoiding traditional clinical settings in Mississippi and Alabama congenital syphilis corridors. India's PLI scheme manufacturing incentives offer the most penetrable geography for contract production of card tests export-bound to African markets. Partner with urgent care clinic chains seeking same-day turnaround without laboratory infrastructure investment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified laboratory conglomerates seeking point-of-care platform capabilities. Five-to-ten-year viability hinges on successful navigation of multiplexed panel substitution threat. Watch FDA review timelines for CLIA-waived platform reclassification as the critical inflection signal determining addressable market expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates card test entry against EU MDR documentation burdens. |
| Hospital System Partnership | Bundled procurement contracts with Texas and Florida health networks consolidate reagent volumes under single-source agreements. |
| CLIA Complexity Reclassification Strategy | Waived status expansion opens urgent care clinic deployment currently restricted from moderate-complexity testing. |
| Reimbursement Strategy Alignment | CMS fee schedule positioning determines whether hospitals absorb testing internally or outsource to diagnostic laboratories. |
| Software Companion Development | Machine-read agglutination algorithms reduce visual interpretation variability and satisfy tightening quality benchmarks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this rapid plasma reagin test market analysis. Primary interviews with diagnostic laboratory directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) databases, CMS reimbursement schedules, and CDC surveillance reports. Bottom-up instrument placement counts and top-down reagent consumption estimates underwent cross-validation.
Data-stream reconciliation across product format, end-user category, delivery mode, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from instrument install base expansion rates, reagent pull-through per analyzer, and point-of-care platform deployment trajectories. Blood bank donor screening protocol changes and CLIA complexity reclassification scenarios fed scenario-weighted outputs.
Regulatory approval delays, reimbursement schedule adjustments, and treponemal test substitution acceleration are the dominant revision risks to modeled forecasts. Forecasts reflect documented assumptions about instrument replacement cycles and laboratory consolidation patterns. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Diabetic Assays Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Extraction Kits Market