
 Blood Volume Analyzer Market | 2026-2036
Blood Volume Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Volume Analyzer Market Outlook
The EU Medical Device Regulation is expanding compliance burdens for blood volume analyzer manufacturers seeking CE marking access. Abbott Laboratories leverages its diagnostics scale to navigate multiplexed assay portfolios alongside hematology platforms. Sysmex Corporation anchors its position through automated cell counter integration with blood volume measurement workflows. Daxor Corporation specializes in indicator dilution technology for direct plasma volume quantification in critical care settings.
A blood volume analyzer quantifies total blood volume, plasma volume, and red cell mass through indicator dilution or tracer kinetic methods, typically employing iodine-131 tagged albumin or Evans blue dye detection with spectrophotometric readout at 620-625 nm wavelength. These instruments serve transfusion medicine, cardiology, and hematology departments requiring precise volume status assessment to guide fluid resuscitation and blood component therapy. Automated systems command the technology hierarchy through walkaway throughput and LIS connectivity, while portable analyzers penetrate point-of-care environments where rapid triage decisions offset lower precision. Optical detection dominates the technology landscape due to established dye-based protocols, though impedance measurement gains traction in resource-limited settings eliminating radiotracer handling requirements.
The US FDA governs 510(k) clearance pathways for blood volume analyzers as Class II medical devices, while the European Medicines Agency coordinates notified body oversight under MDR Annex VIII classification rules. Clinical laboratories must additionally satisfy CAP accreditation standards for analytical validation and proficiency testing participation. Japan's Pharmaceuticals and Medical Devices Agency maintains distinct master file requirements for dye-based diagnostic reagents. Stakeholders must monitor evolving harmonization between ISO 15189 quality standards and national reimbursement coding for blood volume studies to anticipate access expansion or contraction.
Market Dynamics
The Blood Volume Analyzer Market confronts a structural squeeze between tightening FDA 510(k) and EU MDR validation timelines and hospital procurement's pivot toward integrated hematology platforms over standalone units.
Growth Catalysts
- Surgical volume recovery:Cardiac and orthopedic procedure backlogs in the United States, Germany, and Japan are reactivating transfusion medicine departments and their precision volume assessment requirements.
- MDR Annex VIII classification:The EU's tightened in-vitro diagnostic oversight is filtering out marginal competitors and consolidating procurement toward validated systems with robust clinical evidence packages.
- Indicator dilution automation:Walkaway spectrophotometric platforms are replacing manual Evans blue protocols in high-throughput laboratories, compressing turnaround times for plasma volume quantification.
Market Restraints
- Radiotracer supply concentration:Iodine-131 tagged albumin production clusters in a handful of North American and European radiopharmacy facilities, exposing users to isotope shortage risks.
- Capital equipment cycles:Hospital capital budgets prioritize MRI and CT procurement over specialized hematology analyzers, elongating replacement timelines for legacy blood volume systems.
- Optical dye handling costs:Evans blue reagent stability requirements and spectrophotometric maintenance burdens inflate total cost of ownership versus impedance-based alternatives.
Strategic Opportunities
- Point-of-care penetration:Portable impedance analyzers are opening emergency department and field hospital deployments where rapid triage outweighs laboratory-grade precision.
- Japan's PMDA dye reagent pathway:The agency's streamlined master file process for diagnostic reagents offers faster market access for novel tracer formulations than US or EU routes.
- Hematology platform integration:Converged cell counter and volume analyzer workflows are capturing laboratory real estate by eliminating redundant sample handling steps.
Industry Challenges
- CAP proficiency validation:Clinical laboratories face analytical validation burdens and external quality assessment participation costs that strain mid-sized hospital lab budgets.
- LIS interoperability gaps:Legacy hospital information systems require custom middleware development to ingest automated blood volume analyzer data streams, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Volume Analyzer Market |
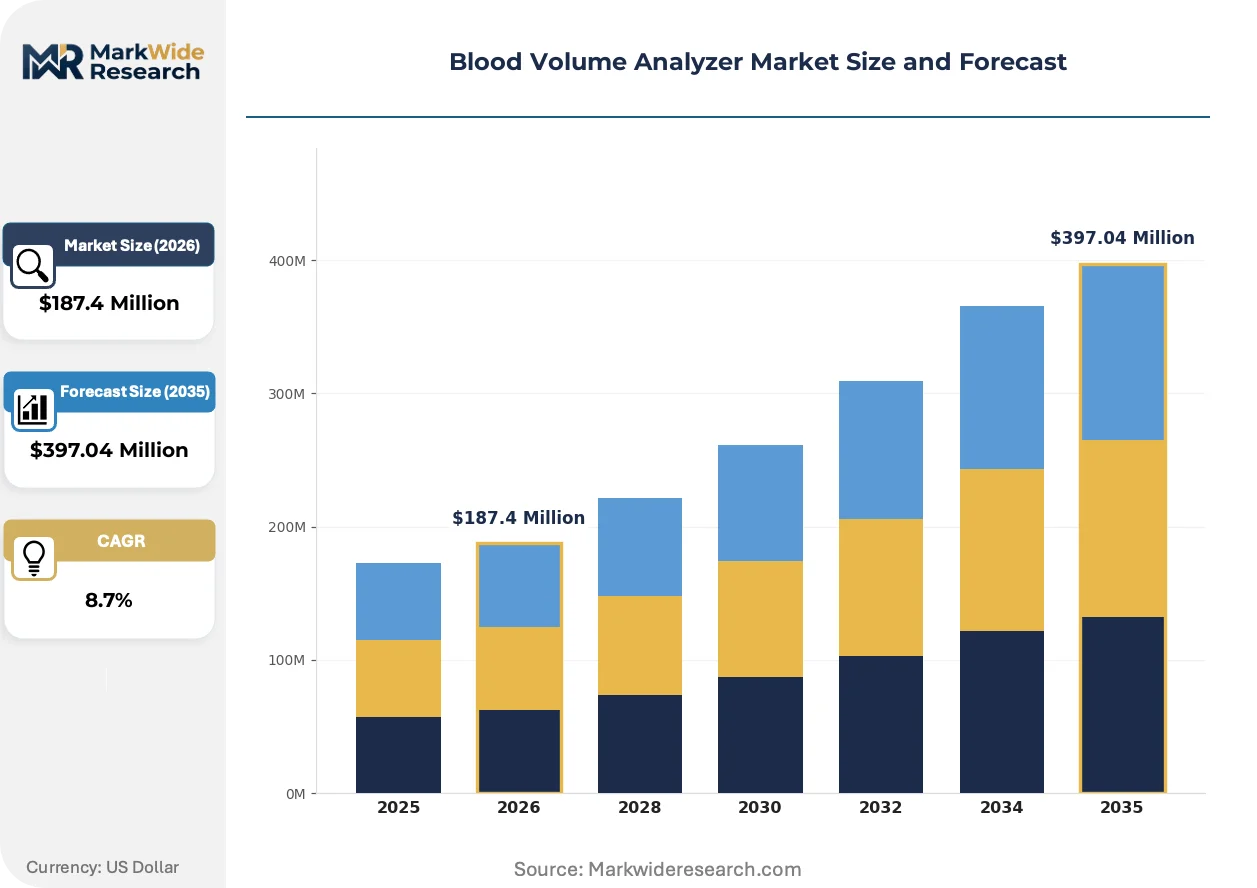
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Desktop Analyzers, Automated Systems, Handheld Devices End User: Hospitals, Diagnostic Centers, Research Laboratories, Blood Banks Technology: Optical Detection, Impedance Measurement, Ultrasound, MRI-Based Application: Transfusion Medicine, Cardiology, Hematology, Clinical Research |
| Companies Covered | Abbott Laboratories, Sysmex Corporation, Daxor Corporation, Mindray, Siemens Healthineers, Bayer, Bio-Rad Laboratories, HORIBA ABX SAS, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Volume Analyzer Market Strategic Shifts
Spectrophotometric detection methods are yielding ground to non-radioactive alternatives as supply chain fragility and waste disposal costs reshape equipment preferences across transfusion medicine.
Impedance-based blood volume measurement is expanding into resource-limited clinical settings by eliminating radiotracer handling protocols and their associated regulatory burdens. Community hospitals and regional medical centers in India and Southeast Asia are adopting these systems despite reduced precision versus optical methods. The technology is expanding into markets previously inaccessible due to isotope licensing requirements.
The EU MDR's Annex VIII classification rules for in-vitro diagnostics are extending notified body review timelines and clinical evidence requirements for new blood volume analyzer submissions. Manufacturers must now demonstrate analytical performance across broader patient populations to secure CE marking. German and French notified bodies are applying the most stringent interpretations, compressing the viable vendor base for European hospital tenders.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases and negotiating third-party maintenance agreements. Independent service organizations are capturing calibration and repair work previously held by original equipment manufacturers. This pattern is most pronounced in United States academic medical centers with dedicated clinical engineering departments.
Blood Volume Analyzer Market Segmentation
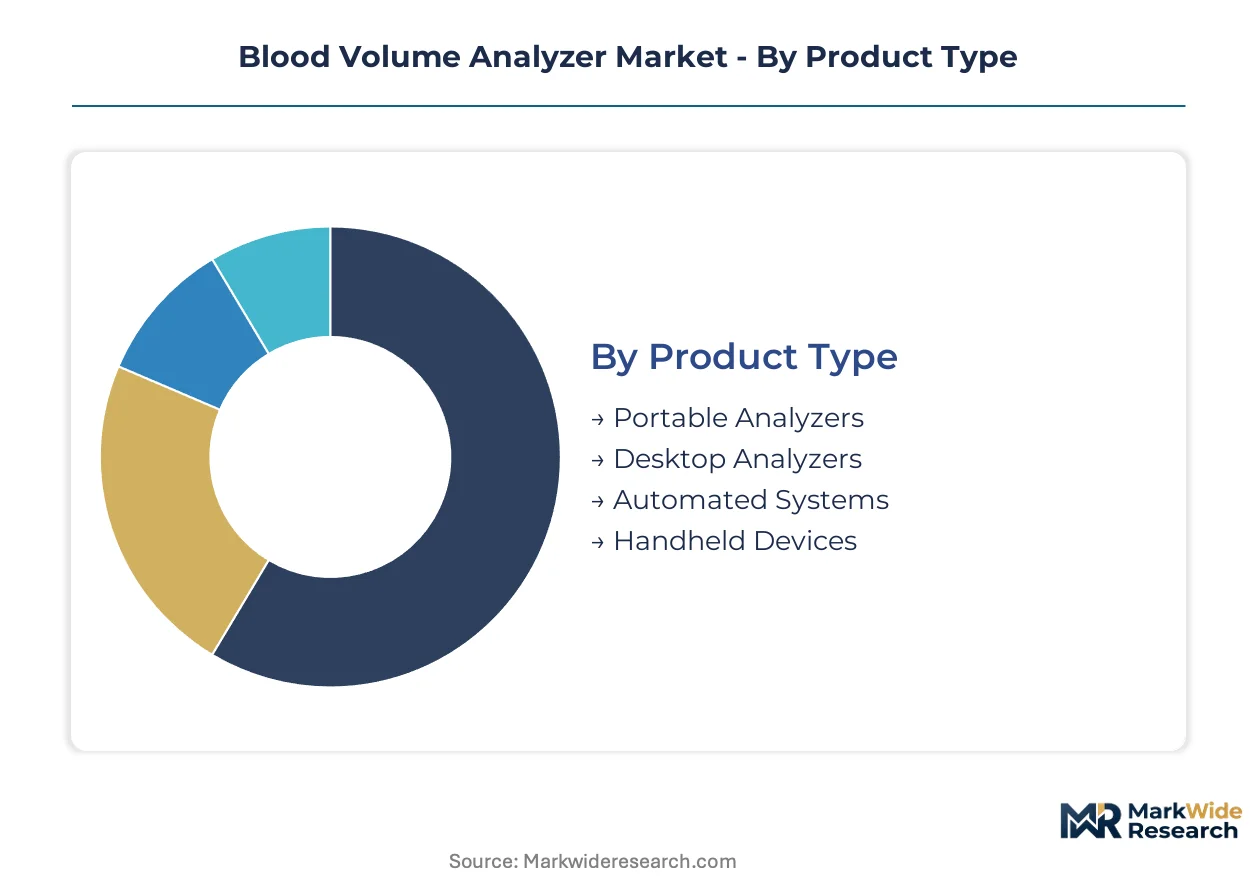
Blood volume analyzer procurement follows distinct upgrade cycles across product tiers, with automated systems displacing manual platforms in high-throughput settings while portable units capture decentralized care expansion. Segmentation reveals how technology maturity, reimbursement pathways, and clinical workflow integration reshape vendor priorities across four critical dimensions.
Product Type:
Replacement cycles accelerate where capital budgets align with integrated hematology platform investments, compressing standalone analyzer refresh timelines.
- Automated Systems:Walkaway spectrophotometric platforms with LIS connectivity dominate academic medical center procurement. Demand concentrates in United States tertiary hospitals where transfusion medicine departments require high-throughput plasma volume quantification for complex surgical schedules.
- Portable Analyzers:Battery-powered impedance units enable emergency department triage without radiotracer handling protocols. Expansion concentrates in Japanese regional hospitals and German field hospital deployments where rapid volume assessment outweighs laboratory precision.
- Desktop Analyzers:Mid-sized optical systems serve community hospital laboratories with moderate transfusion volumes.
- Handheld Devices:Compact impedance meters penetrate point-of-care settings in India and Southeast Asia where infrastructure constraints limit centralized laboratory access.
Volume placements concentrate in Automated Systems; the faster expansion belongs to Portable Analyzers.
End User:
Procurement authority shifts toward integrated health system supply chains, consolidating vendor relationships across multiple analyzer categories under single-source agreements.
- Hospitals:Transfusion medicine, cardiology, and critical care departments drive precision volume assessment demand. United States academic medical centers anchor procurement volume through bundled hematology platform contracts that include blood volume modules.
- Diagnostic Centers:Specialized reference laboratories in Germany and Japan perform outsourced plasma volume studies for smaller hospitals lacking in-house capability.
- Research Laboratories:Clinical trial sites require validated volume measurement for pharmacokinetic studies and fluid resuscitation protocol development.
- Blood Banks:Collection facilities utilize donor volume screening to optimize apheresis procedures and component yield calculations.
Procurement volume clusters in Hospitals; Diagnostic Centers are climbing the fastest as outsourcing expands.
Technology:
Cost tier differentiation separates capital-intensive optical platforms from emerging impedance alternatives that eliminate radiotracer supply dependencies.
- Optical Detection:Evans blue dye spectrophotometry at 620-625 nm wavelength remains the analytical gold standard. Demand persists in United States and European reference laboratories where FDA 510(k) and MDR Annex VIII validation requirements favor established protocols.
- Impedance Measurement:Non-radioactive electrical impedance eliminates isotope licensing and waste disposal burdens. Adoption accelerates in Indian and Southeast Asian community hospitals where regulatory barriers previously blocked market entry.
- Ultrasound:Doppler-based volume estimation serves niche applications in cardiac catheterization laboratories.
- MRI-Based:Magnetic resonance quantification remains restricted to research settings due to capital cost and scan time requirements.
Revenue concentration sits with Optical Detection; Impedance Measurement is gaining share fastest through geographic expansion.
Application:
Margin structures vary sharply across clinical specialties, with transfusion medicine commanding premium pricing for regulatory-validated systems while research applications tolerate higher analytical uncertainty.
- Transfusion Medicine:Perioperative blood management and massive transfusion protocols require precise volume status assessment. United States cardiac surgery programs anchor demand through Joint Commission compliance requirements for blood conservation.
- Cardiology:Heart failure clinics utilize serial volume measurements to guide diuretic therapy and decongestion strategies. German cardiology departments integrate analyzers with hemodynamic monitoring suites.
- Hematology:Myeloproliferative disorder workups require red cell mass quantification to distinguish true polycythemia from spurious elevations.
- Clinical Research:Pharmaceutical trials employ volume measurement for fluid balance assessment in investigational drug safety studies.
Commercial priority attaches to Transfusion Medicine; Cardiology shows the steepest expansion trajectory as heart failure volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device zones in Massachusetts and Bavaria concentrate blood volume analyzer development through proximity to academic medical centers and streamlined FDA 510(k) and EU MDR pre-submission pathways.
United States
Cardiac surgery volume at Cleveland Clinic and Mayo Clinic sustains demand for perioperative blood management protocols. FDA 510(k) clearance timelines for Class II hematology devices average 180 days for predicate-based submissions. Boston's Route 128 corridor hosts indicator dilution technology development alongside transfusion medicine research consortia.
Germany
Heart failure clinic expansion in Berlin and Munich drives serial plasma volume monitoring for diuretic therapy optimization. BfArM notified body oversight under MDR Annex VIII extends clinical evidence requirements for dye-based diagnostic systems. Freiburg's medical technology cluster integrates blood volume modules into automated hematology platform workflows.
Japan
Aging demographics and surgical volume at Tokyo University Hospital and Osaka University Hospital sustain precision transfusion medicine demand. PMDA master file requirements for Evans blue reagents offer streamlined market access versus US or EU routes. Nagoya's medical device manufacturing base produces portable impedance analyzers for regional hospital deployment.
India
Community hospital expansion in Maharashtra and Karnataka adopts impedance-based systems to bypass radiotracer licensing barriers. CDSCO medical device rules classify blood volume analyzers as Class C devices requiring import license validation for optical detection platforms. Hyderabad's diagnostic equipment manufacturing zone assembles cost-optimized portable units for Southeast Asian export.
United Kingdom
NHS blood and transplant services consolidate reference laboratory testing for plasma volume studies at Oxford and Cambridge academic centers. MHRA post-Brexit recognition of EU MDR certificates delays new analyzer introductions by 12-18 months. London's medical technology procurement frameworks prioritize integrated hematology platforms over standalone blood volume systems.
Blood Volume Analyzer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven diagnostic platforms absorb standalone volume analyzer functionality. The vendor base separates into three strategic archetypes: integrated hematology conglomerates, indicator dilution specialists, and emerging impedance technology developers. Consolidation pressures favor acquisition of dye-based protocol expertise by automated platform manufacturers. Geographic expansion into India's community hospital segment and Japan's regional medical center network represents the dominant competitive maneuver.
Within the integrated diagnostics tier, Abbott Laboratories and Siemens Healthineers occupy positions exemplifying platform convergence strategies, while Sysmex Corporation anchors the hematology-automation archetype through cell counter integration. Daxor Corporation represents the pure-play specialist model focused on critical care volume quantification. These three companies illustrate the competitive spectrum from diversified medical technology conglomerates to single-technology developers navigating divergent regulatory pathways across FDA, MDR, and PMDA jurisdictions.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Sysmex Corporation |
| Daxor Corporation |
| Mindray |
| Siemens Healthineers |
| Bayer |
| Bio-Rad Laboratories |
| HORIBA ABX SAS |
| Beckman Coulter |
| Others |
Value Chain & Pricing Dynamics
Iodine-131 isotope spot prices cascade through blood volume analyzer supply chains into three-tier pricing structures across premium, standard, and economy levels. Optical detection platforms tethered to North American radiopharmacy supply command premium positioning, while impedance-based alternatives exploit dye reagent cost volatility to capture mid-market procurement.
Pricing Analysis
Short lead-time premiums apply to FDA 510(k)-cleared systems with validated tracer protocols, while spot inventory discounts emerge for refurbished optical platforms in secondary markets. Pricing stratifies across premium, standard, and economy tiers based on certification level (FDA versus CE marking tier) and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian and Southeast Asian manufacturers are bypassing radiotracer licensing through impedance technology. Academic medical centers in the United States show least price sensitivity due to bundled hematology platform contracts; community hospitals in emerging markets demonstrate highest sensitivity to capital equipment outlays.
Supply Chain Analysis
Direct-to-hospital channels handle United States academic medical center demand, while distribution runs through regional diagnostic equipment distributors in Germany and Japan. Manufacturing concentrates in the United States, Germany, and Japan for optical detection platforms; China and India anchor impedance analyzer assembly. Supply chains draw from iodine-131 radiopharmacy facilities in North America and Europe, Evans blue dye chemical suppliers in Germany and Switzerland, and semiconductor components from Taiwan and South Korea. Single-source vulnerability concentrates in iodine-131 production, where five North American facilities serve global demand. Third-party maintenance organizations are capturing calibration and repair work previously held by original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blood volume analyzer competition is becoming a vertical-integration race, with platform manufacturers pursuing backward integration into indicator dilution protocol expertise to capture transfusion medicine department budgets.
For Market Incumbents: Anticipate impedance technology substitution by securing exclusive distribution rights for emerging non-radioactive tracer formulations. Lock in hospital system GPO contracts across hematology platform bundles before EU MDR Annex VIII compliance costs filter out marginal competitors. Prioritize in-house production of spectrophotometric detection modules to defend margin position against independent service organization encroachment on maintenance revenue. For New Entrants and Emerging Players: The premium-to-economy price-point gap in portable analyzers opens white-space entry for battery-powered impedance units targeting Japanese regional hospitals and German field hospital deployments. India's community hospital segment offers the most penetrable geography, with CDSCO Class C device rules favoring domestic assembly over import-dependent optical platforms. Pursue PMDA master file partnerships with established dye reagent suppliers to accelerate regulatory access versus de novo FDA 510(k) pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play indicator dilution specialists with installed base concentration in United States academic medical centers. Long-term viability hinges on convergence with automated hematology workflows rather than standalone analyzer positioning. Watch for FDA 510(k) clearance timeline compression as the inflection signal for optical detection platform recovery versus impedance substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Annex VIII compliance separates viable European vendors from filtered competitors. |
| Hospital System Partnership | GPO contracts at Cleveland Clinic and Mayo Clinic anchor high-throughput platform placements. |
| Backward Integration into Tracer Supply | Radiopharmacy facility partnerships secure iodine-131 allocation priority during shortage cycles. |
| Software Companion Development | LIS middleware solutions resolve interoperability gaps delaying automated analyzer deployment. |
| Reimbursement Strategy | CPT code alignment for blood volume studies determines hospital laboratory budget allocation. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU MDR notified body submission records, and PMDA master file registrations, complemented by interviews with transfusion medicine directors, hospital biomedical engineers, GPO contracts managers, and clinical laboratory accreditation officers. Secondary sources included CAP proficiency testing participation data, CMS Medicare reimbursement schedules, and ISO 15189 quality standard implementation reports. Bottom-up modeling of analyzer placements by hospital tier and top-down triangulation against hematology platform market estimates validated volume outputs.
Cross-referencing historical placement patterns against expert panel input on MDR compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user facility scale, detection technology category, and clinical application specialty. CAGRs derived from weighted average of procedure volume growth and capital equipment replacement cycle compression. Industry-specific inputs incorporated cardiac surgery backlog recovery trajectories and radiotracer supply concentration risk factors.
Inputs from FDA 510(k) databases and EU notified body registries were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around quarterly placement estimates. Forecasts reflect assumptions regarding surgical volume normalization and MDR implementation enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Vacuum Blood Collection Tube Market