
 Point of Care Diagnostics Market | 2026-2036
Point of Care Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care Diagnostics Market Analysis
The FDA's emergency use authorization pathway is broadening the cost-of-entry calculus for molecular diagnostics entrants by reducing traditional clinical trial burdens while raising post-market surveillance obligations. Abbott leverages its vertically integrated manufacturing footprint to sustain margin control across glucose meter and cardiac biomarker portfolios. Siemens Healthineers anchors European hospital networks with centralized laboratory connectivity that extends into point-of-care nodes. Danaher Corporation competes through specialized microfluidics expertise that differentiates its infectious disease testing platforms from conventional lateral flow alternatives.
Point of care diagnostics encompasses portable analytical systems designed to deliver clinical-grade results at or near the patient site, typically operating with sample volumes below 500 microliters and turnaround times under 30 minutes for time-critical decisions. These systems serve primary industrial purposes in decentralized healthcare delivery, enabling triage acceleration in emergency departments and chronic disease monitoring outside traditional laboratory infrastructure. Glucose meters occupy the most mature segment with compressed margins and replacement-driven demand, while molecular diagnostics represents the fastest-expanding technology category as nucleic acid amplification platforms shrink toward handheld formats. Infectious disease testing captures disproportionate investment flow following pandemic-era infrastructure buildout, and home care settings emerge as a contested channel where regulatory clarity on remote result interpretation remains unsettled.
FDA oversight through the Clinical Laboratory Improvement Amendments and EU MDR certification requirements under notified body supervision collectively shape product development timelines and geographic launch sequencing for device manufacturers. The EPA regulates waste streams from disposable test cartridges, adding compliance layers that influence material selection and end-of-life design protocols. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payer policies will determine whether home-based testing achieves economic viability comparable to clinic-administered alternatives.
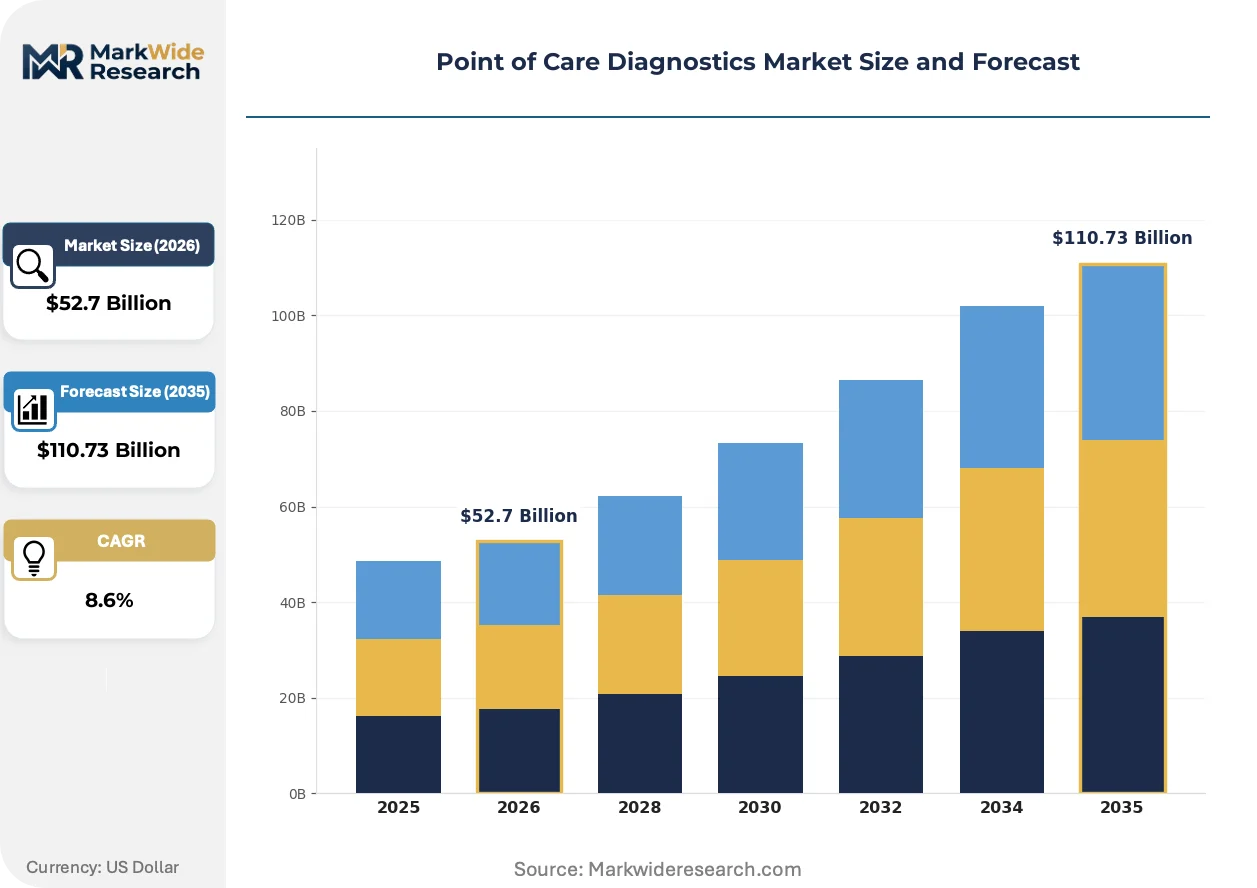
Market Dynamics
Decentralized testing infrastructure is compressing traditional laboratory workflows into handheld formats, forcing incumbents to defend centralized revenue streams against portable molecular platforms that bypass legacy capital equipment.
Growth Catalysts
- FDA Emergency Use Authorization:The abbreviated pathway accelerates molecular diagnostic commercialization while maintaining clinical validity standards for infectious disease panels.
- Emergency Department Triage:Hospital networks deploy rapid pathogen identification to reduce admission bottlenecks and antibiotic stewardship delays.
- Microfluidics Miniaturization:Sample volume requirements below 500 microliters enable fingerstick collection methods that eliminate phlebotomy infrastructure.
Market Restraints
- Reimbursement Code Gaps:CMS and private payers lag in establishing parity pricing between clinic-administered and home-based testing, suppressing home care channel viability.
- Cartridge Manufacturing Concentration:Disposable consumable production clusters in East Asian contract manufacturers, exposing supply continuity to geopolitical friction.
- CLIA Complexity:Clinical Laboratory Improvement Amendments waive requirements for waived tests but impose quality control burdens that elevate operational costs for moderate-complexity platforms.
Strategic Opportunities
- Chronic Disease Monitoring:Cardiac biomarker and HbA1c testing platforms penetrate home care settings where remote patient monitoring reimbursement codes are stabilizing.
- EU MDR Convergence:Harmonized certification requirements across European notified bodies create pathway efficiency for manufacturers pursuing multi-country hospital procurement.
- Multiplex Panel Expansion:Respiratory pathogen combinations beyond SARS-CoV-2 capture seasonal diagnostic demand from urgent care networks seeking operational efficiency.
Industry Challenges
- Bioinformatics Talent Scarcity:Result interpretation algorithms require computational biology expertise that outpaces supply from traditional medical device engineering pipelines.
- Interoperability Friction:Point-of-care devices must integrate with electronic health record systems that lack standardized data exchange protocols, delaying hospital adoption timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care Diagnostics Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Hemoglobin A1c Test Kits, Infectious Disease Testing, Cardiac Biomarkers Technology: Microfluidics, Lateral Flow Assays, Molecular Diagnostics, Immunoassays End User: Clinics, Hospitals, Home Care Settings, Emergency Departments Application: Chronic Disease Management, Infectious Disease Detection, Pregnancy Testing, Cardiovascular Risk Assessment |
| Companies Covered | Abbott, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Danaher Corporation, BD, bioMérieux, QIAGEN, Thermo Fisher Scientific Inc., QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care Diagnostics Market Emerging Trajectories
Automation of nucleic acid amplification is eliminating manual sample preparation steps that previously required laboratory technician intervention, collapsing turnaround times toward real-time clinical decision-making.
Isothermal amplification chemistry is automating thermal cycling steps that conventional PCR platforms delegate to benchtop equipment, enabling handheld devices that match reference laboratory sensitivity. Community health centers and urgent care chains in the United States are deploying these platforms for sexually transmitted infection screening where same-day treatment initiation improves epidemiological outcomes. The technology is automating workflow steps that previously required CLIA-certified personnel, expanding test administration to nursing staff without molecular biology training.
EU MDR Article 10 technical documentation requirements are extending clinical evidence obligations to legacy devices previously certified under the Medical Devices Directive, forcing portfolio reassessment among established manufacturers. Notified body capacity constraints in Germany and the Netherlands are extending certification timelines, delaying product launches for mid-tier entrants lacking existing quality management system infrastructure. Infectious disease testing platforms face heightened scrutiny for analytical specificity claims, driving manufacturers toward larger clinical validation cohorts than predecessor regulatory frameworks demanded.
Hospital procurement committees are consolidating vendor relationships around integrated laboratory information system connectivity, favoring platforms with bidirectional electronic health record integration over standalone devices. Emergency departments in the United States and Germany are prioritizing middleware solutions that aggregate point-of-care results into centralized dashboards, displacing paper-based documentation workflows. This consolidation pattern concentrates purchasing power among health systems with sufficient scale to negotiate enterprise-wide pricing agreements, compressing margins for manufacturers dependent on fragmented clinic sales channels.
Point of Care Diagnostics Market Segmentation
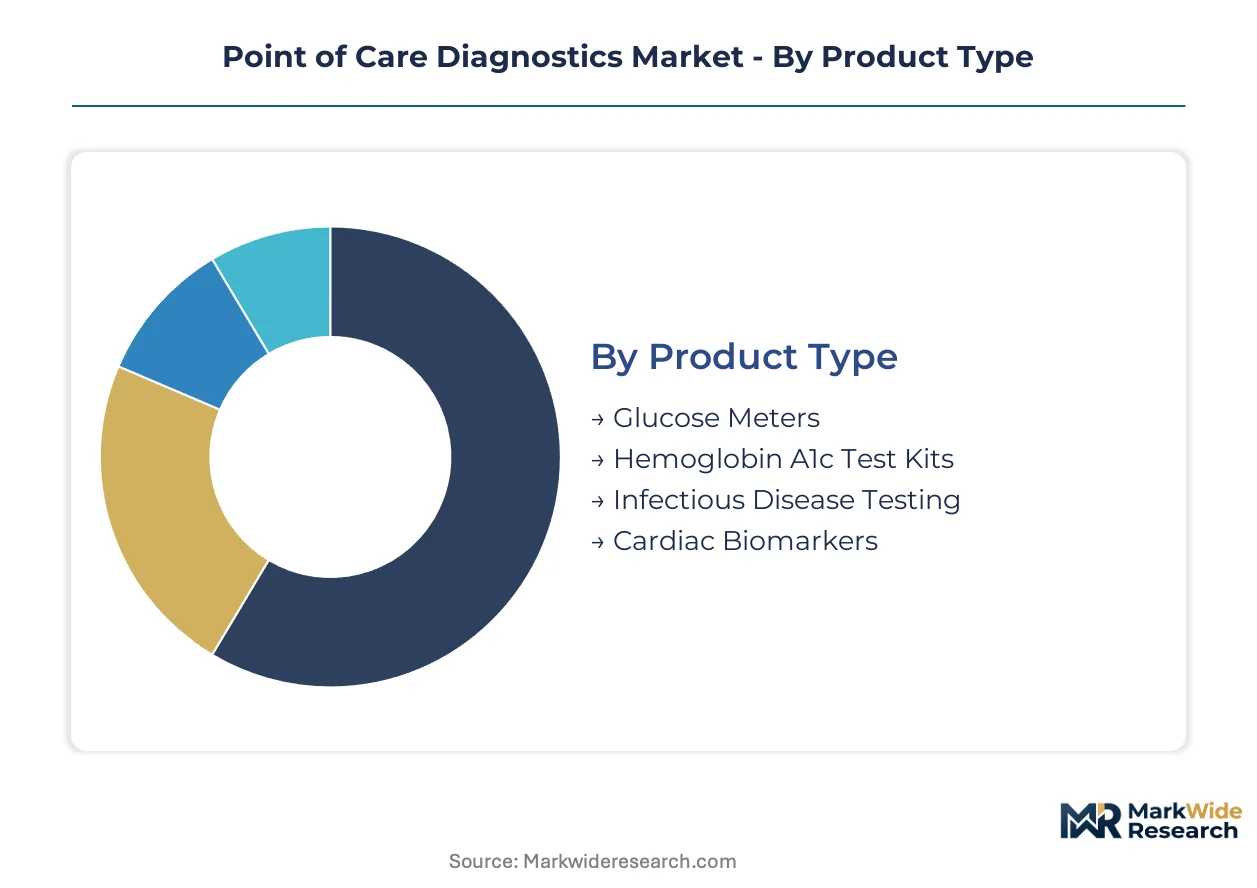
Point of care diagnostics fragments across four distinct taxonomies that shape procurement behavior and margin structure differently. Product type determines replacement cycle economics. Technology selection dictates regulatory pathway complexity and manufacturing capital requirements.
Product Type:
Buyers in this category separate by reimbursement stability and consumable attachment rate rather than upfront device cost.
- Glucose Meters:Electrochemical biosensors with capillary blood sampling dominate daily diabetes management. Demand concentrates in United States home care settings where CMS reimbursement codes sustain recurring strip purchases.
- Infectious Disease Testing:Nucleic acid amplification and antigen detection platforms target respiratory, sexually transmitted, and gastrointestinal pathogens. Emergency departments in Germany and the United States deploy multiplex panels to compress antibiotic stewardship timelines.
- Hemoglobin A1c Test Kits:Boronate affinity chromatography and immunoassay methods deliver laboratory-correlated glycemic control metrics. United States accountable care organizations integrate these into value-based diabetes management contracts.
- Cardiac Biomarkers:Quantitative troponin and BNP assays operate with 15-minute turnaround for acute coronary syndrome rule-out. Hospital networks in China prioritize these for chest pain pathway acceleration.
Volume sits with glucose meters; growth tilts toward infectious disease testing.
Technology:
Technology choice here tracks sample volume minimums and thermal control requirements, which determine portability ceiling and operator skill barriers.
- Molecular Diagnostics:Isothermal amplification and micro-PCR platforms achieve reference laboratory sensitivity in handheld formats. China's NMPA has accelerated registration timelines for SARS-CoV-2/flu/RSV combination assays.
- Microfluidics:Laminated polymer cartridges integrate sample preparation, reagent storage, and waste containment in sub-500 microliter footprints. German hospital procurement committees favor these for CLIA-waived operation by nursing staff.
- Lateral Flow Assays:Nitrocellulose membrane immunochromatography delivers qualitative results without powered instrumentation. United States urgent care chains deploy these for streptococcal pharyngitis screening.
- Immunoassays:Fluorescence and chemiluminescence detection methods quantify protein biomarkers with picogram sensitivity. Emergency departments prioritize these for cardiac troponin protocols requiring traceable calibration.
Revenue concentrates in immunoassays; steepest expansion trajectory belongs to molecular diagnostics.
End User:
End user segmentation follows capital availability and regulatory certification depth, with home care representing the contested frontier.
- Hospitals:Integrated health systems demand bidirectional electronic health record connectivity and enterprise middleware dashboards. United States academic medical centers negotiate volume-based pricing for multi-site standardization.
- Emergency Departments:Triage acceleration drives 24/7 staffing requirements and rapid pathogen identification workflows. German hospital networks deploy these platforms for sepsis bundle compliance.
- Clinics:Federally qualified health centers in the United States seek waived-complexity devices to avoid CLIA personnel costs. Seasonal respiratory panels capture peak demand during influenza surges.
- Home Care Settings:Remote patient monitoring reimbursement gaps suppress channel viability despite glucose meter penetration. China's internet hospital regulations are clarifying telemedicine result interpretation protocols.
Procurement volume clusters in hospitals; home care captures the fastest share gain as reimbursement codes stabilize.
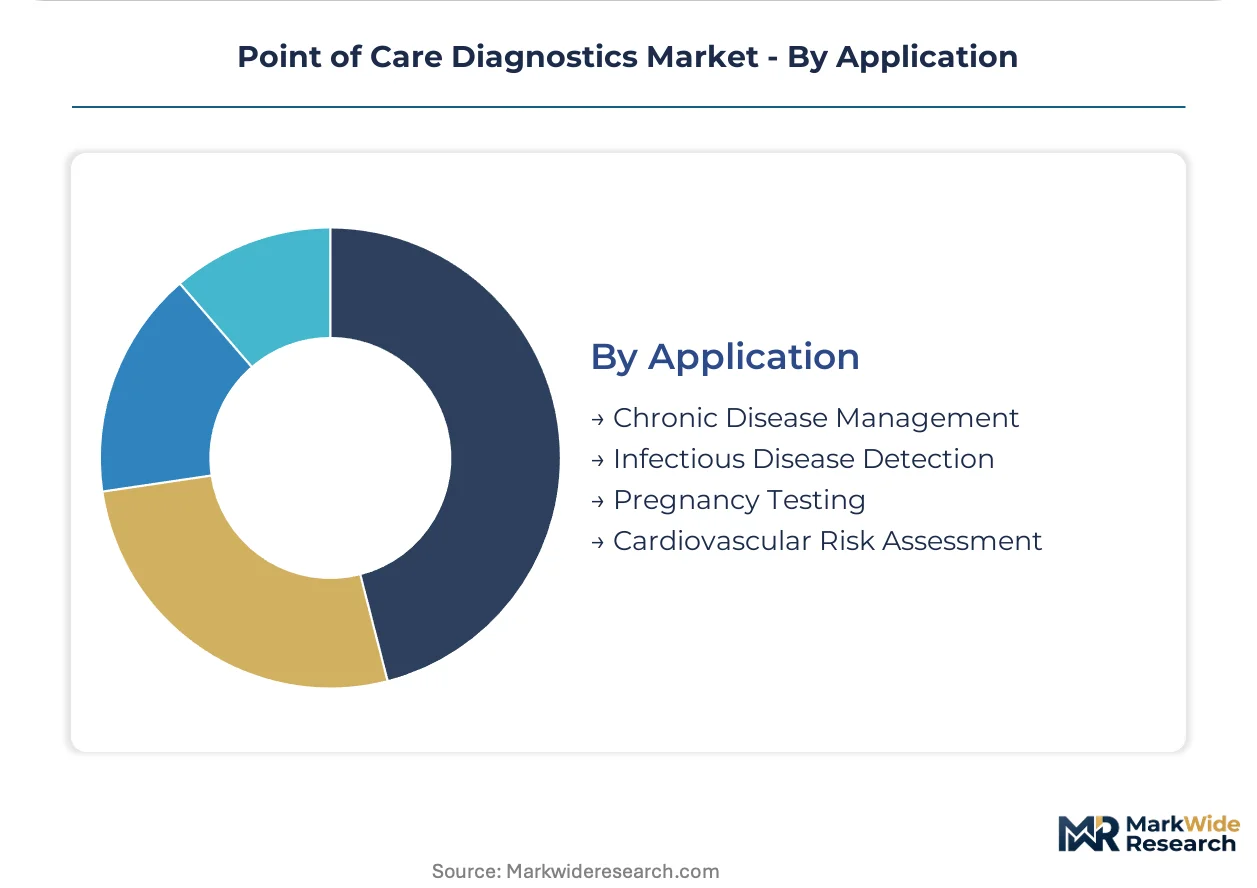
Application:
Application demand correlates with chronic disease prevalence curves and acute outbreak patterns rather than technology novelty.
- Infectious Disease Detection:Syndromic respiratory panels and sexually transmitted infection platforms address antimicrobial resistance surveillance. United States public health laboratories subsidize deployment in underserved counties.
- Chronic Disease Management:Diabetes and cardiovascular monitoring platforms integrate with remote patient monitoring ecosystems. German disease management programs reimburse HbA1c testing at quarterly intervals.
- Cardiovascular Risk Assessment:Lipid panels and cardiac biomarkers stratify acute chest pain presentations. China's tiered hospital system directs high-sensitivity troponin testing to provincial centers.
- Pregnancy Testing:Human chorionic gonadotropin detection remains the most penetrated home diagnostic category. Retail pharmacy distribution in the United States sustains commodity margin structures.
Chronic disease management holds current volume leadership; infectious disease detection is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks and German hospital procurement committees currently drive the majority of point-of-care diagnostic volume, while China's NMPA regulatory reforms are accelerating domestic manufacturer participation in molecular diagnostics.
United States
Emergency department triage acceleration and accountable care organization value-based contracts sustain demand for rapid infectious disease panels and cardiac biomarkers. FDA's emergency use authorization pathway compresses commercialization timelines for molecular diagnostic entrants while elevating post-market surveillance obligations. The Boston-Cambridge corridor hosts concentrated bioinformatics talent pools that support algorithm development for result interpretation platforms.
Germany
Hospital network consolidation around integrated laboratory information systems drives procurement standardization across multi-site health systems. EU MDR notified body supervision through German and Dutch certification bodies extends technical documentation requirements for legacy device portfolios. The Rhine-Ruhr metropolitan region anchors European distribution networks for microfluidics cartridge manufacturing.
China
Tiered hospital system reforms direct point-of-care cardiac biomarker testing toward provincial medical centers while expanding access in county-level facilities. NMPA has accelerated registration timelines for SARS-CoV-2/flu/RSV combination assays to support respiratory surveillance infrastructure. The Yangtze River Delta concentration of polymer manufacturing supplies disposable test cartridge substrates for domestic and export markets.
United Kingdom
National Health Service integrated care systems are piloting remote patient monitoring reimbursement frameworks that would clarify home-based testing economics. MHRA operates recognition routes for FDA-cleared devices that streamline parallel market entry for US manufacturers. The Oxford-Cambridge arc concentrates lateral flow assay development expertise transferred from pandemic-era manufacturing scale-up.
Japan
Aging demographic pressure and primary care workforce constraints drive adoption of CLIA-waived devices for nursing staff administration in community health settings. PMDA consultation programs for in vitro diagnostics provide regulatory pathway clarity for multiplex panel submissions. The Kansai region's precision manufacturing base supplies miniaturized optical detection components for fluorescence immunoassay platforms.
Point of Care Diagnostics Market Vendor Landscape
United States-based producers anchor the premium molecular diagnostics tier; European specialists hold consolidated positions in immunoassay and microfluidics platforms. The vendor structure concentrates around integrated health system procurement relationships, with mid-tier entrants facing elevated barriers from electronic health record interoperability requirements. Three archetypes dominate: vertically integrated conglomerates with captive manufacturing, specialized microfluidics technology licensors, and regional rapid test assemblers. Competitive dynamics center on M&A activity targeting connectivity middleware capabilities and strategic partnerships with East Asian contract manufacturers for cartridge supply security.
Within the vertically integrated tier, Abbott and Siemens Healthineers exemplify archetypes that combine device manufacturing with centralized laboratory connectivity solutions. Danaher Corporation occupies a position representing specialized microfluidics expertise that differentiates platform architectures from conventional lateral flow alternatives. These three entities anchor distinct strategic approaches to defending procurement relationships against portable molecular platforms that bypass legacy capital equipment requirements.
| Leading Market Players |
|---|
| Abbott |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| BD |
| bioMérieux |
| QIAGEN |
| Thermo Fisher Scientific Inc. |
| QuidelOrtho Corporation |
| Others |
Supply Flow & Price Mechanics
Isothermal amplification chemistry miniaturization is collapsing thermal cycling equipment requirements while simultaneously shifting cost economics toward polymer cartridge substrates and concentrating manufacturing leverage among East Asian precision molders. This production-method transition rewards manufacturers with captive microfluidics capabilities while squeezing margin structures for device-only competitors dependent on contract consumable supply.
Pricing Analysis
Volume sits with glucose meters where strip commoditization compresses margins to replacement economics; premium accrues to molecular diagnostics platforms commanding instrument-plus-consumable bundling. Three-tier pricing structure across CLIA-waived, moderate-complexity, and laboratory-correlated certification levels segments buyer willingness-to-pay by regulatory burden and result traceability requirements. Cost compression in lateral flow infectious disease panels intensifies as urgent care chains consolidate procurement around multi-pathogen respiratory combinations. Federally qualified health centers exhibit highest price sensitivity due to capped reimbursement rates, while academic medical centers prioritize middleware integration over per-test economics.
Supply Chain Analysis
Domestic-content mandates in China's NMPA procurement guidelines and India's PLI scheme for medical devices are reshaping sourcing patterns for polymer substrates and optical detection components. Disposable cartridge manufacturing concentrates in China, South Korea, and Germany, drawing from specialized polycarbonate resin grades, nitrocellulose membranes, and fluorescence detection dyes. Single-source vulnerability runs through East Asian contract molders serving multiple competing platform manufacturers. Distribution runs through health system GPO contracts in the United States, hospital procurement consortiums in Germany, and tiered hospital network tenders in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where cartridge manufacturing control and electronic health record middleware development represent the decisive upstream and downstream levers separating sustainable margin structures from commoditization traps.
For Market Incumbents: Deepen microfluidics cartridge manufacturing ownership to defend consumable attachment rates against emerging molecular platforms with open-system architectures. Secure exclusive middleware partnerships with Epic and Cerner to embed bidirectional result transmission as a switching cost. Portable nucleic acid amplification entrants threaten hospital laboratory revenue streams; backward integration into polymer substrate production mitigates East Asian supply concentration risk.
For New Entrants and Emerging Players: Urgent care chains represent the most penetrable channel partner type for CLIA-waived respiratory panels, bypassing entrenched hospital procurement relationships. Target county-level hospital networks in China's tiered system where NMPA accelerated registration timelines lower regulatory barriers. Home care settings offer white-space expansion as remote patient monitoring reimbursement codes stabilize, with telemedicine platform partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by conglomerates seeking microfluidics IP portfolios and FDA-cleared assay menus. Long-term viability hinges on demonstrating sustainable consumable pull-through rates exceeding instrument depreciation cycles. Watch for inflection when CMS establishes reimbursement parity between clinic-administered and home-based molecular testing, signaling channel economics viability.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Complexity Navigation | Quality management system investment unlocks moderate-complexity assay expansion beyond waived-test limitations. |
| EU MDR Technical Documentation | Notified body certification pathway secures German hospital procurement committee access for legacy device portfolios. |
| Hospital System Partnership | Enterprise middleware integration contracts concentrate purchasing power and displace standalone device competitors. |
| Microfluidics Manufacturing Scale-Up | Captive cartridge production insulates margin structures from East Asian contract manufacturer supply friction. |
| Reimbursement Strategy Development | Remote patient monitoring code advocacy determines home care channel economic viability against clinic alternatives. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, and CMS reimbursement code proposals, complemented by interviews with hospital procurement managers, biomedical engineers at academic medical centers, CLIA laboratory directors, and GPO contracts specialists. Secondary validation drew from hospital capital expenditure databases, infectious disease surveillance reports from the United States and Germany, and NMPA registration timelines. Bottom-up instrument and consumable unit economics triangulated against top-down health system diagnostic spending allocations.
Segment-level outputs across the projection horizon reflect modeled interactions between product type replacement cycles, technology regulatory pathway complexity, end user capital availability, and application prevalence curves. CAGRs derived from instrument installation base growth, consumable pull-through rate assumptions, and pricing trajectory by certification tier. Forecast inputs incorporated CLIA waiver expansion timelines, EU MDR notified body capacity constraints, and NMPA domestic manufacturer preference policies.
Caveats apply where FDA emergency use authorization pathway modifications, EU MDR Article 10 clinical evidence requirement shifts, or CMS remote patient monitoring reimbursement decisions could materially shift the outlook. Pandemic-era infrastructure buildout assumptions and cartridge manufacturing geographic concentration represent specific revision triggers for infectious disease testing demand. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Non-Invasive Biosensors Market