
 US Prostate Cancer Nuclear Medicine Diagnostics Market | 2026-2036
US Prostate Cancer Nuclear Medicine Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Prostate Cancer Nuclear Medicine Diagnostics Market Insights
Gallium-68 PSMA radiotracers is expanding access to precision prostate cancer staging across US health systems. Lantheus leverages its radiopharmaceutical manufacturing infrastructure to supply major academic medical centers. Blue Earth Diagnostics anchors the competitive landscape with specialized PET imaging agents. Telix Pharmaceuticals Limited competes through targeted therapeutic diagnostics development.
US Prostate Cancer Nuclear Medicine Diagnostics encompasses radiopharmaceutical-based molecular imaging that detects prostate-specific membrane antigen expression or osteoblastic bone metastases, utilizing technetium-99m, gallium-68, or fluorine-18 labeled compounds with gamma camera or PET-CT detection thresholds. The primary purpose is non-invasive tumor localization, staging, and treatment response monitoring in urologic oncology. PSMA PET leads product type segmentation due to superior sensitivity for biochemical recurrence detection versus conventional bone scintigraphy. Hybrid imaging dominates technology adoption by fusing functional PET data with anatomical CT detail. Oncology clinics represent the fastest-growing end user segment as outpatient molecular imaging capacity expands.
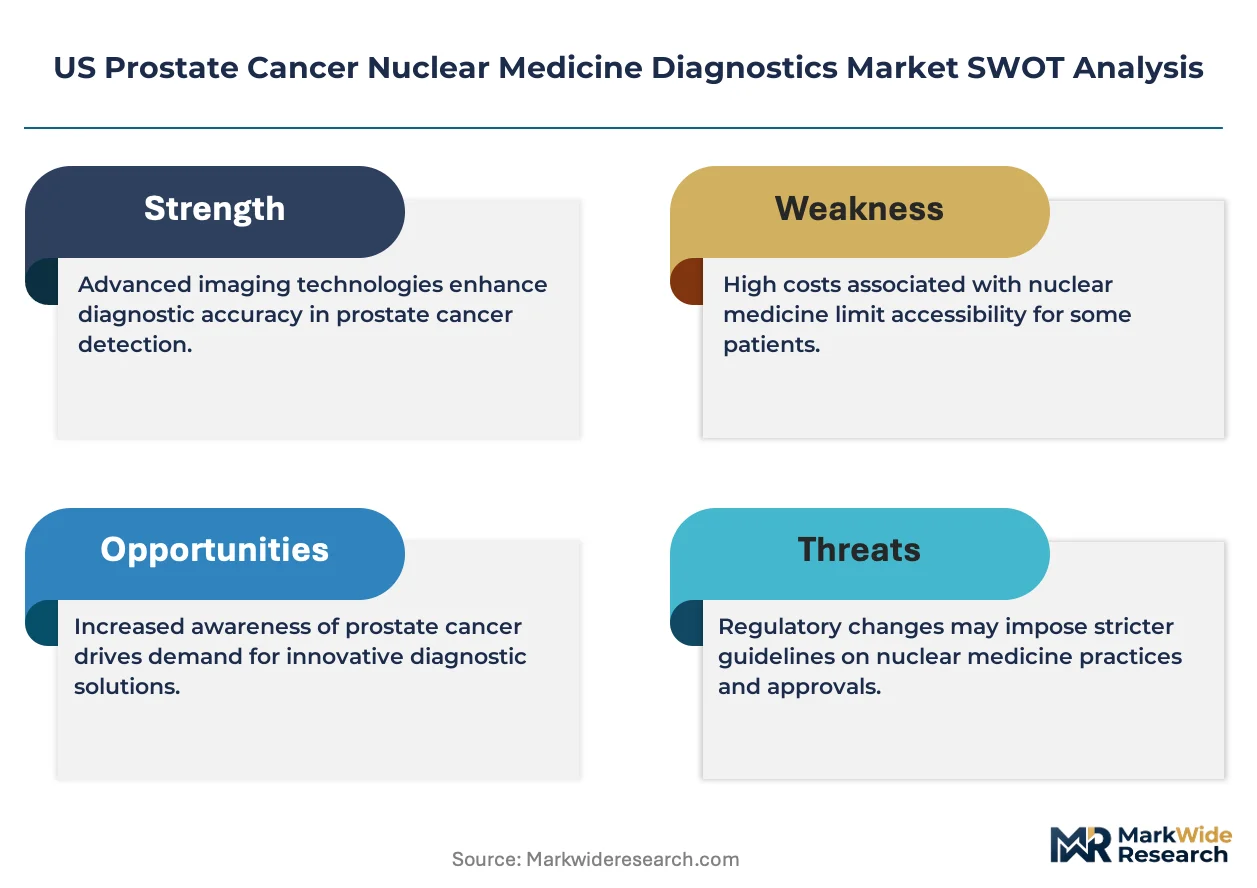
FDA regulates radiopharmaceutical safety and efficacy through New Drug Applications and orphan drug designations, while NRC governs radioactive material handling, storage, and disposal at clinical sites. CMS reimbursement determinations for PSMA PET procedures directly shape provider adoption economics and patient access. Stakeholders must monitor evolving NRC agreement state regulations and CMS national coverage decisions as novel alpha-emitter theranostics enter clinical practice.
Market Dynamics
PSMA PET imaging is consolidating clinical workflows across US urologic oncology, compressing the diagnostic timeline from biochemical recurrence detection to treatment initiation while displacing conventional bone scintigraphy in academic medical centers.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement for PSMA PET procedures under Medicare Advantage plans accelerates patient access in community oncology networks.
- Outpatient Oncology Clinics:Freestanding imaging centers in Texas and Florida are deploying fixed PET-CT systems to capture referral volume from independent urology practices.
- Gallium-68 Generator Infrastructure:On-site radiopharmaceutical production eliminates cold-chain logistics constraints and enables same-day scanning protocols.
Market Restraints
- Molybdenum-99 Supply Concentration:Aging reactors in Canada and Europe create vulnerability for technetium-99m bone scan agents still used in rural health systems.
- NRC Agreement State Variability:Inconsistent radioactive materials licensing requirements across California, Texas, and New York complicate multi-site health system expansion.
- Fluorine-18 Cyclotron Capital Intensity:The $3-5 million infrastructure requirement per production site limits PSMA PET radiotracer manufacturing to major metropolitan hospital networks.
Strategic Opportunities
- Theranostic Pairing:Alpha-emitter therapy demand in the Southeast is creating pull-through for companion diagnostic imaging using lutetium-177 PSMA radioligands.
- Mobile PET-CT Deployment:Leased imaging units are penetrating underserved markets in the Mountain West where fixed scanner density remains below national averages.
- IRA Domestic Manufacturing Incentives:Tax credits for active pharmaceutical ingredient production are attracting radiopharmaceutical contract manufacturing investment to the Ohio River Valley.
Industry Challenges
- Radiochemist Talent Pipeline:The specialized synthesis expertise required for gallium-68 and fluorine-18 labeling exceeds current nuclear pharmacy residency output.
- PET-CT Interoperability:DICOM standardization gaps between molecular imaging workstations and electronic health record systems delay report integration into multidisciplinary tumor boards.
- Alpha-Emitter Waste Disposal:Limited licensed burial capacity for actinium-225 and radium-223 contaminated materials constrains therapeutic expansion in the Northeast corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Prostate Cancer Nuclear Medicine Diagnostics Market |
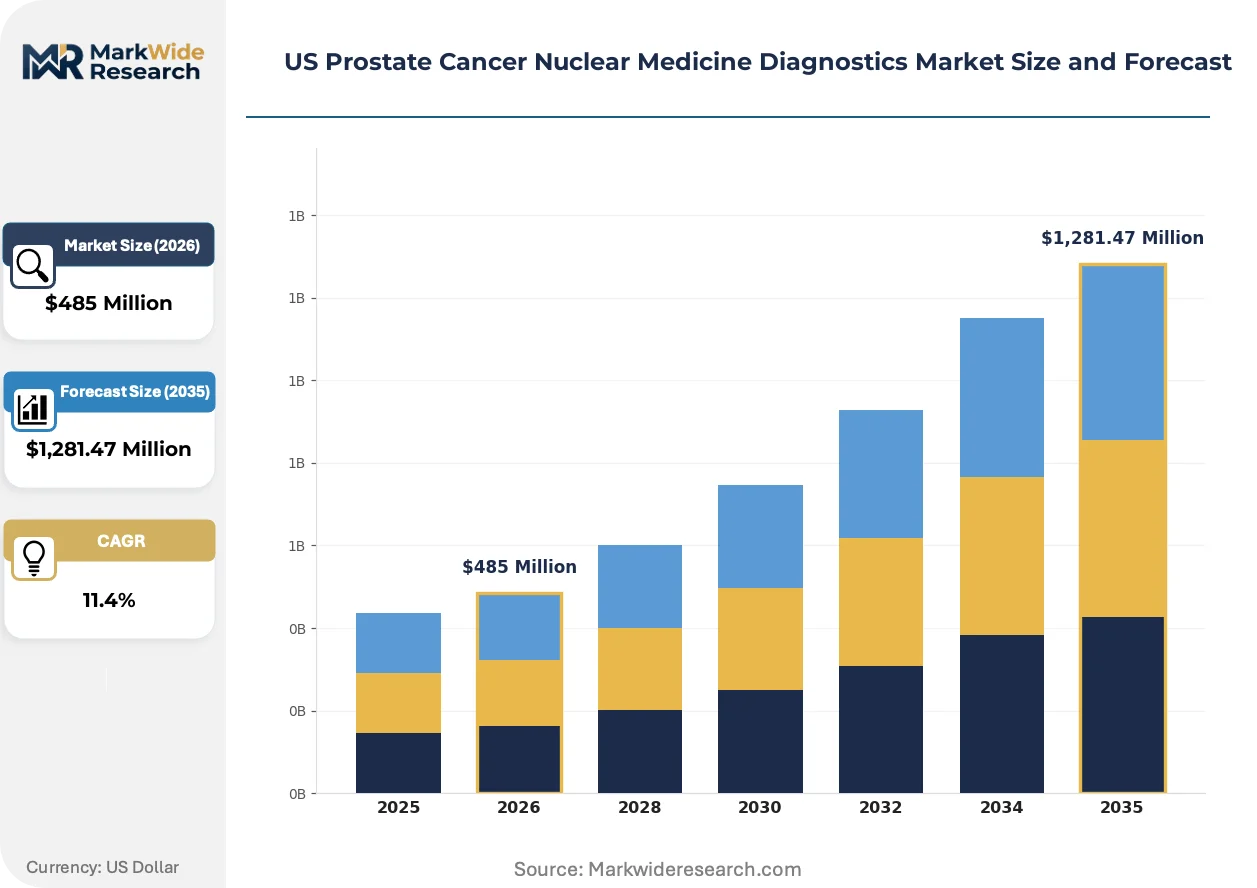
| Market Size in 2026 | $485 Million |
| Market Size in 2035 | $1,281.47 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PSMA PET, Bone Scintigraphy, CT Scans, MRI Technology: Hybrid Imaging, Digital Imaging, Nuclear Medicine, Radiopharmaceuticals End User: Oncology Clinics, Hospitals, Diagnostic Centers, Research Institutions Delivery Mode: In-Hospital, Home Care, Mobile Services, Telemedicine |
| Companies Covered | Blue Earth Diagnostics, Lantheus, Cardinal Health, Telix Pharmaceuticals Limited, NCM-USA LLC, Jubilant Draximage Radiopharmacies, Inc., Siemens Healthcare Private Limited, CURIUM PHARMA, PETNET Solutions, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Prostate Cancer Nuclear Medicine Diagnostics Market Trends and Innovations
Artificial intelligence integration and theranostic platform development are compressing the diagnostic-therapeutic continuum, enabling personalized treatment selection based on quantitative PSMA expression metrics rather than qualitative visual assessment alone.
Artificial intelligence quantification tools are consolidating radiologist workflow efficiency by automating PSMA lesion segmentation and standardized uptake value measurement. Community hospital radiology departments in the Midwest are piloting FDA-cleared algorithms to reduce interpretation variability and accelerate report turnaround. This consolidation is compressing the competitive advantage gap between academic subspecialists and general diagnostic radiologists.
FDA breakthrough device designation pathways are accelerating novel radiopharmaceutical review timelines for prostate cancer indications. The agency's expanded access programs enable earlier patient exposure to investigational PET agents before full approval. Oncology clinics in California and Massachusetts are leveraging these mechanisms to participate in phase III trials for next-generation small molecule PSMA ligands.
Patient self-referral patterns are fragmenting traditional hospital-based imaging capture as direct-to-consumer prostate health screening programs proliferate. Independent imaging centers in Florida and Arizona are marketing cash-pay PSMA PET packages to patients with rising PSA levels outside established urologist relationships. This channel shift is pressuring academic medical centers to reduce scheduling friction and expand evening and weekend scanner availability.
US Prostate Cancer Nuclear Medicine Diagnostics Market Segmentation
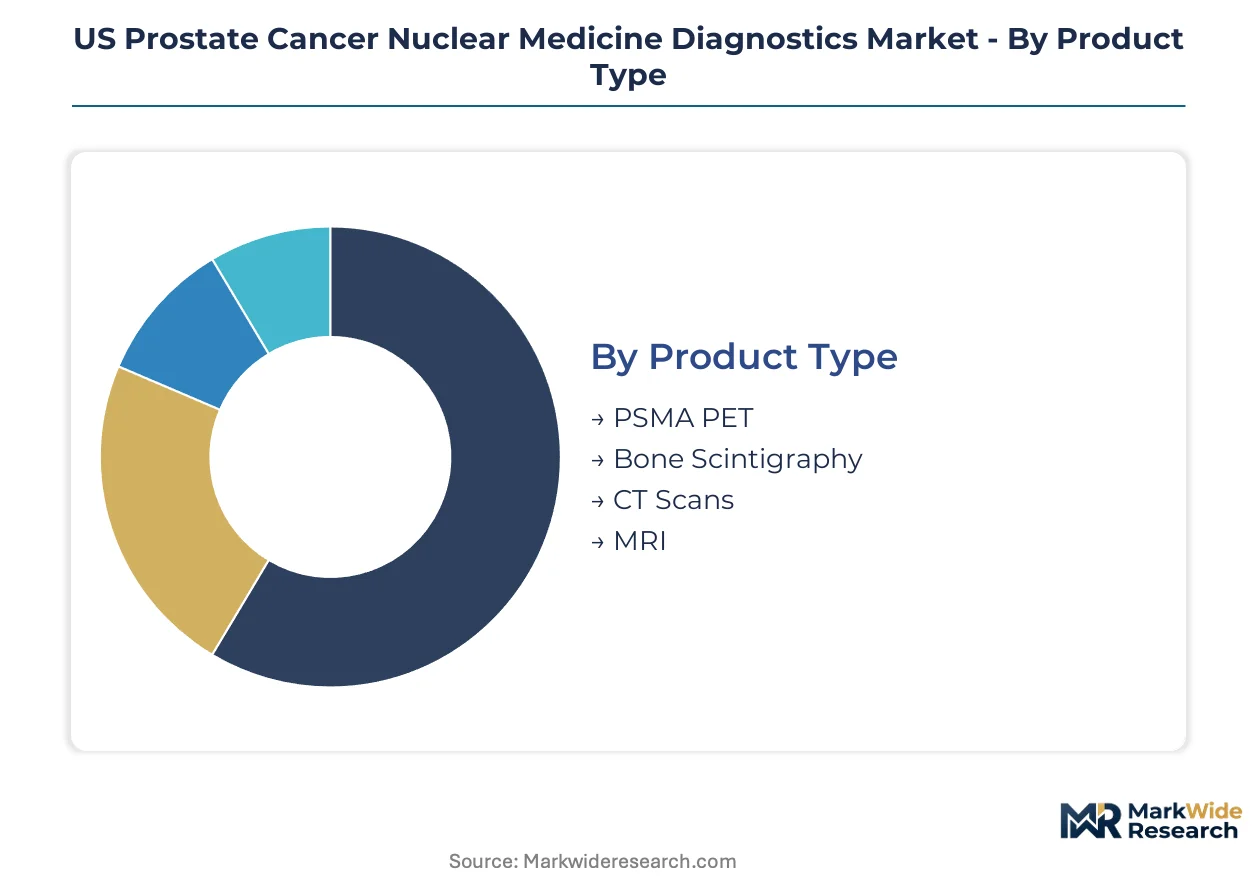
Segmentation in prostate cancer nuclear medicine diagnostics reveals how clinical workflows, capital deployment, and reimbursement economics fragment demand across distinct operational models. Each category exposes different integration depths—from standalone outpatient services to embedded hospital systems—shaping vendor go-to-market strategies and capital allocation priorities.
Product Type:
PSMA PET operates as the embedded diagnostic anchor within urologic oncology workflows, while bone scintigraphy persists in standalone rural deployment where capital constraints limit PET-CT penetration.
- PSMA PET:Gallium-68 and fluorine-18 labeled prostate-specific membrane antigen ligands enable whole-body metastatic staging with superior sensitivity for biochemical recurrence detection versus conventional imaging. Demand concentrates in metropolitan hospital networks across the Northeast and California where academic medical centers drive referral volume and CMS reimbursement pathways are established.
- Bone Scintigraphy:Technetium-99m methylene diphosphonate scans detect osteoblastic bone metastases through gamma camera imaging at lower cost per procedure than molecular PET. Rural health systems in the Mountain West and Great Plains retain this modality where fluorine-18 cyclotron infrastructure remains economically unviable and molybdenum-99 supply chains still reach.
- CT Scans:Anatomical cross-sectional imaging provides structural correlation for PET fusion and independent staging in patients with iodinated contrast tolerance.
- MRI:Pelvic multiparametric MRI enables local tumor localization and extraprostatic extension assessment prior to definitive therapy planning.
Volume placements concentrate in PSMA PET; the faster expansion belongs to this same segment as CMS national coverage determinations broaden community access.
Technology:
Cost tier differentiation separates capital-intensive hybrid installations from lower-barrier digital and radiopharmaceutical alternatives that penetrate budget-constrained settings.
- Hybrid Imaging:PET-CT and PET-MRI fusion systems combine functional radiotracer distribution with anatomical detail, commanding premium capital expenditure and specialized radiologist interpretation. Academic medical centers in Texas and Florida anchor procurement volume for these integrated platforms.
- Digital Imaging:Software-based image reconstruction, noise reduction, and quantitative analysis tools upgrade existing scanner capabilities without hardware replacement. Community hospital networks in the Midwest adopt these solutions to narrow the diagnostic accuracy gap with academic referral centers.
- Nuclear Medicine:Gamma camera and SPECT systems for technetium-99m bone scintigraphy persist in high-throughput screening applications.
- Radiopharmaceuticals:Diagnostic tracers and therapeutic isotopes constitute the consumable revenue stream recurring across every imaging procedure.
Capital deployment tilts toward hybrid configurations; radiopharmaceuticals capture the steepest expansion trajectory as theranostic pairing accelerates.
End User:
Customer type segmentation maps how site-of-care economics and referral pattern control determine purchasing authority and volume concentration.
- Oncology Clinics:Freestanding outpatient facilities owned by urology groups or independent operators capture PSA surveillance and biochemical recurrence monitoring outside hospital walls. Texas and Florida lead this segment's expansion where certificate-of-need restrictions are absent and physician entrepreneurship is culturally embedded.
- Hospitals:Integrated health systems with captive referral networks and inpatient surgical volumes anchor PET-CT capital installation and complex case staging. Metropolitan hospital networks in California and Massachusetts concentrate procurement authority through centralized radiology service line management.
- Diagnostic Centers:Independent imaging facilities without oncology practice ownership compete on price and scheduling accessibility for cash-pay and commercial insurance patients.
- Research Institutions:Academic medical centers with NIH funding and clinical trial portfolios drive novel radiopharmaceutical validation and FDA breakthrough device pathway utilization.
Procedure volume concentrates in hospitals; oncology clinics are climbing the fastest as vertical integration between urology practices and imaging assets deepens.
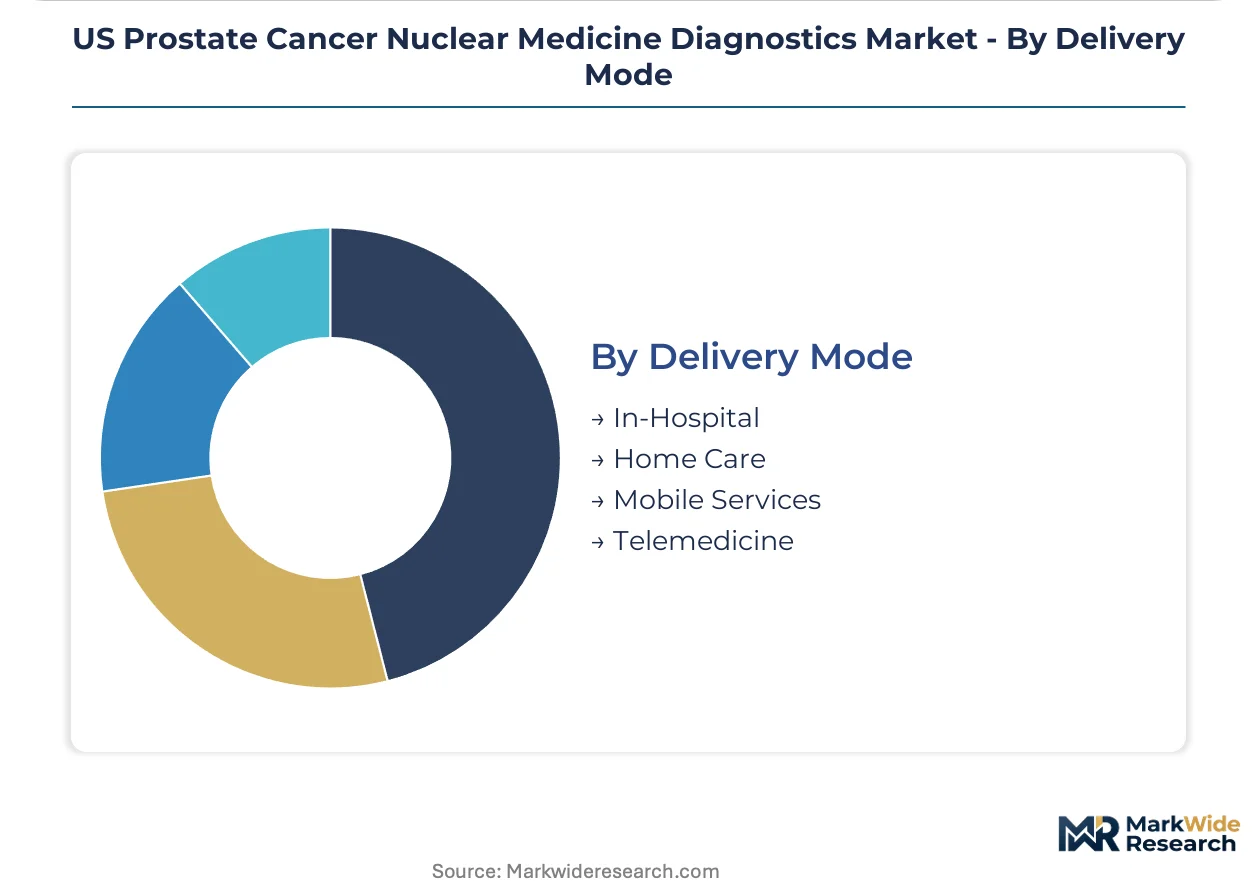
Delivery Mode:
Supply concentration and geographic reach constraints shape which delivery models achieve viable unit economics across different population density environments.
- In-Hospital:Fixed PET-CT installations within academic medical centers and community hospitals capture complex staging cases and therapeutic monitoring with immediate multidisciplinary team access. The Northeast corridor and California dominate this channel through established nuclear medicine departments and NRC agreement state licensing density.
- Mobile Services:Leased trailer-mounted PET-CT units rotate through rural markets and small community hospitals below fixed scanner viability thresholds. The Mountain West and Upper Midwest rely on this model where population dispersion defeats capital recovery calculations for permanent installation.
- Home Care:Patient-administered radiopharmaceutical protocols and remote monitoring applications remain investigational for prostate cancer diagnostics.
- Telemedicine:Teleradiology interpretation of molecular imaging studies enables subspecialist coverage for community sites lacking on-site nuclear medicine expertise.
Fixed infrastructure dominates current placement; mobile services are expanding most quickly as vendor fleet deployment models mature and rural access mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed urban cores are concentrating radiopharmaceutical manufacturing investment through IRA tax credits, anchoring production clusters in Ohio River Valley and Southeast corridors where land costs and regulatory density favor capital-intensive isotope facilities.
Northeast Corridor
Academic medical centers in Boston and New York Metro drive PSMA PET procedure volume through NIH-funded clinical trial portfolios and established nuclear medicine residency pipelines. FDA breakthrough device designations accelerate novel radiopharmaceutical access for participating institutions. Philadelphia anchors theranostic pairing adoption with integrated lutetium-177 therapy and diagnostic imaging workflows.
California
Silicon Valley AI quantification tools compress radiologist interpretation time for community hospital networks adopting PSMA PET. CMS national coverage determinations for prostate cancer staging procedures expand Medicare Advantage reimbursement in Los Angeles and San Francisco metropolitan statistical areas. Stanford and UCSF medical centers validate next-generation small molecule ligands through expanded access programs.
Texas
Freestanding oncology clinics in Dallas-Fort Worth and Houston deploy fixed PET-CT systems without certificate-of-need restrictions, capturing referral volume from independent urology practices. NRC agreement state licensing enables faster radioactive materials permitting for multi-site health system expansion. San Antonio's military medical complex drives veteran-specific prostate cancer screening protocols.
Florida
Direct-to-consumer prostate health screening programs fragment traditional hospital-based imaging capture in Miami and Tampa markets. Cash-pay PSMA PET packages attract patients with rising PSA levels outside established urologist relationships. Mobile PET-CT services penetrate the Panhandle and rural Gulf Coast where fixed scanner density remains below national averages.
Mountain West
Leased trailer-mounted PET-CT units rotate through Colorado, Utah, and Arizona markets below permanent installation viability thresholds. Molybdenum-99 supply chain vulnerabilities from aging Canadian reactors sustain technetium-99m bone scintigraphy in rural health systems. Phoenix anchors regional radiopharmaceutical distribution through centralized gallium-68 generator deployment.
US Prostate Cancer Nuclear Medicine Diagnostics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated radiopharmaceutical developers controlling proprietary isotope supply chains while independent imaging service providers compete on scheduling accessibility. The vendor base concentrates around three strategic archetypes: theranostic platform developers pairing diagnostics with alpha-emitter therapies, radiopharmaceutical contract manufacturers scaling gallium-68 and fluorine-18 production, and imaging center operators capturing outpatient procedure volume through urology practice integration. Dominant competitive moves include backward integration into cyclotron infrastructure and strategic partnerships securing NRC licensing across multiple agreement states.
Within the theranostic platform tier, Telix Pharmaceuticals Limited and Blue Earth Diagnostics exemplify developers advancing PSMA-targeted radioligands through FDA regulatory pathways. Lantheus occupies a position among contract manufacturing specialists leveraging radiopharmaceutical production infrastructure to supply major academic medical centers. These three companies represent distinct competitive vectors: therapeutic diagnostics convergence, specialized PET imaging agent development, and manufacturing scale deployment.
| Leading Market Players |
|---|
| Blue Earth Diagnostics |
| Lantheus |
| Cardinal Health |
| Telix Pharmaceuticals Limited |
| NCM-USA LLC |
| Jubilant Draximage Radiopharmacies, Inc. |
| Siemens Healthcare Private Limited |
| CURIUM PHARMA |
| PETNET Solutions, Inc. |
| Others |
Pricing and Supply Chain Analysis
Molybdenum-99 reactor maintenance cycles cascade through technetium-99m pricing tiers, compressing margins for bone scintigraphy agents in rural health systems while gallium-68 generator reliability commands premium positioning in metropolitan hospital networks.
Pricing Analysis
Same-day scanning availability drives premium pricing for gallium-68 PSMA radiotracers against fluorine-18 alternatives requiring cyclotron proximity and longer production lead times. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center contracts with guaranteed volume commitments from spot purchases by independent imaging centers and cash-pay patient packages. Cost compression in technetium-99m bone scintigraphy is intensifying because molybdenum-99 supply volatility from aging Canadian reactors forces inventory carrying cost absorption. Community hospital networks exhibit highest price sensitivity due to constrained capital budgets and Medicare reimbursement rate dependency.
Supply Chain Analysis
Radiochemist residency program output in the Ohio River Valley and Southeast corridors constrains gallium-68 and fluorine-18 labeling capacity expansion despite IRA tax credit attraction. Isotope production concentrates in Canada, the Netherlands, and South Africa for molybdenum-99; domestic cyclotron infrastructure in California, Texas, and Massachusetts anchors fluorine-18 supply. Raw material dependencies rest on enriched uranium targets, specialized chemical precursors for PSMA ligand synthesis, and helium-3 for neutron detection systems. Single-source vulnerability from the NRU reactor closure legacy creates acute disruption risk for technetium-99m distribution. Distribution runs through centralized radiopharmacy networks serving hospital systems, with mobile generator deployment penetrating Mountain West markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PSMA PET imaging is displacing conventional bone scintigraphy as the staging standard, compressing the diagnostic window from biochemical recurrence detection to treatment initiation and reshaping capital allocation across urologic oncology workflows.
For Market Incumbents: Hedge cyclotron infrastructure concentration risk by securing gallium-68 generator supply agreements with multiple contract manufacturers across NRC agreement states. Fortify position through backward integration into radiopharmaceutical production capacity in the Ohio River Valley, leveraging IRA domestic manufacturing incentives to capture cost advantages against spot-market isotope purchasers facing molybdenum-99 volatility. For New Entrants and Emerging Players: Direct-to-consumer digital health platforms offer the lowest barrier entry path, enabling cash-pay PSMA PET package marketing to patients with rising PSA levels outside established urology referral networks. Target the Mountain West and Upper Midwest mobile PET-CT service gaps where fixed scanner density remains below viability thresholds for hospital-based competitors. Partner with independent urology practices for vertical imaging asset integration rather than competing head-to-head with academic medical center radiology departments. For Investors and Strategic Acquirers: Distressed-cycle entries favor radiopharmaceutical contract manufacturers with NRC licensing breadth across multiple agreement states in the Southeast and Texas corridors. Long-term viability centers on theranostic platform convergence, where diagnostic imaging pull-through from lutetium-177 alpha-emitter therapy demand creates recurring revenue streams. Watch FDA breakthrough device designation velocity for next-generation small molecule PSMA ligands as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS national coverage determination navigation accelerates Medicare Advantage access for community oncology networks. |
| Manufacturing Scale-Up | Gallium-68 generator infrastructure deployment eliminates cold-chain constraints and enables same-day scanning protocols. |
| Regulatory Approval Pathway | FDA breakthrough device designation compresses novel radiopharmaceutical review timelines for prostate cancer indications. |
| Hospital System Partnership | Academic medical center alliances secure captive referral volume and NIH-funded clinical trial participation. |
| Pipeline Diversification | Lutetium-177 theranostic pairing expands from diagnostic staging into therapeutic monitoring and response assessment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with nuclear medicine department heads, radiopharmacy operations directors, urology practice administrators, and CMS reimbursement policy specialists. FDA New Drug Application databases, NRC radioactive materials licensing records, hospital procurement databases, and GPO contract repositories provided procedure volume and pricing benchmarks. Bottom-up installation counts for PET-CT systems and top-down radiopharmaceutical production estimates were triangulated against Medicare claims data.
Segmentation dimensions were modeled at the product-type level for PSMA PET versus bone scintigraphy modality splits, at the technology level for hybrid imaging capital deployment versus consumable radiopharmaceutical flows, and at the end-user level for hospital-based versus freestanding oncology clinic site-of-care economics. CAGRs were derived from procedure volume growth trajectories and reimbursement rate evolution across the projection horizon. Forecast inputs incorporated gallium-68 generator installation curves, cyclotron infrastructure investment pipelines, and NRC agreement state licensing expansion patterns.
The model holds under stable CMS national coverage determination continuity and molybdenum-99 supply chain baseline reliability; deviation in FDA regulatory timelines or Canadian reactor unplanned outages would shift radiopharmaceutical availability assumptions and pricing tier stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Rapid Oral Fluid Screening Device Market