
 South Africa in-Vitro Diagnostics Market | 2026-2036
South Africa in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa in-Vitro Diagnostics Market Analytics
South Africa is fragmenting as a procurement geography, with provincial health departments and private hospital groups operating on divergent tender timelines and technical specifications. Siemens Healthineers anchors the high-end imaging-integrated diagnostics segment through its installed base in tertiary facilities. Abbott Laboratories competes aggressively in point-of-care immunoassays, leveraging its Alere acquisition infrastructure to reach clinic-level buyers. Bio-Rad Laboratories specializes in quality control materials and reference standards that laboratories require for ISO 15189 accreditation compliance.
In-vitro diagnostics encompasses reagents, instruments, and analytical systems used to detect diseases, conditions, or infections in specimens taken from the human body, typically operating through biochemical, immunological, or nucleic acid amplification methods with sensitivity thresholds measured in picograms per milliliter. These technologies serve clinical decision-making by enabling screening, diagnosis, patient monitoring, and treatment selection across acute and chronic care pathways. Molecular diagnostics represents the fastest-growing application segment, driven by PCR and sequencing demand for HIV viral load monitoring and tuberculosis drug-resistance profiling. Reagents capture the largest revenue pool due to recurring consumption tied to instrument installed bases, while software segments remain nascent but gain traction where laboratories seek LIS integration and automated result reporting.
SAHPRA regulates all in-vitro diagnostic devices under the Medicines and Related Substances Act, requiring conformity assessment evidence that increasingly references CE marking or FDA 510(k) clearance as acceptable equivalence. The South African Bureau of Standards (SBS) and National Health Laboratory Service (NHLS) additionally shape procurement through technical specifications embedded in public sector tenders. Stakeholders must monitor SAHPRA's transition toward risk-based classification rules for IVDs, as this will reshape registration timelines and distributor qualification requirements for new market entrants.
Market Dynamics
SAHPRA's tightening quality standards for imported diagnostic kits are fragmenting procurement geography across South Africa's nine provinces, forcing distributors to abandon uncertified suppliers and requalify CE-IVD and FDA-cleared alternatives.
Growth Catalysts
- HIV viral load monitoring protocols:The NHLS mandates PCR-based HIV viral load testing for treatment optimization, driving sustained reagent consumption through public hospital networks.
- ISO 15189 accreditation pressure:Private laboratory chains seeking international accreditation must procure quality control materials and reference standards, expanding the addressable market for specialized consumables.
- Gauteng province density:Johannesburg and Pretoria host South Africa's densest clusters of academic medical centers and private laboratory chains, concentrating demand for high-throughput analytical systems.
Market Restraints
- Import dependency for reagents:Over 70% of diagnostic reagents originate from European and North American manufacturers, exposing distributors to currency volatility and extended lead times.
- CE-IVD clearance as de facto barrier:SAHPRA's acceptance of CE marking as conformity evidence excludes uncertified manufacturers, limiting supplier base expansion and price competition.
- Limited local instrument manufacturing:South Africa lacks domestic production of molecular diagnostic platforms, forcing capital outflow for instrument procurement and maintenance contracts.
Strategic Opportunities
- KwaZulu-Natal expansion:Durban's underserved private healthcare infrastructure presents whitespace for point-of-care immunoassay deployment in clinic-level settings.
- Tuberculosis drug-resistance profiling:Sequencing-based resistance testing for multidrug-resistant TB strains remains underpenetrated relative to HIV molecular diagnostics.
- Laboratory Information System integration:NHLS digitalization initiatives create demand for middleware connecting analytical instruments to centralized reporting platforms.
Industry Challenges
- Biomedical engineering skill scarcity:Maintenance and calibration of PCR and sequencing platforms requires specialized technicians, with training programs failing to match instrument deployment rates.
- SAHPRA registration timeline variability:Risk-based classification transition creates uncertainty for new market entrants regarding documentation requirements and distributor qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa in-Vitro Diagnostics Market |
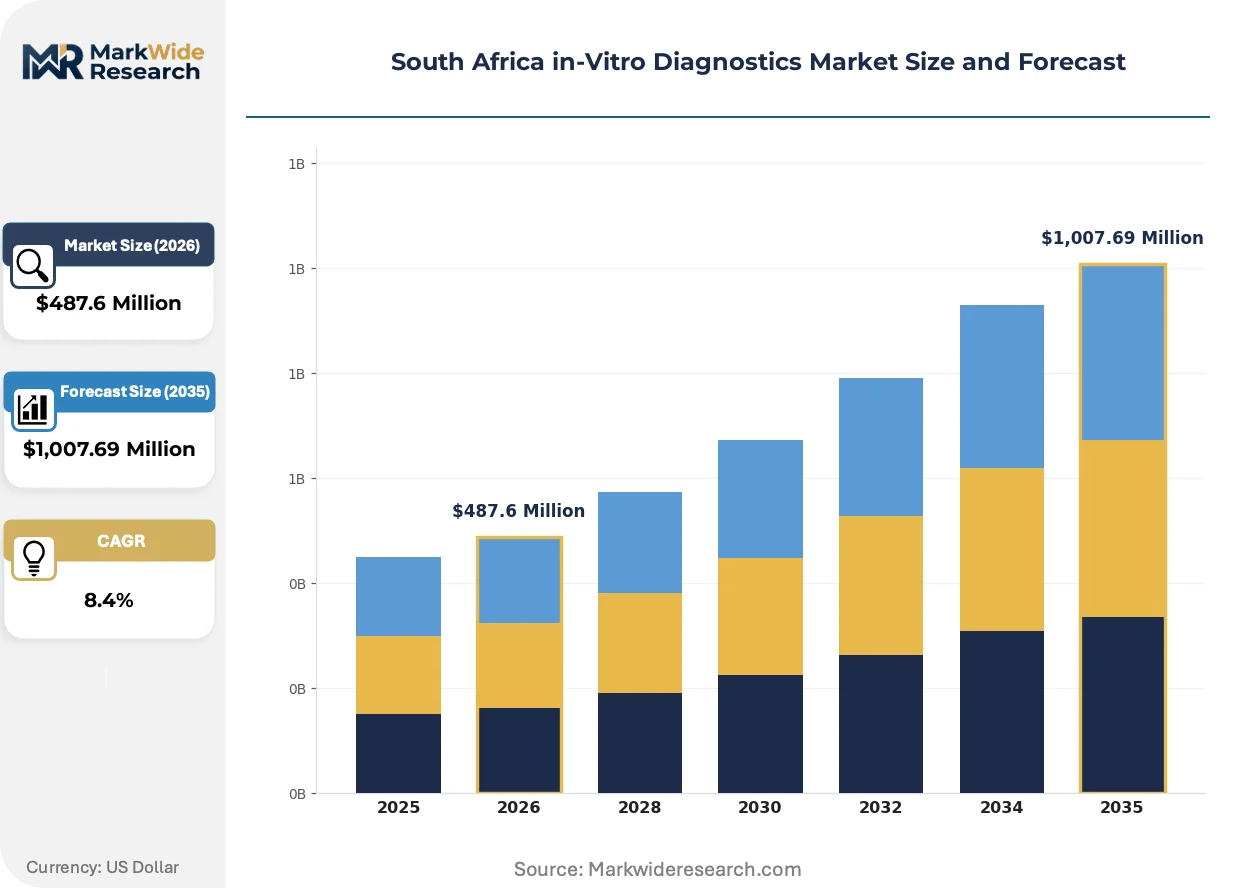
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Control Materials Application: Clinical Chemistry, Immunoassays, Microbiology, Molecular Diagnostics End User: Hospitals, Laboratories, Blood Banks, Research Institutes Technology: ELISA, PCR, Flow Cytometry, Sequencing |
| Companies Covered | Siemens Healthineers, Abbott Laboratories, F. Hoffmann-La Roche Ltd, Danaher Corporation, Thermo Fisher Scientific, Becton, Dickinson and Company, Bio-Rad Laboratories, bioMérieux SA, Sysmex Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa in-Vitro Diagnostics Market Evolving Landscape
Molecular diagnostics is hybridizing with imaging-integrated workflows, while provincial procurement fragmentation and quality-control-driven purchasing reshape competitive positioning across South Africa's public and private laboratory segments.
Multiplex PCR panels for simultaneous HIV, TB, and hepatitis detection are hybridizing with automated nucleic acid extraction platforms. Academic medical centers in Johannesburg are adopting these integrated systems to compress turnaround times for infectious disease screening. The technology is hybridizing previously separate testing workflows, reducing manual handling steps and enabling same-day result reporting for complex co-infection cases.
SAHPRA's transition toward risk-based IVD classification rules is compressing registration timelines for low-risk devices while extending documentation requirements for high-complexity molecular platforms. Distributors must now stratify portfolio management strategies, prioritizing CE-IVD-cleared instruments with established clinical evidence packages. Private laboratory chains are responding by consolidating supplier relationships with manufacturers possessing robust regulatory affairs capabilities.
Centralized tendering through provincial health departments is displacing hospital-level purchasing autonomy for reagent procurement. The Western Cape and Gauteng health departments now negotiate multi-year framework agreements directly with manufacturers, bypassing traditional distributor markups for high-volume consumables. This concentration is most visible in the NHLS network, where standardized test menus and automated ordering systems reduce laboratory-level discretion over supplier selection.
South Africa in-Vitro Diagnostics Market Segmentation
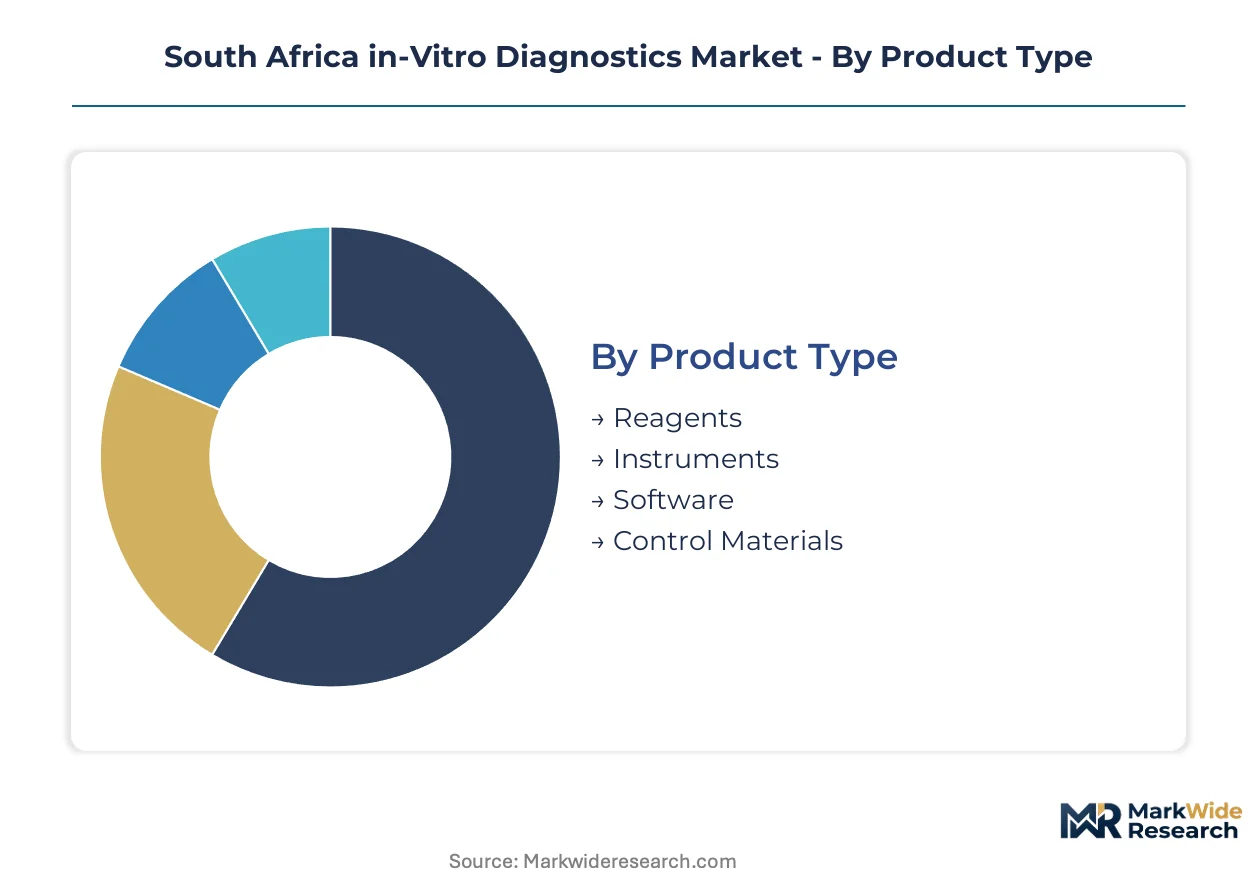
IVD market segmentation in South Africa tracks procurement cycles that range from daily reagent replenishment to multi-year instrument amortization. Understanding these velocity differentials helps distributors align inventory financing with provincial tender schedules and private laboratory capital expenditure patterns.
Product Type:
Reagents turn over fastest with weekly replenishment cycles, while instruments anchor the longest procurement timelines stretching across capital budget cycles.
- Reagents:Consumable biochemical and immunological formulations consumed per test with picogram-per-milliliter sensitivity thresholds. NHLS public hospital networks in Gauteng province drive bulk purchasing through centralized tender frameworks, with HIV viral load PCR kits representing the highest-volume category.
- Instruments:Analytical platforms including PCR thermal cyclers, automated immunoassay systems, and flow cytometers requiring SAHPRA registration and ISO 15189 alignment. Academic medical centers in Johannesburg and Pretoria concentrate demand for high-throughput systems capable of processing thousands of samples daily.
- Software:Laboratory Information System modules and middleware connecting instruments to centralized reporting platforms.
- Control Materials:Reference standards and quality control substances required for accreditation compliance.
Reagents anchors the volume base while software gains share at the steepest rate.
Application:
Cost tiers separate commodity testing from premium molecular profiling, with reimbursement differentials shaping procurement authority distribution between public and private channels.
- Clinical Chemistry:Routine biochemistry panels for metabolic and organ function assessment using spectrophotometric methods. Private laboratory chains in Gauteng deploy high-throughput analyzers for glucose, lipid, and liver enzyme testing.
- Molecular Diagnostics:Nucleic acid amplification and sequencing for pathogen detection and resistance profiling. NHLS mandates PCR-based HIV viral load monitoring across public hospital networks, sustaining reagent consumption at scale.
- Immunoassays:Antibody and antigen detection through chemiluminescence and ELISA platforms.
- Microbiology:Culture-based and rapid pathogen identification for antimicrobial susceptibility testing.
Clinical Chemistry generates the highest test volumes while molecular diagnostics commands the steepest expansion trajectory.
End User:
Customer type determines specification stringency, with blood banks and research institutes imposing distinct technical requirements compared to routine clinical settings.
- Hospitals:Tertiary and district facilities combining emergency diagnostics with chronic disease monitoring. Public hospital networks in KwaZulu-Natal are expanding point-of-care testing capabilities for infectious disease screening.
- Laboratories:Private chains and NHLS-affiliated facilities processing high sample volumes under accreditation pressure. ISO 15189 compliance drives quality control material procurement across Gauteng and Western Cape provinces.
- Blood Banks:Transfusion services requiring serological and nucleic acid testing for donor screening.
- Research Institutes:Academic and epidemiological facilities conducting drug-resistance surveillance and assay validation.
Laboratories anchor the volume base while blood banks gain share at the steepest rate.
Technology:
Technology maturity separates established platforms with standardized protocols from emerging methods facing SAHPRA registration uncertainty.
- PCR:Polymerase chain reaction platforms for nucleic acid amplification with established HIV and TB diagnostic protocols. NHLS standardization across nine provinces creates predictable demand for thermal cyclers and extraction automation.
- Sequencing:Next-generation and Sanger methods for drug-resistance mutation profiling. Academic medical centers in Johannesburg are adopting targeted sequencing for multidrug-resistant tuberculosis strain identification.
- ELISA:Enzyme-linked immunosorbent assay for antibody and antigen detection in serological screening.
- Flow Cytometry:Cell sorting and immunophenotyping platforms for hematological malignancy assessment.
PCR anchors the volume base while sequencing gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAHPRA anchors regulatory harmonization across South Africa's nine provinces, with provincial health departments operating divergent procurement frameworks that reshape distributor qualification requirements and tender participation rules.
Gauteng
Johannesburg and Pretoria host the densest clusters of academic medical centers and private laboratory chains. The Gauteng Department of Health negotiates multi-year framework agreements directly with manufacturers for NHLS network reagents. High-throughput PCR and sequencing platforms concentrate in tertiary facilities across the Johannesburg-Pretoria corridor.
KwaZulu-Natal
Durban's private healthcare infrastructure remains underserved relative to Gauteng, creating whitespace for point-of-care immunoassay deployment. The KwaZulu-Natal Department of Health is expanding infectious disease screening protocols through public hospital networks. Clinic-level buyers in eThekwini municipality drive demand for portable diagnostic systems.
Western Cape
Cape Town anchors the province's laboratory accreditation pressure, with ISO 15189 compliance driving quality control material procurement. The Western Cape Health Department centralizes tendering for high-volume consumables, bypassing traditional distributor markups. Academic medical centers in the city adopt multiplex PCR panels for HIV-TB co-infection screening.
Eastern Cape
Port Elizabeth and East London district hospitals face biomedical engineering skill scarcity for PCR platform maintenance. The Eastern Cape Department of Health relies on NHLS-affiliated laboratories for molecular diagnostics outsourcing. Rural facility networks concentrate demand for simplified point-of-care testing workflows.
South Africa in-Vitro Diagnostics Market Competitive Landscape
Capability concentration sits with full-system integrators; scale advantage sits with reagent specialists with recurring revenue models. The vendor base stratifies across three tiers: multinational conglomerates with imaging-integrated diagnostics portfolios, point-of-care specialists leveraging clinic-level distribution, and quality control material providers serving accreditation-driven private chains. Dominant competitive moves include strategic partnerships with provincial health departments for framework agreement positioning, and portfolio diversification into multiplex infectious disease panels.
Among the multinational tier, Siemens Healthineers and Abbott Laboratories exemplify divergent positioning archetypes. Siemens Healthineers occupies the high-end imaging-integrated diagnostics segment through tertiary facility installed bases. Abbott Laboratories sits within the point-of-care immunoassay tier, leveraging clinic-level reach. Bio-Rad Laboratories represents the specialized quality control archetype, anchoring ISO 15189 compliance demand.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories |
| bioMérieux SA |
| Sysmex Corporation |
| Others |
Value Network & Pricing Analysis
CE-IVD clearance bottlenecks at SAHPRA determine both pricing tier spreads and supply chain shape, compressing margins for uncertified distributors while concentrating procurement authority with manufacturers possessing established regulatory dossiers. Currency volatility against the Rand amplifies these effects, forcing distributors to hedge reagent imports or absorb exchange-driven cost swings.
Pricing Analysis
Gauteng province commands pricing premiums of 15-25% above Eastern Cape benchmarks, reflecting concentration of academic medical centers and private laboratory chains with less price-sensitive procurement committees. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15189-accredited facilities from district hospitals and clinic-level buyers. Pricing pressure stems from NHLS framework agreements that bypass traditional distributor markups for high-volume HIV viral load reagents. Private laboratory chains exhibit lowest price sensitivity due to accreditation-driven quality requirements, while rural district hospitals face severe budget constraints.
Supply Chain Analysis
Export-control restrictions on nucleic acid amplification technologies limit flows from US and EU manufacturers to South African distributors, extending lead times for PCR thermal cyclers and sequencing platforms. Diagnostic reagents originate predominantly from Germany, the United States, and Singapore, with specialized enzymes and fluorescent probes sourced from Switzerland and Japan. Supply chain risk centers on single-source dependency for HIV viral load PCR kits, where NHLS standardization locks in manufacturer-specific reagent formats. Distribution runs through authorized distributor networks with SAHPRA-registered import licenses, bypassing direct manufacturer-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's in-vitro diagnostics market sits in early-cycle recovery, with NHLS digitalization and provincial framework agreement expansion driving capital deployment back toward molecular platform upgrades.
For Market Incumbents: Build switching-cost moats through LIS integration and multi-year service contracts that embed instruments within NHLS network infrastructure. Siemens Healthineers and Abbott Laboratories should deepen backward integration into reagent manufacturing to offset currency exposure, while consolidating distributor relationships ahead of SAHPRA's risk-based classification transition. Threat vectors include emerging point-of-care specialists and provincial tender consolidation that disintermediates traditional channel partners. For New Entrants and Emerging Players: Build out KwaZulu-Natal's clinic-level immunoassay whitespace before Gauteng saturation intensifies, targeting Durban's underserved private healthcare infrastructure with portable diagnostic systems. Tuberculosis drug-resistance profiling remains underpenetrated relative to HIV molecular diagnostics, offering a beachhead for sequencing-based resistance testing platforms. Go-to-market execution should prioritize direct engagement with KwaZulu-Natal Department of Health infectious disease screening expansion programs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors quality-control material specialists and LIS middleware providers over capital-intensive instrument manufacturers. Long-term viability over the next decade hinges on regulatory affairs capabilities and provincial framework agreement positioning. Acquisition targets should demonstrate established SAHPRA registration pathways and NHLS network penetration. Watch SAHPRA risk-based classification implementation timelines as the critical inflection signal for distributor qualification requirements and new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Accelerates SAHPRA registration timelines for molecular diagnostic platforms entering the NHLS network. |
| Hospital System Partnership | Locks in reagent consumption through multi-year framework agreements with Gauteng and Western Cape health departments. |
| Software Companion Development | Enables LIS integration that reduces laboratory-level discretion over supplier selection in NHLS-affiliated facilities. |
| Reimbursement Strategy | Aligns test menu pricing with National Health Insurance benefit schedules under South Africa's healthcare financing reform. |
| Quality Control Material Expansion | Captures ISO 15189 accreditation-driven demand from private laboratory chains in Cape Town and Johannesburg. |
Research Methodology
The analysis maps molecular diagnostics, immunoassays, clinical chemistry, and microbiology segments, each validated through biomedical engineers, NHLS procurement officers, private laboratory chain directors, and SAHPRA regulatory affairs specialists. Primary fieldwork combined structured interviews with secondary validation against SAHPRA registration databases, NHLS tender documentation, ISO 15189 accreditation records, and provincial health department framework agreements. Bottom-up instrument and reagent volume estimates triangulated against top-down market sizing derived from import customs data and distributor revenue disclosures.
Assumptions held SAHPRA's acceptance of CE-IVD and FDA clearance as conformity evidence constant across the projection horizon, while varying provincial tender consolidation rates and NHLS digitalization timelines. Segmentation dimensions modeled include product type, application, technology platform, and end-user facility tier. CAGRs derived from regression analysis of historical procurement volumes against HIV viral load testing protocol expansion and tuberculosis resistance profiling adoption curves. Forecast inputs incorporated PCR thermal cycler deployment rates and sequencing platform penetration in academic medical centers.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by multinational conglomerates or disruptive point-of-care entrants would shift outcomes beyond modeled ranges. Material shifts in SAHPRA risk-based classification implementation schedules, Rand volatility against Euro and Dollar benchmarks, or NHLS network restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Elisa Tests Market
Diagnostics
Semen Analysis Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Antigen Kit Market
Diagnostics
Rapid Plasma Reagin Test Market