
 Asia-Pacific Radioimmunoassay Market | 2026-2036
Asia-Pacific Radioimmunoassay Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Radioimmunoassay Market Outlook
Hospital laboratories are reorganizing procurement priorities around automated radioimmunoassay platforms, while research institutions cede share to high-throughput diagnostic buyers. Merck KGaA leverages its reagent manufacturing scale to anchor supply contracts across Japanese university hospitals. Beckman Coulter, Inc. competes through analyzer integration with existing immunoassay workflows in Australian pathology networks. EUROIMMUN Medizinische Labordiagnostika AG specializes in autoimmune endocrine panels that differentiate its kit portfolio from commodity hormone assays.
Radioimmunoassay is a competitive binding technique that quantifies antigen concentration through displacement of radiolabeled ligands from high-affinity antibodies, typically employing iodine-125 tracers with detection sensitivity reaching picomolar ranges; the method serves as a gold-standard reference for peptide hormone and tumor marker quantification in clinical and research settings. Reagents and kits capture the dominant margin pool due to recurring consumable demand, while analyzers face slower replacement cycles. Clinical diagnostics leads application volume, though therapeutic monitoring for biologics represents the fastest-expanding use case as monoclonal antibody therapies proliferate across Asia-Pacific markets.
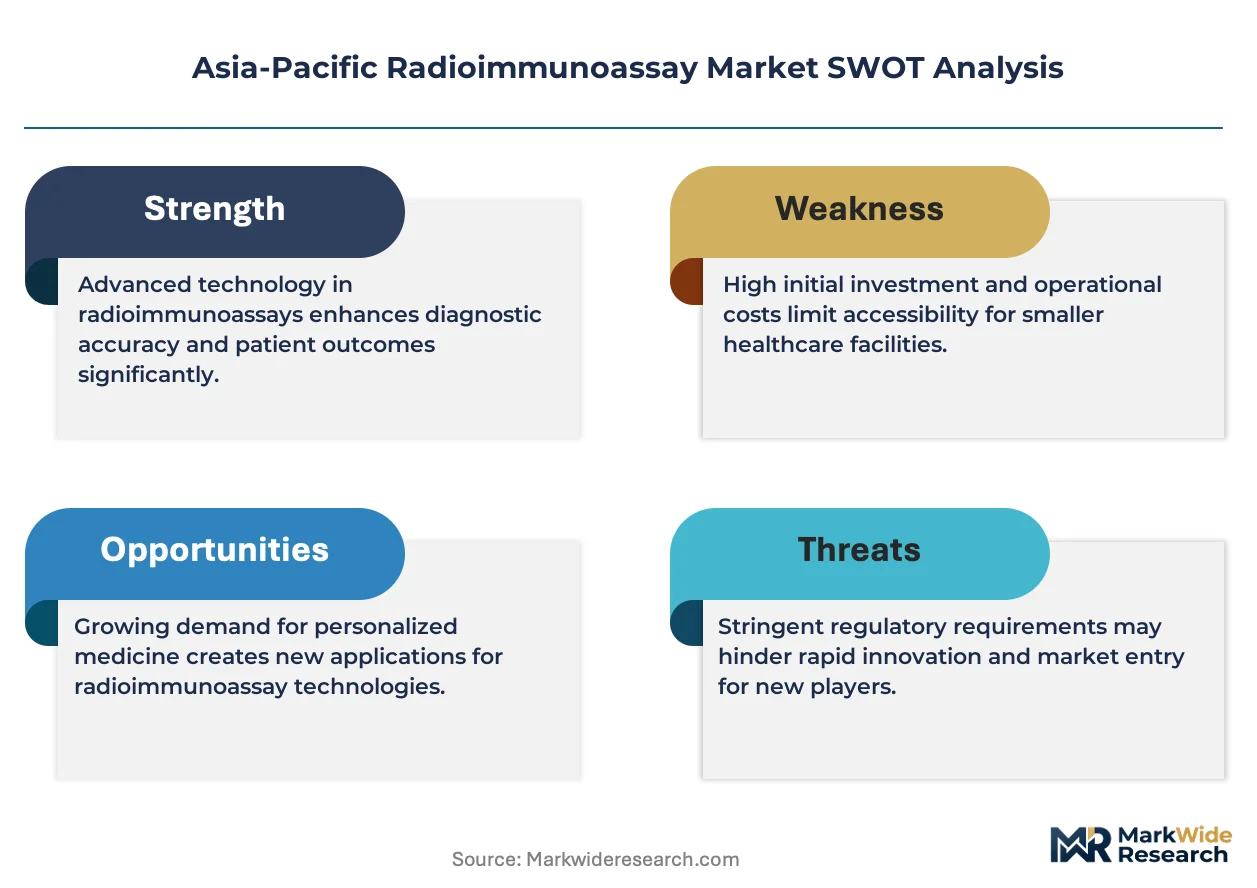
Japan's PMDA enforces stringent radioisotope handling licensure that shapes facility investment thresholds, while Australia's TGA aligns IVD performance standards with EU MDR equivalence pathways. India's CDSCO registration mandates for imported diagnostic kits are forcing distributors to establish local technical documentation capabilities. Stakeholders must weigh automation capital commitments against the regulatory cost of maintaining multi-country isotope permits as non-radioactive substitute technologies mature.
Market Dynamics
Centralized laboratory automation across China's tier-one hospital networks is compressing procurement timelines and forcing reagent suppliers to integrate with existing immunoassay workflows, while India's CDSCO registration mandates reshape distributor capabilities.
Growth Catalysts
- CDSCO Registration Mandates:India's tightened in-vitro diagnostic requirements push clinical laboratories toward validated assay platforms, filtering out unstandardized imports and consolidating procurement around certified reagent suppliers.
- Endocrine Testing Expansion:Southeast Asian clinical diagnostic laboratories are scaling RIA-based hormone panels, driven by rising diabetes and thyroid disorder prevalence in urban populations.
- Iodine-125 Tracer Sensitivity:Picomolar detection thresholds maintain radioimmunoassay as the gold-standard reference method for peptide hormones, preserving its position against chemiluminescence alternatives in reference laboratories.
Market Restraints
- Radioisotope Handling Licensure:Japan's PMDA enforces stringent facility certification thresholds that elevate capital requirements for new laboratory entrants, constraining market expansion beyond established hospital networks.
- Non-Radioactive Substitute Maturation:Chemiluminescence immunoassay platforms from European and North American manufacturers are capturing routine hormone testing volumes in Australian and South Korean tertiary hospitals.
- Reagent Import Dependency:Specialized antibody and tracer production concentrates in Japanese and European supply bases, exposing Asia-Pacific distributors to currency volatility and extended lead times.
Strategic Opportunities
- Therapeutic Monitoring for Biologics:Monoclonal antibody therapy expansion across Asia-Pacific markets creates demand for pharmacokinetic RIA panels in oncology and autoimmune treatment centers.
- TGA-Aligned Pathway Leverage:Australia's equivalence recognition with EU MDR performance standards enables streamlined kit registration for manufacturers already certified under European frameworks.
- Tier-Two Hospital Penetration:China's provincial hospital networks outside Beijing, Shanghai, and Guangzhou remain underpenetrated for automated RIA platforms, offering whitespace for integrated analyzer-reagent contracts.
Industry Challenges
- Multi-Country Isotope Permit Maintenance:Laboratories operating across Japan, Australia, and Southeast Asian jurisdictions face fragmented regulatory compliance costs that erode margin on cross-border service contracts.
- Technician Specialization Scarcity:Radiochemistry expertise required for iodine-125 handling and waste management is concentrating in aging workforce cohorts, constraining laboratory expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Radioimmunoassay Market |
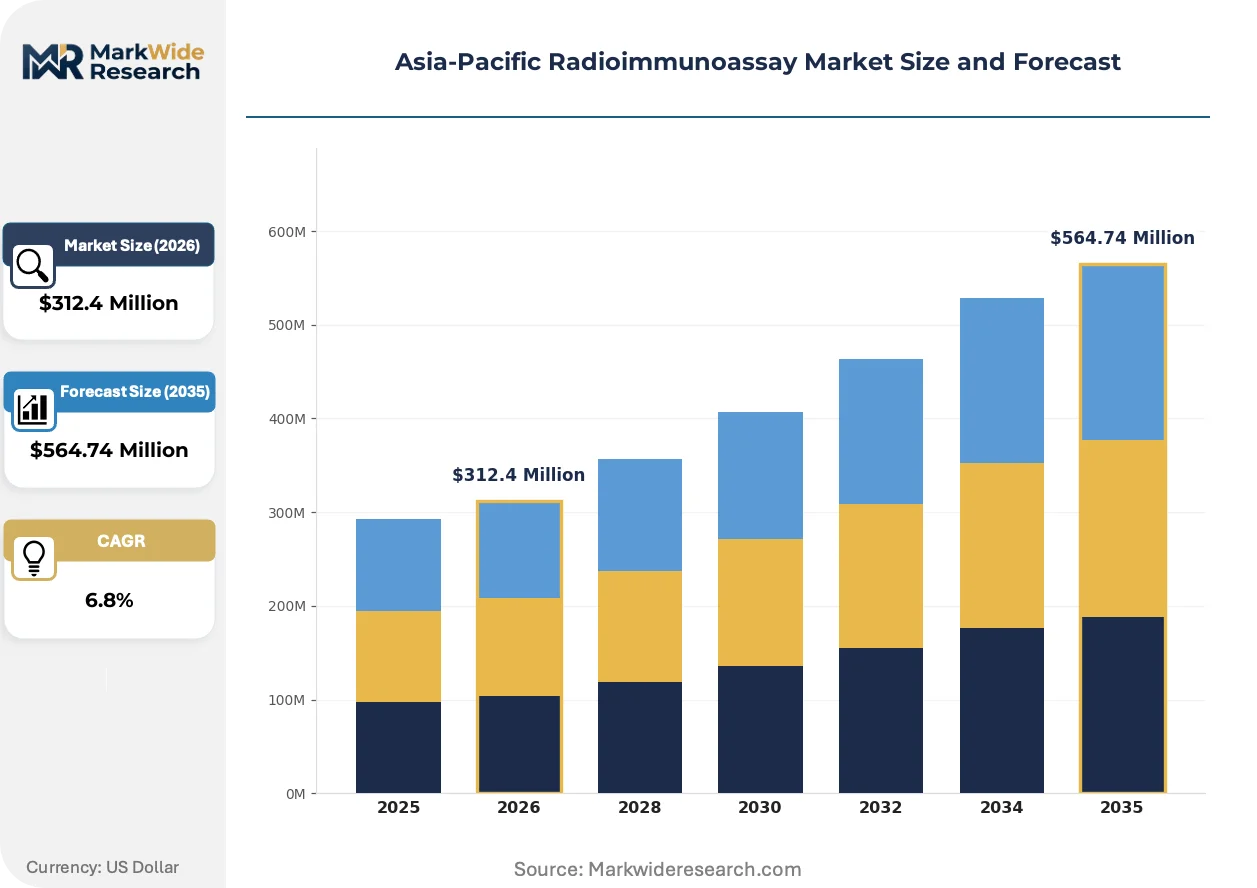
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Analyzers, Detectors Application: Preclinical Testing, Clinical Diagnostics, Drug Discovery, Therapeutic Monitoring End User: Hospitals, Diagnostic Labs, Research Institutions, Pharmaceutical Companies Technology: Radioactive Isotopes, Non-Radioactive Substitutes, Automation, Manual Techniques |
| Companies Covered | Immuno-Biological Laboratories Co., Ltd., Abcam plc, Merck KGaA, MP Biomedicals, Tecan Trading AG, PerkinElmer Inc., Beckman Coulter, Inc., Berthold Technologies GmbH & Co. KG, EUROIMMUN Medizinische Labordiagnostika AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Radioimmunoassay Market Strategic Shifts
Workflow integration pressures and tracer handling constraints are accelerating technology substitution patterns, while regulatory alignment efforts and procurement centralization reshape competitive positioning across the region.
Magnetic bead-based separation systems are supplanting traditional centrifugation and precipitation steps in automated radioimmunoassay platforms. Japanese university hospitals and Australian pathology networks are adopting these systems to reduce hands-on technician time and improve inter-run reproducibility. The shift is compressing assay turnaround times from four hours to under ninety minutes, enabling same-day endocrine reporting in high-volume settings.
PMDA's radioisotope facility licensure requirements are tightening waste handling and personnel training protocols for iodine-125 users. The policy elevates operational compliance costs for independent clinical laboratories while reinforcing competitive moats for hospital-integrated reference centers with captive waste management infrastructure. Tier-one hospital networks in Tokyo and Osaka are consolidating outpatient endocrine testing into centralized nuclear medicine departments to amortize fixed compliance investments.
Reagent rental and cost-per-test contracting models are displacing capital purchase arrangements for analyzer procurement. Chinese provincial health bureaus and Australian public pathology networks are prioritizing vendors offering bundled reagent supply with equipment placement, transferring obsolescence risk to manufacturers. This shift is most pronounced in China's tier-two city hospital clusters, where budget constraints limit upfront automation capital deployment.
Asia-Pacific Radioimmunoassay Market Segmentation
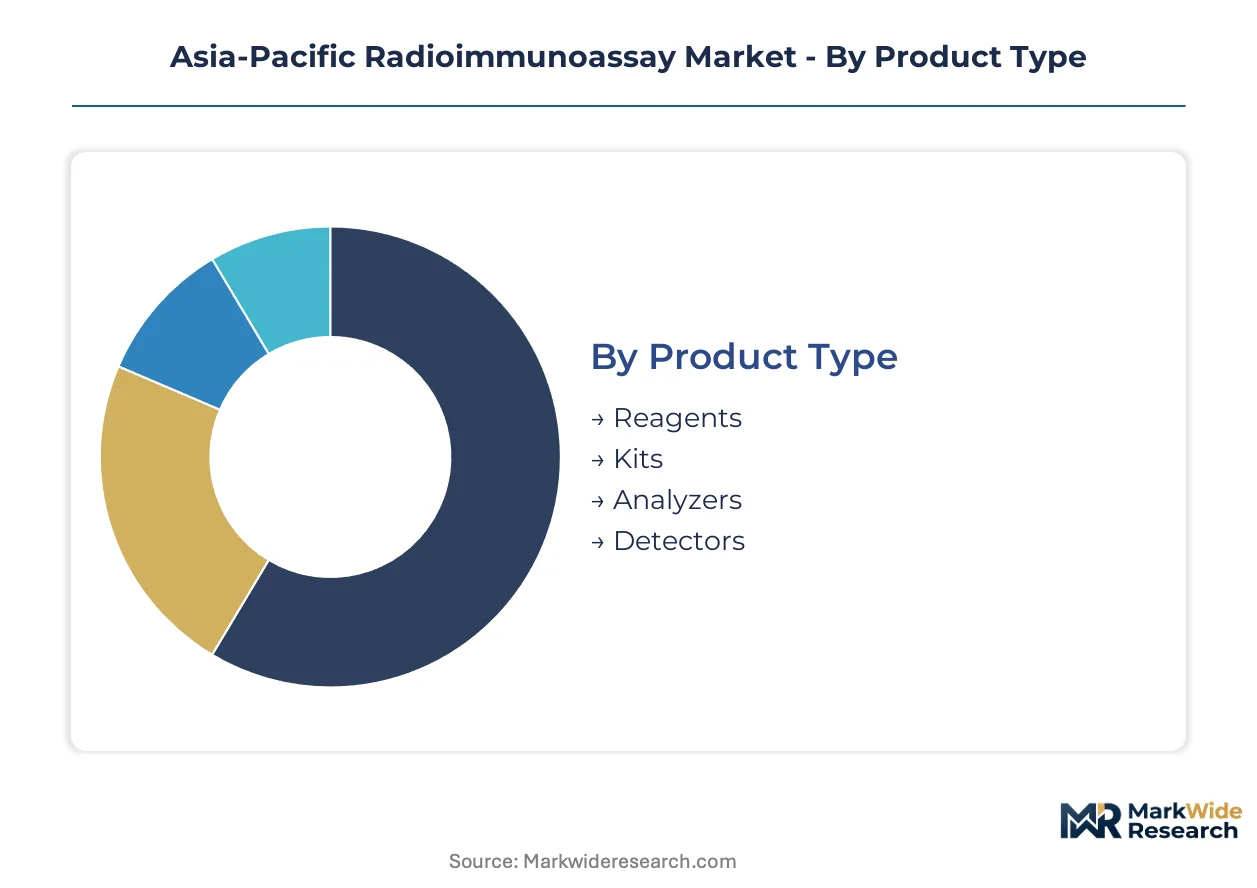
Radioimmunoassay market segmentation reveals where substitution pressure concentrates most intensely. Product categories face divergent fates as automation investments reshape procurement economics across Asia-Pacific hospital networks.
Product Type:
Reagents and kits face the strongest substitution threat from chemiluminescence platforms, while analyzers defend installed-base positions through workflow integration lock-in.
- Reagents:High-affinity antibodies and radiolabeled tracers constitute the recurring consumable base. China's tier-one hospital networks concentrate procurement through centralized laboratory automation contracts, compressing supplier margins.
- Kits:Pre-configured assay panels for thyroid, reproductive, and adrenal hormones dominate routine diagnostic volumes. Australian pathology networks and Japanese university hospitals standardize on validated kit platforms to satisfy PMDA and TGA compliance requirements.
- Analyzers:Automated platforms with magnetic bead separation reduce assay turnaround from four hours to ninety minutes. Replacement cycles extend beyond seven years in budget-constrained Southeast Asian facilities.
- Detectors:Gamma counters and scintillation-based readout systems complete the instrumentation chain. India's CDSCO registration mandates favor integrated analyzer-detector systems over modular configurations.
Reagents anchor the volume base while kits gain share at the steepest rate as laboratories outsource panel configuration to certified manufacturers.
Application:
Cost tier differentiation separates reference-grade validation work from high-throughput routine screening across Asia-Pacific healthcare systems.
- Preclinical Testing:Pharmacokinetic profiling for monoclonal antibody candidates requires picomolar sensitivity. Contract research organizations in Singapore and South Korea expand capacity to serve global pharmaceutical sponsors.
- Clinical Diagnostics:Endocrine panels for diabetes and thyroid disorders generate the highest test volumes. China's provincial health bureaus consolidate outpatient testing into centralized nuclear medicine departments.
- Drug Discovery:Peptide hormone quantification supports target validation and biomarker identification. Japanese pharmaceutical companies maintain captive RIA capabilities despite outsourcing trends.
- Therapeutic Monitoring:Biologics pharmacokinetics represents the most quickly expanding application as monoclonal antibody therapies proliferate across oncology and autoimmune treatment centers.
Clinical diagnostics commands the installed base while therapeutic monitoring climbs the fastest as biologics penetration deepens.
End User:
Customer type determines automation capital availability and regulatory compliance burden distribution across the region.
- Hospitals:Tier-one networks in Tokyo, Shanghai, and Sydney integrate RIA into nuclear medicine departments with captive waste management infrastructure. PMDA radioisotope licensure reinforces competitive moats for hospital-integrated reference centers.
- Diagnostic Labs:Independent clinical laboratories face elevated operational compliance costs under fragmented multi-country permit requirements. Australian public pathology networks prioritize reagent rental models over capital purchase.
- Research Institutions:University hospitals in Japan and Australia adopt magnetic bead-based separation systems to reduce technician hands-on time. Aging radiochemistry workforce constrains expansion timelines.
- Pharmaceutical Companies:In-house bioanalytical groups cede share to specialized contract research organizations as RIA expertise concentrates in external providers.
Hospitals retain the dominant share position while diagnostic labs expand most quickly through reagent rental contracting models.
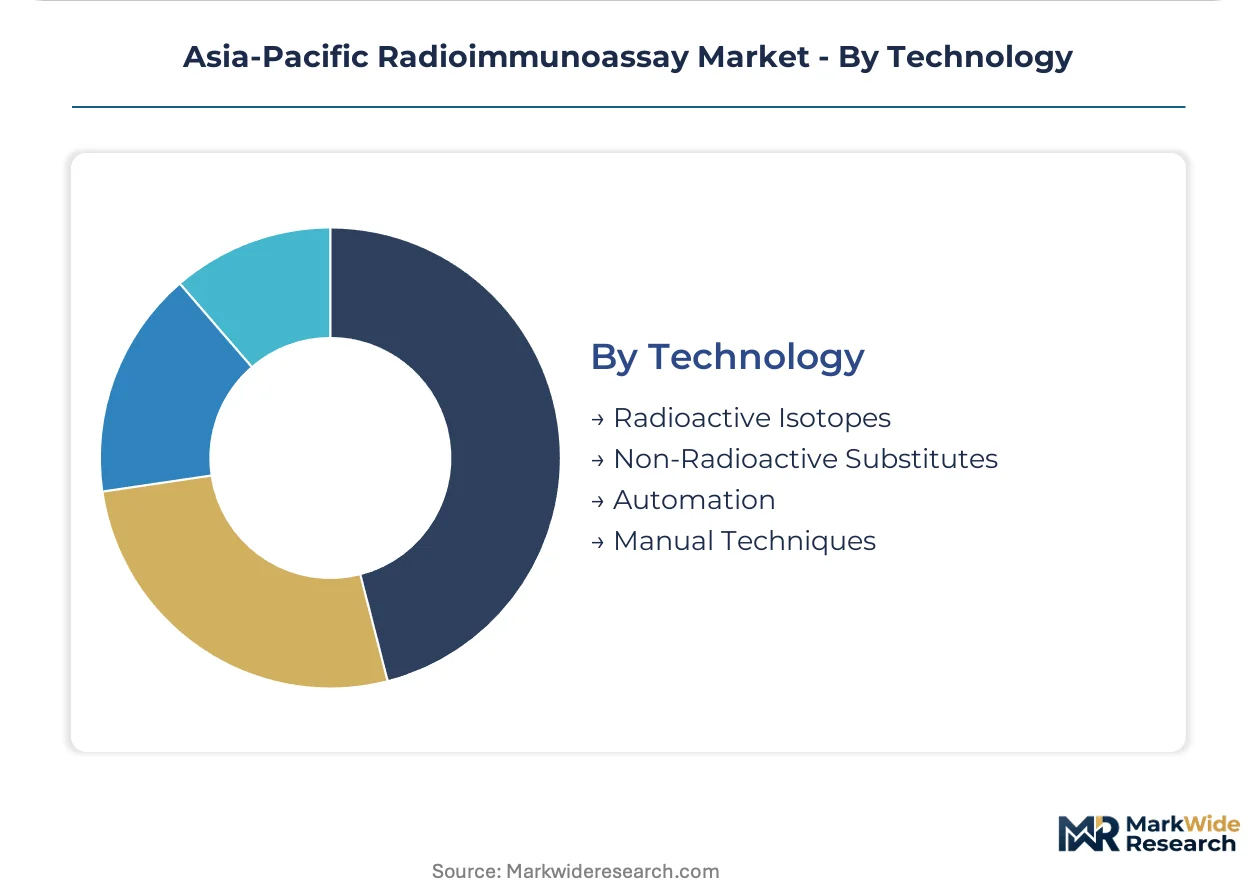
Technology:
Maturity gradients separate established radioactive methods from emerging non-radioactive alternatives in different application tiers.
- Radioactive Isotopes:Iodine-125 tracers maintain gold-standard reference status for peptide hormone quantification. Japan's PMDA enforces stringent facility certification thresholds that constrain new laboratory entrants.
- Non-Radioactive Substitutes:Chemiluminescence immunoassay platforms capture routine hormone testing volumes in Australian and South Korean tertiary hospitals. Sensitivity gaps persist for picomolar-range applications.
- Automation:Integrated analyzer-reagent workflows compress turnaround times and improve inter-run reproducibility. Chinese tier-two city hospital clusters prioritize bundled supply contracts over upfront capital deployment.
- Manual Techniques:Precipitation and centrifugation methods persist in resource-limited Southeast Asian settings with lower test volumes. Technician specialization scarcity accelerates substitution pressure.
Radioactive isotopes defend the reference-tier position while automation gains share fastest through procurement centralization in Chinese hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese reagent manufacturers supply centralized laboratory networks across China and Southeast Asia, while Australian distributors bridge European kit certifications into Asia-Pacific hospital procurement channels.
China
Tier-one hospital networks in Beijing, Shanghai, and Guangzhou are consolidating outpatient endocrine testing into centralized nuclear medicine departments. NMPA registration pathways for imported diagnostic kits require local clinical trial data, forcing distributors to establish Shanghai-based technical documentation teams. Yangtze River Delta medical device clusters are absorbing reagent rental contracts as provincial health bureaus limit upfront capital deployment.
Japan
PMDA radioisotope facility licensure enforces stringent waste handling protocols that elevate operational compliance costs for independent laboratories. Tokyo and Osaka hospital-integrated reference centers leverage captive waste management infrastructure to amortize fixed investments across high-volume endocrine panels. Kanto region university hospitals are adopting magnetic bead-based separation systems to compress assay turnaround times.
India
CDSCO registration mandates for imported diagnostic kits are filtering out unstandardized reagent suppliers and consolidating procurement around certified manufacturers. Maharashtra and Karnataka state health departments are expanding RIA-based thyroid and diabetes screening programs in urban municipal hospitals. Mumbai-based distributors are building local technical documentation capabilities to satisfy tightened import requirements.
Australia
TGA alignment with EU MDR performance standards enables streamlined kit registration for European-certified manufacturers entering the market. New South Wales and Victoria public pathology networks are prioritizing reagent rental models over analyzer capital purchases. Sydney and Melbourne hospital clusters are integrating automated RIA platforms into existing immunoassay workflows.
South Korea
MFDS medical device regulations require local adverse event reporting infrastructure for imported diagnostic platforms. Seoul Capital Area tertiary hospitals are capturing routine hormone testing volumes through chemiluminescence substitution, though reference laboratories retain RIA for picomolar-range applications. Busan-Ulsan pharmaceutical manufacturing zones are expanding contract research capacity for monoclonal antibody pharmacokinetic studies.
Asia-Pacific Radioimmunoassay Market Competitive Environment
Listed leaders compete with private specialists across reagent manufacturing scale and analyzer integration depth. The vendor base clusters around three tiers: diversified life science conglomerates with captive antibody production, mid-scale diagnostic platform integrators, and niche autoimmune panel specialists. Strategic moves concentrate on workflow integration partnerships and reagent rental contracting models that transfer obsolescence risk to manufacturers.
Within the diversified conglomerate tier, Merck KGaA and PerkinElmer Inc. exemplify players with cross-border reagent supply infrastructure. Beckman Coulter, Inc. occupies a position among platform integrators leveraging existing immunoassay workflow relationships. EUROIMMUN Medizinische Labordiagnostika AG represents the specialist archetype with differentiated autoimmune endocrine portfolios.
| Leading Market Players |
|---|
| Immuno-Biological Laboratories Co., Ltd. |
| Abcam plc |
| Merck KGaA |
| MP Biomedicals |
| Tecan Trading AG |
| PerkinElmer Inc. |
| Beckman Coulter, Inc. |
| Berthold Technologies GmbH & Co. KG |
| EUROIMMUN Medizinische Labordiagnostika AG |
| Others |
Value Chain & Pricing Dynamics
Chemiluminescence substitution in routine hormone testing is compressing RIA reagent premiums while simultaneously shifting procurement geography toward Japanese and European supply bases with captive antibody production. This input transition elevates currency exposure for Asia-Pacific distributors while concentrating price-setting power among iodine-125 tracer manufacturers with PMDA-certified facilities.
Pricing Analysis
Next-generation magnetic bead-based separation systems command 40-60% premiums over legacy precipitation platforms, while manual centrifugation methods face steepest price erosion. Three-tier pricing structure across premium automated platforms, standard benchtop analyzers, and economy manual kits reflects certification grade and workflow integration depth. Cost compression in the economy tier intensifies because Southeast Asian budget constraints limit upfront capital deployment. Diagnostic labs in Australian public pathology networks exhibit highest price sensitivity, while Japanese university hospitals prioritize inter-run reproducibility over per-test cost.
Supply Chain Analysis
Extended lead times for iodine-125 tracers and high-affinity antibodies expose Asia-Pacific distributors to six-month replenishment cycles. Specialized reagent production concentrates in Japan, Germany, and Switzerland, drawing from radioisotope handling facilities with PMDA and BfArM licensure. Single-source vulnerability concentrates in iodine-125 supply, where reactor-dependent production faces regulatory restriction risks. Distribution runs through Shanghai and Singapore hub warehouses serving tier-one hospital networks across China and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent rental contracting models represent the dominant service-attach opportunity, with cost-per-test arrangements expanding faster than analyzer hardware placements as Chinese provincial health bureaus limit capital deployment.
For Market Incumbents: Shield installed-base positions by deepening backward integration into iodine-125 tracer production and securing PMDA facility certifications that constrain new laboratory entrants. Chemiluminescence substitution in Australian and South Korean tertiary hospitals threatens routine hormone testing volumes, necessitating workflow integration partnerships that embed RIA as reference-grade validation for biologics pharmacokinetics. For New Entrants and Emerging Players: TGA-aligned EU MDR equivalence pathways offer fastest regulatory entry for European-certified kit manufacturers targeting Australian public pathology networks. China's tier-two city hospital clusters outside Beijing, Shanghai, and Guangzhou remain underpenetrated for automated platforms, presenting whitespace for bundled reagent-analyzer contracts with provincial health bureaus prioritizing operational expenditure models over capital purchase. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale diagnostic platform integrators lacking captive antibody production, creating consolidation targets for diversified life science conglomerates seeking reagent manufacturing scale. Long-term viability hinges on therapeutic monitoring for biologics penetration across oncology and autoimmune treatment centers, with monoclonal antibody therapy expansion serving as the critical inflection signal for pharmacokinetic RIA panel demand.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Contracting | Transfers obsolescence risk to manufacturers while securing recurring revenue from Chinese provincial health bureaus. |
| PMDA Facility Certification | Creates regulatory moats for hospital-integrated reference centers with captive iodine-125 waste management infrastructure. |
| Magnetic Bead Separation Adoption | Compresses assay turnaround from four hours to ninety minutes in Kanto region university hospitals. |
| Biologics Pharmacokinetic Panel Development | Captures fastest-expanding application as monoclonal antibody therapies proliferate across Asia-Pacific oncology centers. |
| CDSCO Local Technical Documentation | Enables continued kit import access as India's tightened registration mandates filter unstandardized reagent suppliers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with clinical laboratory directors, nuclear medicine department heads, IVD procurement managers, and CDSCO regulatory consultants; and secondary validation against NMPA registration databases, PMDA facility licensure records, TGA IVD approval listings, and hospital procurement contract disclosures. Bottom-up triangulation across reagent consumption estimates and top-down analyzer placement tracking ensured convergence.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application tier, end-user category, and technology generation, with CAGRs derived from segment-level growth rate reconciliation. Industry-specific inputs incorporated PMDA radioisotope facility expansion timelines, CDSCO registration pathway throughput, and chemiluminescence platform substitution rates in Australian tertiary hospitals.
Underlying assumptions cover regulatory pathway stability and iodine-125 supply continuity, with deviation risk concentrated in multi-country isotope permit fragmentation and radiochemistry workforce scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
IVD Antibody Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Global Urinalysis Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Elisa Tests Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market