
 Global Headlight Control Module Market | 2026-2036
Global Headlight Control Module Market Size, Share, and Industry Trends Forecast 2026-2036
Global Headlight Control Module Market Intelligence
Software-defined features, particularly over-the-air updates for lighting performance, is realigning the value proposition of headlight control modules. HELLA GmbH & Co. KGaA leverages its deep expertise in automotive electronics to develop advanced adaptive control modules. Continental AG differentiates its offerings through system integration, bundling modules with sensor fusion for autonomous functions. Valeo SA anchors its competitive positioning in visibility systems, specializing in innovative LED and laser technologies.
A headlight control module is an electronic control unit that manages and regulates the functions of a vehicle's headlamps. It communicates via the vehicle's CAN bus network to control voltage, current, and switching logic for various lighting sources. Adaptive control modules represent the fastest-growing product type, driven by safety feature proliferation in passenger vehicles. The transition to LED technology from older halogen systems continues to define the market's technological landscape.
Vehicle safety mandates from bodies like the US National Highway Traffic Safety Administration and regulations under the UNECE framework shape module design. For instance, NHTSA's updated FMVSS 108 rule permitting adaptive driving beam systems in the United States directly influences product development. The central strategic decision for suppliers involves allocating R&D resources between cutting-edge smart modules for electric vehicles and cost-effective solutions for legacy platforms.
Market Dynamics
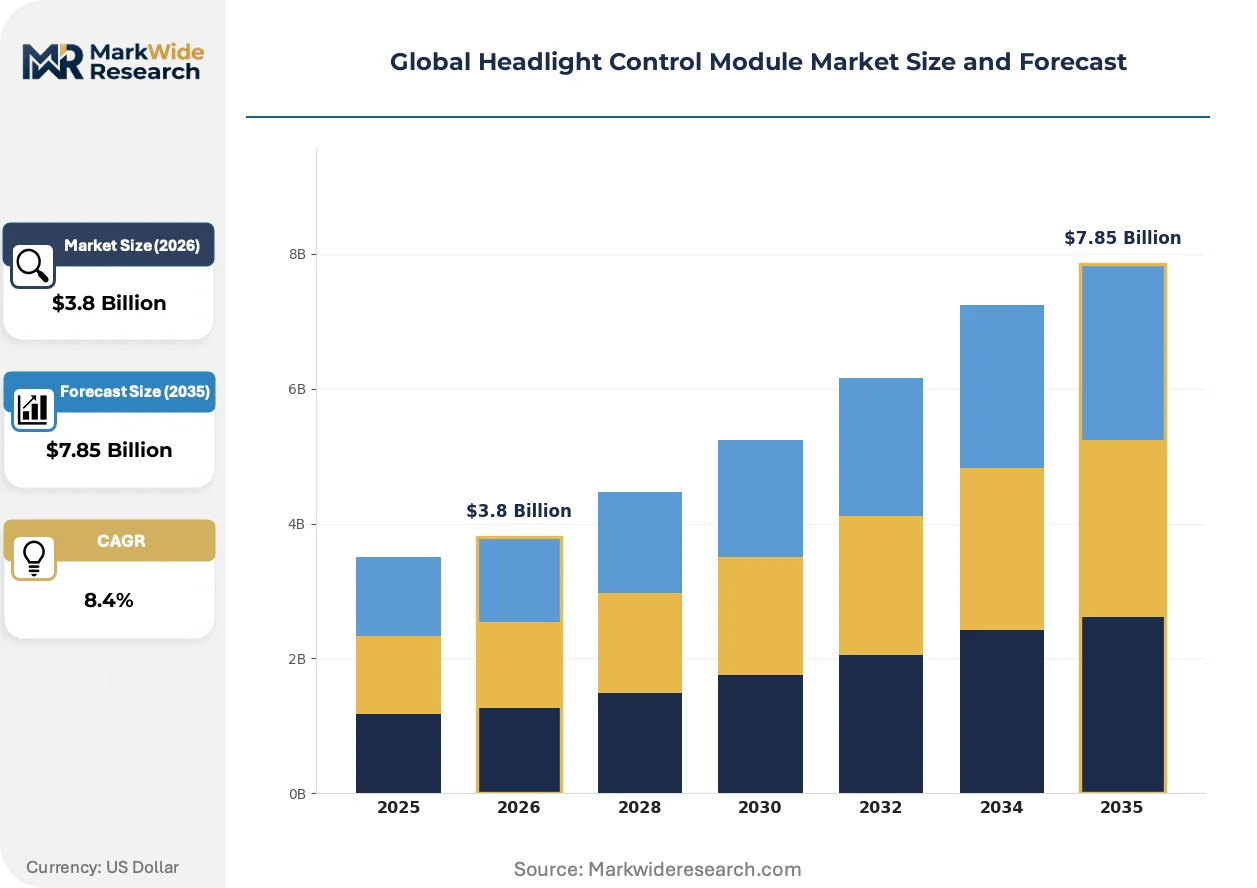
The central dynamic in the headlight control module market is the strategic tension between developing high-cost, feature-rich adaptive modules for new electric and software-defined vehicles and supplying cost-effective, reliable units for high-volume legacy internal combustion engine platforms.
Growth Catalysts
- Regulatory Mandates:The updated FMVSS 108 rule from the US National Highway Traffic Safety Administration, which now permits adaptive driving beam systems, directly stimulates demand for advanced control modules in the North American passenger vehicle market.
- Technology Transition:The widespread shift to LED and matrix LED headlamps from halogen systems in mass-market vehicles necessitates more sophisticated electronic control units to manage complex switching, dimming, and thermal management functions.
- ADAS Proliferation:Growing consumer and regulatory demand for active safety features in key automotive production hubs like Germany and Japan requires advanced headlight controllers that can integrate with camera and sensor data for adaptive lighting.
Market Restraints
- Input Cost Volatility:Module manufacturers are exposed to price fluctuations and supply constraints for essential components like automotive-grade microcontrollers and power MOSFETs, impacting production costs and margins.
- Technical Debt:The long lifecycle of automotive platforms forces suppliers to maintain and support older-generation modules for the aftermarket, diverting resources from innovation and next-generation product development.
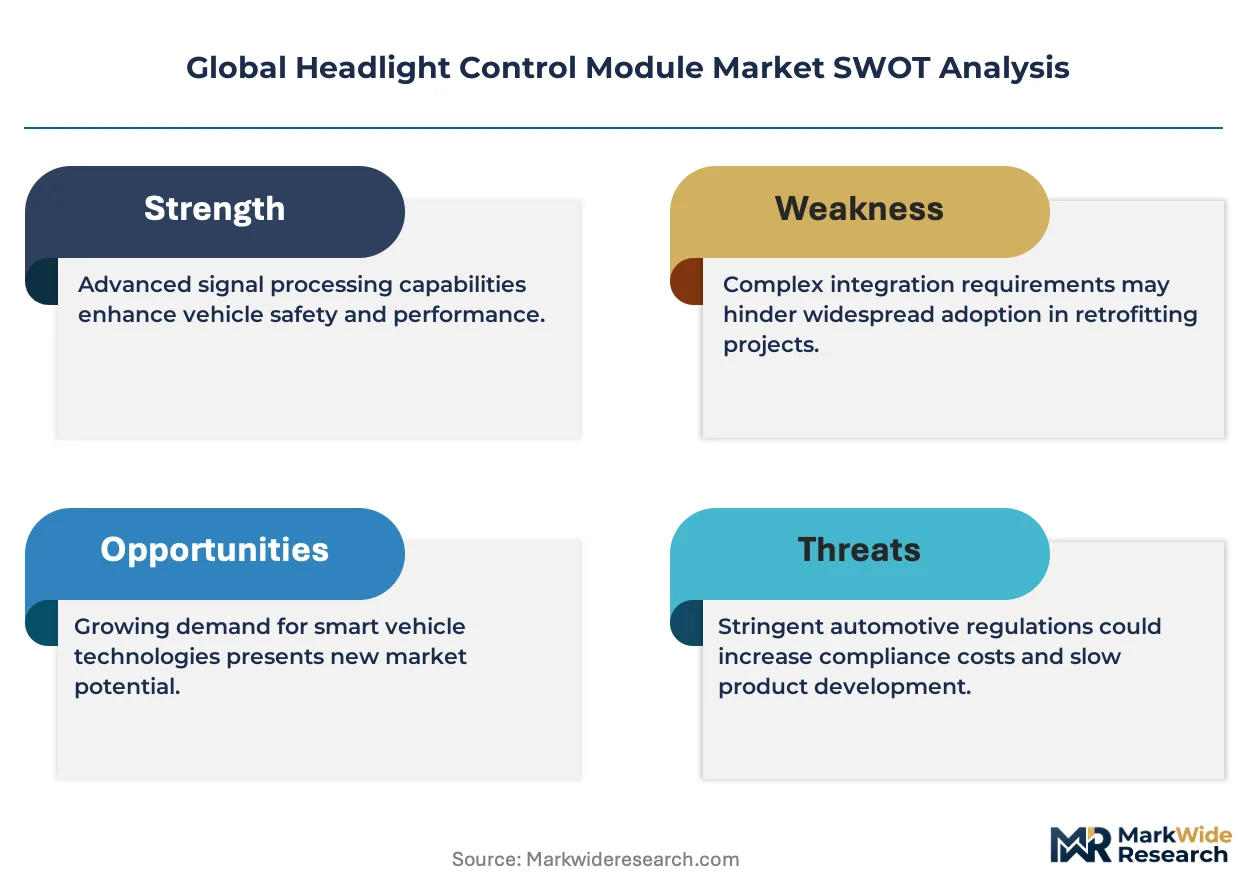
- Substitution by Integration:The trend towards domain control units in zonal E/E architectures threatens the discrete headlight control module, as its functions become absorbed into a larger, more centralized vehicle computer.
Strategic Opportunities
- Software-Defined Features:Offering lighting performance and animation features as over-the-air (OTA) software updates creates new, recurring revenue streams for automakers and module suppliers, decoupling revenue from the initial hardware sale.
- Commercial Vehicle Electrification:Developing ruggedized, energy-efficient LED control modules for electric trucks and buses presents a significant opportunity, as fleet operators prioritize total cost of ownership and component longevity. *Aftermarket Upgrades: A market exists for plug-and-play adaptive lighting upgrade kits for popular vehicle models, allowing suppliers to capture value from enthusiasts and owners of vehicles not originally equipped with advanced lighting.
Industry Challenges
- Functional Safety Compliance:Achieving ISO 26262 certification for software and hardware is a complex and time-consuming process, requiring extensive validation and documentation that can delay product launches and increase development costs.
- Interoperability Complexity:Ensuring a single module can communicate flawlessly with a diverse array of camera, sensor, and CAN bus protocols from multiple vendors across different automaker platforms remains a significant engineering hurdle.
- Cybersecurity Threats:As headlight controllers become more connected, they represent a potential attack vector for malicious actors, requiring robust cybersecurity measures to prevent unauthorized control of vehicle lighting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Headlight Control Module Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Control Module, Automatic Control Module, Adaptive Control Module, Smart Control Module Technology: LED, Xenon, Halogen, Laser, OLED Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-road Vehicles, Specialty Vehicles End User: OEMs, Tier-1 Manufacturers, Aftermarket Suppliers, Automotive Service Centers |
| Companies Covered | HELLA GmbH & Co. KGaA, Valeo SA, Continental AG, Denso Corporation, Koito Manufacturing Co., Ltd., Marelli Holdings Co., Ltd., Hyundai Mobis, Aptiv, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Headlight Control Module Market Strategic Shifts & Innovations
The evolution from hardware-defined components to software-centric systems is redefining the function and value of headlight control modules. This transition enables lighting to become a dynamic, updatable feature that contributes to vehicle safety, branding, and user experience.
The move toward zonal electronic architectures is a primary technological shift. These systems consolidate control functions, including lighting, into powerful domain or zonal controllers, reducing wiring complexity and enabling more integrated vehicle behaviors. Premium electric vehicle platforms are the earliest adopters of this architecture, driving demand for software-heavy control solutions. This architectural consolidation is electrifying the vehicle's core logic, allowing for more sophisticated and coordinated lighting animations and predictive beam-shaping based on real-time data.
Harmonization of international standards under the UNECE World Forum for Harmonization of Vehicle Regulations is streamlining product development. Regulations like UNECE R48 and R149 provide a common framework for the performance and approval of adaptive driving beam (ADB) systems. This allows suppliers to design a single module architecture that can be certified for use in multiple key markets, including the European Union and Japan. The passenger vehicle segment, which has global platform strategies, benefits most directly from this regulatory convergence.
A feature-on-demand purchasing model for advanced lighting capabilities is altering procurement patterns. Automakers are commissioning hardware modules with latent capabilities that can be activated post-sale via a software license purchase by the vehicle owner. This unbundles the cost of advanced features from the initial vehicle price, shifting the transaction from a one-time hardware sale to a potential recurring software revenue stream. The trend is most visible in the premium and luxury vehicle segments in North America and Europe.
Global Headlight Control Module Market Segmentation
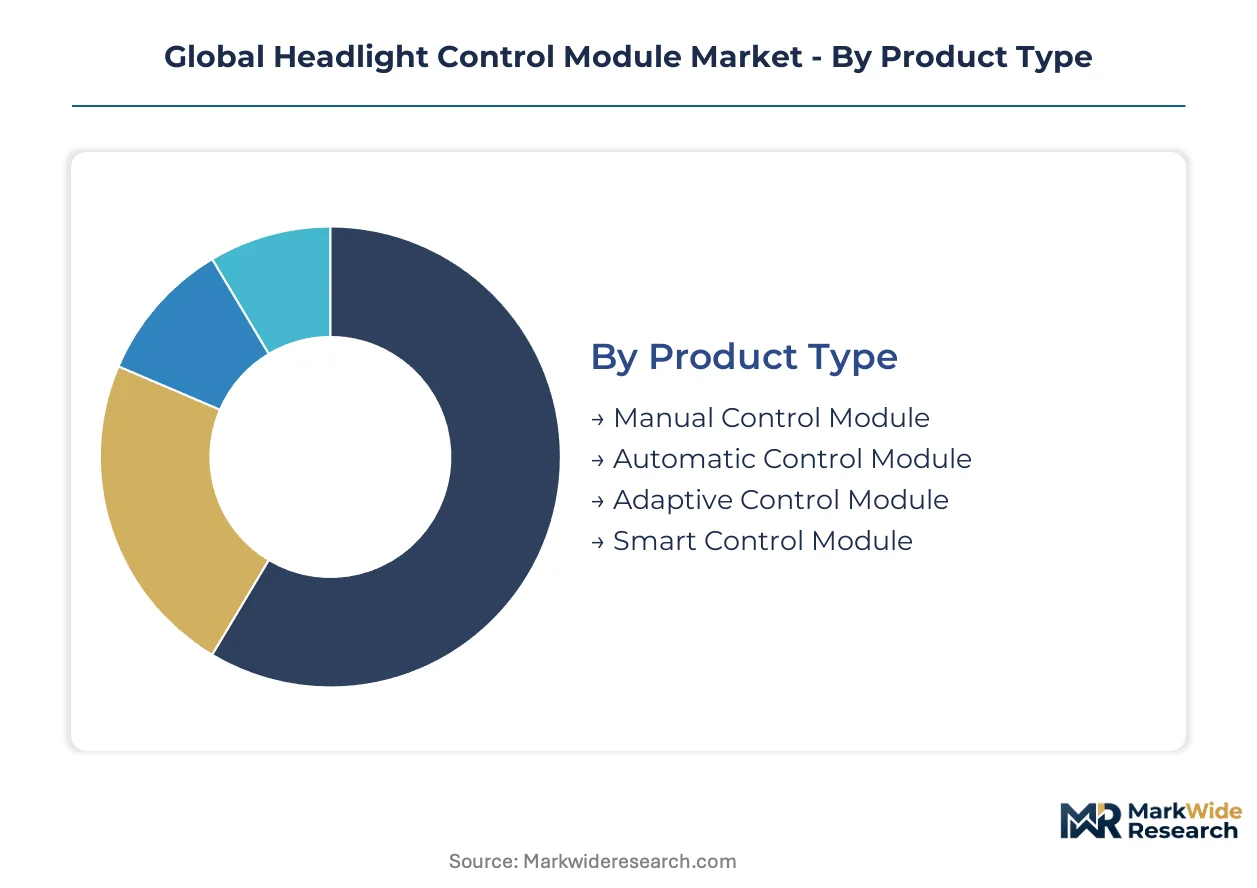
Understanding the market for headlight control modules requires a detailed examination of its constituent parts, as each segment presents unique technological requirements and commercial opportunities. This segmentation highlights where innovation is concentrated and where established solutions maintain market share.
Product Type:
The volume of headlight control modules sold often dictates the complexity of their features, creating a clear distinction between basic and premium offerings.
- Adaptive Control Module:This electronic unit manages dynamic beam patterns, adjusting light distribution based on road conditions, speed, and traffic. Demand concentrates in Germany and the United States, driven by updated safety regulations like FMVSS 108.
- Smart Control Module:These advanced modules integrate sophisticated processing for predictive lighting, vehicle-to-everything communication, and over-the-air updates. Demand focuses on electric vehicle platforms and luxury segments, where software-defined features enhance user experience.
- Manual Control Module:These modules provide basic on/off and high/low beam switching for older or entry-level vehicle platforms.
- Automatic Control Module:This type offers automatic headlight activation and dimming functions, often linked to ambient light sensors.
Mature deployment sits with Manual Control Modules. Newer deployment is concentrated in Smart Control Modules.
Technology:
The cost structure of headlight control modules varies significantly with the underlying lighting technology, influencing adoption rates across vehicle segments.
- LED:These modules utilize light-emitting diodes for efficient and flexible illumination, enabling complex beam shaping and styling. Demand is widespread across mass-market passenger vehicles, driven by energy efficiency mandates and design flexibility.
- Laser:Employing high-intensity laser diodes, these modules provide precise, long-range illumination with minimal energy consumption. Demand is concentrated in premium and luxury vehicle segments in Europe, where advanced visibility features differentiate models.
- Xenon:High-intensity discharge (HID) lamps require specific control modules for their high-voltage ignition and stable operation.
- Halogen:These traditional incandescent lamps use the simplest control modules, primarily managing on/off switching and basic power delivery.
- OLED:Organic light-emitting diode modules offer ultra-thin, flexible lighting elements for advanced design and animation possibilities.
The transition from incandescent sources to solid-state lighting is driving a fundamental shift in module design, requiring greater thermal and power management capabilities.
Application:
The scale of production and specific operational demands define the requirements for headlight control modules across different vehicle applications.
- Passenger Vehicles:These applications integrate sophisticated adaptive lighting features for enhanced safety, driver comfort, and aesthetic appeal. Demand is highest in global automotive production centers, including Japan and the United States, due to consumer preferences and regulatory pushes.
- Commercial Vehicles:This segment requires rugged and durable control modules designed to withstand harsh operating conditions, vibrations, and extended duty cycles. Demand is increasing in fleet electrification initiatives, especially in Europe, focusing on energy efficiency and reliability.
- Two-Wheelers:Headlight control modules for motorcycles and scooters focus on compact design and basic functionality for safety lighting.
- Off-road Vehicles:These modules are built for extreme durability and resistance to environmental factors, often for high-lumen output.
- Specialty Vehicles:This category includes modules for emergency vehicles, agricultural machinery, and construction equipment, often with unique lighting patterns.
Passenger vehicle integration drives significant module innovation, while commercial applications prioritize ruggedness and long-term operational efficiency.
End User:
The distribution channels and procurement dynamics for headlight control modules vary considerably depending on the end-user segment, impacting pricing and service models.
- OEMs:Original Equipment Manufacturers integrate headlight control modules directly into new vehicle production lines. Demand is characterized by long-term supply agreements and stringent quality standards, particularly from major automakers in Germany.
- Tier-1 Manufacturers:These suppliers develop and provide complete lighting systems, including integrated modules, directly to OEMs. Demand involves close collaboration on system design and validation, especially for complex adaptive lighting solutions for global platforms.
- Aftermarket Suppliers:These entities provide replacement or upgrade headlight control modules for vehicles already in operation.
- Automotive Service Centers:These centers install replacement modules during vehicle maintenance or repair, often sourcing from aftermarket suppliers.
Initial hardware sales are dominated by OEMs and Tier-1 suppliers, while aftermarket channels provide ongoing service and upgrade opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global market for headlight control modules exhibits a clear divide between production centers and consumption drivers. Demand for advanced modules is highest in mature automotive markets, while manufacturing capabilities are concentrated in key industrial hubs. This dynamic shapes investment and regulatory focus across continents.
Germany
German automotive production drives significant demand for adaptive control modules, particularly for premium vehicles. Regulations under the UNECE framework influence module design and performance standards for export. Automotive innovation in Bavaria and Baden-Württemberg focuses on integrating advanced lighting with autonomous driving functions.
United States
US demand for sophisticated headlight control modules stems from a strong passenger vehicle market and evolving safety standards. The updated FMVSS 108 rule directly stimulates development of adaptive driving beam systems. Manufacturing and R&D activities in Michigan concentrate on integrating these modules into next-generation vehicle platforms.
Japan
Japanese automakers prioritize advanced headlight control modules for their global passenger vehicle platforms, emphasizing safety and technological sophistication. Compliance with UNECE R48 and R149 regulations ensures market access for adaptive systems. Automotive R&D centers in Aichi Prefecture and Kanagawa are pioneering predictive lighting technologies.
China
China's burgeoning electric vehicle market creates substantial demand for smart control modules, supporting advanced lighting features. Government policies, including MIIT guidelines, promote domestic development of intelligent vehicle systems. Major automotive manufacturing clusters in Shanghai and Guangdong are rapidly adopting software-defined lighting solutions.
South Korea
South Korean automotive manufacturers increasingly integrate advanced headlight control modules to enhance vehicle safety and user experience. Government initiatives support the development of smart mobility solutions, including connected lighting systems. Research hubs in Gyeonggi-do and Ulsan focus on miniaturization and energy efficiency for LED control units.
Global Headlight Control Module Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in headlight control modules. The market exhibits a tiered structure, with established automotive electronics suppliers alongside specialized lighting component manufacturers. Strategic archetypes include full-system integrators, dedicated module specialists, and emerging software-centric providers. Dominant competitive moves involve strategic partnerships for sensor integration and focused R&D allocation towards software-defined features.
Within the full-system integration tier, German-based Continental AG differentiates its offerings through bundling modules with sensor fusion for autonomous functions, serving a broad range of global automakers. Similarly, French-based Valeo SA anchors its competitive positioning in advanced visibility systems, specializing in innovative LED and laser technologies that enhance both safety and design. German manufacturer HELLA GmbH & Co. KGaA represents a dedicated module specialist, leveraging deep expertise in automotive electronics to develop advanced adaptive control modules for diverse vehicle platforms worldwide. These established players consistently drive innovation in complex lighting management.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| Valeo SA |
| Continental AG |
| Denso Corporation |
| Koito Manufacturing Co., Ltd. |
| Marelli Holdings Co., Ltd. |
| Hyundai Mobis |
| Aptiv |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
Specialized engineering talent in automotive electronics, concentrated in Germany and Japan, influences the pricing tiers for advanced headlight control modules, creating a premium for highly innovative solutions.
Pricing Analysis
Cost-down pressure on basic control modules accelerates because of intense competition and the commoditization of older technologies. The dominant pricing model is per-unit transactional, with long-term contracts for OEM supply. Price differentiation drivers include the module's functional safety certification level (e.g., ISO 26262 compliance) and the degree of software customization for specific vehicle platforms. Passenger vehicle OEMs, especially in the mass market, exhibit the highest price sensitivity, while luxury segment buyers prioritize advanced features over cost.
Supply Chain Analysis
Achieving automotive-grade qualification gates access to the headlight control module supply chain, ensuring component reliability. Geographic supply concentration for microcontrollers and power MOSFETs centers in Taiwan, South Korea, and China. Raw material dependencies include rare earth elements for LED production and specialized semiconductors for processing units. Commodity price volatility for these essential components presents a structural risk to module manufacturers. Distribution runs through a multi-tiered model, with Tier-1 manufacturers supplying integrated lighting systems directly to OEMs, complemented by a smaller aftermarket channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation is a defining characteristic of this market, driven by the increasing capital expenditure required for software-defined features and functional safety compliance.
For Market Incumbents: Anticipate the shift to zonal E/E architectures by deepening vertical integration into software development for centralized vehicle control units. Focus R&D resources on predictive lighting algorithms and over-the-air update capabilities to counter the threat of new software-centric entrants. Secure long-term supply agreements for critical semiconductors to mitigate input cost volatility.
For New Entrants and Emerging Players: Launch via niche opportunities in aftermarket upgrades for adaptive lighting, targeting popular vehicle models not originally equipped with advanced features. The commercial vehicle electrification segment represents a penetrable application, prioritizing ruggedness and energy efficiency over complex animations. Develop specialized software solutions for lighting control, offering licensing models to smaller OEMs or Tier-1 suppliers.
For Investors and Strategic Acquirers: Re-rating potential sits with companies demonstrating strong intellectual property in software-defined lighting and robust cybersecurity frameworks given the increasing connectivity of vehicle systems. Focus on acquiring specialized firms with expertise in AI-driven adaptive beam-shaping or advanced thermal management for high-power LEDs. The signal to watch is the widespread adoption of feature-on-demand purchasing models by mass-market automakers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Software-Defined Lighting Platforms | Enables recurring revenue streams and rapid feature deployment through over-the-air updates for automakers. |
| Secure Long-term Semiconductor Supply Contracts | Mitigates input cost volatility and ensures production continuity for critical electronic components. |
| Develop Ruggedized Modules for Commercial EVs | Captures opportunities in fleet electrification by meeting demands for durability and energy efficiency. |
| Pursue ISO 26262 Functional Safety Certification | Establishes credibility and market access for advanced adaptive control modules in safety-critical applications. |
| Form Strategic Partnerships for Sensor Fusion | Integrates lighting control with ADAS data, enabling more sophisticated and responsive adaptive beam patterns. |
Research Approach
Document review covered SEC filings, industry association reports, and technical standards from UNECE and NHTSA, complemented by interviews with OEM platform engineers, Tier-1 procurement leads, and automotive electronics R&D directors. This approach ensured a comprehensive understanding of market dynamics. Primary insights were triangulated against secondary data sources, including automotive production databases and technology journals, to validate market sizing and trends.
Market sizing and forecasting outputs reflect a structured analytical framework applied across the analysis window. The model segmented the market by product type (adaptive, smart), technology (LED, Laser), application (passenger, commercial), and end-user (OEM, aftermarket). Compound annual growth rates were derived from historical data analysis and projected technological adoption rates. Key forecast inputs included vehicle production volumes by segment and regulatory timelines for advanced lighting features.
Regulatory shifts, technological breakthroughs, and macroeconomic fluctuations are the dominant revision risks to the market projections. Forecasts reflect assumptions regarding component availability and the pace of EV adoption. A model refresh is warranted upon material change in global automotive production volumes or safety mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Xenon Lights Market
Lighting
Solid-State Lighting Source Market
Lighting
Smart Industrial Illumination Market
Lighting
Ultraviolet Lamps Market
Lighting
Lighting Market
Lighting
Dimmers Market
Lighting
Programmable Stage Lighting Market
Lighting
Smart Lamp Market
Lighting
Global Lighting Control System Market
Lighting
Solar Lights Market
Lighting
Illuminating Signs Market
Lighting
Wireless Lighting Market
Lighting
Solar Spotlights Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Industrial Lighting Market