
 Solar Spotlights Market | 2026-2036
Solar Spotlights Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Spotlights Market Insights
Modular solar spotlight kits with swappable battery packs and adjustable lumen heads is realigning buyer choice toward upgradeable systems rather than disposable fixtures. Signify Holding leverages its Philips Hue ecosystem to anchor premium connected outdoor lighting positions. Jinhua Sunmaster Lighting Co. Ltd competes on manufacturing scale, sustaining cost leadership across stake-mounted and wall-mounted configurations. Fonroche Lighting America, Inc. specializes in commercial-grade flood light systems, dominating municipal and industrial procurement channels in North America.
Solar spotlights are photovoltaic-powered directional luminaires comprising monocrystalline or polycrystalline panels, lithium iron phosphate or nickel-metal hydride battery packs, and LED or halogen emitters housed in IP65-rated enclosures, designed to convert stored solar energy into focused illumination for security, landscape, or task lighting applications without grid connection. LED technology leads the technology dimension due to lumen-per-watt efficiency and declining diode costs, while halogen retains niche share in cold-climate installations where instant full brightness matters. Wall-mounted installation commands the strongest margin pool among residential buyers, whereas stake-mounted products drive volume through garden and pathway applications.
EPA ENERGY STAR and FCC Part 15 standards govern efficiency claims and wireless connectivity modules in the United States, while EU RoHS and CE marking restrict hazardous substances and mandate conformity for products entering European markets. The EU Green Deal's building renovation wave indirectly stimulates outdoor lighting retrofits. Stakeholders must monitor battery chemistry regulations and emerging right-to-repair mandates that could reshape product architecture and aftermarket service models.
Market Dynamics
Modular battery-swappable architectures are restructuring buyer economics in solar spotlights, shifting procurement criteria from upfront fixture cost toward lifecycle upgradeability and component serviceability across residential and commercial installations.
Growth Catalysts
- California Title 24 energy codes:Outdoor lighting mandates in drought-prone municipalities accelerate grid-independent solar adoption for compliance without trenching costs.
- Lithium iron phosphate chemistry:Superior thermal stability and cycle life versus nickel-metal hydride variants enable extended warranty terms and rental financing models.
- Suburban infill developments:Master-planned communities in Texas, Florida, and Arizona specify solar pathway lighting to avoid utility connection fees and accelerate occupancy permits.
Market Restraints
- Polysilicon supply concentration:Panel cost volatility tracks Xinjiang-sourced wafer availability, exposing manufacturers to forced labor disclosure requirements under US UFLPA enforcement.
- Seasonal irradiance mismatch:Northern latitude installations face winter performance gaps requiring oversized battery packs that inflate unit economics.
- Grid-tied LED retrofits:Existing 120V landscape systems with smart home integration present lower switching costs than full solar replacement for premium residential buyers.
Strategic Opportunities
- EU Green Deal renovation wave:Building envelope retrofits in Germany, France, and Italy trigger coordinated outdoor lighting upgrades with solar qualification for green mortgage financing.
- Right-to-repair mandates:Proposed EU battery regulations would standardize cell formats and diagnostic ports, enabling aftermarket service networks and subscription maintenance revenue.
- IoT convergence with energy harvesting:Bluetooth mesh and LoRaWAN modules powered by surplus panel capacity eliminate battery replacement in connected security applications.
Industry Challenges
- IP65 testing backlog:Third-party enclosure certification queues at UL and Intertek extend product launch timelines by 8-14 weeks for seasonal selling windows.
- Electrochemical engineering scarcity:Battery management system firmware talent concentrates at automotive and consumer electronics employers, forcing lighting OEMs into contract development arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Spotlights Market |
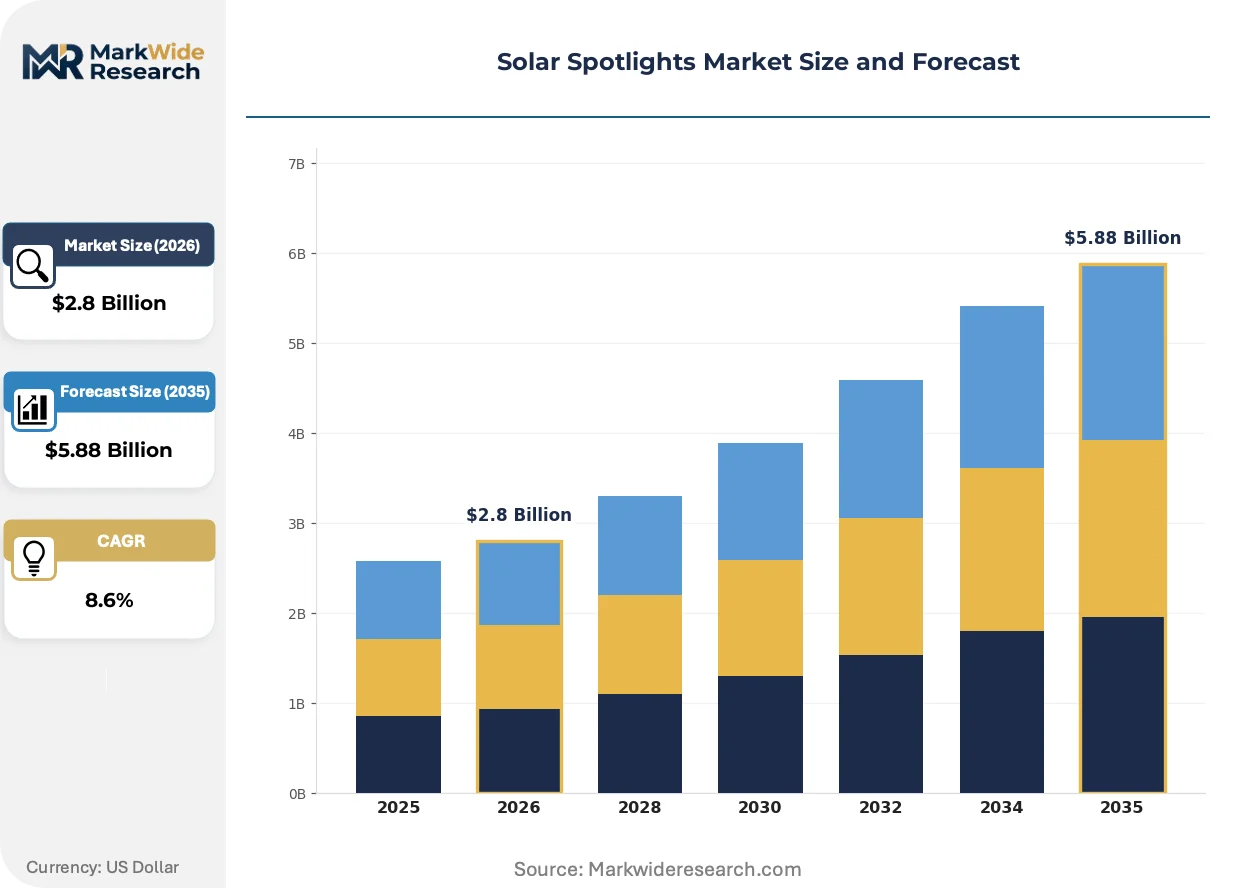
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Lights, Garden Lights, Pathway Lights, Flood Lights Technology: LED, Halogen, Xenon, Fluorescent Installation: Surface-Mounted, Stake-Mounted, Wall-Mounted, Hanging End User: Residential, Commercial, Industrial, Recreational |
| Companies Covered | Sunna Design SA, Greenshine New Energy, SEPCO Solar Electric Power Company, Solar Street Lights USA, Signify Holding, Jinhua Sunmaster Lighting Co. Ltd, Fonroche Lighting America, Inc., Sokoyo Solar Lighting Co. Ltd, Gama Sonic USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Spotlights Market Trends and Innovations
Active material and connectivity innovations are compressing product replacement cycles while expanding addressable use cases beyond traditional landscape illumination into security and task-specific applications.
Perovskite tandem cell research is expanding into pilot production for solar spotlights, promising 30%+ conversion efficiency in low-light conditions. Early adopters in Nordic municipal procurement are testing these panels for winter performance validation. The technology is expanding into premium residential segments previously unserved by conventional silicon economics.
EPA ENERGY STAR Version 2.0 outdoor lighting specifications tighten standby power limits and require standardized lumen maintenance reporting. Manufacturers must redesign driver electronics and thermal management to maintain certification eligibility for retail distribution. California utilities have integrated these standards into rebate qualification, redirecting R&D spending toward efficiency margin rather than lumen output alone.
Home improvement retailers are unbundling installation from product sales, offering certified contractor networks as a separate transaction. This disintermediates traditional electrical contractor relationships and shifts margin capture toward the retail channel. The pattern is most visible in big-box outdoor seasonal resets across the US Sun Belt, where DIY preference collides with permitting complexity for hardwired alternatives.
Solar Spotlights Market Segmentation
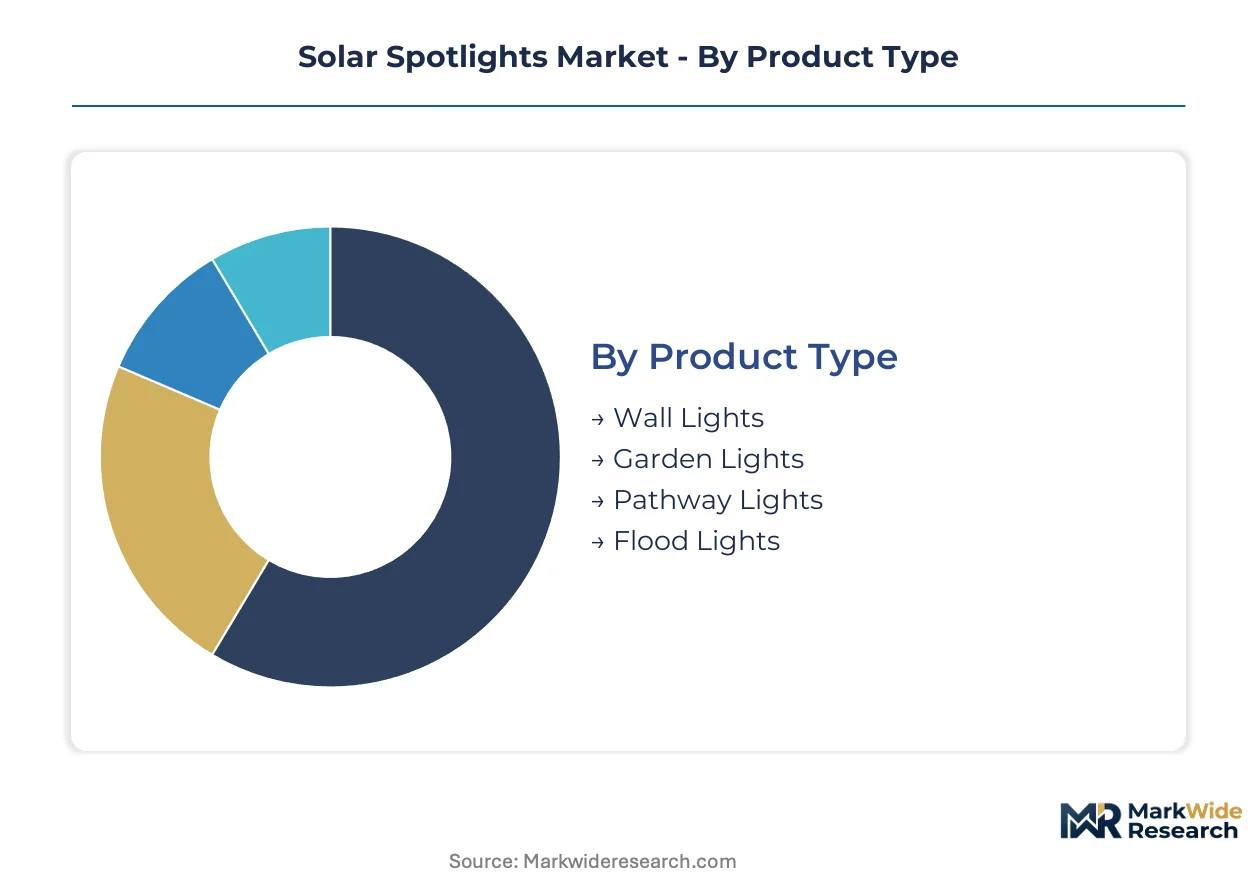
Segmentation in solar spotlights reveals how procurement criteria diverge across technical specifications and use environments. Buyers prioritize lumen output, battery chemistry, and mounting flexibility based on installation constraints and regulatory exposure.
Product Type:
Supply concentration in panel sourcing and battery pack assembly favors manufacturers with captive component access across fixture categories.
- Wall Lights:Compact directional housings with integrated photovoltaic cells and motion-sensing modules. Municipal procurement in California drought-prone zones drives specification for Title 24 compliance without trenching infrastructure.
- Flood Lights:High-output arrays exceeding 2,000 lumens for security perimeters and commercial facades. Industrial buyers in Texas and Arizona specify these for perimeter illumination where grid connection costs exceed solar capital expenditure.
- Garden Lights:Low-profile decorative fixtures for ornamental landscaping.
- Pathway Lights:Stake-based linear arrays for residential walkways and master-planned community circulation networks.
Flood lights absorb the bulk of installed capacity; wall lights are expanding most quickly.
Technology:
Cost tier stratification separates premium solid-state emitters from legacy thermal sources with diverging efficiency profiles.
- LED:Gallium nitride diode arrays delivering 120+ lumens per watt with 50,000-hour rated life. ENERGY STAR certification eligibility under EPA Version 2.0 standards channels retail distribution toward this technology in US big-box channels.
- Halogen:Tungsten-halogen filaments providing instant full output without warm-up latency. Cold-climate installations in Minnesota and Wisconsin retain this technology where winter temperature swings degrade lithium battery performance.
- Xenon:High-intensity discharge sources for specialty security applications requiring precise color rendering.
- Fluorescent:Compact spiral and tube configurations for budget residential retrofits.
LED captures dominant share; halogen retains niche positioning in northern latitude deployments.
Installation:
Margin structure varies sharply by mounting complexity and electrical permitting requirements.
- Wall-Mounted:Bracket-attached housings with integrated junction boxes for vertical surfaces. Premium residential buyers in Florida suburban infill developments favor these for facade illumination without hardwiring permits.
- Stake-Mounted:Ground-penetrating posts with adjustable tilt mechanisms. Volume concentration in garden and pathway applications drives manufacturing scale at Jinhua Sunmaster and comparable OEMs.
- Surface-Mounted:Deck and patio fixtures with adhesive or screw-base attachment.
- Hanging:Pendant configurations for covered outdoor living spaces and pergola structures.
Stake-mounted fixtures command volume leadership; wall-mounted configurations deliver superior margin capture.
End User:
Customer type determines procurement channel, financing structure, and service life expectations.
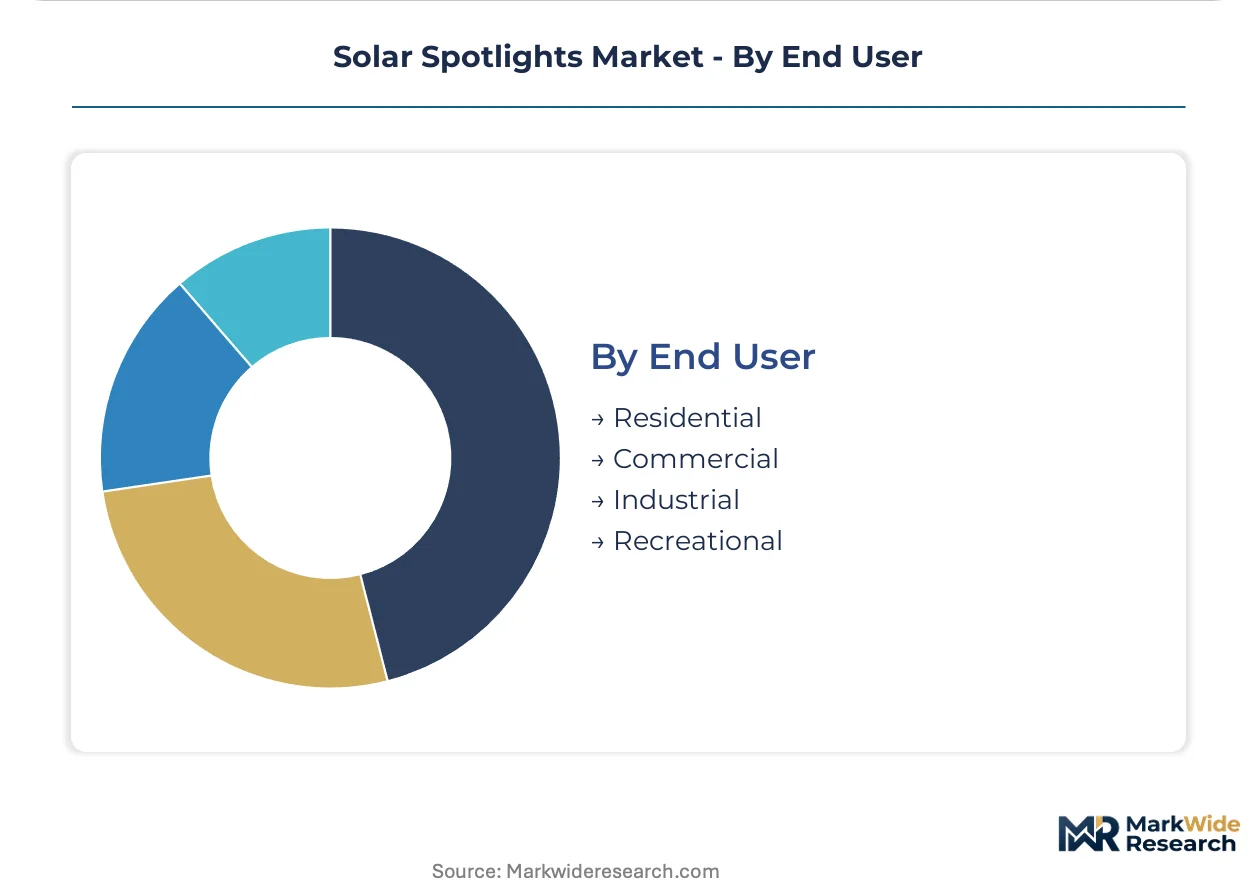
- Residential:Single-family and multi-family homeowners purchasing through retail and direct-to-consumer channels. California rebate programs tied to ENERGY STAR qualification accelerate adoption in drought-prone municipalities seeking grid independence.
- Commercial:Property managers and facility operators specifying outdoor lighting for retail, hospitality, and office assets. Master-planned community developers in Texas and Arizona specify solar pathway systems to accelerate occupancy permits.
- Industrial:Manufacturing and logistics facilities requiring perimeter security illumination.
- Recreational:Parks, golf courses, and campground operators with seasonal usage patterns.
Residential absorbs the bulk of unit shipments; commercial is climbing the fastest on project-scale deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates photovoltaic panel manufacturing while the United States absorbs the largest share of finished fixture consumption. This production-consumption divide shapes trade flows and regulatory compliance costs across the value chain.
United States
California's Title 24 energy codes drive municipal procurement of grid-independent outdoor lighting in drought-prone zones. The EPA's ENERGY STAR Version 2.0 standards tighten standby power limits for retail distribution eligibility. Suburban infill developments in Texas, Florida, and Arizona specify solar pathway systems to bypass utility connection fees.
Germany
The EU Green Deal's building renovation wave stimulates coordinated outdoor lighting retrofits with green mortgage financing. RoHS and CE marking requirements restrict hazardous substances in battery pack assemblies. Industrial clusters in Bavaria test perovskite tandem cells for Nordic municipal winter performance validation.
China
Domestic manufacturers leverage captive polysilicon supply and lithium iron phosphate cell production at scale. The country's national energy administration enforces dual carbon goals that accelerate solar lighting deployment in rural infrastructure programs. Zhejiang and Guangdong provinces concentrate export-oriented fixture assembly operations.
France
ANSM and CNIL guidelines intersect with CE marking for connected outdoor lighting products with data collection capabilities. The EU's proposed right-to-repair battery regulations would standardize cell formats for aftermarket service networks. Municipal procurement in Provence-Alpes-Côte d'Azur prioritizes solar security perimeters for coastal tourism infrastructure.
Australia
New South Wales and Victoria deploy solar flood lighting for perimeter security at mining and logistics facilities where grid extension costs prove prohibitive. The country's national standards body aligns enclosure rating requirements with IEC frameworks. Queensland's recreational park operators adopt seasonal solar installations for campground illumination.
Solar Spotlights Market Competitive Landscape
The competitive structure tilts toward scale-driven manufacturers with captive component access. Tiered positioning separates premium connected lighting ecosystems from cost-optimized volume producers. Three archetypes dominate: integrated electronics conglomerates with smart home platforms, Chinese manufacturing specialists with backward panel and battery control, and regional commercial-grade system providers with municipal procurement relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among the integrated electronics tier, Signify Holding anchors premium connected outdoor lighting positions through ecosystem integration. Jinhua Sunmaster Lighting Co. Ltd and Fonroche Lighting America, Inc. exemplify divergent scale strategies: the former occupies manufacturing-intensive cost leadership, while the latter sits within commercial-grade municipal specialization. Sunna Design SA represents European engineering-focused positioning with emphasis on architectural integration.
| Leading Market Players |
|---|
| Sunna Design SA |
| Greenshine New Energy |
| SEPCO Solar Electric Power Company |
| Solar Street Lights USA |
| Signify Holding |
| Jinhua Sunmaster Lighting Co. Ltd |
| Fonroche Lighting America, Inc. |
| Sokoyo Solar Lighting Co. Ltd |
| Gama Sonic USA |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Zhejiang and Guangdong provinces anchor component sourcing for solar spotlight manufacturing, translating captive polysilicon access into pricing discipline that resists volatile wafer spot markets. Their financing patterns favor equipment-heavy balance sheets over working capital intensity, reinforcing long-term contract structures with municipal buyers in California and Texas drought zones.
Pricing Analysis
Cost-down pressure on economy-tier fixtures accelerates because Jinhua Sunmaster and comparable OEMs exploit manufacturing scale to compress per-unit margins below 15 percent. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified connected systems from basic stake-mounted units, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from polysilicon supply concentration in Xinjiang exposing manufacturers to UFLPA disclosure overhead. Residential DIY buyers through big-box channels exhibit highest price sensitivity; commercial municipal procurement with green mortgage financing shows lowest.
Supply Chain Analysis
UL and Intertek certification queues gate product launch timelines, forcing OEMs to book enclosure testing slots 8-14 weeks ahead of seasonal selling windows. Panel sourcing concentrates in China, Vietnam, and Malaysia; battery pack assembly draws from domestic lithium iron phosphate cell production in Zhejiang. Raw material dependencies span monocrystalline wafers, lithium iron phosphate cathodes, and gallium nitride driver chips. Single-source vulnerability in third-party IP65 testing creates regulatory chokepoint risk. Distribution runs through home improvement retail networks with unbundled contractor installation services capturing margin shift from traditional electrical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polysilicon purification capacity constraints in non-Xinjiang geographies prop pricing power for manufacturers with qualified alternate sourcing, sustaining margin pools despite downstream cost compression.
For Market Incumbents: Deepen backward integration into lithium iron phosphate cell formats to preempt EU right-to-repair battery standardization mandates. Secure captive polysilicon supply from Vietnam and Malaysia to defend margin position against UFLPA enforcement exposure. Expand UL pre-certified enclosure inventories to compress 8-14 week testing backlogs threatening seasonal launch windows. For New Entrants and Emerging Players: EU Green Deal building renovation wave in Germany, France, and Italy opens a window for solar pathway lighting bundled with green mortgage financing. Target Nordic municipal procurement testing perovskite tandem cells for winter performance validation as most penetrable white-space. Pursue certified contractor network partnerships with big-box retailers to disintermediate traditional electrical channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap OEMs with captive component access in Zhejiang and Guangdong provinces where dual carbon enforcement pressures balance sheet restructuring. Battery management system firmware talent scarcity at automotive and consumer electronics employers signals long-term viability for lighting OEMs with in-house electrochemical engineering. Watch IP65 testing queue lengths at UL and Intertek as inflection indicator for product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Tandem Cell Pilot Production | Nordic municipal winter validation expands addressable markets beyond silicon economics. |
| EU Right-to-Repair Battery Compliance | Standardized cell formats enable subscription maintenance revenue and aftermarket service networks. |
| Certified Contractor Network Partnerships | Big-box retail channel control shifts margin capture from traditional electrical contractors. |
| Non-Xinjiang Polysilicon Supply Qualification | UFLPA-compliant sourcing defends US market access against forced labor disclosure enforcement. |
| IoT Energy Harvesting Module Integration | Bluetooth mesh and LoRaWAN powered by surplus panel capacity eliminates battery replacement costs. |
Research Methodology
Document review covered SEC filings from lighting OEMs, EPA ENERGY STAR certification databases, and EU RoHS compliance registries, complemented by interviews with municipal procurement officers in California and Texas, big-box retail category managers, and battery pack assembly engineers in Zhejiang province. Secondary validation drew from customs trade data, FERC interconnection filings, and IEC enclosure standard documentation. Bottom-up fixture shipment estimates triangulated against top-down solar lighting market absorption models.
Historical panel input from polysilicon supply chain disruptions and ENERGY STAR Version 2.0 efficiency standard adoption cross-referenced against primary interview intelligence across the analysis window. Segmentation dimensions modeled include product type, battery chemistry, installation configuration, and end-user procurement channel. CAGRs derived from unit economics trajectories of lithium iron phosphate versus nickel-metal hydride variants and rebate program qualification thresholds. Forecast inputs incorporated Title 24 compliance mandates and green mortgage financing penetration rates.
The model assumes a particular technology adoption path; alternative pathways for perovskite tandem cell commercialization would alter the outlook for winter performance gaps in northern latitude installations. Forecasts reflect assumptions around IP65 testing queue normalization and Xinjiang supply chain substitution velocity. A model refresh is warranted upon material change in EPA standby power limits or EU battery standardization enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Solar Column Headlight Market
Lighting
Street and Roadway Lighting Market
Lighting
Smart Lamp Market
Lighting
Smart Lighting Market
Lighting
Global Machine Vision Lighting Market
Lighting
Indicator Lights Market
Lighting
High Bay Lighting Market
Lighting
North America Outdoor Lighting Market
Lighting
Digital Light Processing Technology Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Directional Luminaire Market
Lighting
Recessed Lighting Market
Lighting
Programmable Stage Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Hazardous Location LED Lighting Market