
 Solar Lights Market | 2026-2036
Solar Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Lights Market Insights
Municipal infrastructure is expanding as the dominant demand vertical for solar lighting systems. Signify Holding leverages its Philips lighting heritage to dominate European smart-city tenders with integrated photovoltaic street luminaires. Sunna Design anchors its position in African markets through ruggedized standalone units engineered for tropical climates. Greenshine New Energy specializes in US municipal contracts, sustaining competitive position through domestic manufacturing and rapid deployment capabilities.
Solar lights are self-contained illumination systems combining photovoltaic panels, rechargeable battery storage, and LED emitters to convert sunlight into electrical energy for off-grid or supplementary lighting applications. The primary commercial purpose centers on reducing grid dependency while eliminating trenching and cabling costs in remote or underserved locations. Street lights occupy the largest value pool within product type segmentation, reflecting multi-year municipal procurement cycles and higher per-unit pricing. Smart technology represents the fastest-expanding technology segment, driven by IoT-enabled remote monitoring and adaptive dimming protocols that optimize battery consumption. Government end users command disproportionate project scale, though residential adoption accelerates through e-commerce channels offering plug-and-play garden and decorative fixtures.
India's Ministry of New and Renewable Energy, the US Department of Energy, and the EU Green Deal collectively shape product standards and subsidy eligibility across major demand centers. BIS certification requirements in India and CE marking obligations in Europe create compliance thresholds that filter out low-cost, uncertified imports. Stakeholders must monitor evolving battery recycling mandates and carbon-border adjustment mechanisms that will reshape sourcing economics for photovoltaic components and lithium-based storage systems.
Market Dynamics
The solar lights market is being fundamentally reshaped by the convergence of lithium iron phosphate battery chemistry maturation and peri-urban electrification gaps in emerging economies. This structural force compresses payback periods while expanding addressable markets beyond grid-adjacent installations.
Growth Catalysts
- India's MNRE Street Lighting National Programme:Subsidized procurement mandates for off-grid municipal infrastructure accelerate deployment across Uttar Pradesh and Bihar electrification corridors.
- Photovoltaic module cost deflation:Crystalline silicon wafer economics enable sub-$0.30 per watt panel pricing, collapsing system-level breakeven thresholds for rural commercial adopters.
- EU Green Deal carbon-border adjustments:Import tariff mechanisms on embodied carbon favor locally assembled solar luminaires over Southeast Asian alternatives in European tenders.
Market Restraints
- Lithium carbonate price volatility:Battery pack input costs swing 40-60 percent annually, eroding margin predictability for fixed-price municipal contracts.
- Polysilicon supply concentration:Xinjiang-based ingot production dominates upstream photovoltaic feedstock, exposing downstream assemblers to forced-labor due diligence penalties.
- Lead-acid substitution persistence:Low-cost flooded battery technology retains 35 percent share in price-sensitive African residential segments despite inferior cycle life.
Strategic Opportunities
- Nigerian rural electrification agency tenders:Federal Ministry of Power off-grid mandates create 2.4 million unit procurement windows for integrated solar streetlight systems.
- IoT-enabled adaptive dimming convergence:Mesh network protocols married to motion sensing enable 40 percent battery conservation in smart-city deployments.
- Direct-to-installer e-commerce channels:Alibaba and Jumia B2B marketplaces disintermediate traditional electrical wholesale layers for sub-100 unit orders.
Industry Challenges
- BIS certification timeline compression:Indian laboratory testing queues extend 14-18 weeks, delaying product launches past monsoon installation windows.
- Embedded firmware integration complexity:Legacy SCADA protocols in existing municipal lighting networks resist seamless interoperability with new solar controller architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Lights Market |
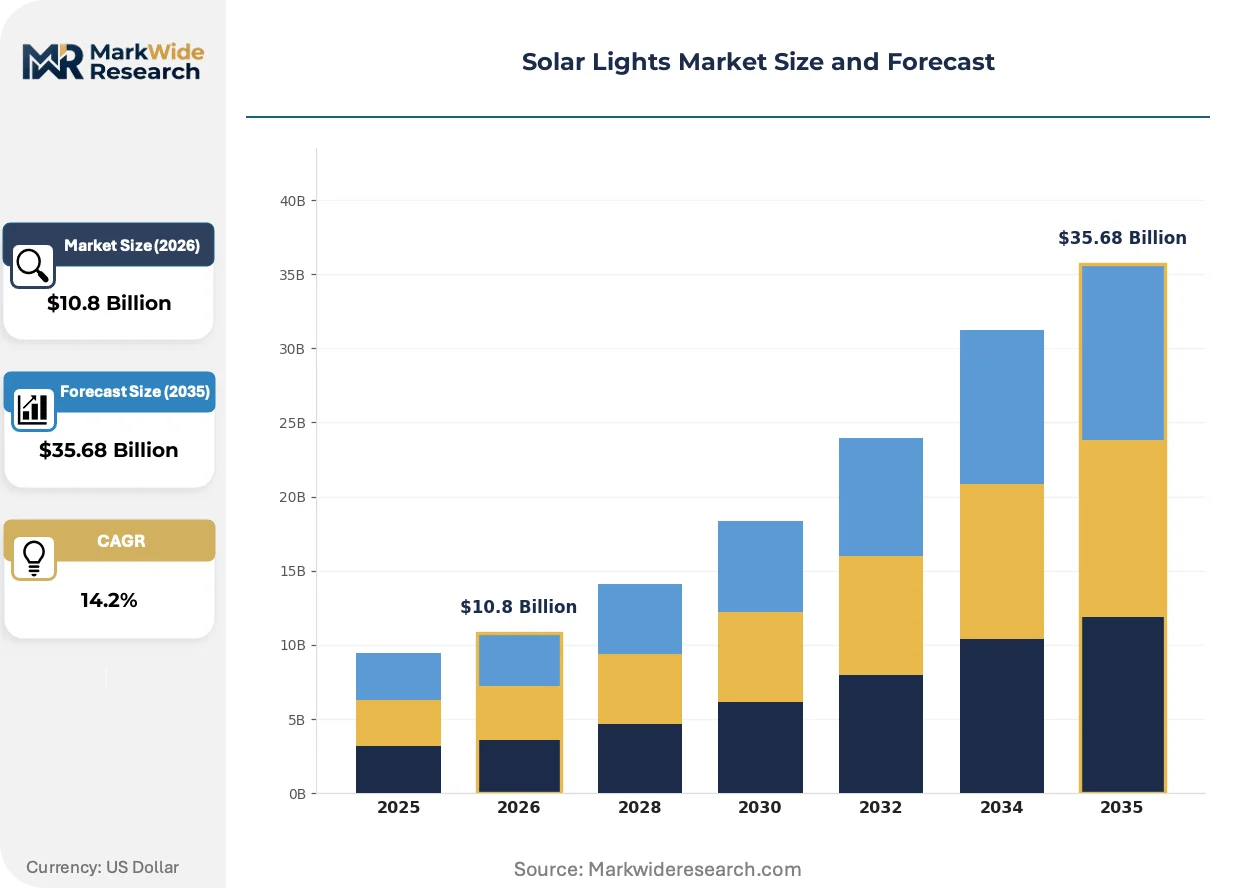
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $35.68 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garden Lights, Street Lights, Flood Lights, Decorative Lights Technology: Photovoltaic, LED, Hybrid, Smart End User: Residential, Commercial, Industrial, Government Installation Type: Standalone, Grid-Connected, Integrated, Temporary |
| Companies Covered | Signify Holding, Sunna Design, Greenshine New Energy, Solar Electric Power Company (SEPCO), Solar Street Lights USA, Fonroche Lighting, SolarOne Solutions, Gama Sonic, Sokoyo Solar Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Lights Market Trends and Innovations
Technology trajectories in solar lighting are converging around intelligence at the edge, battery chemistry diversification, and procurement model disintermediation. These forces collectively compress total cost of ownership while fragmenting traditional supply relationships.
Lithium iron phosphate cell chemistry is rewriting autonomy benchmarks for tropical deployments. The chemistry's thermal stability eliminates cooling overhead in 45°C ambient conditions prevalent across sub-Saharan Africa. Kenyan county governments now specify LFP-dominant systems in 5-year tender cycles. The technology is rewriting competitive differentiation away from lumen output toward guaranteed dusk-to-dawn operational reliability.
EU F-Gas Regulation phase-down mandates are accelerating hydrocarbon refrigerant adoption in solar-powered cold-chain lighting hybrids. The policy compresses allowable global warming potential thresholds for integrated cooling-luminaire systems. German agricultural cooperatives retrofitting vineyard frost-protection lighting face compliance deadlines driving replacement demand.
Municipal buyers are consolidating vendor relationships around performance-contracting structures that transfer operational risk to equipment suppliers. French departmental authorities now favor 10-year service agreements over capital purchase models. This behavioral pivot favors vertically integrated manufacturers with in-house installation and maintenance capabilities over component assemblers.
Solar Lights Market Segmentation
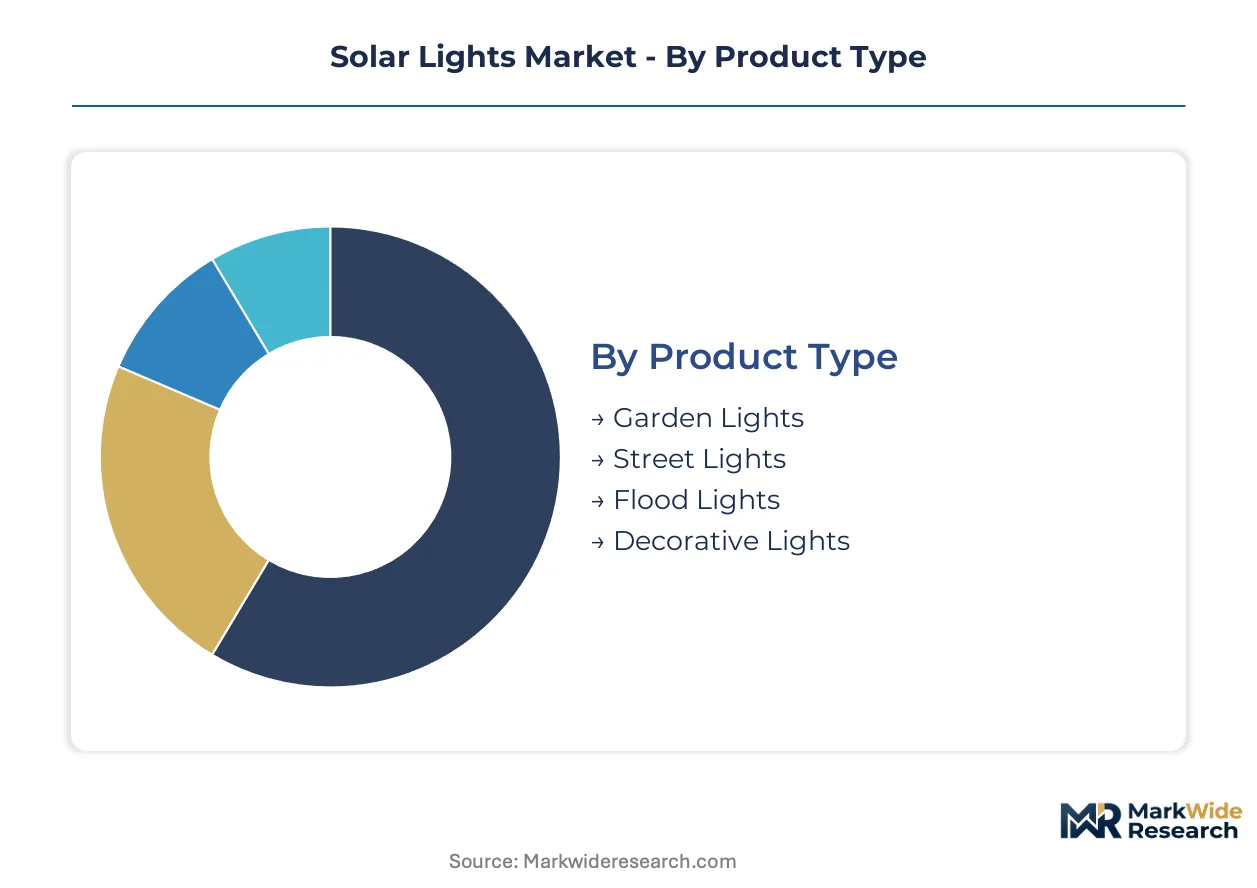
Segmentation in solar lighting reveals how certification burdens, autonomy requirements, and procurement scale reshape vendor strategy across product tiers. Each dimension carries distinct compliance thresholds and margin structures that determine competitive viability.
Product Type:
CE marking governs European street and flood luminaires, while BIS certification delays Indian garden light launches by 14-18 weeks. Decorative fixtures face lighter documentation loads, accelerating e-commerce penetration.
- Street Lights:Integrated photovoltaic panels, lithium iron phosphate storage, and 4000-6500K LED arrays deliver 50,000+ hour operational life. Municipal procurement in Uttar Pradesh and Bihar electrification corridors concentrates demand, with 10-year service agreements displacing capital purchase models.
- Garden Lights:Low-voltage stake-mounted systems with 5-15 watt monocrystalline panels and nickel-metal hydride or small lithium packs. Direct-to-installer channels on Alibaba and Jumia disintermediate wholesale layers for sub-100 unit residential orders.
- Flood Lights:High-lumen output systems (3000-20000 lumens) with motion sensing and dusk-to-dawn photocells. Commercial perimeter security applications in Nigerian rural electrification zones drive specification.
- Decorative Lights:String, lantern, and pathway aesthetic fixtures with minimal autonomy requirements. Seasonal demand spikes through Amazon and Flipkart retail channels dominate revenue timing.
Street Lights sits at the top of the volume ranking, with Garden Lights climbing the fastest.
Technology:
Cost tiers separate established photovoltaic-LED combinations from premium smart systems with IoT integration. Hybrid architectures command mid-tier positioning through diesel or grid backup redundancy.
- Smart:Mesh-networked controllers with adaptive dimming protocols, remote battery monitoring, and SCADA interoperability. French departmental authorities specify these for 40% conservation targets in performance-contracting structures.
- Photovoltaic:Standalone silicon wafer conversion with PWM or MPPT charge controllers. Crystalline silicon cost deflation below $0.30 per watt collapses breakeven thresholds for rural commercial adopters across sub-Saharan Africa.
- LED:Solid-state emitter technology with 90+ CRI options and 2700-6500K correlated color temperature ranges. Emitter efficacy gains now secondary to battery chemistry differentiation in vendor positioning.
- Hybrid:Solar-primary systems with grid-tie or generator backup for critical continuity. Kenyan county government specifications for tropical climate resilience favor this architecture in 5-year tender cycles.
Photovoltaic maintains volume leadership, though Smart systems gain share fastest through municipal IoT mandates.
End User:
Customer type determines contract structure, with government verticals demanding performance guarantees and residential segments prioritizing plug-and-play simplicity.
- Government:Federal, state, and municipal procurement with multi-year maintenance obligations. Nigeria's Rural Electrification Agency tenders specify 2.4 million integrated solar streetlight units with 5-year operational risk transfer to vendors.
- Residential:Individual household acquisition through retail and e-commerce channels. Indian peri-urban electrification gaps coincide with falling module costs to accelerate adoption in Bihar and Uttar Pradesh corridors.
- Commercial:Corporate campus, retail parking, and agricultural perimeter applications. German vineyard cooperatives retrofit frost-protection lighting under EU F-Gas Regulation compliance deadlines.
- Industrial:Warehouse exterior, mining site, and logistics yard illumination with ruggedized IP65+ enclosures. Operational continuity requirements drive hybrid specification over pure standalone systems.
Government commands the largest project scale, while Residential expands most quickly through channel disintermediation.
Installation Type:
Supply concentration in battery and panel sourcing shapes which installation architectures achieve cost competitiveness in which geographies.
- Standalone:Fully off-grid systems with no external electrical connection. Sunna Design anchors African market position through tropical-climate ruggedization of these units.
- Grid-Connected:Solar-primary with grid backup and net-metering compatibility. US municipal contracts favor this architecture where existing trenching permits grid interconnection.
- Integrated:Luminaire, panel, battery, and controller as single factory-sealed assembly. BIS certification complexity filters out low-cost uncertified imports in Indian procurement.
- Temporary:Rapid-deployment systems for construction sites, events, and emergency response. Reduced autonomy requirements enable lead-acid substitution despite inferior cycle life.
Standalone leads by deployment count, with Integrated climbing fastest through factory-sealed reliability guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uttar Pradesh electrification corridors concentrate procurement velocity for off-grid municipal infrastructure, while Bihar peri-urban zones accelerate residential adoption through falling photovoltaic module costs.
United States
US Department of Energy efficiency mandates and IRA tax credits drive municipal procurement of grid-connected solar street systems. Domestic manufacturing incentives favor locally assembled luminaires in federal infrastructure tenders. California and Texas urban corridors lead deployment scale through rapid-deployment contracting frameworks.
India
Uttar Pradesh and Bihar electrification gaps coincide with MNRE subsidized procurement mandates for off-grid street lighting. BIS certification requirements filter uncertified imports, compressing vendor qualification timelines. Peri-urban corridors in Maharashtra and Karnataka accelerate residential adoption through e-commerce channel penetration.
Germany
EU Green Deal carbon-border adjustment mechanisms favor European-assembled systems over Southeast Asian alternatives. F-Gas Regulation compliance deadlines drive agricultural cooperative retrofit demand for frost-protection lighting. Bavarian vineyard clusters specify hydrocarbon refrigerant hybrids under phasedown mandates.
Nigeria
Federal Ministry of Power rural electrification agency tenders specify 2.4 million integrated solar streetlight units with operational risk transfer to vendors. Lead-acid battery substitution persists in price-sensitive residential segments despite lithium iron phosphate maturation. Lagos and Abuja municipal corridors anchor commercial-scale procurement velocity.
France
Departmental authorities favor 10-year performance-contracting service agreements over capital purchase models. CE marking governs smart-city IoT-enabled luminaire specifications with adaptive dimming protocols. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur regional clusters consolidate vendor relationships around vertically integrated maintenance capabilities.
Solar Lights Market Competitive Landscape
Performance-contracting service agreements dominate the current landscape as municipal buyers transfer operational risk to equipment suppliers. The vendor base stratifies across vertically integrated manufacturers with in-house installation capabilities, component assemblers dependent on third-party maintenance networks, and regional specialists capturing tropical-climate ruggedization niches. Strategic archetypes include European smart-city integrators, African standalone unit specialists, and US domestic manufacturing champions. Competitive intensity centers on geographic expansion into Nigerian and Indian tender windows and technology licensing for IoT-enabled adaptive dimming protocols.
Among European-heritage lighting conglomerates, Signify Holding occupies a position exemplifying smart-city integration capabilities, while Sunna Design anchors the African-market specialist archetype through tropical-climate engineering focus. Greenshine New Energy represents the domestic-manufacturing champion model in US municipal contracting.
| Leading Market Players |
|---|
| Signify Holding |
| Sunna Design |
| Greenshine New Energy |
| Solar Electric Power Company (SEPCO) |
| Solar Street Lights USA |
| Fonroche Lighting |
| SolarOne Solutions |
| Gama Sonic |
| Sokoyo Solar Lighting |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between BIS-endorsed municipal systems and uncertified garden fixtures manifests in both pricing power concentration among qualified vendors and supply chain segmentation between laboratory-tested and direct-ship channels. Indian procurement mandates filter out low-cost imports through 14-18 week testing queues, while European CE marking creates parallel compliance tiers that reshape component sourcing economics.
Pricing Analysis
Input-cost pass-through from lithium carbonate volatility swings battery pack economics 40-60 percent annually, eroding margin predictability for fixed-price municipal contracts. Three-tier pricing structure across premium smart-city systems, standard photovoltaic standalone units, and economy lead-acid garden fixtures reflects certification burden and autonomy specification divergence. Cost compression in the economy tier intensifies as direct-to-installer e-commerce channels disintermediate wholesale markups. Government verticals exhibit lowest price sensitivity through performance-contracting structures, while African residential segments remain most cost-responsive.
Supply Chain Analysis
Workforce availability constraints in Vietnamese and Bangladeshi electronics assembly hubs are redirecting component finishing toward Indian domestic manufacturing zones under PLI scheme incentives. Photovoltaic wafer production concentrates in China, lithium iron phosphate cell output clusters in China and South Korea, and LED emitter fabrication spans Taiwan and Malaysia. Single-source vulnerability in Xinjiang polysilicon feedstock exposes downstream assemblers to forced-labor due diligence penalties. Distribution runs through municipal tender aggregators in India and Nigeria, direct-installer platforms in peri-urban corridors, and electrical wholesale networks in European smart-city deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in solar lighting rests on lithium iron phosphate chemistry maturation collapsing battery replacement cycles and enabling premium-tier service contracting. Cost-down trajectories in crystalline silicon modules simultaneously compress breakeven thresholds for rural commercial adopters.
For Market Incumbents: Acquire tropical-climate engineering capabilities to defend African market position against emerging Asian component assemblers. Backward integration into lithium iron phosphate cell production secures supply continuity against carbonate price volatility. Investment in BIS pre-certification testing infrastructure compresses Indian product launch timelines past monsoon installation windows.
For New Entrants and Emerging Players: Begin with Nigerian Rural Electrification Agency tender participation where 2.4 million unit procurement windows favor new vendor qualification. Peri-urban Indian residential segments offer penetrable white-space through Jumia and Alibaba B2B marketplace direct-installer channels. Lead with plug-and-play garden light simplicity rather than competing on municipal smart-city complexity.
For Investors and Strategic Acquirers: Consolidation pressure builds where performance-contracting service agreements favor vertically integrated manufacturers with captive installation and maintenance networks over pure component assemblers. Long-term viability centers on 10-year operational risk transfer capabilities and IoT-enabled adaptive dimming protocol ownership. Watch for EU carbon-border adjustment mechanism enforcement as inflection indicator for European assembly premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium iron phosphate supply insulates against carbonate volatility eroding municipal contract margins. |
| Performance-Contracting Service Agreement Expansion | Ten-year operational risk transfer to vendors displaces capital purchase models in French departmental procurement. |
| IoT-Enabled Adaptive Dimming Protocol Licensing | Mesh network interoperability captures 40 percent battery conservation premiums in smart-city tenders. |
| BIS Pre-Certification Testing Infrastructure Investment | Compressed laboratory queue access accelerates Indian product launches ahead of monsoon installation windows. |
| Direct-to-Installer E-Commerce Channel Development | Alibaba and Jumia B2B marketplace presence disintermediates wholesale layers for sub-100 unit residential orders. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down photovoltaic component supply tracking forms the analytical core of this study. Primary interviews with MNRE program officers, Nigerian Rural Electrification Agency tender administrators, French departmental procurement directors, Kenyan county government infrastructure leads, and Indian solar EPC contractors combined with secondary validation from BIS certification databases, EU Green Deal implementation documents, MNRE subsidy disbursement records, and lithium carbonate price indices. Cross-referencing installation volume claims against module import customs data and battery pack production disclosures enabled triangulation of market sizing.
Input-output matrix framing connects crystalline silicon wafer cost trajectories, lithium iron phosphate cell pricing, and LED emitter efficacy gains to end-user segment adoption elasticities across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user vertical, and installation architecture, with regional regulatory framework clusters as an industry-specific overlay. CAGRs were derived from polynomial curve fitting of historical procurement cycles and scenario-weighted elasticity assumptions. Forecast inputs incorporate MNRE subsidized procurement mandate trajectories and EU F-Gas Regulation compliance deadline clustering.
Several conditions sit outside the modeled scope, including forced-labor due diligence enforcement intensity in Xinjiang polysilicon sourcing and monsoon seasonality impacts on Indian installation velocity. Forecasts reflect assumptions about lithium carbonate price reversion and crystalline silicon module cost continuation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Portable Lamps Market
Lighting
US Indoor LED Lighting Market
Lighting
COB Photo Light Market
Lighting
Global Headlight Control Module Market
Lighting
Lighting Management System Market
Lighting
Industrial Lighting Cybersecurity Market
Lighting
Wireless Lighting Market
Lighting
Flexible Lighting Foils Market
Lighting
Dimmers Market
Lighting
Industrial OLED Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
Hazardous Lighting Market
Lighting
Germany Indoor LED Lighting Market
Lighting
High-End Lighting Market
Lighting
Europe Lighting Control Systems Market