
 Smart Industrial Illumination Market | 2026-2036
Smart Industrial Illumination Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Industrial Illumination Market Insights
ISO 50001 energy management certification is unwinding competitive access for suppliers lacking documented efficiency protocols. Signify leverages its vertical integration across LED modules and control software to sustain pricing power in European retrofit contracts. Acuity Brands anchors its position through deep R&D intensity in sensor-integrated luminaires for North American warehousing chains. Cree Lighting specializes in high-efficacy chip architectures that dominate heat-intensive machine shop environments.
Smart industrial illumination encompasses networked lighting systems engineered for factory floors, warehouses, and assembly operations, typically delivering 150-200 lumens per watt with integrated occupancy sensing and daylight harvesting protocols. These systems reduce energy draw through automated dimming while feeding operational data into facility management platforms. LED product types command the dominant installed base due to lumen depreciation rates below 30% over 50,000 hours, though OLED segments attract interest where uniform panel emission benefits quality control stations. Wireless technology adoption outpaces wired alternatives in brownfield retrofits where conduit replacement proves cost-prohibitive, while Bluetooth Mesh gains traction for its self-healing topology across sprawling warehousing facilities.
The U.S. Department of Energy's SSL program and EPA ENERGY STAR specifications shape minimum efficacy thresholds for qualifying products, while EU Ecodesign directives under the EU Green Deal mandate phased elimination of inefficient industrial luminaires. China's GB standards enforced by SAMR require domestic manufacturers to meet escalating efficacy tiers for factory certification compliance. Facility managers and OEM procurement teams must weigh interoperability commitments against protocol fragmentation as DALI, Zigbee, and proprietary mesh networks compete for backbone dominance in multi-vendor environments.
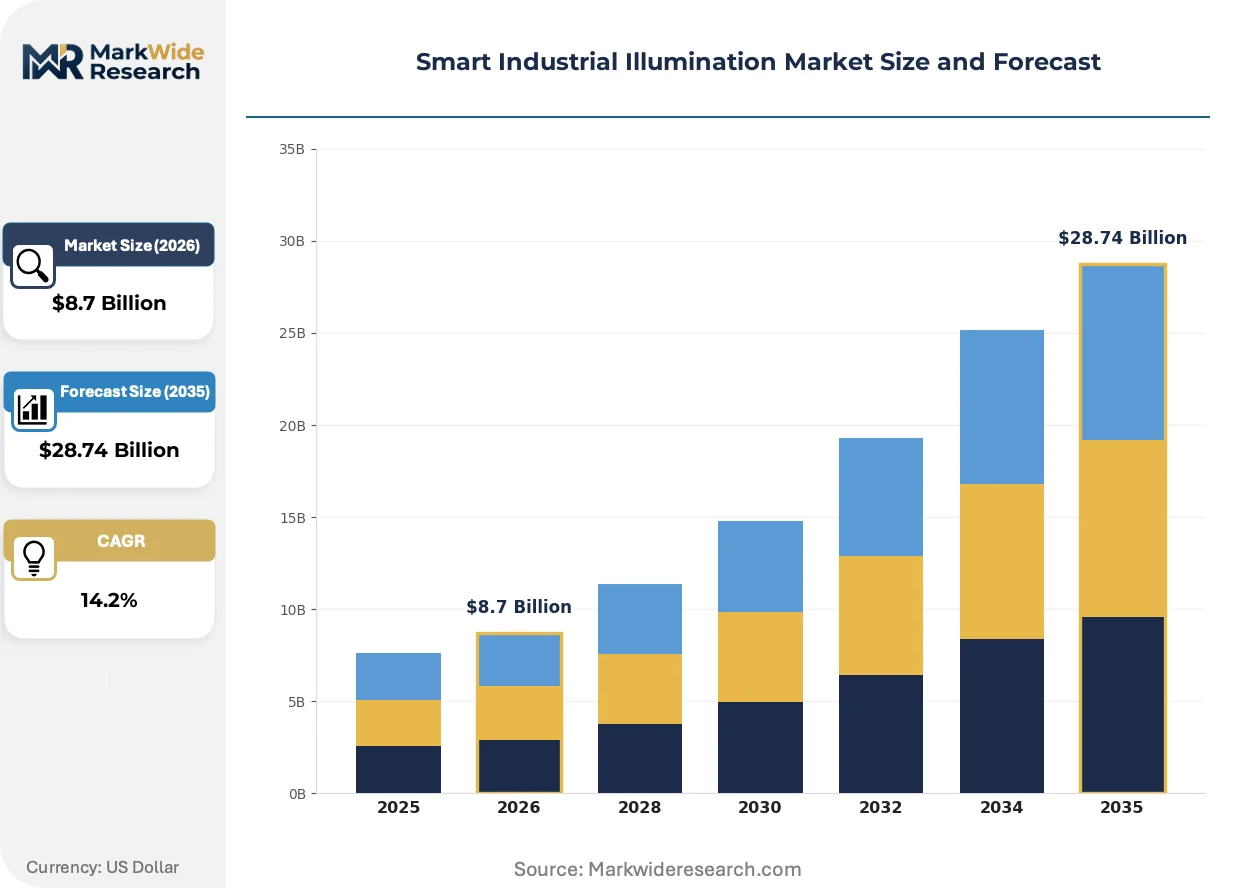
Market Dynamics
Retrofit momentum across brownfield manufacturing facilities is compressing replacement cycles as facility managers prioritize energy cost reduction over capital preservation. Wireless control architectures are displacing wired infrastructure where conduit access proves prohibitively expensive.
Growth Catalysts
- EU F-Gas Regulation:Phasedown mandates for high-global-warming-potential refrigerants in climate-controlled facilities accelerate LED transitions in European industrial zones.
- Automotive manufacturing clusters:Germany's automotive belt drives concentrated demand for precision illumination systems supporting quality control and robotic vision applications.
- Bluetooth Mesh topology:Self-healing network architectures reduce commissioning costs across sprawling warehousing facilities, enabling scalable deployment without backbone rewiring.
Market Restraints
- Protocol fragmentation:Competition between DALI, Zigbee, and proprietary mesh networks creates interoperability friction in multi-vendor environments, locking buyers into single-supplier ecosystems.
- Rare earth element concentration:Phosphor and magnet supply dependence on concentrated upstream sources introduces input cost volatility and geopolitical exposure.
- Legacy HID infrastructure:Existing high-bay sodium and metal halide installations with remaining functional life delay capital redeployment decisions.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced manufacturing create localized assembly demand for industrial-grade LED systems in emerging factory zones.
- Sensor-luminaire convergence:Integration of environmental monitoring, occupancy detection, and asset tracking into lighting hardware opens data monetization channels.
- China's dual carbon goals:National decarbonization targets enforced by MEE escalate factory energy audits, expanding retrofit service markets in Yangtze River Delta clusters.
Industry Challenges
- ISO 50001 documentation burden:Energy management certification requirements demand specialized compliance expertise that smaller installation contractors struggle to resource.
- Legacy control system integration:BACnet and Modbus interoperability gaps force costly middleware development for facility management platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Industrial Illumination Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Fluorescent, High-Intensity Discharge, Incandescent, Neon Technology: IoT-Enabled, Wired, Wireless, Bluetooth Mesh, Zigbee, DALI Application: Manufacturing Floors, Warehousing Facilities, Assembly Lines, Quality Control Stations, Packaging Areas, Machine Shops End User: OEMs, Tier-1 Component Makers, Facility Managers, Maintenance Crews, Safety Inspectors |
| Companies Covered | Signify, Acuity Brands, Zumtobel Group, TRILUX, Cree Lighting, Schneider Electric, Siemens, ABB, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Industrial Illumination Market Trends and Innovations
Illumination hardware is absorbing adjacent building systems functionality as sensor density increases and computing migrates to edge nodes. Control intelligence is decentralizing from central servers to luminaire-embedded processors.
Occupancy sensing hardware is miniaturizing through solid-state radar and passive infrared integration into LED driver form factors. Automotive paint shops and semiconductor cleanrooms in Germany and South Korea are adopting these embedded sensors at accelerated replacement cycles. Component consolidation is compressing bill-of-materials costs while enabling granular zone control without dedicated sensor infrastructure.
The EU Ecodesign directive under the EU Green Deal mandates phased elimination of inefficient industrial luminaires through minimum efficacy thresholds. Manufacturers must redesign optical systems and thermal management to maintain lumen output at reduced wattage. High-bay applications in Polish and Romanian logistics facilities face the most compressed compliance timelines.
Facility managers now bundle lighting retrofit decisions with broader energy performance contracting rather than treating illumination as isolated capex. Engineering-procurement-construction firms are displacing traditional electrical distributors as primary specification influencers. This consolidation is most pronounced in North American warehousing chains pursuing portfolio-wide standardization.
Smart Industrial Illumination Market Segmentation
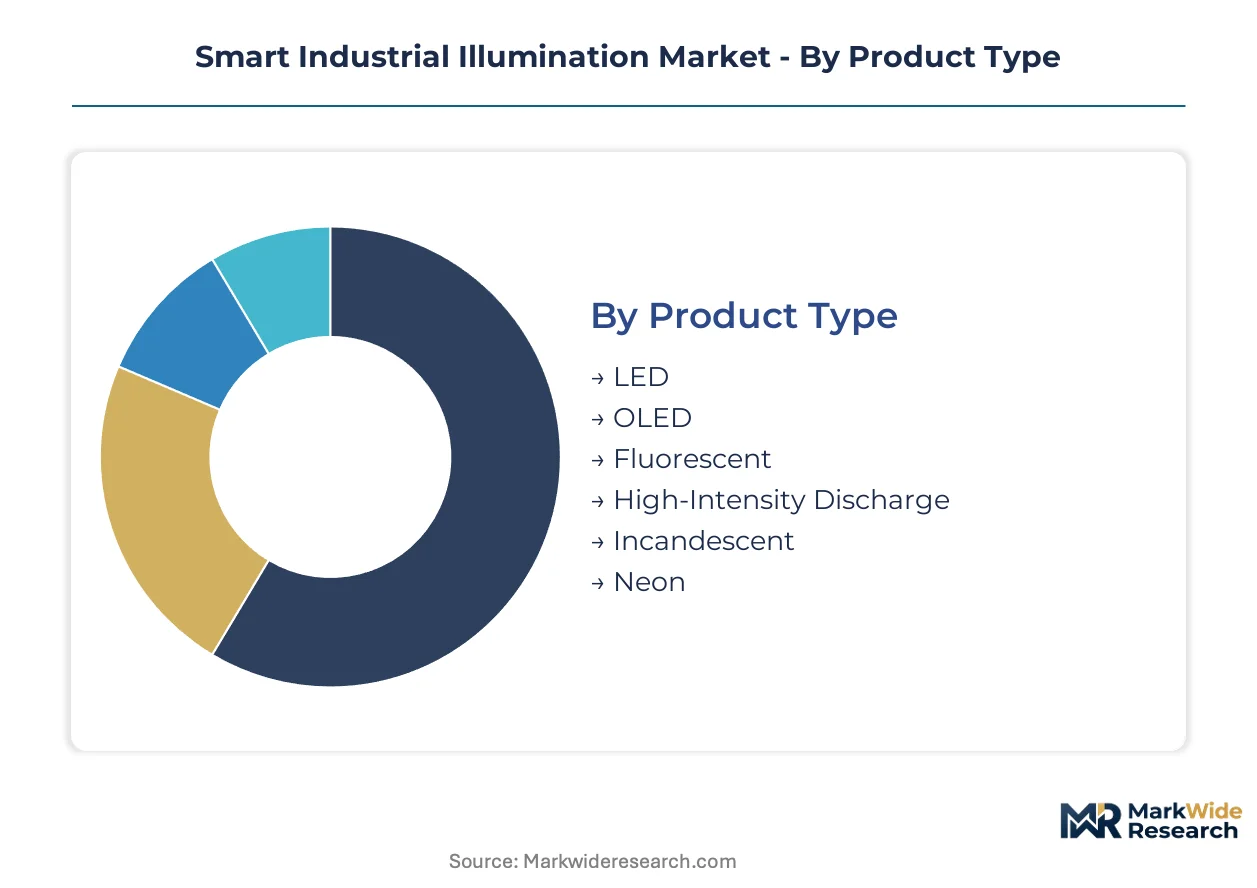
Segmentation in smart industrial illumination reveals distinct procurement patterns across product architectures, control protocols, and operational environments. Facility managers and OEM procurement teams prioritize different performance attributes based on retrofit constraints and energy audit mandates.
Product Type:
Electrical distributors and EPC firms push LED and OLED through retrofit contracts, while legacy HID moves through maintenance procurement channels for functional replacements.
- LED:Dominant solid-state architecture delivering 150-200 lumens per watt with lumen depreciation below 30% across 50,000 hours. Germany's automotive belt and China's Yangtze River Delta manufacturing clusters drive concentrated specification demand under EU Ecodesign and China's GB standards.
- OLED:Uniform panel emission technology attracting quality control station deployments where glare-free surface illumination benefits inspection protocols. Semiconductor cleanrooms in South Korea accelerate replacement cycles for these thin-form installations.
- Fluorescent:Legacy tube systems remaining in budget-constrained brownfield retrofits where capital preservation overrides efficiency gains.
- High-Intensity Discharge:Existing sodium and metal halide high-bay infrastructure delaying capital redeployment where functional life persists.
- Incandescent:Niche heat-lamp applications in specialized process heating, largely phased from general illumination.
- Neon:Signage and indicator applications marginal to industrial floor illumination, retained in legacy safety marking.
By volume, LED leads. By growth pace, OLED is gaining share fastest.
Technology:
Control protocol selection determines margin structure, with proprietary mesh networks commanding premium pricing against open-standard alternatives.
- IoT-Enabled:Cloud-connected architectures feeding operational data into facility management platforms. North American warehousing chains specify these systems for portfolio-wide energy performance contracting.
- Wired:DALI and proprietary bus systems preferred in greenfield construction where conduit access is planned. Polish and Romanian logistics facilities face compressed compliance timelines under EU Ecodesign mandates.
- Wireless:Radio-frequency architectures displacing wired infrastructure where conduit replacement proves cost-prohibitive in brownfield manufacturing floors.
- Bluetooth Mesh:Self-healing topology reducing commissioning costs across sprawling warehousing facilities without backbone rewiring.
- Zigbee:Low-power mesh alternative competing for backbone dominance in multi-vendor environments with interoperability friction.
- DALI:Digital addressable lighting interface standard mandated in European public procurement and spreading to industrial specification.
Retrofit channels favor wireless. New construction specifications tilt toward wired.
Application:
Machine shops and quality control stations command pricing premiums against warehousing volume plays.
- Manufacturing Floors:High-bay and task lighting systems supporting continuous production environments. India's PLI scheme for advanced manufacturing creates localized assembly demand in emerging factory zones.
- Warehousing Facilities:Aisle-optimized illumination with occupancy sensing and daylight harvesting protocols. Engineering-procurement-construction firms displace traditional distributors as primary specification influencers here.
- Assembly Lines:Precision task lighting with color rendering critical for defect detection.
- Quality Control Stations:Uniform illumination requirements driving OLED interest and embedded sensor integration for environmental monitoring.
- Packaging Areas:Moderate-specification general illumination with standard occupancy controls.
- Machine Shops:Heat-intensive environments where Cree Lighting's high-efficacy chip architectures dominate thermal management requirements.
Warehousing delivers volume concentration. Quality control stations generate margin expansion.
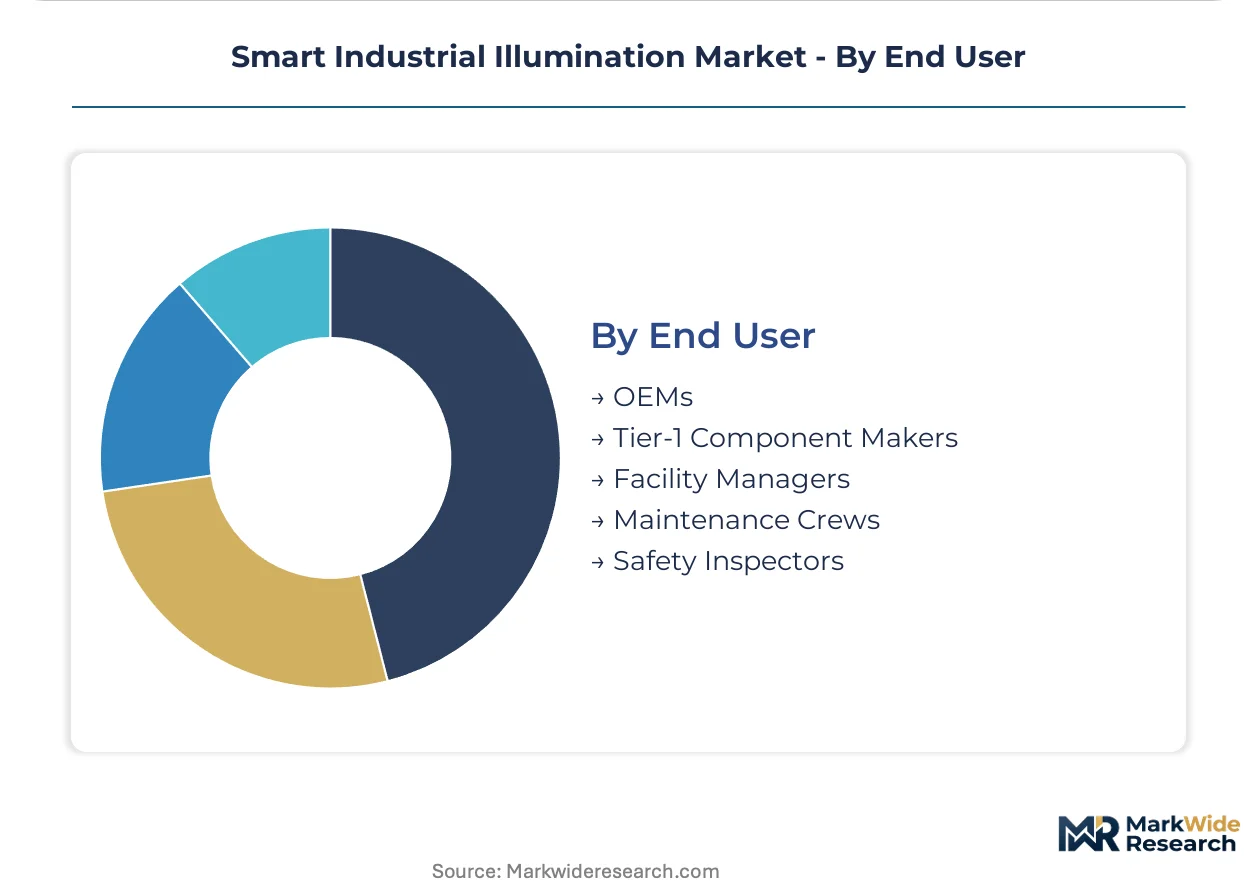
End User:
OEM procurement teams and facility managers diverge on interoperability commitments versus protocol fragmentation tolerance.
- OEMs:Original equipment manufacturers specifying integrated lighting for machinery and production lines. Signify leverages vertical integration across LED modules and control software to sustain pricing power in these European retrofit contracts.
- Tier-1 Component Makers:Automotive and electronics suppliers in Germany's automotive belt driving precision illumination for robotic vision applications.
- Facility Managers:Building operators bundling lighting retrofit decisions with broader energy performance contracting rather than isolated capex treatment.
- Maintenance Crews:Reactive procurement channels for replacement lamps and ballasts, price-sensitive and specification-flexible.
- Safety Inspectors:Compliance-driven specification for emergency and egress lighting meeting OSHA and national workplace safety requirements.
Facility managers control retrofit growth. OEMs anchor new equipment attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation and the EU Green Deal are accelerating LED transitions across European industrial zones. Manufacturing floors in Germany's automotive belt and China's Yangtze River Delta drive concentrated adoption. Facility managers in India leverage PLI scheme incentives for localized assembly.
United States
North American warehousing chains specify IoT-enabled systems for portfolio-wide energy performance contracting. EPA ENERGY STAR specifications shape minimum efficacy thresholds for qualifying products. The Department of Energy's SSL program influences procurement across Midwest manufacturing corridors.
Germany
Automotive manufacturing clusters demand precision illumination supporting quality control and robotic vision applications. EU Ecodesign directives mandate phased elimination of inefficient industrial luminaires. Bavaria's machine shops and Baden-Württemberg's Tier-1 component makers dominate specification volume.
China
National decarbonization targets enforced by MEE escalate factory energy audits across manufacturing zones. GB standards from SAMR require domestic manufacturers to meet escalating efficacy tiers. The Yangtze River Delta manufacturing clusters expand retrofit service markets under dual carbon goals.
India
Production-linked incentives for advanced manufacturing create localized assembly demand in emerging factory zones. CEA compliance requirements shape procurement protocols for industrial-grade systems. Maharashtra and Gujarat industrial corridors concentrate specification activity for LED transitions.
South Korea
Semiconductor cleanrooms accelerate replacement cycles for thin-form OLED installations. MFDS-adjacent workplace standards influence illumination specifications in precision manufacturing. Gyeonggi-do and Chungcheongnam-do electronics clusters drive embedded sensor integration demand.
Smart Industrial Illumination Market Competitive Landscape
Player mix skews toward diversified electrical conglomerates with captive lighting divisions. Market structure shows moderate consolidation around vertically integrated suppliers and specialized component architects. Three archetypes dominate: full-stack control-software integrators, high-efficacy chip specialists, and sensor-luminaire convergence players. Competitive moves center on backward integration into LED module production and strategic partnerships for wireless protocol standardization.
Among Netherlands-based lighting conglomerates, Signify occupies a position exemplifying full-stack integration across LED modules and control software. Acuity Brands, an American corporation, represents the sensor-integrated luminaire archetype for North American warehousing applications. Cree Lighting anchors the high-efficacy chip specialist tier, with its name indicating concentration on solid-state illumination architectures.
| Leading Market Players |
|---|
| Signify |
| Acuity Brands |
| Zumtobel Group |
| TRILUX |
| Cree Lighting |
| Schneider Electric |
| Siemens |
| ABB |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Asian LED chip foundries compresses margin floors for downstream luminaire assemblers while concentrating pricing power among module suppliers with captive wafer capacity. This scale asymmetry forces tier-2 fixture manufacturers to absorb input volatility or cede share to vertically integrated competitors.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with ISO 50001-documented suppliers commanding project-based pricing against transactional spot purchasing for uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by interoperability depth and after-sales service bundling. Cost compression in the economy tier intensifies as Chinese GB-standard compliance becomes table stakes. Maintenance crews exhibit highest price sensitivity, while facility managers pursuing energy performance contracting prioritize lifecycle value over upfront unit cost.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains inbound logistics costs for phosphor and driver component shipments to European assembly plants. Module production concentrates in China, Taiwan, and South Korea, with rare earth phosphor supply drawing from concentrated upstream sources in China and Myanmar. Single-source vulnerability for specialized LED chips introduces geopolitical exposure. Distribution runs through engineering-procurement-construction firms displacing traditional electrical distributors in North American warehousing retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth Mesh protocol standardization and EU Ecodesign mandate acceleration are compressing replacement cycles, creating a high-growth disruption window for positioning across retrofit channels.
For Market Incumbents: Shield retrofit contract margins by deepening backward integration into LED driver production and securing ISO 50001 certification coverage across installation partner networks. Wireless protocol fragmentation threatens lock-in advantages; prioritize DALI-2 interoperability investments to defend specification influence in European public procurement. For New Entrants and Emerging Players: Differentiate on sensor-luminaire convergence for quality control station applications in South Korean semiconductor cleanrooms and German automotive paint shops. India's PLI scheme for advanced manufacturing offers the most penetrable geography for localized assembly partnerships. Pursue EPC firm direct relationships rather than distributor channel buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among control-software integrators with SaaS-tiered service contracts feeding facility management platforms. Five-to-ten year viability favors sensor-luminaire convergence players with embedded radar and PIR integration capabilities. Watch for inflection when EU F-Gas Regulation phase-down accelerates climate-controlled facility retrofit mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Modules | Captures margin compression from Asian chip foundry concentration for European retrofit specialists. |
| Bluetooth Mesh Certification Program | Reduces commissioning friction across sprawling warehousing facilities for North American EPC partners. |
| Sensor-Luminaire Convergence R&D | Enables environmental monitoring monetization in German automotive quality control stations. |
| ISO 50001 Compliance Investment | Unlocks European public procurement access under EU Green Deal energy audit mandates. |
| Joint Venture in India PLI Zones | Localizes assembly capacity for Maharashtra and Gujarat industrial corridor retrofit demand. |
Research Methodology
Operator-level perspectives from facility managers, EPC specification engineers, OEM procurement teams, and lighting maintenance directors anchored the qualitative base. Primary interviews triangulated with secondary validation from EPA ENERGY STAR product databases, EU Ecodesign directive compliance registries, SAMR GB standards filings, and customs trade data for LED module import flows. Bottom-up installation volume estimates and top-down market sizing converged through iterative reconciliation.
Sensitivity analysis tested forecast robustness across protocol adoption scenarios and regulatory enforcement intensity variations throughout the projection horizon. Segmentation dimensions modeled include product architecture, control protocol, application environment, and end-user procurement archetype. CAGRs derived from logistic diffusion curves fitted to retrofit penetration rates and replacement cycle compression patterns. Industry-specific inputs incorporated EU F-Gas Regulation phase-down schedules and China's dual carbon audit enforcement timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation and stable rare earth supply access; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as Bluetooth Mesh standardization progress and India PLI scheme expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Xenon Flashlamps Market
Lighting
Hazardous Lighting Market
Lighting
Specialty Lighting Market
Lighting
Solid State Lighting System Market
Lighting
Lighting Product Market
Lighting
Display Light Control Film Market
Lighting
Smart Lamp Market
Lighting
Dimmer and Color Tunable Market
Lighting
Global Work Lights Market
Lighting
Global Lighting Control System Market
Lighting
Softbox Lighting Kit Market
Lighting
North America Street Lighting Market
Lighting
Photography Light Box Market
Lighting
Circadian Lighting Market
Lighting
Intelligent Lighting Market
Lighting
North America Outdoor Lighting Market