
 Global Intelligent Flow Meter Market | 2026-2036
Global Intelligent Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
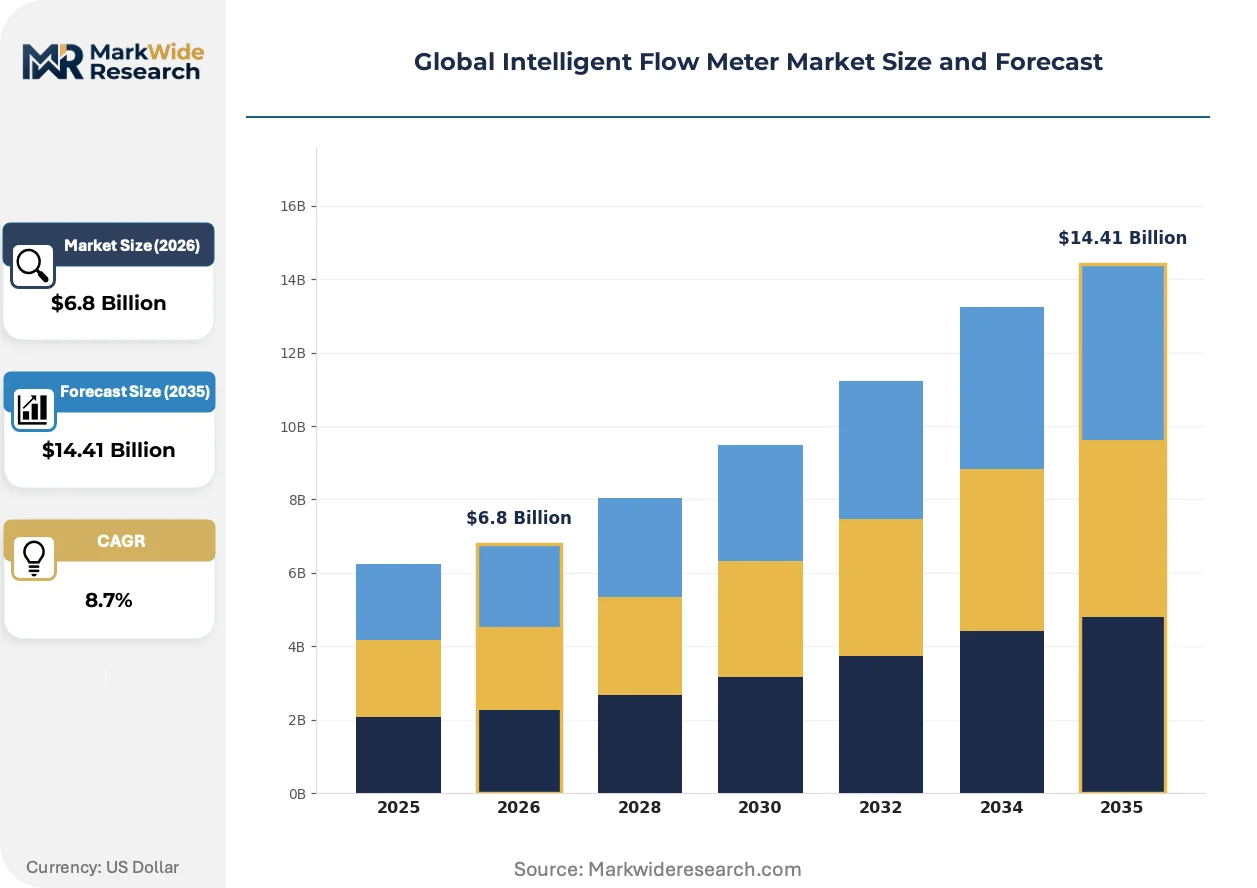
Global Intelligent Flow Meter Market Outlook
Germany's industrial automation corridor is reshaping competitive dynamics for intelligent flow instrumentation. Emerson Electric leverages its Rosemount measurement platform to dominate custody transfer applications in hydrocarbon processing. Yokogawa Electric Corporation anchors Asian supply networks through specialized vortex and magnetic flow meter production. ABB Ltd. differentiates via integrated digital twin compatibility across its Process Automation division.
An intelligent flow meter combines primary sensing elements with embedded microprocessors, communication protocols, and diagnostic algorithms to deliver real-time volumetric or mass flow measurement with accuracy typically ranging from ±0.1% to ±0.5% of reading. These instruments serve critical process control, billing verification, and regulatory compliance functions across fluid handling industries. Electromagnetic and ultrasonic product types command the widest installed base due to non-intrusive measurement and minimal pressure loss characteristics. Smart sensor and IoT integration technologies are expanding fastest as end users prioritize predictive maintenance and cloud-connected asset management over standalone analog devices.
The EPA mandates flow monitoring for Clean Water Act discharge permits, while IEC 61508 and IEC 61511 standards enforce safety instrumented system integrity for meters in hazardous process loops. FDA 21 CFR Part 11 compliance shapes pharmaceutical sector procurement specifications for electronic records and audit trails. Stakeholders must evaluate how evolving cybersecurity frameworks for operational technology networks will reshape hardware authentication requirements and software update protocols across distributed meter fleets.
Market Dynamics
The EU F-Gas Regulation is compressing deployment timelines for refrigerant-dependent meter technologies while accelerating ultrasonic and Coriolis alternatives across European hydrocarbon processing facilities. IEC 61508 functional safety mandates are simultaneously forcing hardware redesign cycles for safety instrumented systems.
Growth Catalysts
- Ultrasonic technology maturation:Non-intrusive measurement eliminates pressure drop penalties in custody transfer pipelines. Oil and gas operators in the Permian Basin and North Sea are retrofitting differential pressure installations.
- EPA Clean Water Act enforcement:Discharge permit mandates require continuous flow monitoring at municipal wastewater treatment facilities. Utilities face penalties for non-compliance.
- India:The PLI scheme for precision instrumentation is attracting component manufacturing to Pune and Bengaluru industrial corridors. Domestic production reduces import dependency for magnetic flow meter coils.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependency for electromagnetic meters concentrates in Chinese processing facilities. Price volatility disrupts cost forecasting.
- Coriolis meter fabrication complexity:Precision tube bending and welding requirements limit qualified supplier pools. Lead times extend to 26 weeks for high-pressure hydrogen service.
- IEC 61508 SIL certification:Third-party validation for safety instrumented systems adds 14-18 months to product launch schedules. Smaller manufacturers lack capital for parallel certification tracks.
Strategic Opportunities
- Brazil:ANVISA pharmaceutical manufacturing expansion creates demand for FDA 21 CFR Part 11 compliant sanitary flow meters. Local calibration infrastructure remains underdeveloped.
- Digital twin convergence:Integration of real-time flow data with ABB Ability and Siemens Xcelerator platforms enables predictive maintenance contracts. Asset performance management software vendors seek hardware partnerships.
- Saudi Arabia:SABIC and Aramco downstream expansion mandates intelligent instrumentation for flare gas monitoring and carbon intensity tracking. Royal Commission environmental permits specify smart meter architectures.
Industry Challenges
- Embedded systems cybersecurity:IEC 62443 certification for operational technology networks requires firmware architecture redesign. Legacy fieldbus protocols lack native encryption.
- Metrology technician scarcity:Custody transfer calibration demands specialized training in gravimetric proving systems. Vocational programs in Houston and Rotterdam cannot match replacement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Flow Meter Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Ultrasonic, Differential Pressure, Vortex Technology: Smart Sensor, Remote Monitoring, Data Analytics, IoT Integration End User: Water Utilities, Oil & Gas, Chemical Processing, Pharmaceuticals Installation: Indoor, Outdoor, Permanent, Portable |
| Companies Covered | Siemens AG, Emerson Electric, ABB Ltd., Yokogawa Electric Corporation, Endress+Hauser, Honeywell International, Azbil Corporation, Sierra Instruments, Badger Meter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Flow Meter Market Strategic Shifts
Edge computing architectures are redistributing diagnostic intelligence from centralized control rooms to field-mounted devices. This shift compresses response latency for process anomalies while altering hardware design priorities.
Multipath ultrasonic arrays with beam steering capabilities are digitizing custody transfer measurement in natural gas pipelines. Midstream operators in the Appalachian Basin and Dutch Groningen field are replacing orifice plate installations. The technology eliminates mechanical wear points while enabling bidirectional flow computation for storage injection cycles.
The EU F-Gas Regulation phase-down schedule is accelerating refrigerant leak detection mandates across industrial refrigeration networks. Food processing facilities in Germany and France must install continuous monitoring for systems above 50 kg charge. Meter suppliers are integrating infrared spectroscopy modules to distinguish refrigerant species from background gases.
Lifecycle service contracting is displacing capital equipment sales in municipal water utilities. Veolia and Suez are bundling flow instrumentation with calibration and data analytics under 15-year agreements. The model concentrates procurement authority at corporate headquarters rather than distributed plant engineering departments.
Global Intelligent Flow Meter Market Segmentation
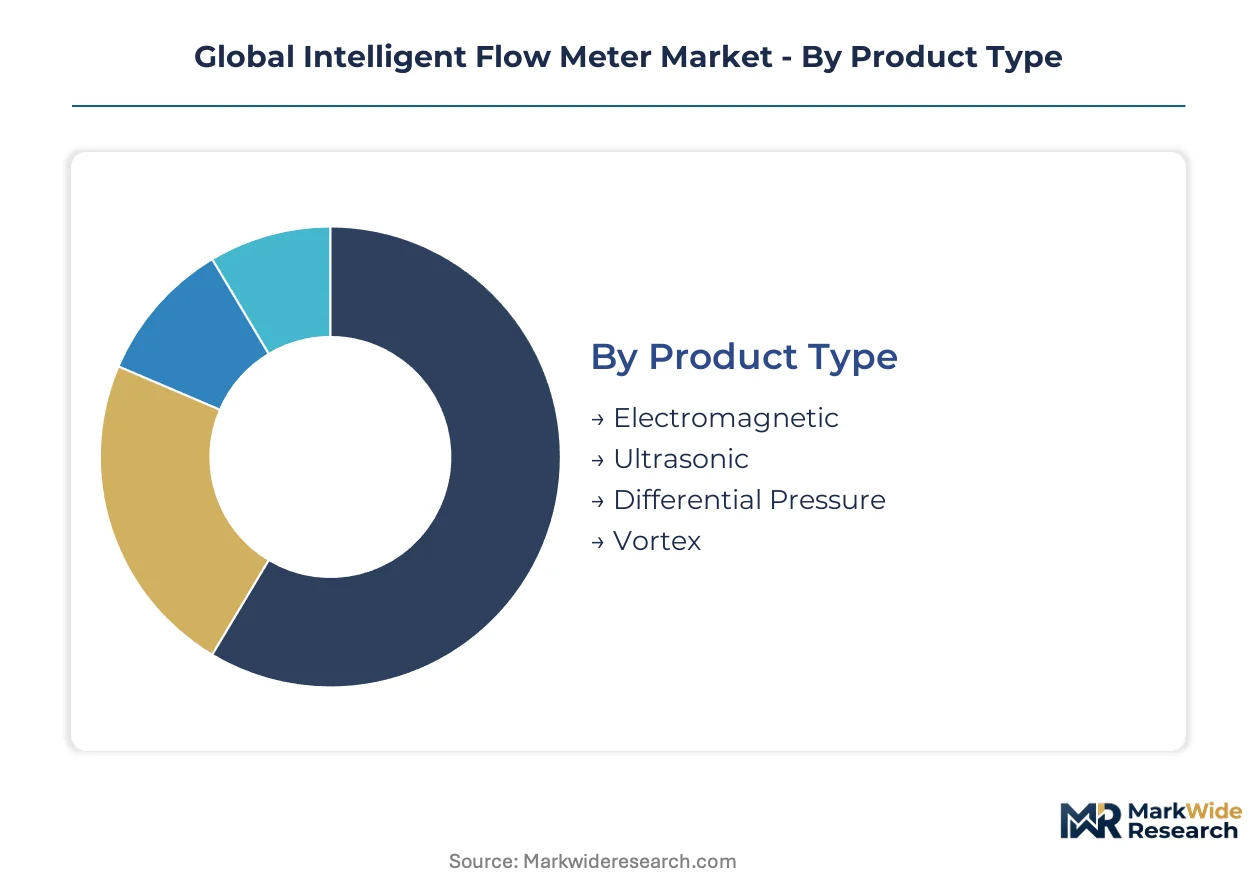
Intelligent flow meter segmentation reveals divergent service intensity patterns across product architectures. Electromagnetic and ultrasonic variants demand specialized calibration protocols, while technology tiers determine software update frequency and predictive maintenance contract structures.
Product Type:
After-sales-service intensity varies sharply across primary sensing architectures, with custody transfer applications requiring traceable calibration chains.
- Electromagnetic:Faraday's law-based measurement using excitation coils and paired electrodes delivers conductive fluid accuracy without flow obstruction. Water utilities in Germany specify these for billing-grade applications where magnetic susceptibility conflicts with ultrasonic alternatives.
- Ultrasonic:Transit-time or Doppler principles enable non-intrusive installation with zero pressure drop. Oil and gas operators in the Permian Basin and North Sea are retrofitting differential pressure installations for custody transfer pipelines where mechanical wear threatens measurement integrity.
- Differential Pressure:Orifice plates and venturi tubes remain cost-effective for high-temperature steam service.
- Vortex:Von Kármán shedding suits clean liquids and gases with moderate turndown requirements.
Electromagnetic holds the largest share; momentum sits with ultrasonic as midstream operators prioritize non-intrusive architectures.
Technology:
Technology tiers stratify by data processing location, with edge-mounted diagnostics commanding premium service attach rates.
- Smart Sensor:Embedded microprocessors enable local signal conditioning, fault detection, and digital communication without external controllers. Chemical processing facilities in the US Gulf Coast deploy these for SIL-rated safety loops where IEC 61508 mandates self-diagnostic capabilities.
- IoT Integration:Cloud-connected architectures support fleet-wide asset management and over-the-air firmware updates. Municipal water utilities in Singapore and Copenhagen are bundling these with 15-year lifecycle service contracts that transfer operational risk to instrumentation vendors.
- Remote Monitoring:Cellular or Ethernet backhaul enables centralized diagnostics for distributed installations.
- Data Analytics:Pattern recognition algorithms predict drift and recommend calibration intervals.
Smart Sensor dominates installed value; IoT Integration is expanding most quickly as utilities outsource asset management.
End User:
End-user concentration shapes regional manufacturing footprints, with pharmaceutical demand anchoring FDA 21 CFR Part 11 compliance investments.
- Oil & Gas:Custody transfer, flare gas monitoring, and allocation measurement demand ±0.1% accuracy with metrological traceability. Saudi Aramco and SABIC downstream expansions specify intelligent architectures for carbon intensity tracking under Royal Commission environmental permits.
- Pharmaceuticals:Sanitary design, electropolished surfaces, and electronic batch records satisfy FDA and EMA validation requirements. ANVISA manufacturing expansion in Brazil is outpacing local calibration infrastructure for CIP/SIP-compatible electromagnetic meters.
- Water Utilities:EPA Clean Water Act discharge mandates drive continuous monitoring retrofits.
- Chemical Processing:Aggressive media compatibility and hazardous area certification dominate procurement.
Oil & Gas retains the deepest value pool; Pharmaceuticals is climbing the fastest on regulatory compliance spending.
Installation:
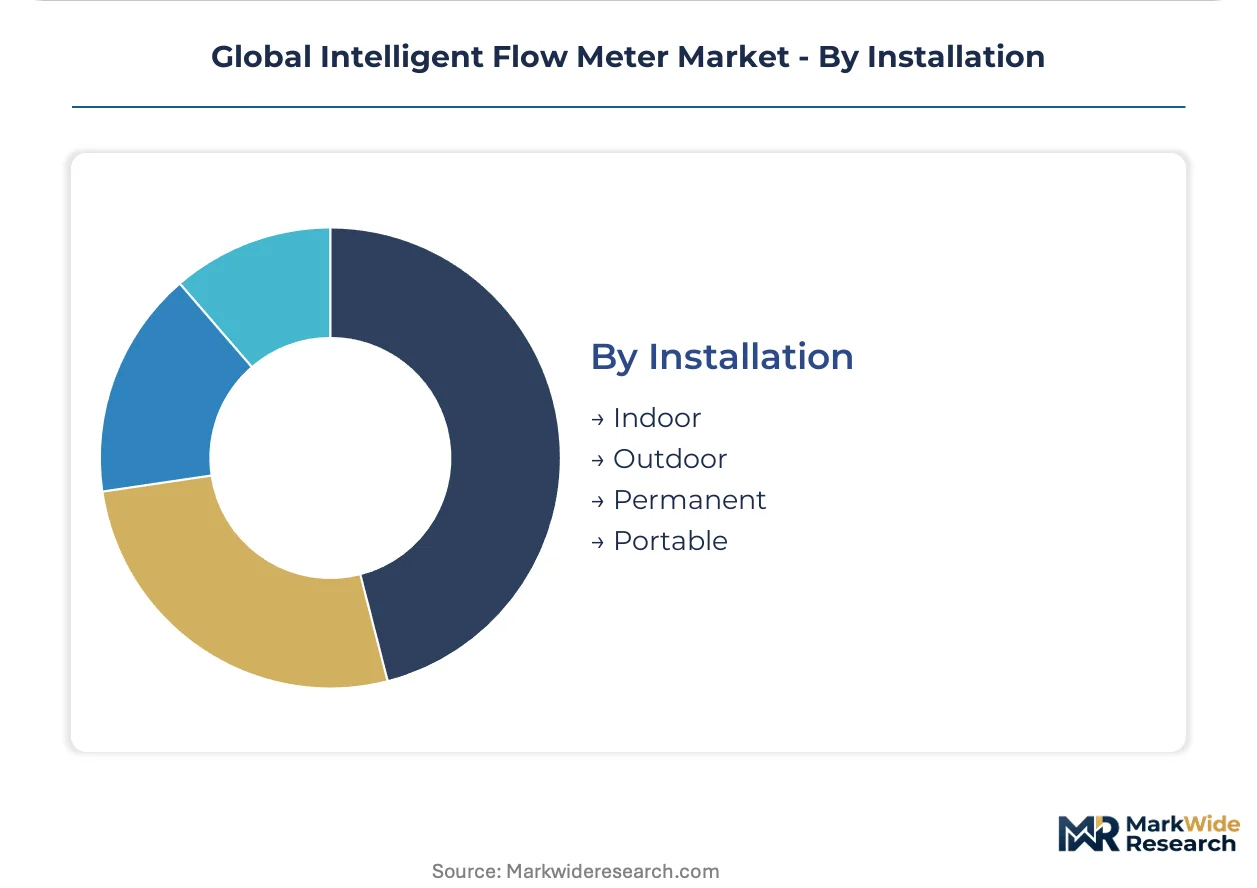
Installation mode determines enclosure specifications and commissioning complexity, with portable units requiring rental fleet logistics.
- Permanent:Fixed pipeline installation with hardwired power and signal connections supports 20-year design life. German industrial automation corridors standardize these for process control loops where unplanned shutdowns cost millions.
- Outdoor:NEMA 4X or IP66 enclosures withstand temperature cycling and moisture ingress.
- Indoor:Controlled environment specifications reduce enclosure costs for utility buildings.
- Portable:Battery-powered clamp-on ultrasonic units enable spot measurement and verification.
Permanent installation commands the greatest volume; portable configurations are gaining share fastest in verification and temporary measurement applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes intelligent flow meters primarily for process control loops in chemical processing corridors, whereas Saudi Arabia deploys identical hardware for flare gas monitoring and carbon intensity tracking under environmental permit mandates. This consumption-mix differential shapes regional supplier footprints and service contract structures.
United States
Midstream operators in the Permian Basin and Appalachian Basin retrofit differential pressure installations with multipath ultrasonic arrays for custody transfer pipelines. EPA Clean Water Act enforcement mandates continuous flow monitoring at municipal wastewater facilities across Texas and Pennsylvania. Houston anchors gravimetric proving system calibration infrastructure, though vocational programs cannot match technician replacement rates.
Germany
Industrial automation corridors in Bavaria and Baden-Württemberg standardize permanent-installation electromagnetic meters for billing-grade water utility applications. EU F-Gas Regulation phase-down schedules accelerate refrigerant leak detection mandates across food processing facilities in France and Germany. Siemens AG and Endress+Hauser anchor precision instrumentation manufacturing clusters around Munich and Freiburg.
Saudi Arabia
SABIC and Aramco downstream expansion projects specify intelligent architectures for flare gas monitoring and carbon intensity tracking. Royal Commission environmental permits mandate smart meter architectures for new petrochemical installations. The Eastern Province concentrates procurement authority for instrumentation serving Jubail Industrial City and Yanbu complexes.
India
PLI scheme incentives for precision instrumentation attract component manufacturing to Pune and Bengaluru industrial corridors, reducing import dependency for magnetic flow meter coils. Domestic production capacity expands for excitation coil assemblies previously sourced from Chinese rare earth processing facilities. Maharashtra and Karnataka state industrial policies prioritize instrumentation cluster development.
Brazil
ANVISA pharmaceutical manufacturing expansion creates demand for FDA 21 CFR Part 11 compliant sanitary flow meters for CIP/SIP-compatible process lines. Local calibration infrastructure for electromagnetic meter verification remains underdeveloped relative to installation growth. São Paulo state concentrates pharmaceutical production capacity requiring validated electronic batch records.
Global Intelligent Flow Meter Market Competitive Environment
Capability concentration sits with specialized instrumentation houses possessing SIL certification expertise and metrological traceability chains; scale advantage sits with diversified industrial conglomerates leveraging cross-divisional digital platform integration. The market structures around three tiers: custody transfer specialists with gravimetric proving capabilities, process automation generalists bundling flow measurement with control systems, and component suppliers feeding magnetic coil and ultrasonic transducer demand. Dominant competitive moves include M&A to acquire SIL-rated product portfolios and strategic partnerships with asset performance management software vendors.
Within the custody transfer specialist tier, Emerson Electric and Endress+Hauser occupy positions defined by metrological accreditation depth and safety instrumented system certification breadth. Yokogawa Electric Corporation exemplifies the Asian supply network anchor archetype, while ABB Ltd. represents the integrated digital platform vector through its Process Automation division. Siemens AG anchors German manufacturing clusters for precision instrumentation. These named entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Siemens AG |
| Emerson Electric |
| ABB Ltd. |
| Yokogawa Electric Corporation |
| Endress+Hauser |
| Honeywell International |
| Azbil Corporation |
| Sierra Instruments |
| Badger Meter |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese rare earth magnet processing facilities is compressing excitation coil pricing while forcing electromagnetic meter suppliers toward ultrasonic and Coriolis alternatives. This utilization dynamic simultaneously erodes margin buffers in the magnetic flow meter tier and accelerates supplier migration toward certification-intensive architectures where pricing power persists.
Pricing Analysis
Long-term service contracts dominate intelligent flow meter procurement, with municipal water utilities and oil and gas operators locking in 10-15 year lifecycle agreements that bundle hardware, calibration, and predictive analytics. Price differentiation rests on SIL certification tier and metrological traceability depth, with IEC 61508-validated instruments commanding substantial premiums over standard process control variants. Cost compression in the electromagnetic segment intensifies as neodymium price volatility disrupts cost forecasting for Faraday-law-based designs. Chemical processing facilities exhibit lowest price sensitivity due to hazardous area certification requirements, while municipal utilities in emerging markets drive hardest bargain on upfront capital outlays.
Supply Chain Analysis
Contract manufacturing for ultrasonic transducer assemblies concentrates in South Korea and Japan, while precision tube bending for Coriolis meters anchors in Germany and Switzerland. Rare earth magnet supply draws from Chinese processing facilities, with secondary sourcing from Vietnamese and Australian mines. Single-source vulnerability in neodymium oxide refining creates exposure to export quota shifts. Distribution runs through authorized system integrators and direct OEM sales forces, with aftermarket service contracts increasingly disintermediating traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal water utility consolidation into regional operating companies like Veolia and Suez is shifting procurement authority from plant engineers to corporate headquarters, concentrating buyer power and favoring vendors with integrated service capabilities.
For Market Incumbents: Build certification moats through parallel IEC 61508 SIL and IEC 62443 cybersecurity validation tracks that smaller competitors cannot fund. Expand gravimetric proving system capacity in Houston and Rotterdam to address metrology technician scarcity threatening custody transfer service revenue. Threat substitution from clamp-on ultrasonic retrofits demands defensive positioning in differential pressure replacement cycles. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA pharmaceutical corridor where local calibration infrastructure lags manufacturing expansion. Target portable verification services for midstream oil and gas operators requiring spot measurement without pipeline shutdown. Go-to-market through rental fleet partnerships with industrial equipment distributors bypasses incumbent direct sales networks. For Investors and Strategic Acquirers: Capital is best deployed toward SIL-certified product specialists with captive metrological traceability chains rather than undifferentiated hardware assemblers. Long-term viability favors vendors integrating edge computing diagnostics with asset performance management platforms. Watch for inflection in Saudi Aramco and SABIC instrumentation specifications that would validate smart meter architectures for carbon intensity tracking.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61508 SIL Certification Investment | Third-party validation opens safety instrumented system procurement at SABIC and Aramco facilities. |
| Backward Integration into Transducer Manufacturing | In-house ultrasonic sensor production reduces dependency on South Korean contract manufacturers. |
| Digital Twin Platform Partnership | Integration with ABB Ability and Siemens Xcelerator enables predictive maintenance contract bundling. |
| Regional Calibration Infrastructure Buildout | Gravimetric proving systems in São Paulo and Bengaluru capture pharmaceutical and PLI-scheme demand. |
| Cybersecurity Firmware Architecture Redesign | IEC 62443 compliance addresses operational technology network mandates from EU regulators. |
Study Parameters
Initial hypotheses were tested against primary input from instrumentation procurement managers at oil and gas operators, metrology technicians at gravimetric proving facilities, and regulatory compliance officers at pharmaceutical manufacturers, then refined through secondary validation. Bottom-up demand modeling drew from EPA discharge permit filings, EU F-Gas Regulation implementation timelines, and ANVISA manufacturing license databases. Top-down supply assessment incorporated customs data on magnetic flow meter coil imports and IEC certification registry analysis.
Demand-supply balance across the analysis window was modeled through segmentation by product architecture, technology tier, and end-user concentration, with CAGRs derived from installed base replacement cycles and greenfield project pipelines. Forecast inputs incorporated PLI scheme disbursement schedules in India, Royal Commission environmental permit issuance rates in Saudi Arabia, and municipal water utility privatization trajectories in Brazil.
Macroeconomic conditions sit as an overlay; deviation in rare earth magnet pricing, hydrocarbon capital expenditure cycles, or pharmaceutical manufacturing investment would shift the trajectory. Quarterly review of IEC certification backlog durations, neodymium oxide export quotas, and technician training program graduation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market