
 Industrial Lighting Market | 2026-2036
Industrial Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Lighting Market Intelligence
The traditional skill set of electrical contractors specializing in incandescent and fluorescent systems is collapsing under the shift to integrated IoT controls. This transition creates an opening for firms with deep software and networking expertise. Signify Holding leverages its extensive portfolio in connected lighting to capture this value shift. Acuity Brands differentiates with its focus on intelligent building solutions, while Eaton Corporation sustains its position through a strong distribution network for both legacy and new technologies.
Industrial lighting encompasses durable, high-output illumination systems designed for harsh environments, often requiring IP65 or higher ratings for dust and water resistance. Its primary purpose is to ensure safety, visibility, and productivity in facilities like factories and warehouses. The transition to LED products is nearly complete, making it the dominant product type by revenue and volume. Within applications, warehousing shows significant expansion, while the high bay technology segment continues to command a large share due to its suitability for large, open spaces.
Regulatory frameworks like the EU's RoHS directive and the US EPA's ENERGY STAR program mandate specific material and efficiency standards. In China, national GB standards for lighting products govern market access and safety compliance. These regulations collectively push manufacturers toward more sustainable and energy-efficient designs. The critical decision for facility managers now revolves around balancing upfront smart lighting investment against long-term operational savings and productivity gains.
Market Dynamics
The convergence of solid-state lighting with IoT networking protocols is the central force redefining industrial illumination. This shift displaces traditional electrical hardware expertise, creating value for firms proficient in software integration and data management within facility operations.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and similar energy efficiency standards in North America are accelerating the replacement of legacy fluorescent and HID systems with LED technology, especially in new manufacturing facilities.
- Warehousing Automation:Expansion in e-commerce logistics and automated warehousing requires advanced, controllable illumination to support robotic navigation and vision systems, driving demand for smart lighting fixtures.
- Manufacturing Expansion in Asia:The development of new industrial parks and factories across India and Southeast Asia creates greenfield opportunities for modern, high-bay LED lighting installations from the outset.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment required for integrated smart lighting systems, including sensors and control software, deters adoption among smaller industrial operators with constrained capital budgets.
- System Interoperability:A lack of universal standards between different IoT control platforms and lighting hardware from various manufacturers creates integration complexity and vendor lock-in risks for facility managers.
- Component Supply Volatility:The reliance on a concentrated semiconductor supply chain for LED drivers and control chips introduces vulnerability to price fluctuations and lead-time extensions, impacting production schedules.
Strategic Opportunities
- Service-Based Models:The transition to Lighting-as-a-Service (LaaS) models allows vendors to offer fully managed illumination solutions, bypassing high upfront costs for customers and creating recurring revenue streams.
- Controlled Environment Agriculture:The expansion of indoor vertical farming presents a significant opportunity for specialized LED grow lights designed with specific spectral outputs to optimize crop yield and quality.
- Incentivized Retrofitting:Government incentives and utility rebates in markets like the United States, tied to programs like the IRA, encourage the retrofitting of older industrial facilities with energy-efficient smart lighting.
Industry Challenges
- Specialized Skills Gap:A shortage of technicians and engineers with combined expertise in electrical systems, networking, and software programming hinders the installation and maintenance of complex connected lighting systems.
- Legacy System Integration:Integrating new IoT-enabled lighting controls with existing, disparate building management systems (BMS) in older industrial plants poses a significant technical and operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Lighting Market |
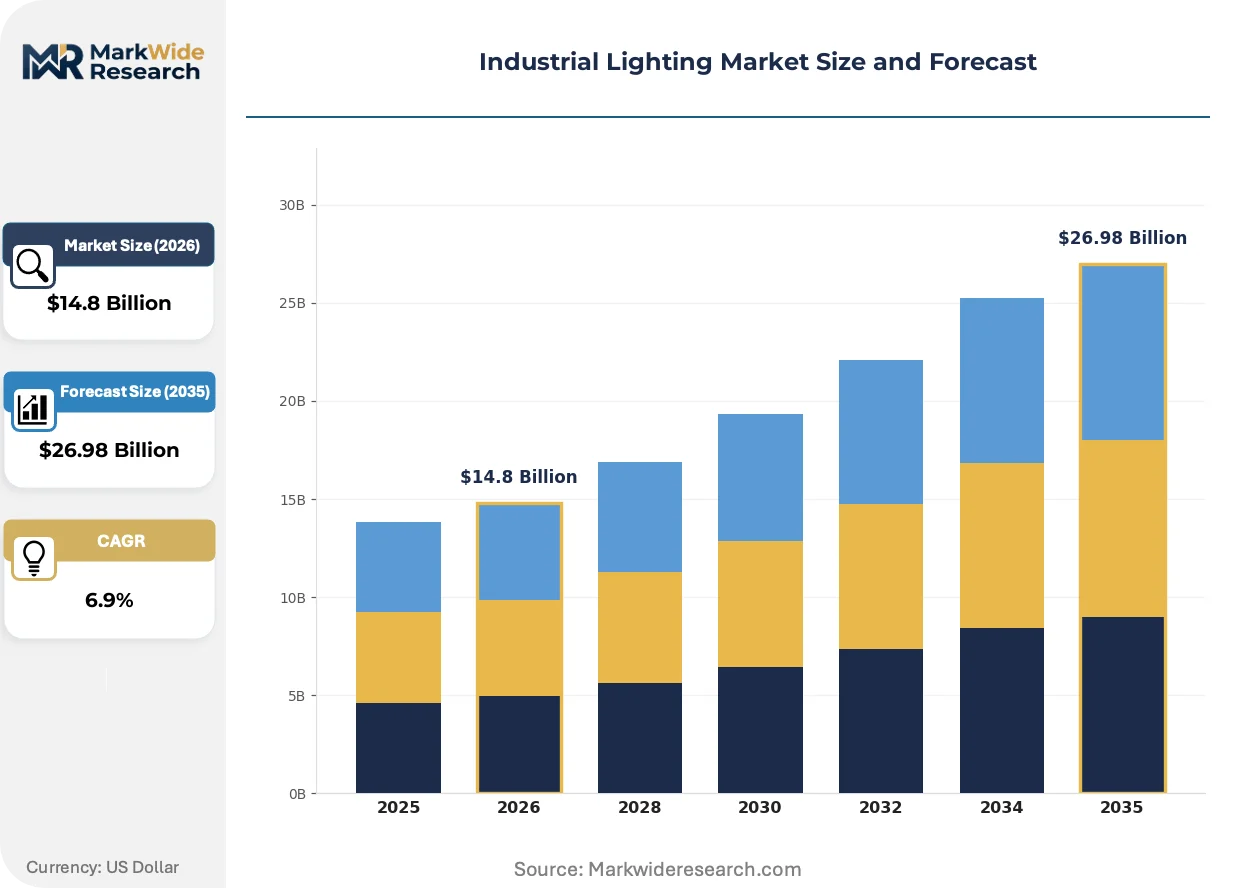
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
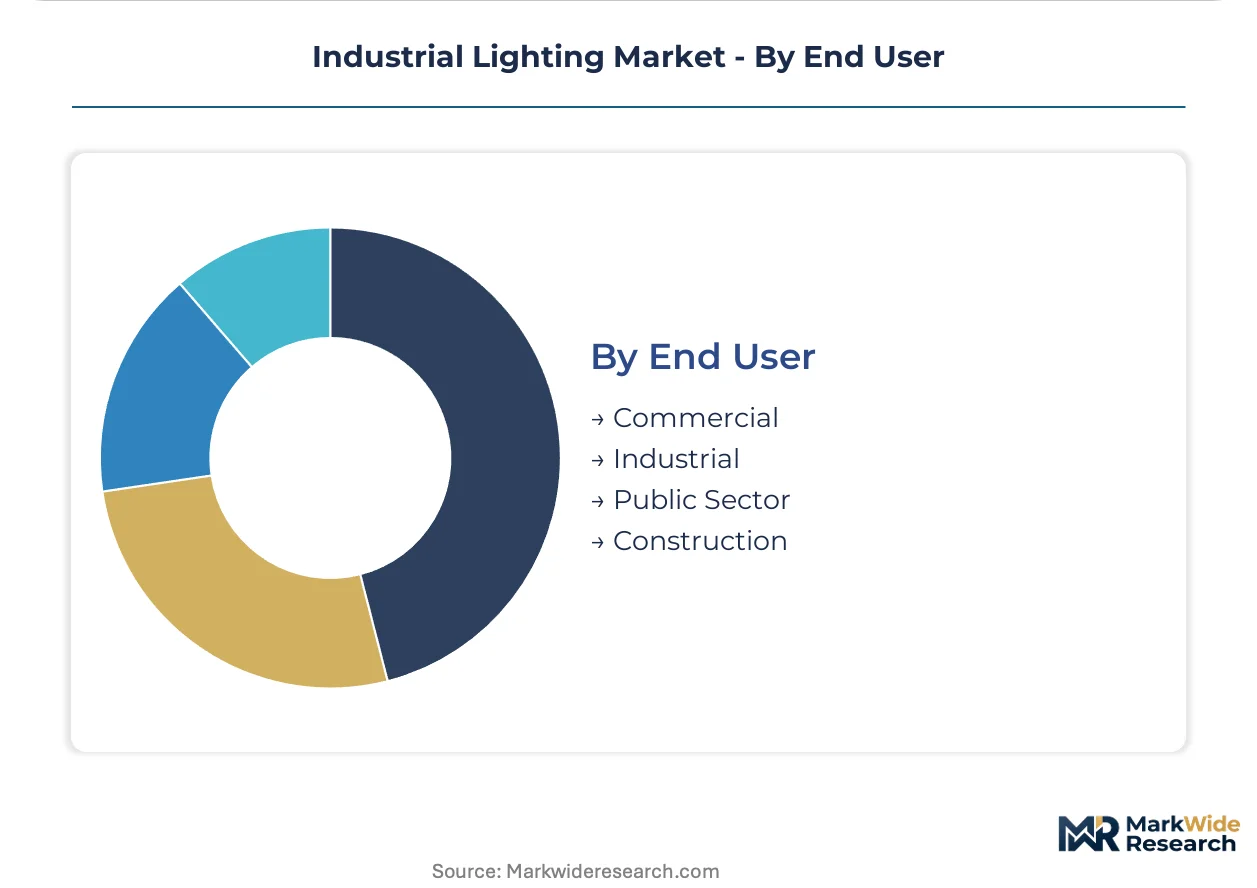
| Segmentation | Product Type: LED, HID, Fluorescent, Incandescent Application: Manufacturing, Warehousing, Oil & Gas, Transportation Technology: Smart Lighting, Emergency Lighting, Solar Lighting, High Bay End User: Commercial, Industrial, Public Sector, Construction |
| Companies Covered | Signify Holding, Acuity Brands, Eaton Corporation, ams OSRAM, Hubbell Incorporated, Cree Lighting, Dialight, Zumtobel Group, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Lighting Market Strategic Shifts & Innovations
The industrial lighting sector is shifting from a hardware-centric model to one defined by software and service integration. This evolution prioritizes data-driven operational efficiency over simple illumination, changing how facilities procure and manage light.
Tunable-spectrum LED technology allows dynamic adjustment of light color and intensity. Human-centric lighting applications adopt this to improve worker alertness, while horticulture uses it for crop cycles. This capability is bifurcating the market into basic, fixed-output luminaires and premium, application-specific intelligent systems commanding higher margins.
China's national GB standards, coupled with its dual carbon goals, impose strict energy efficiency and safety requirements. These regulations raise the entry barrier, forcing manufacturers to redesign products for compliance. The high-bay and explosion-proof lighting segments are particularly affected, requiring significant investment to meet updated MIIT performance specifications.
Buying decisions for industrial lighting are moving from facilities maintenance toward IT and operations departments. This disrupts the traditional electrical distributor channel, as purchasing criteria now include network security and API compatibility. The change is most visible in logistics and advanced manufacturing, where lighting is part of the digital infrastructure.
Industrial Lighting Market Segmentation
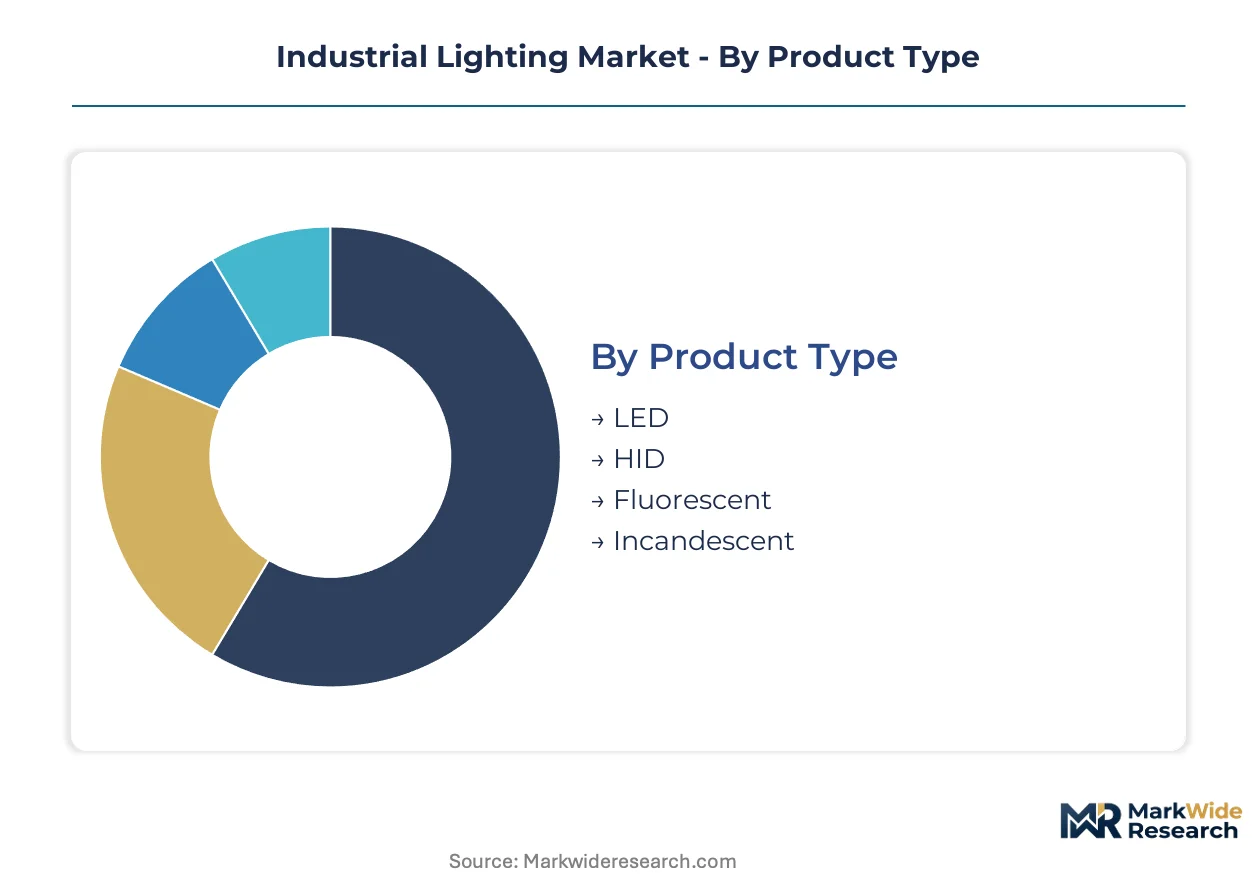
Understanding the distinct segments within the industrial lighting market reveals how regulatory frameworks, technological advancements, and end-user demands shape product development and adoption. This granular view highlights where innovation concentrates and value is created across the ecosystem.
Product Type:
Regulatory pushes for energy efficiency significantly differentiate product types in industrial lighting, influencing their market viability and replacement cycles.
- LED:These solid-state devices convert electricity directly into light, offering high energy efficiency and long operational lifespans. Demand concentrates in new manufacturing facilities and warehousing, driven by strict energy efficiency regulations and operational cost savings.
- HID:High-intensity discharge lamps produce light by passing an electric arc through a mixture of gas and metal salts, known for high light output in large areas. Replacement demand for HID systems is significant in older industrial plants, spurred by regulatory phase-outs in Europe.
- Fluorescent:These gas-discharge lamps use fluorescence to produce visible light, offering reasonable efficiency but containing mercury.
- Incandescent:These traditional lamps produce light by heating a filament, offering low efficiency and are largely phased out in industrial applications.
LED products handle the majority of throughput; LED also continues as the fastest mover on share.
Application:
Cost tiering significantly impacts adoption patterns across various industrial lighting applications, balancing upfront investment against long-term operational gains.
- Manufacturing:Industrial lighting in manufacturing facilities supports complex assembly lines and precise quality control, often requiring high uniformity and color rendering. New factory builds in India and Southeast Asia are driving demand for modern, high-bay LED installations.
- Warehousing:Illumination systems for warehouses facilitate safe navigation, inventory management, and automated operations, often integrating with robotic vision systems. The expansion of e-commerce logistics requires advanced, controllable lighting to support increased automation.
- Oil & Gas:These demanding environments require explosion-proof and robust lighting solutions to ensure safety and operational continuity.
- Transportation:Lighting for transportation infrastructure includes ports, airports, and rail yards, prioritizing durability and visibility in harsh conditions.
Warehousing applications represent the largest demand volume, while manufacturing facilities are expanding most quickly.
Technology:
Application-specific requirements drive the differentiation of lighting technologies in industrial settings, catering to diverse operational needs.
- Smart Lighting:These systems integrate sensors, controls, and networking capabilities to enable dynamic light adjustment, energy management, and data collection. Demand is concentrating in automated warehousing, where intelligent controls support robotic navigation and operational efficiency.
- High Bay:Designed for large, open spaces with high ceilings, high bay luminaires provide powerful, uniform illumination crucial for visibility and safety. New industrial parks and large-scale factories across Asia are greenfield opportunities for these installations.
- Emergency Lighting:These systems provide illumination during power outages or emergencies, ensuring safe egress and compliance with safety regulations.
- Solar Lighting:Solar-powered lighting solutions offer off-grid operation and reduced energy costs, suitable for outdoor industrial perimeters or remote sites.
High Bay technology dominates installations in large spaces, with smart lighting solutions experiencing the steepest expansion trajectory.
End User:
Customer type dictates specific product feature sets and service requirements for industrial lighting solutions, influencing market penetration.
- Industrial:This segment includes factories, processing plants, and heavy manufacturing facilities, requiring durable, high-output lighting for safety and productivity. Stringent safety standards and continuous operation cycles drive demand for robust, reliable systems.
- Commercial:Commercial end-users encompass offices, retail spaces, and smaller workshops within industrial complexes, seeking energy-efficient and aesthetically pleasing lighting solutions. Energy efficiency mandates and worker well-being initiatives influence purchasing decisions.
- Public Sector:Government-owned facilities, including public utilities and infrastructure projects, require reliable and compliant lighting systems.
- Construction:Temporary and durable lighting solutions are essential for construction sites, ensuring worker safety and project visibility during various phases.
Industrial end-users account for the largest share of deployments, as the public sector climbs the fastest in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial lighting adoption shows differential consumption mixes across major global regions. New manufacturing facilities and warehousing expansion in Asia drive greenfield LED installations, contrasting with significant retrofitting efforts in established European markets. North America balances both new construction and substantial smart lighting upgrades, driven by efficiency mandates and automation.
United States
Warehousing automation and incentivized retrofitting of older industrial facilities represent key demand drivers. The US EPA's ENERGY STAR program and the IRA encourage energy-efficient smart lighting solutions. In the Midwest, automotive manufacturing plants are upgrading to smart LED systems for improved productivity and operational visibility.
Germany
Germany's demand stems from strict energy efficiency mandates and the need for high-quality illumination in advanced manufacturing. The EU Green Deal and RoHS directive accelerate the replacement of legacy fluorescent and HID systems. Industrial hubs in Bavaria are investing in tunable-spectrum LED lighting to optimize worker conditions and energy usage.
China
China's market is driven by the rapid expansion of new industrial parks and advanced manufacturing facilities. National GB standards for lighting products and dual carbon goals enforce strict energy efficiency and safety requirements. The Yangtze River Delta region sees significant demand for high-bay LED installations in new factories and logistics centers.
India
India's industrial lighting market benefits from new factory builds and infrastructure development across diverse industrial sectors. Government initiatives to promote energy conservation are driving LED adoption in industrial settings. Manufacturing facilities in Gujarat are implementing modern high-bay lighting solutions from the outset to enhance operational efficiency.
Japan
Japan's demand emphasizes precision manufacturing and the integration of smart lighting with factory automation systems. METI promotes energy efficiency in industrial operations through various incentive programs and regulations. Advanced electronics plants in the Kanto region are adopting connected lighting for data-driven operational insights and quality control.
Industrial Lighting Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the industrial lighting market structure. These larger entities often offer full-suite intelligent building solutions, leveraging extensive distribution networks across global markets. Strategic archetypes include technology innovators focusing on IoT integration and established players emphasizing robust, durable hardware for harsh environments. Companies are engaging in strategic partnerships to bridge software and hardware expertise, alongside portfolio diversification into Lighting-as-a-Service models.
On the premium-tier vector, Signify Holding exemplifies a global leader with an extensive portfolio in connected lighting solutions, particularly leveraging its expertise in IoT integration. Acuity Brands represents firms focused on intelligent building solutions, integrating lighting with broader facility management systems and data analytics. Eaton Corporation occupies a position as a diversified industrial player, sustaining its presence through strong distribution channels for both legacy and advanced technologies. These entities anchor distinct segments within the market, from software-driven innovation to robust hardware reliability and broad market reach.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Eaton Corporation |
| ams OSRAM |
| Hubbell Incorporated |
| Cree Lighting |
| Dialight |
| Zumtobel Group |
| Panasonic Corporation |
Cost & Logistics Intelligence
Scale economies in LED manufacturing drive down unit costs, shaping supply concentration and influencing price floors across the industrial lighting market. This dynamic encourages consolidation among component suppliers and finished product manufacturers.
Pricing Analysis
Project-based contracts often define pricing for large industrial installations, balancing upfront investment with long-term operational savings. Price differentiation stems from the quality grade of luminaires, such as IP65 or explosion-proof certifications, and the level of customization for tunable-spectrum applications. Pricing pressure on basic LED luminaires intensifies due to commoditization and increased competition from Asian manufacturers. Smaller industrial operators exhibit higher price sensitivity due to constrained capital budgets for integrated smart lighting systems.
Supply Chain Analysis
Component supply volatility stemming from semiconductor chip reliance presents a structural risk for industrial lighting manufacturers. Geographic supply concentrates heavily in China for LED components and driver electronics, with assembly operations also prevalent across Southeast Asia. Key raw material dependencies include specialized semiconductor chips for control systems and rare earth elements used in LED phosphors. Distribution typically runs through established electrical distributors for standard products, while specialized integrators handle complex smart lighting solutions directly for large projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial lighting represents a defensive market with high switching costs once advanced control systems integrate with facility management platforms. Regulatory entrenchment through energy efficiency mandates further strengthens this market's structural advantages.
For Market Incumbents:Consolidate market share by acquiring specialized software and networking firms to enhance IoT integration capabilities. Investing in Lighting-as-a-Service (LaaS) models can create recurring revenue streams and bypass customer capital outlay issues. This strategy helps mitigate the threat from pure-play software integrators and leverages existing channel control through robust distribution networks. Prioritize R&D in open-standard interoperability to simplify integration with diverse building management systems.
For New Entrants and Emerging Players:Lead with niche application solutions, such as specialized LED grow lights for controlled environment agriculture or robust, explosion-proof smart systems. The retrofit market in older industrial facilities, especially those eligible for government incentives like the IRA, offers a penetrable segment. Focus on developing open-source platforms and flexible API compatibility to reduce vendor lock-in risks for facility managers. This approach can differentiate offerings from established players.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among Lighting-as-a-Service (LaaS) providers and firms offering integrated smart lighting solutions with ongoing software subscriptions. The long-term viability of this market hinges on the continued shift towards data-driven operational efficiency and regulatory compliance. Target firms with proprietary IoT platforms, deep software integration expertise, or strong intellectual property in tunable-spectrum LED technology. A specific signal to watch is the increased adoption of open standards for IoT lighting controls, indicating market maturity and reduced integration complexity.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop open IoT integration platforms | Ensures broader compatibility with existing building management systems, reducing customer integration complexity. |
| Expand Lighting-as-a-Service (LaaS) offerings | Transforms upfront capital expenditures into predictable operational costs for customers, creating stable revenue streams. |
| Acquire specialized software/AI firms | Enhances data analytics and intelligent control capabilities, driving higher value from connected lighting systems. |
| Invest in tunable-spectrum LED R&D | Enables dynamic light adjustment for human-centric applications and optimized crop growth, opening new premium segments. |
| Form strategic partnerships with IT/OT providers | Bridges the gap between electrical hardware and digital infrastructure, crucial for advanced manufacturing and logistics. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to triangulate market dynamics and validate quantitative models. Primary interviews included facility managers, electrical contractors, IoT solution architects, and lighting engineers. Secondary validation drew from EU Green Deal reports, US EPA ENERGY STAR data, China's national GB standards, and company financial filings, ensuring a balanced perspective.
The analytical framework projects market evolution across the analysis window, considering volume and value outputs for each segment. Segmentation dimensions modeled include product type, application, technology, end-user, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical trends, projected technology adoption rates, and the anticipated impact of regulatory shifts. Key industry-specific forecast inputs included new manufacturing facility construction rates and e-commerce warehousing expansion.
The analysis sits within stated boundaries; outcomes outside significant regulatory shifts or unforeseen geopolitical disruptions would require recalibration. Forecasts reflect assumptions regarding semiconductor supply chain normalization and continued investment in industrial automation. Practitioners should keep alternative scenarios live as energy policies and global trade conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Solar Lights Market
Lighting
Lighting Fixture Market
Lighting
Ultraviolet Lamps Market
Lighting
Residential Lighting Fixtures Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Vintage Bulb Market
Lighting
Lighting Control Components Market
Lighting
Solid State Lighting System Market
Lighting
Fluorescent Lighting Market
Lighting
Gesture Control Light Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Lamps and Lighting Market
Lighting
Global Lamps Market