
 Xenon Lights Market | 2026-2036
Xenon Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Xenon Lights Market Intelligence
China's Jiangsu and Guangdong provinces is fragmenting xenon lamp manufacturing capacity as domestic suppliers expand ceramic metal-halide foundry operations. Koito Manufacturing Co., Ltd. anchors Japanese OEM supply chains through captive arc-tube production in Yokohama. Hella GmbH & Co. KGaA competes across European premium vehicle programs with modular ballast architectures. Valeo S.A. extends its Maghreb assembly footprint to offset continental labor costs.
Xenon lights are high-pressure gas discharge lamps that produce illumination by ionizing xenon gas between tungsten electrodes within a fused silica arc tube, generating correlated color temperatures of 4,000–6,000 Kelvin and luminous efficacies exceeding 90 lumens per watt. Automotive headlamp applications dominate commercial demand due to superior road penetration and reduced driver fatigue versus halogen alternatives. High-Intensity Discharge systems occupy the dominant revenue share given their penetration in luxury vehicle segments and replacement cycle economics. Medical Lighting applications sustain premium margin pools as surgical suites require precise color-rendering indices above 90. Specialty Lighting segments navigate narrower volume scales but command higher unit values in cinema projection and searchlight operations.
EU REACH restrictions on mercury content compel manufacturers toward lead-free glass sealants and redesigned electrode assemblies. ECE R48 and R98 type-approval frameworks govern photometric performance and installation geometry for road-legal headlamp systems across European markets. NHTSA FMVSS 108 shapes analogous compliance pathways in the United States through beam pattern and glare limitations. Stakeholders must monitor divergence between regional efficiency mandates and the arc-tube thermal management investments required to satisfy them.
Market Dynamics
EU REACH mercury restrictions and Ecodesign efficiency mandates are forcing arc-tube redesigns and electrode material substitutions across European supply chains, compressing margins for legacy glass-sealant formulations while redirecting R&D budgets toward lead-free alternatives.
Growth Catalysts
- ECE R48/R98 Type-Approval Frameworks:European photometric and installation standards sustain replacement demand for OEM-certified HID headlamp systems in Germany and France.
- Medical Surgical Suites:Precise color-rendering requirements above CRI 90 lock in xenon premium positioning for operating theater illumination against LED alternatives.
- East Asian Manufacturing Clusters:South Korean component foundries concentrate ballast and arc-tube supply, lowering procurement costs for Tier 1 lamp assemblers.
Market Restraints
- Fused Silica Input Volatility:Arc-tube substrate costs fluctuate with semiconductor-grade quartz supply constraints.
- LED Substitution Threat:Solid-state automotive lighting achieves comparable luminous efficacy at lower thermal management complexity.
- Single-Source Ballast Dependency:German and Japanese suppliers control proprietary igniter architectures, creating procurement bottlenecks.
Strategic Opportunities
- Cinema Projection Retrofit Cycles:Digital cinema conversion sustains demand for high-CCT xenon short-arc lamps in premium exhibition venues.
- Searchlight Defense Applications:Military and maritime signaling requirements specify xenon for beam-throw distances beyond LED capability.
- EU Green Deal Efficiency Incentives:Energy performance contracting in public lighting creates specification pathways for high-efficacy discharge systems.
Industry Challenges
- Glass-Sealing Technician Shortage:Lead-free sealant chemistry requires retrained furnace operators, constraining Yokohama and Guangdong foundry output.
- Dual Certification Burden:Parallel NHTSA FMVSS 108 and ECE homologation timelines extend product launch cycles for headlamp suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xenon Lights Market |
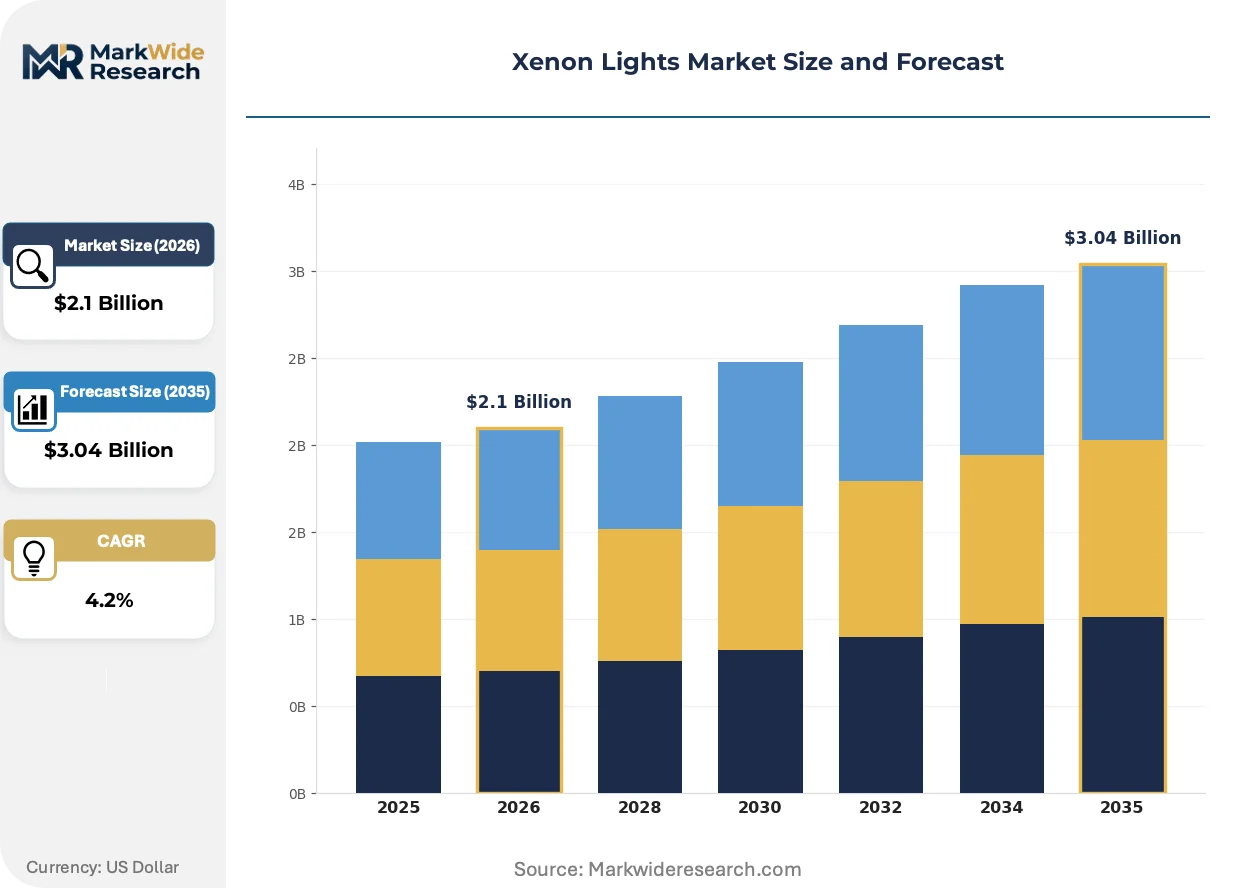
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Intensity Discharge, Low-Intensity Discharge, Automotive Xenon, Specialty Lighting Application: Automotive Headlights, Medical Lighting, Stage Lighting, Photography Lighting Technology: Gas Discharge, Fluorescent, LED, Induction End User: OEMs, Aftermarket Providers, Cinemas, Hospitals |
| Companies Covered | Valeo S.A., Hella GmbH & Co. KGaA, Koninklijke Philips N.V., Marelli Holdings Co., Ltd., Stanley Electric Co., Ltd., ams OSRAM AG, Koito Manufacturing Co., Ltd., Lumileds LLC, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xenon Lights Market Strategic Shifts & Innovations
Technology convergence between ceramic metal-halide formulations and intelligent thermal management is fragmenting traditional xenon market boundaries, while regulatory chemistry restrictions and buyer procurement centralization reshape competitive positioning across automotive and medical verticals.
Ceramic metal-halide arc-tube architectures with improved thermal shock resistance are penetrating automotive forward-lighting specifications. German premium OEMs specify these designs for adaptive headlamp modules. The technology is rendering obsolete conventional quartz envelope constructions in high-vibration applications.
EU REACH Annex XVII mercury restrictions are compelling electrode assembly redesigns and alternative dopant chemistries. Manufacturers face reformulation costs for glass-to-metal seals. Medical lighting suppliers in Switzerland and Germany accelerate lead-free validation programs to maintain CE marking access.
Fleet procurement centralization among European rental and leasing consortia is compressing replacement cycle decision-making. Aggregated volume tenders favor suppliers with modular ballast platforms and pan-European service networks. France and Italy exhibit the fastest consolidation of aftermarket buying power into procurement cooperatives.
Xenon Lights Market Segmentation
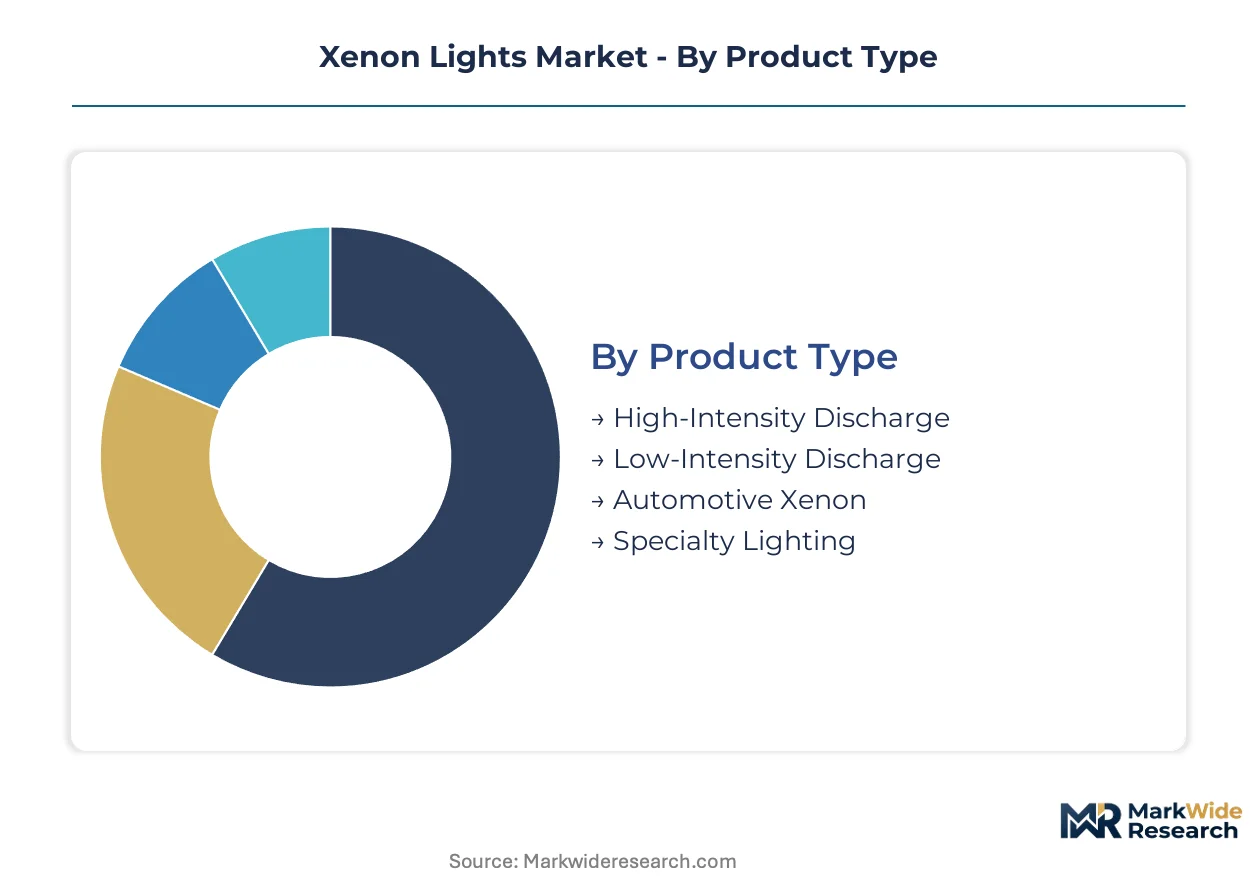
Xenon lamp architectures fragment across performance tiers and procurement channels that reset at fundamentally different intervals. Replacement cycle timing shapes inventory strategy more than any other segmentation variable in this market.
Product Type:
Cycle times range from three-year automotive refresh schedules to decade-long industrial installations, with arc-tube thermal degradation dictating actual replacement rather than calendar age.
- High-Intensity Discharge:These systems operate at 35-70 watts with arc temperatures exceeding 6000K, delivering 90+ lumens per watt through xenon gas ionization between tungsten electrodes. German premium OEMs specify HID modules for adaptive headlamp systems, though ECE R98 type-approval timelines extend product validation cycles.
- Automotive Xenon:Dedicated vehicle-fitment designs integrate proprietary ballast architectures and igniter protocols specific to each manufacturer's electrical bus. South Korean component foundries concentrate arc-tube supply for Tier 1 assemblers serving Hyundai-Kia and Renault-Nissan programs.
- Low-Intensity Discharge:Reduced-wattage variants serve instrument cluster backlighting and interior accent applications where thermal management constraints favor lower arc temperatures.
- Specialty Lighting:Cinema projection and searchlight applications demand short-arc geometries with precise focal point alignment for beam-throw performance.
High-Intensity Discharge anchors the volume base while Automotive Xenon gains share at the steepest rate.
Application:
Cost tiers separate specification-grade medical installations from commodity automotive retrofits, with surgical suites commanding tenfold unit premiums over headlamp replacements.
- Automotive Headlights:Forward-lighting applications dominate commercial demand through superior road penetration and reduced driver fatigue versus halogen alternatives. ECE R48 photometric standards govern European OEM certification, while NHTSA FMVSS 108 shapes compliance pathways in the United States.
- Medical Lighting:Operating theater illumination requires color-rendering indices above 90 to distinguish tissue vascularization, locking in xenon positioning against LED alternatives despite higher thermal loads. Swiss and German suppliers accelerate lead-free validation under EU REACH Annex XVII.
- Stage Lighting:Theater and concert venues specify high-CCT short-arc designs for color temperature consistency across fixture arrays.
- Photography Lighting:Studio flash systems utilize xenon for color stability during rapid-cycle exposure sequences.
Automotive Headlights represent the largest revenue pool while Medical Lighting delivers the highest margin contribution per unit.
Technology:
Supply concentration in electrode assembly and arc-tube fabrication favors gas discharge incumbents, though LED substitution threatens thermal management complexity advantages.
- Gas Discharge:High-pressure xenon ionization between fused silica envelopes generates continuous-spectrum illumination with superior color rendering to phosphor-converted alternatives. Japanese and German suppliers control proprietary igniter architectures, creating procurement bottlenecks for independent assemblers.
- LED:Solid-state alternatives achieve comparable luminous efficacy at reduced thermal management complexity, displacing xenon in mainstream automotive segments.
- Fluorescent:Mercury-vapor excitation of phosphor coatings delivers lower color temperature output for general illumination.
- Induction:Electrodeless designs extend operational lifespan through elimination of arc-point degradation.
Gas Discharge retains specification dominance in color-critical segments while LED expands most quickly in volume-driven applications.
End User:
Procurement centralization separates fleet-scale OEM negotiations from fragmented aftermarket replacement demand, with rental consortia compressing decision cycles in European markets.
- OEMs:Vehicle manufacturers specify headlamp modules through multi-year platform contracts with Tier 1 lamp assemblers. Koito Manufacturing anchors Japanese supply chains through captive arc-tube production in Yokohama.
- Hospitals:Surgical suite procurement committees prioritize CE-marked suppliers with validated lead-free sealant chemistries under EU REACH compliance.
- Aftermarket Providers:Independent distributors serve replacement demand through modular ballast platforms compatible with multiple vehicle fitments.
- Cinemas:Digital cinema conversion sustains demand for high-CCT short-arc lamps in premium exhibition venues requiring precise color temperature control.
OEMs command the deepest procurement leverage while Hospitals sustain the most price-inelastic demand profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese suppliers dominate arc-tube fabrication and ballast engineering, while Chinese foundries expand ceramic metal-halide capacity to serve cost-sensitive automotive programs.
Germany
Premium OEMs in Bavaria and Baden-Württemberg specify adaptive HID modules with ECE R98 type-approval. REACH Annex XVII mercury restrictions compel Hella and other suppliers toward lead-free glass sealants. Stuttgart's engineering clusters concentrate ballast R&D for modular architectures.
Japan
Koito Manufacturing anchors domestic supply chains through captive arc-tube production in Yokohama. METI efficiency guidelines shape thermal management investments for next-generation discharge systems. Chubu region foundries face technician shortages for lead-free furnace operations.
China
Jiangsu and Guangdong provinces fragment manufacturing capacity as domestic suppliers expand ceramic metal-halide operations. MIIT standards govern automotive lighting performance for export-bound production. Yangtze River Delta clusters serve Tier 1 assemblers with lower-cost component sourcing.
South Korea
Hyundai-Kia and Renault-Nissan programs sustain demand for high-performance headlamp systems. MFDS medical device regulations shape surgical lighting specifications for domestic hospital procurement. Busan-Ulsan manufacturing corridors concentrate ballast and igniter component supply.
United States
NHTSA FMVSS 108 beam-pattern requirements extend product validation cycles for headlamp suppliers. Michigan and Ohio automotive clusters sustain replacement demand for OEM-certified HID systems. EPA chemical regulations intersect with state-level efficiency mandates in California and New York.
Xenon Lights Market Key Industry Players
Vertically integrated lamp assemblers and specialized component fabricators split the market into distinct capability tiers. Consolidation pressure concentrates around arc-tube thermal management and proprietary igniter architectures. Three archetypes dominate: captive automotive suppliers with in-house electrode production, modular ballast specialists licensing across vehicle platforms, and medical-grade purveyors with validated lead-free chemistries. Competitive moves center on backward integration into fused silica supply and pan-European service network expansion.
Among European automotive suppliers, Hella GmbH & Co. KGaA and Valeo S.A. exemplify the modular-ballast archetype, while Koito Manufacturing Co., Ltd. represents the vertically integrated Japanese model with captive Yokohama production. These three occupy positions shaped by regional regulatory divergence and OEM procurement centralization.
| Leading Market Players |
|---|
| Valeo S.A. |
| Hella GmbH & Co. KGaA |
| Koninklijke Philips N.V. |
| Marelli Holdings Co., Ltd. |
| Stanley Electric Co., Ltd. |
| ams OSRAM AG |
| Koito Manufacturing Co., Ltd. |
| Lumileds LLC |
| General Electric Company |
| Others |
Cost & Logistics Intelligence
Yokohama-to-Busan maritime corridors carry semiconductor-grade fused silica and precision ballast components, with freight cost volatility transmitting directly to OEM procurement premiums and aftermarket price stratification across certification tiers.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure by compelling lead-free glass sealant reformulation costs onto medical-grade suppliers while automotive HID modules stratify across ECE R98 certified premium, standard retrofit, and economy aftermarket tiers. Price differentiation rests on certification grade and volume scale, with Swiss surgical lighting commanding tenfold premiums over headlamp replacements. Cost compression in automotive aftermarket tiers is intensifying because LED substitution narrows performance gaps. Fleet procurement consortia exhibit highest price sensitivity while hospital surgical committees remain least elastic.
Supply Chain Analysis
South Korean component foundries in Busan-Ulsan corridors, Japanese captive arc-tube facilities in Yokohama, and Chinese ceramic metal-halide expansions in Jiangsu-Guangdong hold dominant contract-manufacturing capacity. Raw material dependencies draw from semiconductor-grade quartz deposits, tungsten electrode feedstock, and lead-free dopant chemistries. Single-source vulnerability concentrates in proprietary German and Japanese igniter architectures. Distribution runs through Tier 1 lamp assemblers serving OEM platform contracts and pan-European aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Xenon lighting faces high-growth disruption from EU Ecodesign efficiency mandates and ceramic metal-halide thermal management convergence, compressing legacy quartz envelope margins while opening premium positioning for adaptive headlamp and surgical suite applications.
For Market Incumbents: Entrench backward integration into fused silica supply and captive electrode production to defend against LED substitution in automotive forward-lighting. Accelerate lead-free sealant validation programs to preempt REACH compliance bottlenecks. Expand pan-European service networks to capture fleet procurement centralization.
For New Entrants and Emerging Players: Build out ceramic metal-halide arc-tube capacity for high-vibration automotive applications where conventional quartz constructions fail. Target medical lighting retrofit cycles in Swiss and German surgical suites requiring CRI 90+ performance. Pursue licensing arrangements with modular ballast specialists to bypass proprietary igniter patent thickets.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized lighting divisions possessing validated EU REACH chemistries but lacking automotive platform scale. Long-term viability hinges on medical segment defensibility against solid-state alternatives. Monitor quarterly arc-tube thermal degradation replacement rates as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Sealant Validation | EU REACH Annex XVII compliance preserves CE marking access for German and Swiss medical suppliers. |
| Ceramic Metal-Halide Capacity Expansion | Thermal shock resistance specifications from Bavarian premium OEMs render quartz envelopes obsolete. |
| Modular Ballast Platform Licensing | Pan-European service networks capture fleet procurement consolidation in France and Italy. |
| Backward Integration into Fused Silica | Semiconductor-grade quartz supply constraints threaten arc-tube substrate cost stability. |
| Medical Lighting Certification Investment | CRI 90+ surgical suite requirements lock in xenon positioning against LED alternatives. |
Research Approach
Initial hypotheses were tested against primary input from Tier 1 lamp assembler procurement directors, automotive OEM platform engineers, hospital biomedical equipment committees, and aftermarket distribution channel managers and refined through secondary validation against ECE R98 type-approval databases, EU REACH Annex XVII regulatory filings, NHTSA FMVSS 108 compliance records, and semiconductor-grade quartz trade flow data. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Demand-supply balance modeling anchored volume projections across product type, application, technology, and end-user segmentation dimensions with particular weighting toward replacement cycle timing and arc-tube thermal degradation curves. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking regulatory implementation timelines. Key inputs included Ecodesign efficiency mandate phase-in schedules and ceramic metal-halide penetration rates in adaptive headlamp specifications.
Stress conditions across fused silica input cost volatility, LED substitution acceleration, and REACH enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of arc-tube foundry output capacity, lead-free furnace operator training pipeline, and fleet procurement tender aggregation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
COB Photo Light Market
Lighting
Global Flame Proof Lighting Market
Lighting
Smart Lights Market
Lighting
UAE Smart Lighting Market
Lighting
Global Stadium Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Bacteriological Light Market
Lighting
Specialty Lighting Market
Lighting
Inspection Lighting Fixture Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
Wireless Lighting Market
Lighting
Programmable Stage Lighting Market
Lighting
Solar Rope Light Market
Lighting
Solid-State Lighting Source Market
Lighting
Graphene Lighting Market