
 Illuminating Signs Market | 2026-2036
Illuminating Signs Market Size, Share, and Industry Trends Forecast 2026-2036
Illuminating Signs Market Foresight
Skilled electrician labor availability for custom channel letter fabrication is collapsing across North American fabrication hubs, creating production backlogs that favor scaled manufacturers. Signarama leverages its franchise network density to sustain national coverage without centralized plant investment. Fortuna Visual Group anchors its position through vertical integration into metal forming and LED module assembly. InteriorTech Sign Company differentiates via specialization in corporate office wayfinding systems with integrated intelligent lighting controls.
Illuminating signs are engineered visual communication devices incorporating light-emitting elements—LED arrays, neon tubing, or electroluminescent films—within weather-rated housings typically fabricated from aluminum, acrylic, or polycarbonate substrates, designed for continuous outdoor operation across temperatures from -20°C to 50°C. Their primary commercial purpose is to extend brand visibility beyond daylight hours while reducing energy consumption versus legacy fluorescent systems. Channel letter signs and LED displays together capture the dominant share of value, with LED displays representing the fastest-expanding product category as pixel pitch technology enables higher-resolution outdoor applications. Digital signage technology within the technology dimension commands premium pricing and recurring content management revenue, while electroluminescent segments occupy narrower niche positions in transportation safety applications.
The US Department of Energy enforces minimum efficacy standards for commercial luminaires through regulatory frameworks that directly shape LED module specification requirements for outdoor advertising installations. China's SAMR and GB standards bodies mandate electromagnetic compatibility and fire-resistance ratings for illuminated facade systems, creating compliance cost barriers for non-domestic suppliers. The EU Ecodesign Directive and F-Gas Regulation constrain legacy fluorescent tube availability, accelerating retrofit demand. Stakeholders must monitor evolving municipal dark-sky ordinances in major US metropolitan markets, as these local regulations increasingly restrict illumination intensity and operating hours for exterior signage.
Market Dynamics
LED pixel pitch compression below 2.5mm is fragmenting competitive positioning between display manufacturers and traditional sign fabricators, forcing capital reallocation across fabrication networks.
Growth Catalysts
- US Department of Energy LED efficacy mandates:Minimum lumens-per-watt thresholds are accelerating retrofit programs across retail and hospitality chains, eliminating legacy fluorescent inventory from supply channels.
- Express format retail expansion:Retailers are deploying compact illuminated signage packages in secondary metropolitan corridors, creating standardized specification demand that favors scaled production.
- Electroluminescent film integration:Transportation safety authorities are specifying thin-film illuminated markers for tunnel and highway applications, opening niche volume for specialized substrate suppliers.
Market Restraints
- Aluminum extrusion input volatility:Channel letter housing fabrication depends on spot-market aluminum pricing, compressing margin predictability for mid-scale fabricators without long-term supply agreements.
- Skilled electrician labor scarcity:North American fabrication hubs face collapsing availability of technicians certified for custom LED array assembly, extending production lead times.
- EU F-Gas Regulation legacy constraints:Fluorescent tube phase-out timelines are compressing retrofit windows, stranding inventory for distributors without LED conversion capabilities.
Strategic Opportunities
- Intelligent lighting control convergence:Corporate office wayfinding systems integrating occupancy sensors and daylight harvesting present white space for specification-focused fabricators.
- China GB standards compliance services:Electromagnetic compatibility certification support for foreign suppliers creates recurring revenue potential for testing and documentation specialists.
- Dark-sky ordinance adaptation:Municipal illumination restrictions in Sun Belt metropolitan markets favor manufacturers with dimmable driver technology and curfew programming capabilities.
Industry Challenges
- Channel letter IP sealing certification:NEMA 4X and IP65 validation timelines for outdoor-rated housings extend product development cycles, delaying revenue recognition.
- Legacy fluorescent ballast integration:Retrofit projects requiring compatibility with existing electrical infrastructure complicate LED driver specification and field commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Illuminating Signs Market |
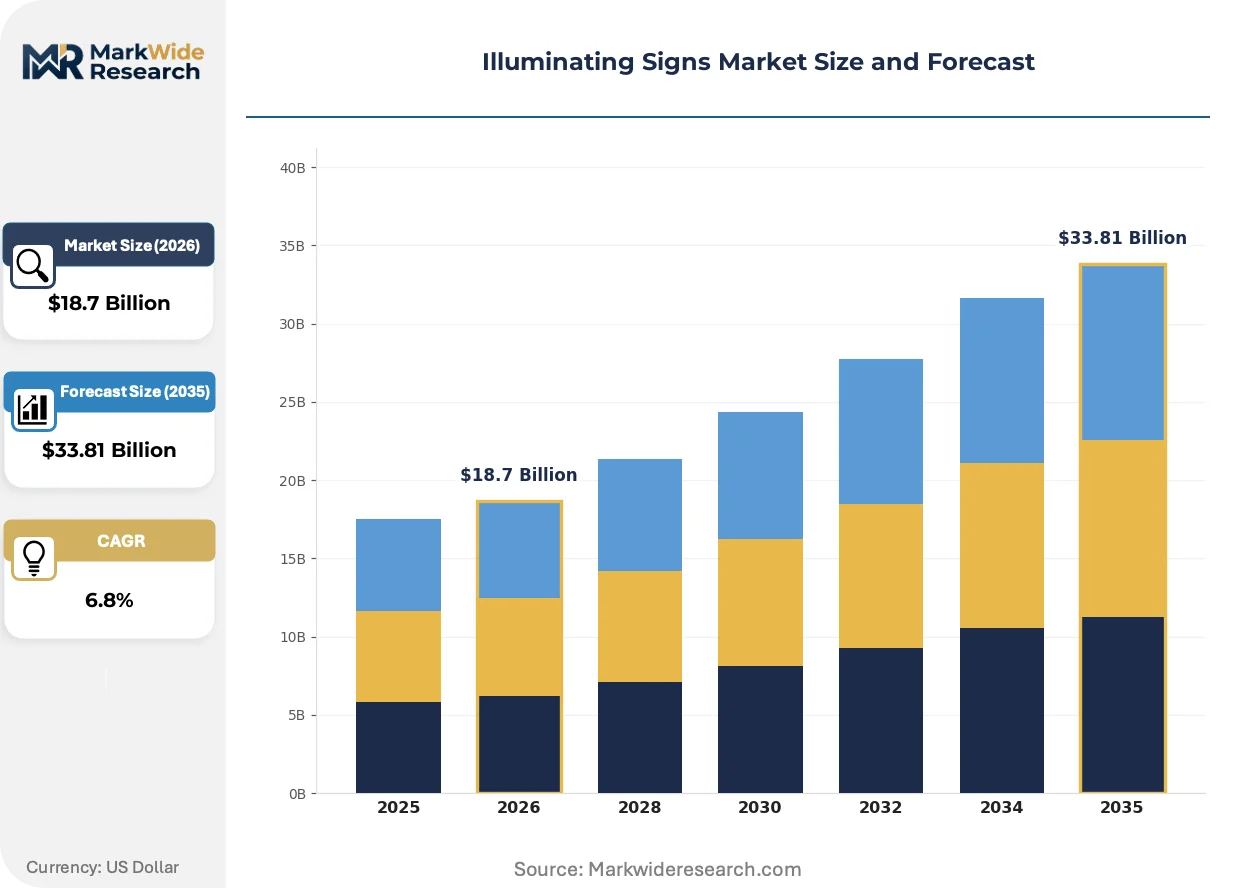
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Channel Letter Signs, LED Displays, Neon Signs, Light Boxes Application: Outdoor Advertising, Retail Storefronts, Event Signage, Wayfinding Systems Technology: Digital Signage, Electroluminescent, Fluorescent, Intelligent Lighting End User: Retail Chains, Hospitality, Transportation, Corporate Offices |
| Companies Covered | Fortuna Visual Group, Zienowicz Sign Co, Sweet Sign Systems, Fink Signs, InteriorTech Sign Company, Signarama, Tupp Signs, Illuminated Sign Solutions, Inc, Elmark Sign Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Illuminating Signs Market Shifts & Advancements
Specification engineering is displacing commodity fabrication as the value capture mechanism, with buyers prioritizing energy modeling and content management capabilities over hardware procurement.
Micro-LED packaging technology is fragmenting the outdoor display category, enabling direct-view applications previously reserved for indoor environments. Large-format retail and sports venue operators are specifying sub-3mm pixel pitch for daylight-visible installations. This convergence is compressing pricing power for conventional SMD module suppliers while elevating semiconductor packaging specialists.
China's SAMR enforcement of GB 7000 standards for illuminated facade systems is restructuring export compliance requirements. Foreign manufacturers must now document fire-resistance ratings and electromagnetic compatibility through accredited domestic laboratories. European and North American suppliers are responding by establishing captive testing relationships with Shanghai and Shenzhen certification bodies.
Buyers are unbundling hardware procurement from content management subscriptions, treating signage networks as software-enabled service platforms. Quick-service restaurant and fuel retail chains are separating capital expenditure for physical installations from recurring platform fees. This bifurcation is most pronounced across United States Sun Belt metropolitan corridors where franchise operators dominate deployment decisions.
Illuminating Signs Market Segmentation
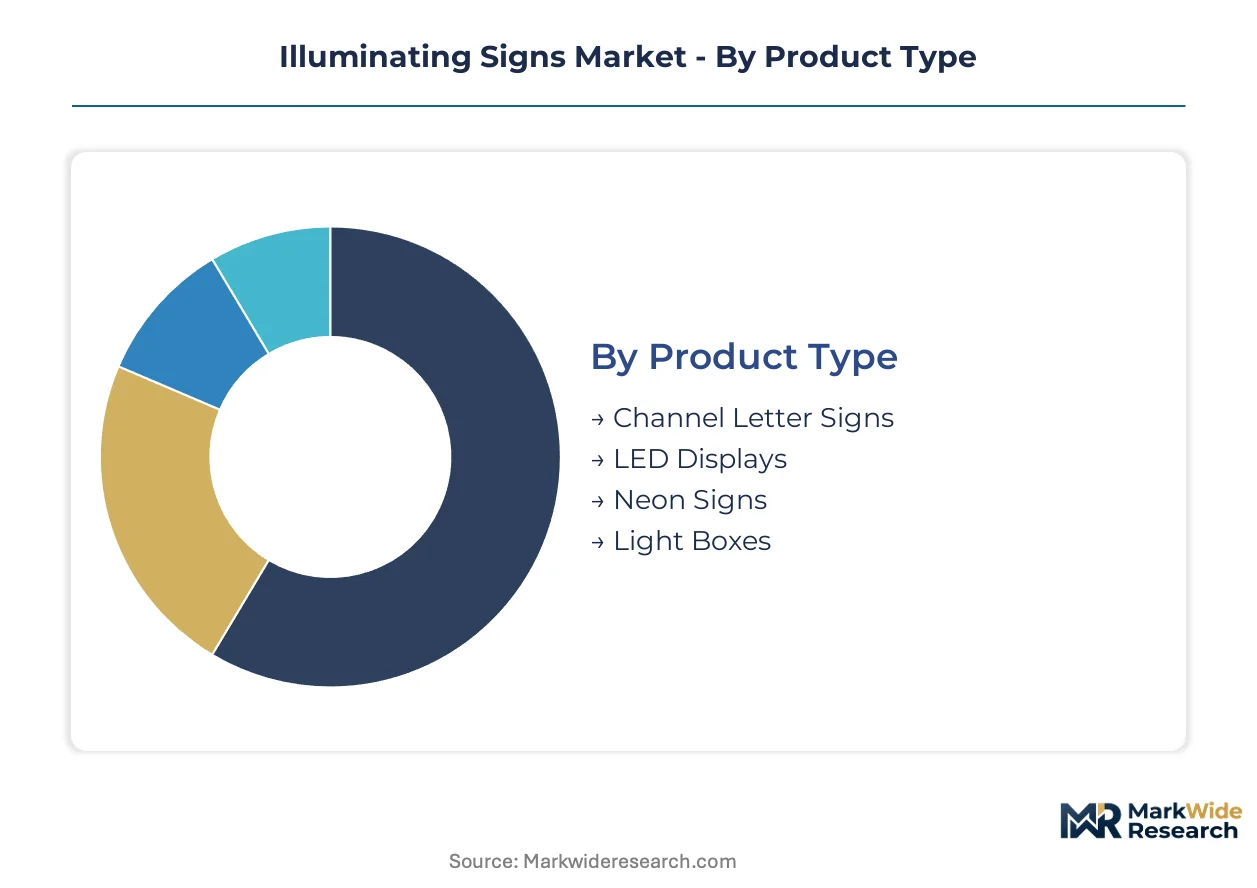
Illuminating signs serve distinct functional requirements across regulatory environments, with certification standards diverging sharply between outdoor advertising, retail, and transportation applications. Segmentation reveals how technology choices lock into specific compliance frameworks and energy efficiency mandates.
Product Type:
Regulatory differentiation separates outdoor-rated housings from interior installations, with NEMA 4X and IP65 certifications mandatory for facade-mounted systems in most US jurisdictions.
- Channel Letter Signs:Fabricated aluminum housings with LED or neon illumination, requiring UL listing for electrical safety in all permanent installations. Demand concentrates across Sun Belt metropolitan retail corridors where dark-sky ordinances restrict illumination intensity and operating hours. The US Department of Energy's efficacy mandates are accelerating LED retrofit programs, eliminating legacy fluorescent inventory.
- LED Displays:Direct-view pixel arrays with pitch compression below 2.5mm enabling daylight-visible outdoor applications. Large-format retail and sports venue operators in the United States are specifying sub-3mm pitch for premium visibility. Micro-LED packaging is fragmenting competitive positioning between display manufacturers and traditional fabricators.
- Neon Signs:Glass tube illumination with noble gas discharge, now occupying niche heritage and artistic applications. Artisan fabrication survives in specialized commercial districts.
- Light Boxes:Backlit graphic displays using edge-lit LED or fluorescent sources, common in transit advertising and retail window installations. China's GB standards mandate electromagnetic compatibility for imported units.
Channel Letter Signs handle the majority of throughput; LED Displays is the fastest mover on share.
Application:
Cost tier stratification separates capital-intensive permanent installations from temporary event deployments, with hardware ownership models diverging accordingly.
- Outdoor Advertising:Billboard and building-mounted systems requiring municipal permitting and FAA clearance near air corridors. Digital conversion is accelerating as operators unbundle hardware from content management subscriptions.
- Retail Storefronts:Brand identity systems spanning flagship flagship and express format footprints. Franchise operators in US Sun Belt corridors dominate deployment decisions, favoring standardized specifications.
- Event Signage:Temporary illuminated installations for trade shows and sporting venues, prioritizing rapid assembly and modular transport. Rental service providers capture recurring revenue.
- Wayfinding Systems:Corporate office and institutional navigation aids integrating occupancy sensors and daylight harvesting controls. Intelligent lighting convergence presents specification-focused opportunities.
Retail Storefronts absorbs the largest capital allocation; Wayfinding Systems is climbing the fastest on specification complexity.
Technology:
Volume concentration favors LED-based platforms, with legacy fluorescent facing forced obsolescence under EU F-Gas Regulation and US efficiency mandates.
- Digital Signage:Networked display systems with centralized content management, commanding premium pricing and recurring platform fees. Quick-service restaurant chains separate capital expenditure from ongoing service subscriptions.
- Electroluminescent:Thin-film illuminated markers specified by transportation safety authorities for tunnel and highway applications. China's SAMR enforcement of GB 7000 standards creates compliance barriers for non-domestic suppliers.
- Fluorescent:Legacy tube systems facing phased availability constraints under EU F-Gas Regulation. Retrofit windows are compressing, stranding distributor inventory without LED conversion capabilities.
- Intelligent Lighting:Sensor-integrated systems enabling dimming, curfew programming, and energy harvesting. Municipal dark-sky ordinances favor manufacturers with adaptive driver technology.
Digital Signage commands the highest value capture; Intelligent Lighting is gaining share fastest on regulatory tailwinds.
End User:
Customer type determines procurement centralization, with retail chains deploying standardized national programs versus fragmented corporate office specifications.
- Retail Chains:Franchise and corporate operators deploying illuminated signage across flagship and express formats. Express format expansion in secondary US metropolitan corridors creates standardized demand favoring scaled production.
- Hospitality:Hotel and restaurant operators balancing brand visibility with energy efficiency targets. LED retrofit programs are accelerating across property portfolios.
- Transportation:Airport, rail, and highway authorities specifying electroluminescent safety markers and dynamic information displays. China's GB standards require fire-resistance documentation through accredited domestic laboratories.
- Corporate Offices:Workplace identity and navigation systems with integrated intelligent controls. Wayfinding specialization differentiates specification-focused fabricators.
Retail Chains drives the dominant volume; Corporate Offices is expanding most quickly on convergence with building automation systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. US operators prioritize retrofit efficiency and dark-sky compliance. Chinese demand centers on export-certified fabrication for foreign brands. European procurement emphasizes circular design and fluorescent phase-out acceleration.
United States
Sun Belt metropolitan corridors from Phoenix to Miami drive retrofit volume as retail chains expand express formats. The US Department of Energy enforces minimum LED efficacy thresholds that eliminate legacy fluorescent inventory from supply channels. Dallas-Fort Worth fabrication hubs face skilled electrician shortages that extend channel letter production lead times.
China
Export-oriented manufacturers dominate LED module assembly for foreign retail brands. SAMR enforcement of GB 7000 standards mandates fire-resistance documentation and electromagnetic compatibility testing through accredited domestic laboratories. Shenzhen and Shanghai certification bodies now serve as captive compliance gateways for European and North American suppliers.
Germany
Industrial signage procurement emphasizes energy modeling and intelligent lighting integration for corporate headquarters. The EU Ecodesign Directive and F-Gas Regulation compress fluorescent retrofit windows while constraining legacy tube availability. Bavarian fabricators specialize in precision metal forming for premium channel letter housings.
United Kingdom
London's commercial district drives demand for heritage-compliant neon restoration alongside digital conversion. Municipal planning authorities enforce illumination intensity restrictions that favor dimmable driver technology. Midlands manufacturing clusters supply standardized LED components to national retail chains.
Japan
Corporate office wayfinding systems integrate occupancy sensors and daylight harvesting controls under METI efficiency guidelines. Premium retail districts in Tokyo and Osaka specify sub-3mm pixel pitch for daylight-visible outdoor displays. Kansai-based fabricators emphasize micro-LED packaging for direct-view applications.
Illuminating Signs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier fragmented by regional service radius and certification capability. Scale advantages concentrate in firms with captive metal forming and LED module assembly, while specification-focused players capture premium pricing through intelligent lighting integration. Two strategic archetypes dominate: vertically integrated fabricators controlling upstream substrate supply, and network-based operators leveraging distributed franchise density for national coverage without centralized plant investment. Competitive moves center on compliance service bundling and content management platform unbundling.
Among North American fabricators, Fortuna Visual Group exemplifies the integrated archetype through backward control over aluminum forming and semiconductor packaging. Signarama occupies the network-density position, sustaining national reach via franchise distribution without heavy manufacturing asset bases. InteriorTech Sign Company represents the specification-specialist tier, differentiating through corporate office wayfinding systems with integrated sensor controls.
| Leading Market Players |
|---|
| Fortuna Visual Group |
| Zienowicz Sign Co |
| Sweet Sign Systems |
| Fink Signs |
| InteriorTech Sign Company |
| Signarama |
| Tupp Signs |
| Illuminated Sign Solutions, Inc |
| Elmark Sign Company |
| Others |
Supply & Pricing Matrix
LED module substitution for legacy fluorescent tubes simultaneously shifts supply geography toward Shenzhen and Seoul semiconductor packaging clusters while compressing margin capture for mid-scale fabricators lacking long-term substrate agreements. This displacement dynamic concentrates pricing power with integrated manufacturers controlling upstream LED die supply.
Pricing Analysis
Long-term offtake agreements dominate procurement between national retail chains and scaled fabricators, while spot-market aluminum pricing governs channel letter housing costs for smaller operators. Premium-mid-economy pricing differentiation separates UL-listed outdoor-rated systems with NEMA 4X certification from uncertified interior alternatives. Cost compression in standard-tier LED displays intensifies as pixel pitch commoditization accelerates. Franchise retail operators in US Sun Belt corridors exhibit highest price sensitivity, whereas corporate office wayfinding buyers prioritize intelligent control integration over unit economics.
Supply Chain Analysis
Extended production lead times for custom channel letter assemblies now stretch beyond contracted delivery windows across Dallas-Fort Worth and Chicago fabrication hubs. LED module assembly concentrates in China, South Korea, and Taiwan, while aluminum extrusion feeds from domestic US and Canadian smelters. Supply chains rest on single-source vulnerability for micro-LED packaging substrates. Distribution runs through franchise network nodes for national coverage, bypassing centralized warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The illuminating signs market sits in early-cycle expansion as municipal dark-sky ordinances across Sun Belt metropolitan corridors force retrofit demand for adaptive driver technology.
For Market Incumbents: Fortify fabrication capacity through backward integration into aluminum forming and captive LED module assembly. The threat of micro-LED packaging specialists displacing conventional SMD suppliers demands upstream control over semiconductor sourcing. Certification investment in GB 7000 compliance through Shanghai accreditation bodies secures China export positioning.
For New Entrants and Emerging Players: Differentiate on intelligent lighting control convergence for corporate office wayfinding systems, where specification complexity exceeds incumbent capability. The most penetrable white space sits with sensor-integrated navigation aids in secondary US metropolitan corridors lacking specialized fabricators. Go-to-market leverage rests on building automation system partnerships rather than direct hardware sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional sign fabricators holding captive metal forming but lacking digital signage platform capabilities. Long-term viability favors targets with recurring content management revenue streams unbundled from hardware procurement. Watch dark-sky ordinance adoption velocity across Phoenix, Miami, and Dallas-Fort Worth as inflection indicator for dimmable driver demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Module Assembly | Captive semiconductor packaging insulates margin from pixel pitch commoditization pressure. |
| GB 7000 Compliance Certification Partnership | Shanghai laboratory relationships unlock China export channels for foreign facade systems. |
| Intelligent Lighting Control Platform Launch | Sensor integration for wayfinding captures specification premiums from corporate office buyers. |
| Franchise Network Density Expansion | Distributed service nodes sustain national coverage without centralized plant capital deployment. |
| Dark-Sky Ordinance Adaptation Program | Curfew programming capabilities meet municipal illumination restrictions in Sun Belt markets. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with sign fabrication executives, LED procurement managers at retail chains, municipal permitting officers, and electrical contractor supervisors; alongside secondary validation through US Department of Energy efficacy filings, China SAMR certification databases, EU Ecodesign Directive implementation reports, and customs trade records for aluminum and LED module imports. Bottom-up channel checks triangulated against top-down market sizing across product type, application, technology, and end-user dimensions.
Across the analysis window, the forecast framework modeled volume and value trajectories through segmentation by product category, regulatory compliance tier, geographic adoption cluster, and buyer procurement centralization. CAGRs were derived from trend extrapolation of retrofit program timelines, retail expansion pipelines, and technology substitution curves. Industry-specific inputs included LED pixel pitch compression rates and municipal dark-sky ordinance adoption patterns.
The analysis sits within stated boundaries; outcomes outside continued efficacy mandate enforcement and aluminum price stability would require recalibration. Forecasts reflect documented assumptions regarding skilled labor availability and franchise network expansion velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Eye-Illuminating Gadgets Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
COB Photo Light Market
Lighting
Recessed Lighting Market
Lighting
Explosion Proof Lighting Market
Lighting
Directional Luminaire Market
Lighting
Vintage Bulb Market
Lighting
Miniature Bulbs Market
Lighting
Solar Spotlights Market
Lighting
Flexible Lighting Foils Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
Photography Light Box Market
Lighting
UV Lamps Market
Lighting
Bulb Market
Lighting
Lighting Fixture Market