
 Industrial LiDAR Integrated Lighting Market | 2026-2036
Industrial LiDAR Integrated Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial LiDAR Integrated Lighting Market Insights
Modular sensor-lighting bundling is shifting procurement patterns across industrial facilities, replacing standalone LiDAR deployments with unified perception-illumination units. Hesai Group leverages its automotive-grade manufacturing scale to supply high-reliability modules for warehouse automation. RoboSense Technology anchors its position through deep specialization in solid-state architectures with integrated photonic arrays. Sick competes aggressively in European factory automation channels with application-specific configurations.
Industrial LiDAR integrated lighting denotes optoelectronic systems combining laser ranging with structured illumination, typically operating at 905 nm or 1550 nm wavelengths with pulse repetition rates exceeding 100 kHz for real-time spatial mapping in low-visibility industrial environments. These systems generate dense point clouds to enable machine vision, collision avoidance, and precision positioning across manufacturing and logistics operations. Solid-state LiDAR segments are capturing margin pools as MEMS-based and optical-phased-array designs displace mechanical spinning units in price-sensitive deployments. Time-of-Flight technology dominates current installations, though Frequency Modulated Continuous Wave architectures are gaining traction in applications requiring simultaneous range and velocity data. Warehouse Automation and Autonomous Guided Vehicles represent the fastest-growing application clusters as fulfillment operators demand sub-centimeter localization accuracy under variable lighting conditions.
The EU Machinery Directive and FDA laser safety classifications shape product certification pathways, with CE marking and 21 CFR 1040.10 compliance becoming mandatory gatekeepers for market access in Europe and the United States. China's GB standards and NMPA optoelectronic device regulations impose additional testing protocols for domestic deployment and export qualification. Stakeholders must monitor evolving wavelength-specific exposure limits and functional safety integrity levels as regulatory convergence between automotive and industrial certification frameworks accelerates design complexity.
Market Dynamics
Modular sensor-lighting bundling is compressing procurement cycles as warehouse operators abandon standalone LiDAR deployments in favor of unified perception-illumination units that reduce integration overhead and accelerate facility commissioning timelines.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for functional safety integrity are compelling factory automation buyers across Germany and Italy to upgrade legacy scanning systems with certified integrated units.
- Solid-state MEMS architecture maturation:Optical-phased-array designs are displacing mechanical spinning units in price-sensitive deployments, opening mid-tier warehouse automation segments previously blocked by cost barriers.
- Yangtze River Delta manufacturing corridor concentration:Automotive and electronics OEMs in Suzhou and Shanghai are embedding solid-state LiDAR into production-line lighting arrays at scale, creating demonstration effects for global facility designers.
Market Restraints
- 1550 nm indium gallium arsenide detector cost volatility:Specialized photodetector substrates face supply concentration among Japanese and Taiwanese foundries, inflating bill-of-materials for long-range industrial units.
- FDA 21 CFR 1040.10 laser safety certification friction:Wavelength-specific exposure limit testing adds six-to-nine month pre-market timelines that delay revenue recognition for North American product launches.
- Time-of-Flight velocity measurement limitation:Pulse-based architectures cannot deliver simultaneous range and Doppler data, forcing buyers toward costlier Frequency Modulated Continuous Wave alternatives for dynamic AGV applications.
Strategic Opportunities
- Underpenetrated cold-storage logistics vertical:Sub-zero warehouse operators in the United States and Germany remain underserved by standard LiDAR units prone to condensation failure, opening white space for hermetically sealed integrated designs.
- China GB standards export harmonization:Alignment between NMPA optoelectronic device regulations and IEC 60825-1 is reducing dual-certification burdens for domestic manufacturers targeting European markets.
- Photonic array-LED convergence:Solid-state LiDAR emitters and structured illumination diodes are merging onto single silicon substrates, enabling chip-scale integration that halves module footprint for narrow-aisle forklifts.
Industry Challenges
- Optomechanical assembly technician scarcity:Precision alignment of MEMS mirrors and collimating lenses requires skills concentrated among German and Japanese specialists, constraining production scaling.
- Multi-jurisdictional certification timeline compression:Simultaneous pursuit of CE marking, FDA 510(k) laser product clearances, and China GB testing stretches engineering resources across incompatible documentation standards.
- Legacy WMS integration complexity:Proprietary point-cloud data formats from integrated lighting units require middleware development to connect with existing warehouse management software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial LiDAR Integrated Lighting Market |
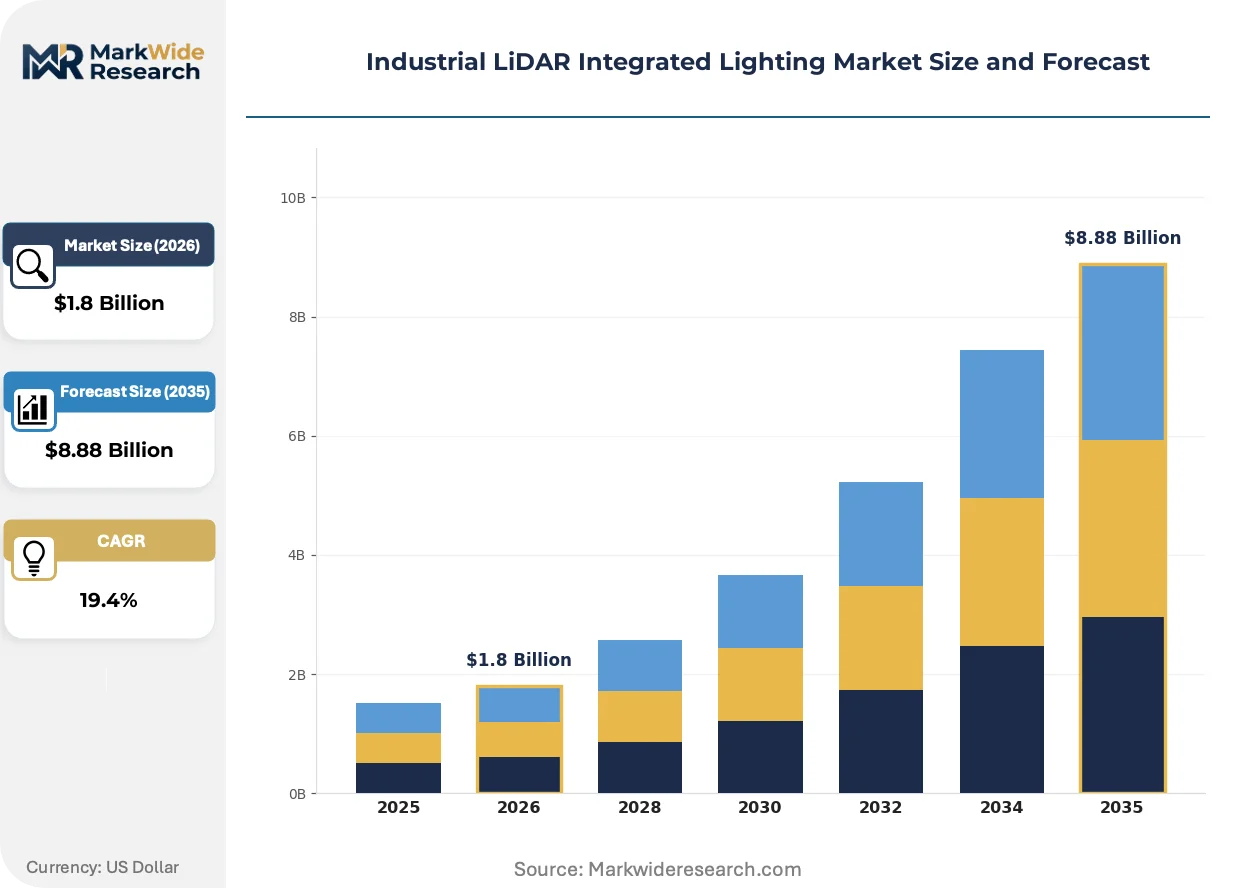
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D LiDAR, 3D LiDAR, Solid-State LiDAR, Flash LiDAR, Fiber-Based LiDAR Technology: Time-of-Flight, Frequency Modulated Continuous Wave, Phase Shift, Triangulation, Optical Coherence Tomography Application: Robotics, Warehouse Automation, Drone Navigation, Autonomous Guided Vehicles, Asset Inspection End User: Manufacturing Plants, Logistics Providers, Research Laboratories, Public Safety Agencies, Construction Contractors |
| Companies Covered | Hesai Group, RoboSense Technology, Ouster, Luminar Technologies, Innoviz Technologies, Leica Geosystems, Trimble, Sick, RIEGL Laser Measurement Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial LiDAR Integrated Lighting Market Trends and Innovations
Three intersecting developments are compressing product lifecycles and redrawing competitive boundaries: silicon photonics integration, regulatory convergence between automotive and industrial safety frameworks, and procurement model evolution toward specification-driven supplier consolidation.
Frequency Modulated Continuous Wave architectures are rewriting competitive positioning in high-dynamic-range applications. These systems emit chirped laser signals that return simultaneous range and velocity vectors without mechanical scanning components. Automotive-grade FMCW suppliers are repurposing production lines for industrial AGV customers demanding sub-centimeter localization under variable reflectivity conditions. The technology is rewriting margin structures by collapsing the historical premium between navigation-grade and safety-rated LiDAR tiers.
REACH substance restrictions and RoHS recast directives are tightening material compliance pathways for optoelectronic assemblies. European manufacturers must now document lead-free solder and restricted phthalate status across full supply chains to maintain CE marking validity. Industrial lighting-LiDAR bundles containing gallium arsenide components face heightened scrutiny under emerging end-of-life electronics recovery mandates, forcing redesigns of detector packaging and thermal management subsystems.
Specification-driven supplier consolidation is concentrating procurement authority among systems integrators with in-house optical engineering capabilities. Tier-one warehouse automation contractors in Germany and the United States are issuing unified performance specifications that bundle illumination uniformity, ranging precision, and safety certification requirements into single-source contracts. Channel intermediaries without optical design competence are losing position to direct manufacturer relationships, particularly in projects requiring custom wavelength selection for specific surface reflectance profiles.
Industrial LiDAR Integrated Lighting Market Segmentation
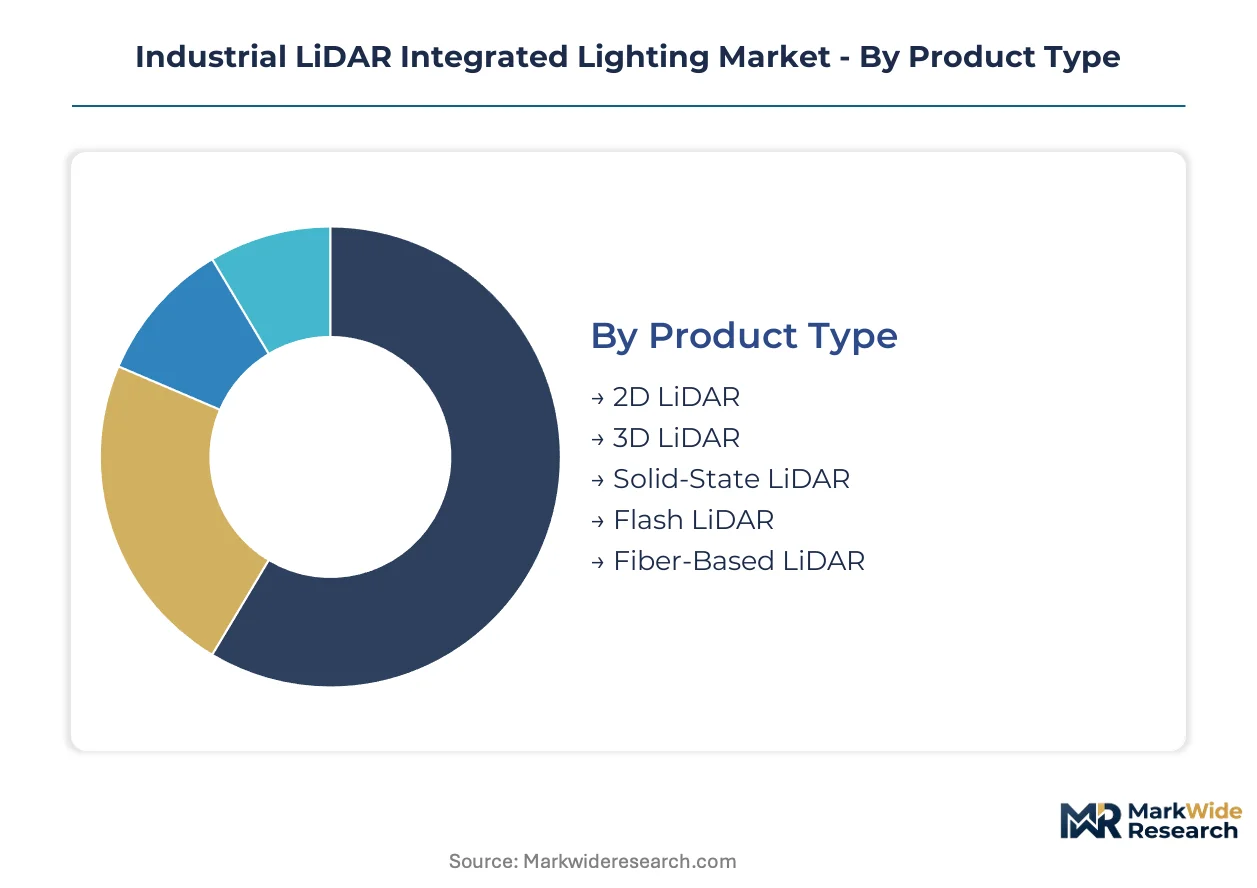
Industrial LiDAR integrated lighting systems fragment across four critical dimensions that determine certification pathways, integration complexity, and procurement economics. Buyers navigate wavelength-specific safety approvals, ranging-technology trade-offs, and end-use environmental constraints when specifying systems for facility deployment.
Product Type:
CE marking under the EU Machinery Directive and FDA 21 CFR 1040.10 laser product classifications impose divergent testing burdens across mechanical and solid-state architectures, with mechanical spinning units facing stricter rotational safety assessments.
- 3D LiDAR:Mechanical or hybrid scanning architectures generate dense volumetric point clouds through azimuth and elevation articulation. Warehouse automation buyers in Germany and the United States scale procurement for narrow-aisle navigation systems requiring sub-centimeter localization accuracy under variable reflectivity conditions.
- Solid-State LiDAR:MEMS mirror or optical-phased-array designs eliminate rotating assemblies through silicon-based beam steering. Automotive and electronics OEMs in China's Yangtze River Delta manufacturing corridor embed these units into production-line lighting arrays, creating reference architectures for global facility designers.
- 2D LiDAR:Single-plane scanning systems deliver linear ranging for perimeter monitoring and simple collision avoidance in cost-constrained deployments.
- Flash LiDAR:Diffuse illumination arrays capture entire scenes without mechanical components, suited to short-range volumetric measurement in confined industrial cells.
- Fiber-Based LiDAR:Erbium-doped fiber amplifiers extend operational range for long-line asset inspection across pipeline and conveyor infrastructure.
Leading the category by volume: Solid-State LiDAR. Growing fastest: 3D LiDAR.
Technology:
Cost tier separation between pulse-based and coherent detection architectures drives specification divergence, with Frequency Modulated Continuous Wave systems commanding premium positioning for velocity-capable applications.
- Time-of-Flight:Pulsed laser emission with direct detection of return signals dominates current installations through simpler signal processing and lower component counts. Logistics providers in high-volume warehouse automation favor ToF for standard AGV navigation where velocity data remains secondary.
- Frequency Modulated Continuous Wave:Chirped coherent detection delivers simultaneous range and Doppler velocity vectors without mechanical scanning. Automotive-grade FMCW suppliers repurpose production lines for industrial AGV customers demanding dynamic obstacle tracking under variable lighting conditions.
- Phase Shift:Continuous-wave interferometric ranging achieves millimeter precision for metrology and alignment applications in precision manufacturing.
- Triangulation:Structured light projection with stereo detection serves short-range inspection tasks in electronics assembly quality control.
- Optical Coherence Tomography:Low-coherence interferometry enables subsurface defect detection in composite material assessment for aerospace manufacturing.
Highest shipment volumes concentrate in Time-of-Flight. Steepest expansion trajectory: Frequency Modulated Continuous Wave.
Application:
Customer type segmentation separates specification-driven systems integrators from price-sensitive facility operators, with autonomous vehicle deployments demanding the most stringent functional safety integrity levels.
- Warehouse Automation:Integrated perception-illumination units enable narrow-aisle forklift navigation and inventory positioning in fulfillment centers. German and United States fulfillment operators specify sub-centimeter accuracy under condensation-prone cold-storage conditions.
- Autonomous Guided Vehicles:Mobile robotic platforms require real-time spatial mapping for dynamic path planning in unstructured industrial environments. Solid-state LiDAR-LED convergence on single silicon substrates halves module footprint for space-constrained AGV designs.
- Robotics:Collaborative robot arms utilize structured illumination for workpiece localization and safety-rated human detection in shared manufacturing cells.
- Drone Navigation:Lightweight solid-state units support indoor aerial inspection in hazardous facility zones inaccessible to ground vehicles.
- Asset Inspection:Long-range fiber-based systems monitor critical infrastructure integrity across pipeline networks and elevated conveyor systems.
Dominant application by procurement value: Warehouse Automation. Climbing the fastest: Autonomous Guided Vehicles.
End User:
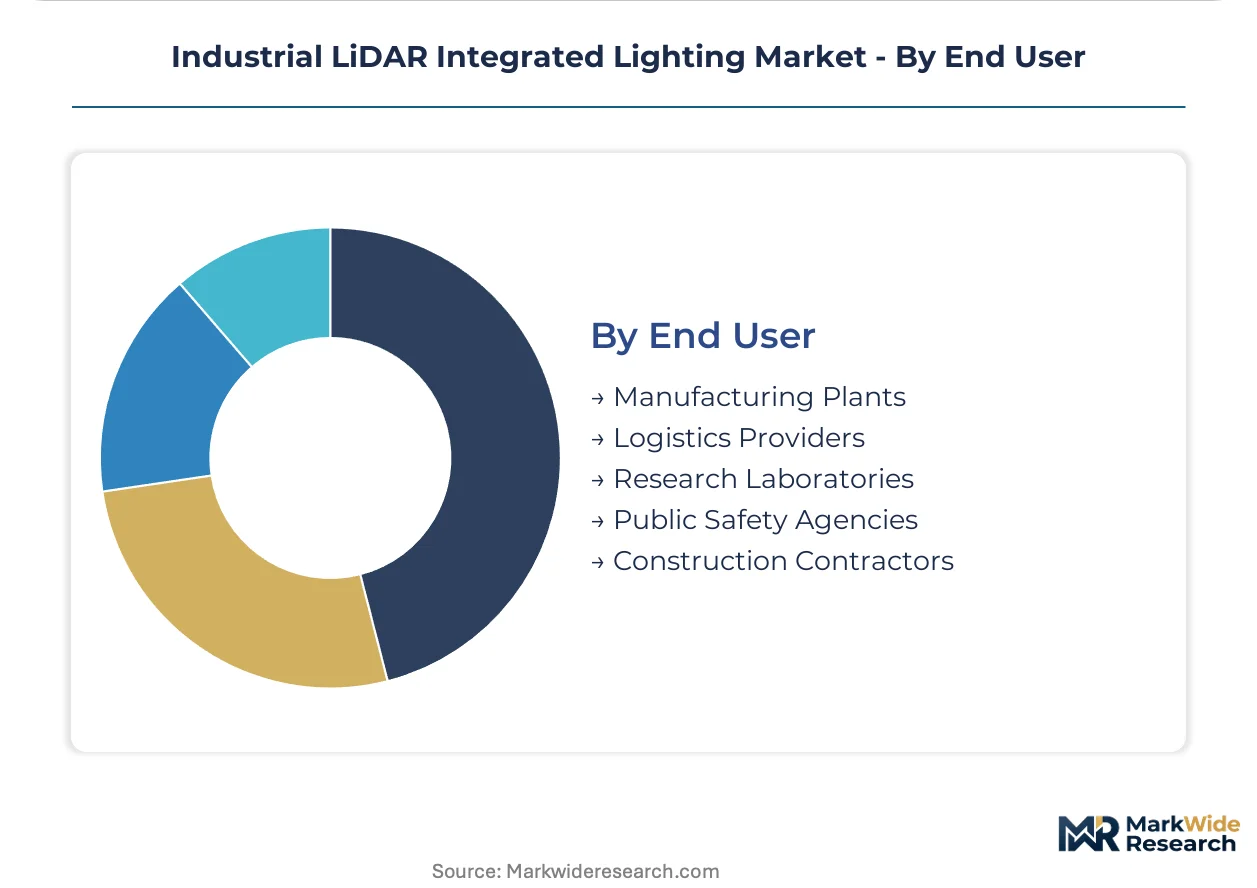
Geographic procurement patterns concentrate demand in manufacturing corridor clusters, with logistics providers and manufacturing plants driving divergent specification priorities around throughput versus precision.
- Manufacturing Plants:Automotive and electronics production facilities in Suzhou and Shanghai integrate solid-state LiDAR into production-line lighting arrays for real-time quality monitoring and robotic guidance.
- Logistics Providers:Third-party fulfillment operators in Germany and the United States scale 3D LiDAR procurement for narrow-aisle warehouse automation, prioritizing rapid facility commissioning over customization.
- Research Laboratories:Metrology and calibration facilities drive demand for phase-shift and triangulation systems requiring NIST-traceable accuracy verification.
- Public Safety Agencies:Hazardous environment response teams deploy portable flash LiDAR units for rapid 3D scene documentation in industrial incident reconstruction.
- Construction Contractors:Earthmoving and site preparation fleets adopt ruggedized 2D LiDAR for equipment proximity alerting in dusty, vibration-intensive conditions.
Largest installed base: Manufacturing Plants. Gaining share fastest: Logistics Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in China's Yangtze River Delta while consumption concentrates in German and United States warehouse automation markets. This geographic split shapes certification requirements and supply chain configurations across the value chain.
China
Automotive and electronics OEMs in Suzhou and Shanghai drive solid-state LiDAR integration into production-line lighting arrays. NMPA optoelectronic device regulations and GB standards impose testing protocols for both domestic deployment and export qualification. The Yangtze River Delta manufacturing corridor generates demonstration effects that influence global facility design patterns.
Germany
Narrow-aisle navigation demand from fulfillment operators compels procurement of 3D LiDAR units with sub-centimeter accuracy specifications. CE marking under the EU Machinery Directive mandates functional safety integrity upgrades for legacy scanning systems. Bavarian and North Rhine-Westphalian automation clusters anchor European demand for certified integrated perception-illumination units.
United States
Cold-storage logistics operators in the Midwest and Southeast remain underserved by standard LiDAR prone to condensation failure. FDA 21 CFR 1040.10 laser safety certification adds six-to-nine month pre-market timelines for product launches. California and Texas distribution centers specify hermetically sealed designs for sub-zero warehouse environments.
Japan
Precision optomechanical assembly skills concentrate among Japanese specialists capable of aligning MEMS mirrors and collimating lenses. METI industrial technology roadmaps support photonics integration investments. Osaka and Nagoya manufacturing zones supply specialized photodetector substrates to long-range industrial unit producers.
South Korea
Seoul Capital Area electronics fabricators source solid-state LiDAR modules for robotic guidance systems in precision manufacturing. MFDS optoelectronic safety standards align with IEC 60825-1 frameworks to reduce dual-certification burdens. Busan-Ulsan industrial corridors test automotive-grade FMCW repurposing for AGV navigation applications.
Industrial LiDAR Integrated Lighting Market Competitive Landscape
The competitive structure tilts toward automotive-scale manufacturers repurposing production lines for industrial segments. Tier-one warehouse automation contractors in Germany and the United States consolidate procurement authority through unified performance specifications bundling illumination uniformity, ranging precision, and safety certification. Three archetypes dominate: automotive-grade scale players, solid-state architecture specialists, and European factory automation incumbents with application-specific configurations. Dominant competitive moves include strategic partnerships with systems integrators possessing in-house optical engineering capabilities and portfolio diversification toward Frequency Modulated Continuous Wave architectures.
Among China-based automotive-scale suppliers, Hesai Group and RoboSense Technology occupy positions exemplifying the migration from passenger vehicle to industrial warehouse applications. Sick anchors the European factory automation channel with CE marking expertise and application-specific configuration capabilities. These three represent the archetype spectrum: scale-driven manufacturing repurposing, solid-state architecture specialization, and regional regulatory navigation.
| Leading Market Players |
|---|
| Hesai Group |
| RoboSense Technology |
| Ouster |
| Luminar Technologies |
| Innoviz Technologies |
| Leica Geosystems |
| Trimble |
| Sick |
| RIEGL Laser Measurement Systems |
| Others |
Pricing and Supply Chain Analysis
Warehouse automation buyers in Germany and the United States consolidating procurement authority around unified perception-illumination specifications are forcing suppliers to absorb integration engineering costs, compressing margins on standard mechanical units while solid-state architectures capture premium positioning.
Pricing Analysis
Price erosion across mechanical spinning LiDAR tiers traces to MEMS-based optical-phased-array designs displacing legacy azimuth-elevation articulation in mid-tier warehouse automation segments. Pricing stratifies across automotive-grade certified, industrial safety-rated, and uncertified economy tiers, with CE marking and FDA 21 CFR 1040.10 compliance commanding substantial premiums. Cost compression in economy segments accelerates because Chinese solid-state suppliers leverage Yangtze River Delta manufacturing scale. Logistics providers operating high-volume fulfillment centers exhibit greatest price sensitivity, while cold-storage operators in sub-zero environments accept premiums for hermetically sealed integrated designs.
Supply Chain Analysis
CE marking and FDA laser safety certification gating creates six-to-nine month pre-market timelines that constrain supplier responsiveness and concentrate order book visibility among pre-qualified manufacturers. Component supply draws from Japanese and Taiwanese foundries for indium gallium arsenide photodetector substrates, Chinese silicon photonics fabs for MEMS mirror arrays, and German optomechanical assembly specialists for precision collimation. Single-source vulnerability around 1550 nm detector substrates inflates bill-of-materials volatility for long-range industrial units. Distribution runs through tier-one warehouse automation contractors in Bavaria and North Rhine-Westphalia issuing unified performance specifications, bypassing channel intermediaries lacking optical engineering competence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive's functional safety integrity mandates erect a cost-of-compliance barrier that rewards incumbents with pre-certified product portfolios while forcing marginal competitors toward aftermarket service arbitrage or exit.
For Market Incumbents: To counter solid-state architecture specialists capturing mid-tier warehouse automation share, accelerate backward integration into silicon photonics fabrication capacity and deepen CE marking expertise through dedicated European certification engineering teams in Stuttgart or Munich. Prioritize captive supply of MEMS mirror substrates to insulate against Taiwanese foundry allocation constraints. For New Entrants and Emerging Players: FDA 21 CFR 1040.10 laser safety certification friction in the United States opens a window for cold-storage logistics specialization, where hermetic sealing against condensation failure remains underserved by incumbent mechanical unit portfolios. Target Midwest and Southeast distribution centers with sub-zero specifications, leveraging direct sales relationships bypassing systems integrator consolidation. For Investors and Strategic Acquirers: The window for entry favors automotive-grade LiDAR manufacturers with repurposable production lines and existing NMPA optoelectronic device qualifications for China export harmonization. Watch for GB standards alignment with IEC 60825-1 as the signal indicating reduced dual-certification burden and accelerated European market penetration for Chinese-origin suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Frequency Modulated Continuous Wave Architecture Migration | Automotive-grade FMCW suppliers repurposing production lines collapse historical premiums between navigation-grade and safety-rated LiDAR tiers. |
| Silicon Photonics Integration Investment | Single-substrate convergence of solid-state LiDAR emitters and structured illumination diodes halves module footprint for narrow-aisle forklift designs. |
| Hermetic Sealing Certification for Cold-Storage | Sub-zero warehouse operators in the United States and Germany remain underserved, creating white space for specialized integrated designs. |
| CE Marking and FDA Dual-Certification Pursuit | Simultaneous compliance with EU Machinery Directive and 21 CFR 1040.10 opens access to German and United States procurement consolidation. |
| Photonic Array-LED Convergence R&D | Chip-scale integration on single silicon substrates enables specification-driven supplier consolidation among tier-one warehouse automation contractors. |
Research Methodology
SEC 10-K filings, EU Machinery Directive certification databases, and NMPA optoelectronic device registration records formed the secondary backbone, cross-referenced against primary interviews with warehouse automation procurement directors, MEMS fabrication engineering leads, and optomechanical assembly technicians. Tier-one systems integrators in Germany and the United States, solid-state LiDAR module suppliers in Suzhou and Shanghai, and precision optics specialists in Osaka and Nagoya provided forward-looking deployment timelines and specification evolution trajectories. Bottom-up unit shipment estimates triangulated against top-down facility automation capex projections.
Historical trendline analysis of automotive LiDAR cost curves and industrial lighting fixture pricing informed elasticity assumptions across the projection horizon. Segmentation modeling incorporated product type, ranging technology, application cluster, and end-user geography dimensions. CAGRs derived from fitted adoption curves weighted against regulatory compliance timeline constraints. Industry-specific inputs included FDA 510(k) laser product clearance duration distributions and Yangtze River Delta manufacturing capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for Frequency Modulated Continuous Wave architectures displacing Time-of-Flight in dynamic AGV applications would alter the outlook. Forecasts reflect assumptions around CE marking timeline compression and GB standards export harmonization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Street Lighting Market
Lighting
Photocell Market
Lighting
Europe Decorative Lighting Market
Lighting
Solar Spotlights Market
Lighting
Graphene Lighting Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Street and Roadway Lighting Market
Lighting
Solid State Lighting System Market
Lighting
Xenon Headlights Market
Lighting
Vintage Bulb Market
Lighting
Ultraviolet Lamps Market
Lighting
OLED Lightening Panels Market
Lighting
Illuminating Signs Market
Lighting
Dimmer and Color Tunable Market