
 Dimmers Market | 2026-2036
Dimmers Market Size, Share, and Industry Trends Forecast 2026-2036
Dimmers Market Analysis
Electrical wholesale distribution is reconfiguring as smart lighting ecosystems displace traditional hardware-centric stocking. Lutron Electronics leverages its proprietary wireless protocols to sustain premium positioning in residential automation channels. Leviton Manufacturing anchors North American supply through deep contractor relationships and broad code-compliant portfolios. Schneider Electric competes on integrated building-management platforms that bundle dimming with energy analytics.
A dimmer is an electrical device that varies the intensity of light output by modulating voltage or current supplied to a lamp, typically supporting loads from 300W to 2000W and operating across 0-10V, DALI, or phase-cut control protocols. Its primary commercial purpose is to reduce energy consumption, extend lamp life, and enable ambiance control in built environments. Smart Dimmers command the fastest expansion as voice-assistant compatibility and app-based scheduling shift homeowner expectations, while Rotary Dimmers occupy a mature, price-sensitive replacement niche in legacy installations. Architectural Lighting applications concentrate margin pools where spec-grade precision and DMX512 programmability justify premium positioning.
The EU Green Deal and REACH chemical compliance constrain material choices for dimmer housings and PCB substrates, while the US Energy Independence and Security Act sets minimum efficacy thresholds that phase out incompatible incandescent-only controls. China's GB standards and CCC certification govern harmonic distortion limits and electromagnetic compatibility for devices entering its massive residential construction pipeline. Stakeholders must monitor divergence between regional interoperability protocols as wireless mesh standards fragment and procurement specifications harden around cybersecurity credentials.
Market Dynamics
Wireless mesh protocols are fragmenting procurement specifications across residential and commercial channels, forcing manufacturers to certify against multiple interoperability standards simultaneously while energy efficiency mandates compress compatible product lifecycles.
Growth Catalysts
- EU Green Deal efficiency mandates:Building codes across Germany, France, and Italy now require dimmable LED compatibility in new construction, accelerating replacement of legacy phase-cut controls.
- Smart home voice integration:Amazon Alexa and Google Home compatibility has become a baseline specification for residential retrofit projects in North American and European markets.
- China's urban residential pipeline:Massive construction volume in tier-one and tier-two cities is absorbing digital dimming systems at scale for high-rise residential towers.
Market Restraints
- Copper and rare earth magnet volatility:Input cost swings for PCB substrates and magnetic components compress margin predictability for mid-tier manufacturers.
- Wireless protocol fragmentation:Competing mesh standards (Zigbee, Z-Wave, Thread, proprietary) force redundant R&D expenditure and inventory duplication.
- Incandescent-only control obsolescence:US Energy Independence and Security Act efficacy thresholds have rendered legacy triac dimmers incompatible with modern LED loads.
Strategic Opportunities
- India's commercial real estate modernization:BIS certification alignment and PLI scheme incentives are opening specification pathways for DALI-compliant building automation.
- Healthcare circadian lighting:Tunable white dimming systems are penetrating hospital and eldercare facilities where HCL (human-centric lighting) protocols justify premium positioning.
- Cybersecurity credential hardening:IEC 62443 certification is becoming a procurement differentiator for connected dimmers in corporate and government installations.
Industry Challenges
- Firmware engineering scarcity:Qualified embedded systems developers capable of wireless stack integration command compensation premiums that strain mid-cap R&D budgets.
- Multi-protocol certification timelines:Simultaneous FCC, CE, and CCC approval cycles extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimmers Market |
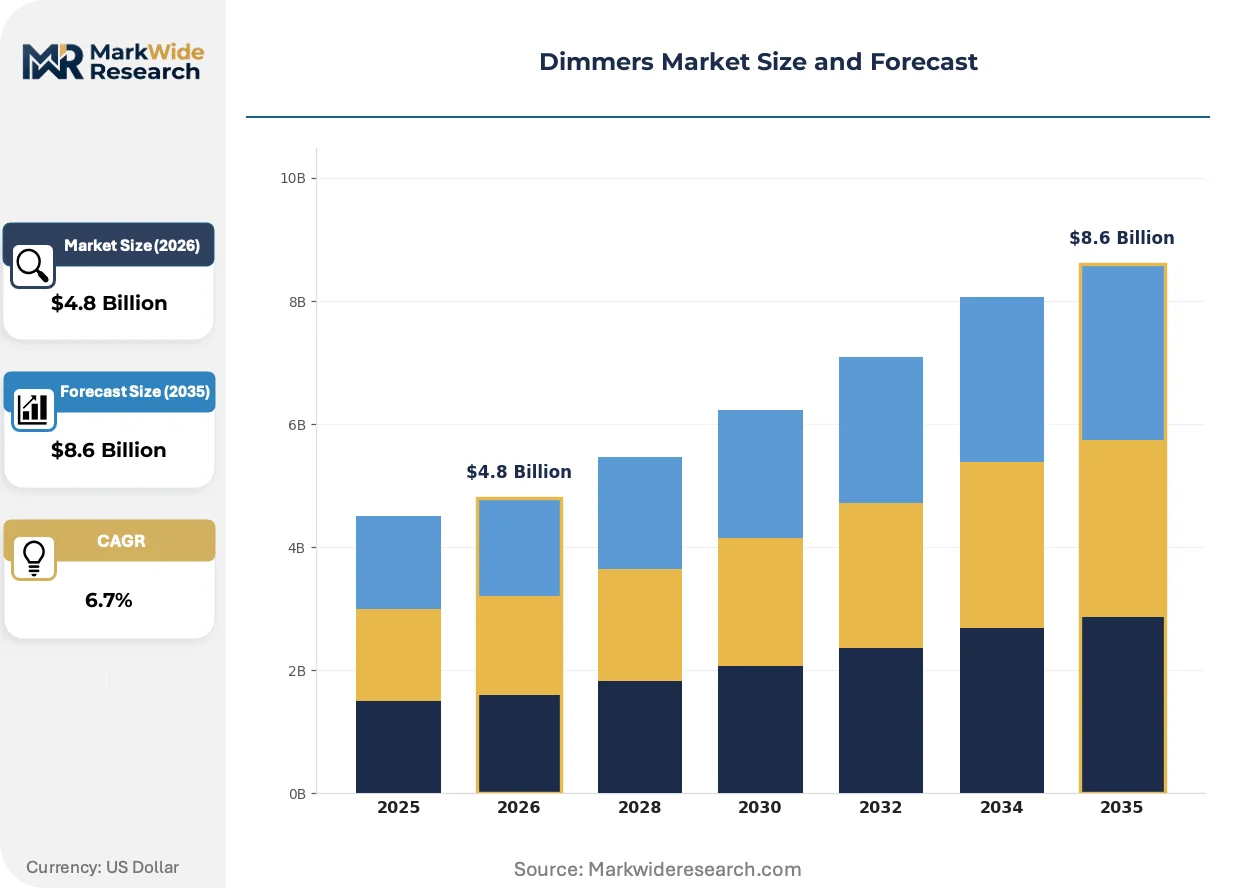
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Dimmers, Slide Dimmers, Touch Dimmers, Smart Dimmers Application: Residential Lighting, Commercial Lighting, Stage Lighting, Architectural Lighting Technology: Analog Dimming, Digital Dimming, Wireless Control, Line Voltage Dimming End User: Homeowners, Contractors, Event Planners, Architects |
| Companies Covered | Lutron Electronics, Leviton Manufacturing, Acuity Brands, Legrand, Schneider Electric, Eaton Corporation, Signify, Hubbell, Philips Lighting Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimmers Market Emerging Trajectories
Digital control architectures are supplanting analog phase-cut mechanisms across all load categories, while regulatory pressure on embodied carbon and interoperability is reshaping certification requirements and procurement criteria simultaneously.
Bluetooth Low Energy mesh is digitizing residential lighting control by enabling direct smartphone commissioning without dedicated hubs. Homeowners in US and UK markets are adopting app-based scheduling and geofencing features at rates that render traditional wall-switch dimming secondary. The technology is digitizing installer workflows and collapsing distributor SKU counts as multi-protocol chips consolidate hardware platforms.
REACH chemical compliance and RoHS substance restrictions are constraining housing material choices for dimmer manufacturers serving European markets. ECHA substance-of-very-high-concern listings now cover specific flame retardants and plasticizers common in legacy electrical enclosures. German and Dutch specifiers are responding by mandating halogen-free PCB substrates and recyclable housing polymers in public procurement tenders.
Electrical contractors are bundling dimming specification with broader smart home system sales rather than treating controls as standalone hardware. This pattern compresses traditional wholesale distributor margins while elevating systems integrator influence in US residential and light commercial channels. The shift is most visible in California and New York metro markets where Title 24 and Local Law 97 compliance complexity favors turnkey provider relationships over product-centric purchasing.
Dimmers Market Segmentation
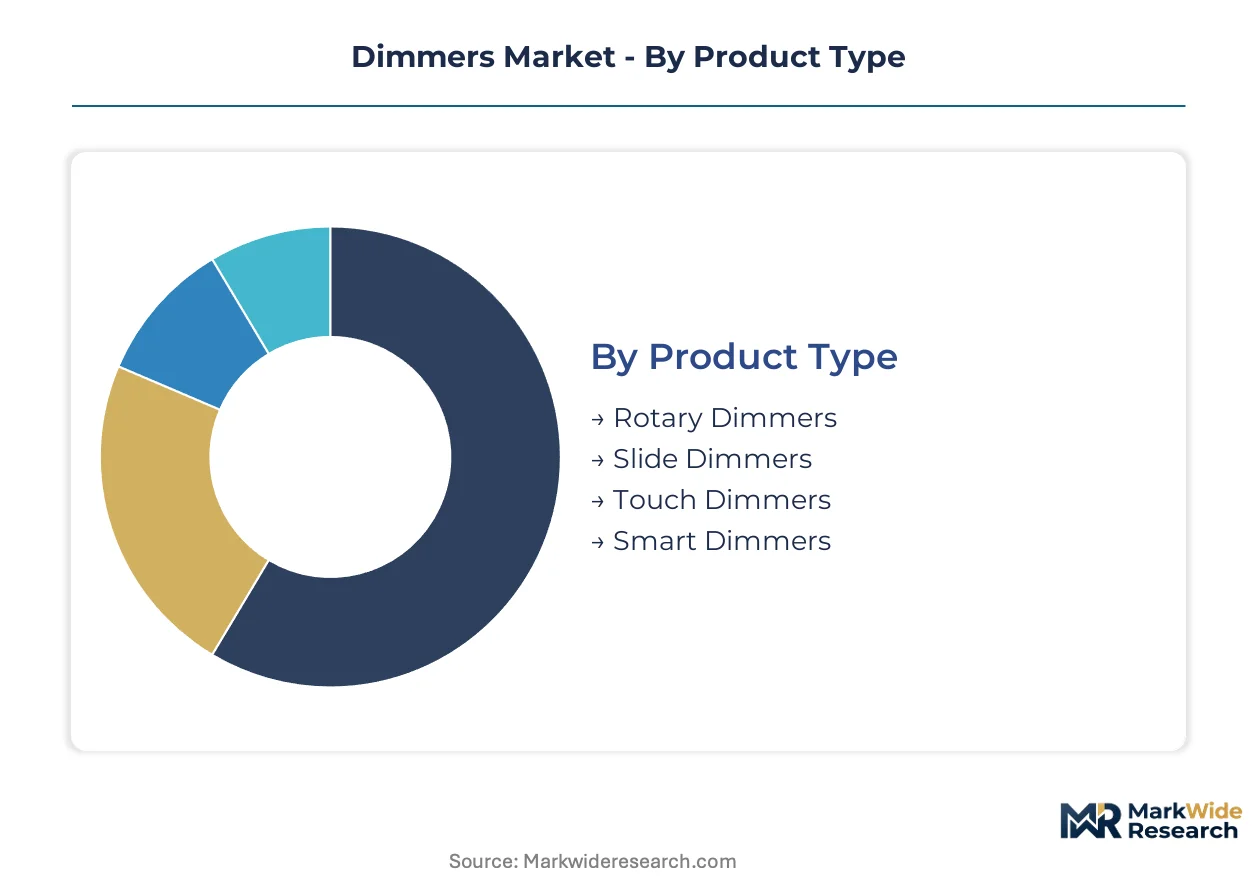
Dimmer segmentation reveals divergent margin structures across installation complexity and control sophistication. After-sales service intensity varies sharply between legacy hardware replacement and connected system maintenance.
Product Type:
Service attach rates climb steeply from mechanical replacement parts to firmware-dependent smart controls.
- Smart Dimmers:Microprocessor-based units with wireless stack integration and over-the-air update capability. Demand concentrates in US and UK residential retrofits where Amazon Alexa and Google Home compatibility drives specification. Firmware engineering scarcity inflates service contract pricing.
- Rotary Dimmers:Legacy phase-cut mechanisms using triac or trailing-edge topology. Replacement volume persists in Germany and France where existing incandescent installations resist full LED conversion. Price compression limits manufacturer service investment.
- Slide Dimmers:Linear potentiometer controls for manual intensity adjustment.
- Touch Dimmers:Capacitive-sensor interfaces with memory preset functionality.
By volume, Rotary Dimmers leads. By growth pace, Smart Dimmers is ahead.
Application:
Specification authority shifts from electrical contractors toward systems integrators as control complexity deepens.
- Architectural Lighting:Spec-grade precision dimming with DMX512 programmability and tunable white capability. Demand clusters in Dubai and Singapore high-rise developments where facade lighting and circadian protocols justify premium positioning. Human-centric lighting mandates in healthcare facilities accelerate specification.
- Residential Lighting:Single-family and multi-family dwelling installations spanning retrofit and new construction. Volume procurement in China's tier-one cities absorbs digital dimming systems at scale for high-rise residential towers. Smart home voice integration has become baseline specification.
- Commercial Lighting:Office, retail, and hospitality environments requiring centralized control.
- Stage Lighting:Entertainment venues requiring high-channel-count DMX control.
Residential Lighting dominates unit shipments. Architectural Lighting captures the steepest expansion trajectory.
Technology:
Control architecture migration from analog to digital is compressing compatible product lifecycles.
- Wireless Control:Mesh-networked dimming using Zigbee, Z-Wave, Thread, or proprietary protocols. Fragmentation across standards forces redundant R&D expenditure and inventory duplication. Bluetooth Low Energy mesh enables direct smartphone commissioning without dedicated hubs.
- Digital Dimming:DALI-2 and 0-10V protocols enabling centralized building management integration. EU Green Deal efficiency mandates in Germany, France, and Italy require dimmable LED compatibility in new construction.
- Analog Dimming:Phase-cut and leading-edge legacy mechanisms.
- Line Voltage Dimming:Direct mains-voltage control without external power supplies.
Digital Dimming leads in commercial specification. Wireless Control is climbing the fastest.
End User:
Procurement influence fragments across project scale and technical sophistication.
- Contractors:Electrical installation professionals specifying controls for new construction and retrofit. Deep relationships with Leviton Manufacturing and Lutron Electronics anchor North American supply. Bundling dimming with broader smart home system sales compresses traditional wholesale distributor margins.
- Homeowners:End consumers purchasing through retail and e-commerce channels. App-based scheduling and geofencing features in US and UK markets render traditional wall-switch dimming secondary. Voice-assistant compatibility shifts expectations.
- Architects:Design professionals specifying aesthetic and functional performance.
- Event Planners:Temporary installation coordinators for entertainment and corporate events.
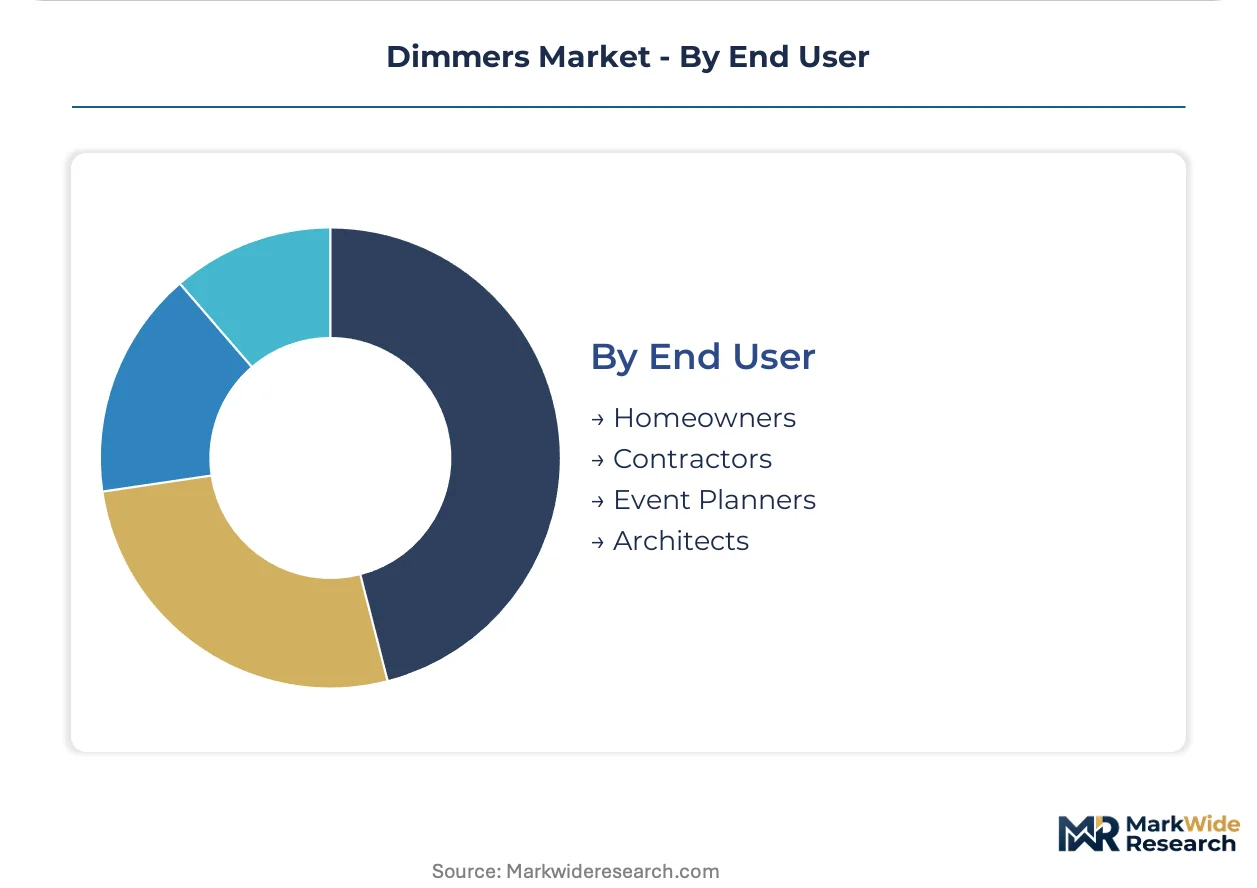
Contractors control commercial volume. Homeowners are gaining share fastest in residential channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards and CCC certification govern China's massive residential construction pipeline, while the EU Green Deal efficiency mandates reshape procurement specifications across Germany, France, and Italy. The United States anchors commercial specification through Title 24 and Local Law 97 compliance complexity.
China
Tier-one and tier-two cities absorb digital dimming systems at scale for high-rise residential towers. GB standards and CCC certification enforce harmonic distortion limits and electromagnetic compatibility for devices entering this construction pipeline. Shanghai and Beijing clusters concentrate procurement volume for smart home-integrated wireless controls.
Germany
Building codes now require dimmable LED compatibility in new construction, accelerating replacement of legacy phase-cut controls. REACH chemical compliance and RoHS substance restrictions constrain housing material choices for manufacturers serving this market. Frankfurt and Munich specification channels drive DALI-2 protocol adoption in commercial building automation.
United States
Title 24 and Local Law 97 compliance complexity favors turnkey provider relationships over product-centric purchasing in California and New York metro markets. FCC certification governs wireless mesh protocol deployment across residential retrofit channels. Electrical contractors bundle dimming specification with broader smart home system sales, compressing traditional wholesale distributor margins.
India
BIS certification alignment and PLI scheme incentives open specification pathways for DALI-compliant building automation in commercial real estate modernization. The country's national electrical regulator enforces safety standards for connected lighting controls entering this expansion pipeline. Mumbai and Delhi-NCR construction clusters concentrate demand for centralized building management integration.
United Kingdom
Bluetooth Low Energy mesh enables direct smartphone commissioning without dedicated hubs, digitizing residential lighting control adoption. CE marking requirements govern product entry despite post-Brexit regulatory divergence. London and Southeast England installer channels drive app-based scheduling and geofencing feature specification at rates rendering traditional wall-switch dimming secondary.
Dimmers Market Vendor Landscape
Specialist wireless protocol developers and diversified electrical component conglomerates split the market between premium residential automation and broad code-compliant portfolios. The vendor base concentrates around three strategic archetypes: proprietary protocol specialists, contractor-relationship anchors, and integrated building-management platform providers. Dominant competitive moves include strategic partnerships for multi-protocol certification and portfolio diversification into energy analytics bundling.
Within the proprietary protocol tier, Lutron Electronics exemplifies premium positioning through wireless stack control. Leviton Manufacturing occupies the contractor-relationship anchor position in North American supply channels. Schneider Electric represents the integrated platform archetype, bundling dimming functionality with broader building automation systems.
| Leading Market Players |
|---|
| Lutron Electronics |
| Leviton Manufacturing |
| Acuity Brands |
| Legrand |
| Schneider Electric |
| Eaton Corporation |
| Signify |
| Hubbell |
| Philips Lighting Holding |
| Others |
Supply Flow & Price Mechanics
Shenzhen's PCB substrate manufacturing cluster anchors global dimmer electronics production, with capacity utilization swings directly transmitting to downstream margin pressure across wireless control tiers. Guangdong province component concentration grants local assemblers procurement leverage that distant manufacturers cannot replicate, compressing pricing power for mid-tier brands serving European retrofit channels.
Pricing Analysis
Price spreads between Shenzhen-sourced and European-manufactured dimmer units now exceed three-to-one for equivalent wireless specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and firmware update commitment, with UL-listed smart dimmers commanding substantial premiums over CCC-only equivalents. Cost compression in rotary dimmer tiers is intensifying because incandescent-only control obsolescence has eliminated replacement demand elasticity. Contractors exhibit highest price sensitivity in bulk commercial procurement, while healthcare specifiers demonstrate lowest sensitivity where circadian protocol compliance justifies premium positioning.
Supply Chain Analysis
Copper laminate and rare earth magnet feedstock volatility sits at the core of input cost unpredictability for dimmer manufacturers. Production gravity centers on China, Vietnam, and Mexico, with PCB fabrication drawing from East Asian substrate specialists while final assembly migrates toward tariff-advantaged locations. Single-source vulnerability concentrates in Zigbee and Thread radio chip supply, where Qualcomm and Silicon Labs capacity constraints ripple through certification timelines. Distribution runs through electrical wholesale channels that are collapsing as contractors bypass traditional stocking for direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless protocol fragmentation fragments competitive space into certification-niche battlegrounds, creating entry points for specialists who master single-standard precision rather than multi-protocol breadth. Smart home voice integration shifts specification authority toward systems integrators, opening margin pools outside traditional hardware-centric positioning.
For Market Incumbents: Build firmware ecosystem moats through over-the-air update infrastructure that locks contractors into recurring service relationships. Deepen backward integration into radio chip sourcing to insulate against Silicon Labs and Qualcomm allocation constraints. Defensive patent clustering around Bluetooth Low Energy mesh commissioning workflows blocks emerging entrants from smartphone-direct configuration parity.
For New Entrants and Emerging Players: India's tier-two commercial real estate corridors offer the most penetrable geographic whitespace, with BIS certification alignment costs substantially below FCC or CE cycles. Healthcare circadian lighting specifications in eldercare facilities present the most accessible application niche, with DALI-2 compliance requirements still sparsely contested. Go-to-market execution should anchor on systems integrator partnerships rather than wholesale distributor relationships that incumbent contractor ties already dominate.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because wireless stack R&D fixed costs will compress mid-cap specialist viability as multi-protocol certification burdens compound. Acquisition targets should profile as regional DALI-2 compliance specialists with healthcare specification relationships and captive firmware engineering teams. The signal to watch is IEC 62443 cybersecurity credential adoption rates in corporate procurement tenders, which will bifurcate investable from stranded asset positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Chip Consolidation | Qualcomm and Silicon Labs platform integration collapses distributor SKU counts and digitizes installer workflows. |
| IEC 62443 Certification Investment | Cybersecurity credential hardening opens corporate and government procurement pathways previously blocked to connected dimmer vendors. |
| Healthcare Circadian Lighting Partnership | Human-centric lighting protocol adoption in eldercare facilities justifies premium positioning for tunable white dimming systems. |
| India BIS Certification Alignment | PLI scheme incentives and commercial real estate modernization create specification pathways for DALI-compliant building automation entrants. |
| Contractor Direct Relationship Buildout | Bypassing wholesale distributors captures margin compression from bundling dimming with broader smart home system sales. |
Methodological Framework
The analysis maps smart dimmer, rotary dimmer, slide dimmer, and touch dimmer sub-sectors, each validated through electrical contractor interviews, systems integrator consultations, and lighting specifier discussions. Primary fieldwork with procurement managers at tier-one residential developers and healthcare facility planners cross-referenced against secondary validation from FCC equipment authorization databases, CE marking registries, and CCC certification listings. Customs trade data for PCB substrate and radio chip imports, alongside SEC filings from listed electrical component conglomerates, anchored bottom-up and top-down triangulation.
Assumptions held fixed include EU Green Deal efficiency mandate enforcement timelines and China's urban residential construction pipeline absorption rates, while wireless protocol adoption curves and copper price trajectories were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, application, control technology, and end-user procurement authority across the analysis window. CAGRs derived from unit shipment trajectories by segment, with pricing elasticity assumptions calibrated against historical phase-cut to digital control migration patterns and firmware update attach rate trends.
Practitioners should monitor REACH substance-of-very-high-concern listing expansions and Thread protocol certification backlog durations for early signals of forecast revision triggers. Cross-checking against IEA building energy efficiency deployment benchmarks and national smart home adoption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Headlight Control Module Market
Lighting
High Bay Lighting Market
Lighting
Bacteriological Light Market
Lighting
Smart Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
Solar Spotlights Market
Lighting
Lighting Market
Lighting
Residential Lighting Fixtures Market
Lighting
Smart Lights Market
Lighting
Hazardous Lighting Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Photocell Market
Lighting
North America Smart Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Industrial LiDAR Integrated Lighting Market