
 Asia-Pacific Hazardous Lighting Market | 2026-2036
Asia-Pacific Hazardous Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hazardous Lighting Market Outlook
Explosion-proof certification tiers above IECEx/ATEX Zone 1 is collapsing the gap between premium industrial lighting and commodity construction fixtures. R. Stahlin Pte Ltd leverages its Singapore engineering base to dominate Southeast Asian offshore platform retrofits. Shenzhen CESP Co Ltd anchors high-volume LED production for Chinese petrochemical complexes through backward integration into driver electronics. Iwasaki Electric Co., Ltd. sustains technical leadership in high-pressure sodium replacements for Japanese LNG terminals.
Asia-Pacific hazardous lighting denotes sealed luminaires engineered to contain internal arcs and limit surface temperatures below auto-ignition thresholds of surrounding gas or dust atmospheres, typically achieving T6 temperature codes and IP66/67 ingress ratings through cast aluminum housings with tempered glass lenses. These fixtures prevent catastrophic ignition in environments where flammable vapors, combustible dusts, or volatile chemical mists persist. LED product lines now capture the bulk of replacement demand as lumen maintenance and thermal management outpace fluorescent alternatives in high-ambient installations. Chemical processing applications generate the steepest specification upgrades as facilities in South Korea and Taiwan replace legacy HID arrays with smart-enabled systems integrating motion sensors for energy reduction in intermittently occupied units. Marine operations represent a concentrated margin pool where salt-corrosion resistance and shock compliance justify substantial price premiums over standard industrial grades.
China's NMPA and SAMR enforce GB 3836 series standards that mandate incremental testing for flameproof and increased-safety constructions, while Australia's IECEx certification scheme administered by the central regulatory body governs equipment acceptance for mining and oilfield deployment. India's CEA electrical safety directives and BIS certification requirements for hazardous area equipment are tightening import compliance timelines and reshaping supplier qualification protocols. Stakeholders must monitor divergence between China's national GB standards and IECEx international frameworks when configuring regional product platforms.
Market Dynamics
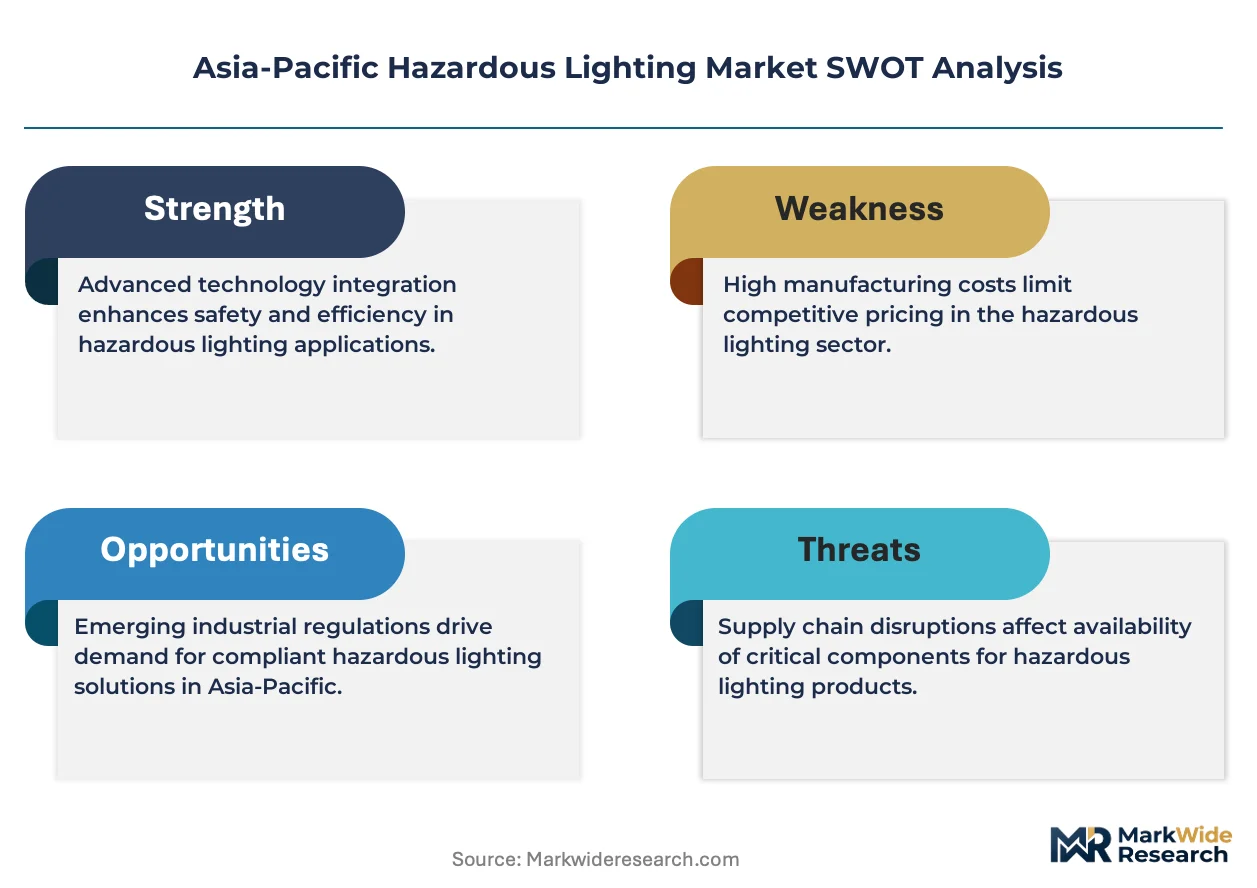
LED thermal management breakthroughs are collapsing the performance gap between explosion-proof fixtures and conventional industrial lighting, triggering wholesale replacement cycles across Asia-Pacific petrochemical corridors.
Growth Catalysts
- GB 3836 Certification Mandates:China's SAMR enforcement of stricter flameproof testing protocols is compelling facility operators to upgrade legacy HID installations with certified LED arrays.
- Offshore Platform Electrification:Southeast Asian oilfield operators are accelerating fixture replacement schedules to meet IECEx Zone 1 standards for drilling rig illumination.
- Smart Sensor Convergence:Motion-activated dimming systems integrated into hazardous-rated housings are reducing energy consumption in intermittently occupied chemical processing units.
Market Restraints
- Driver Electronics Supply Concentration:Dependence on Shenzhen-based semiconductor packaging creates vulnerability to regional logistics disruptions.
- Cast Aluminum Input Volatility:Primary metal price swings directly compress margins for housing manufacturers serving Australian mining procurement.
- Extended IECEx Certification Timelines:Australia's central regulatory body processing delays stretch product qualification cycles beyond eighteen months.
Strategic Opportunities
- Vietnam Petrochemical Buildout:Greenfield refinery complexes in Vung Tau and Binh Duong provinces require complete hazardous lighting infrastructure.
- Hydrogen Economy Infrastructure:Japanese LNG terminal retrofits for ammonia co-firing create demand for T6-rated fixtures in cryogenic zones.
- Digital Twin Integration:Luminaires with embedded condition monitoring sensors enable predictive maintenance contracts in South Korean smart factories.
Industry Challenges
- Explosion-Proof Engineering Talent Scarcity:Shortage of certified designers fluent in both thermal modeling and pressure-purged enclosure standards limits product development velocity.
- Legacy System Integration Complexity:Retrofitting smart-enabled LED arrays into existing DCS architectures in Taiwanese chemical plants demands specialized commissioning expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hazardous Lighting Market |
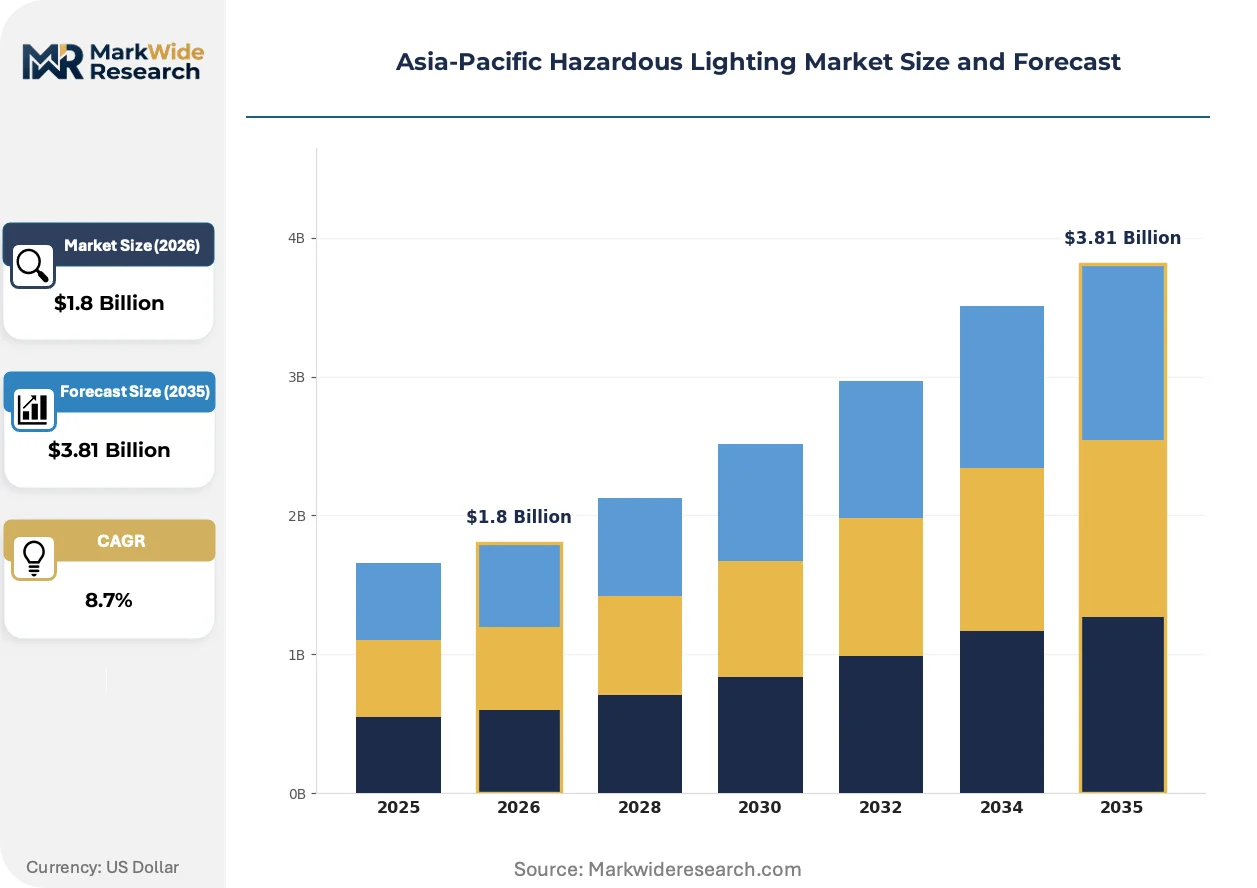
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, HID, Incandescent Application: Mining, Oil & Gas, Chemical Processing, Pharmaceuticals Technology: Smart Lighting, Motion Sensors, Remote Control, Wireless End User: Industrial Facilities, Government Agencies, Marine Operations, Utilities |
| Companies Covered | R. Stahlin Pte Ltd, Shenzhen CESP Co Ltd, Eaton Corporation plc, Glamox Pte. Ltd., Iwasaki Electric Co., Ltd., Dialight plc, ABB Asia Pte. Ltd., Wolf Safety Lamp Co Ltd, Hubbell Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hazardous Lighting Market Strategic Shifts
Thermal management advances and certification convergence are compressing product lifecycles while expanding addressable applications beyond traditional hazardous zones.
Solid-state LED emitters with ceramic substrate architectures are supplanting high-pressure sodium and metal halide sources in high-ambient temperature installations. Australian Pilbara iron ore operators now specify these arrays for haul road lighting where legacy sources failed within months. The shift is compressing replacement cycles from seven years to three while enabling motion-sensor integration previously impossible with HID warm-up constraints.
China's NMPA and SAMR are tightening GB 3836 series enforcement for flameproof and increased-safety constructions, mandating incremental testing protocols that exceed baseline IECEx requirements. Domestic petrochemical operators in Zhejiang and Shandong provinces face compressed compliance timelines. Manufacturers are responding with dual-certification product platforms configured for both Chinese national and international acceptance.
Specification authority is migrating from maintenance departments to central procurement functions with total-cost-of-ownership mandates. Channel intermediaries in Indonesia and Thailand are losing influence as direct manufacturer relationships with EPC contractors consolidate specification control. This concentration is most pronounced in Singapore's Jurong Island chemical cluster where integrated project delivery models dominate capital expenditure.
Asia-Pacific Hazardous Lighting Market Segmentation
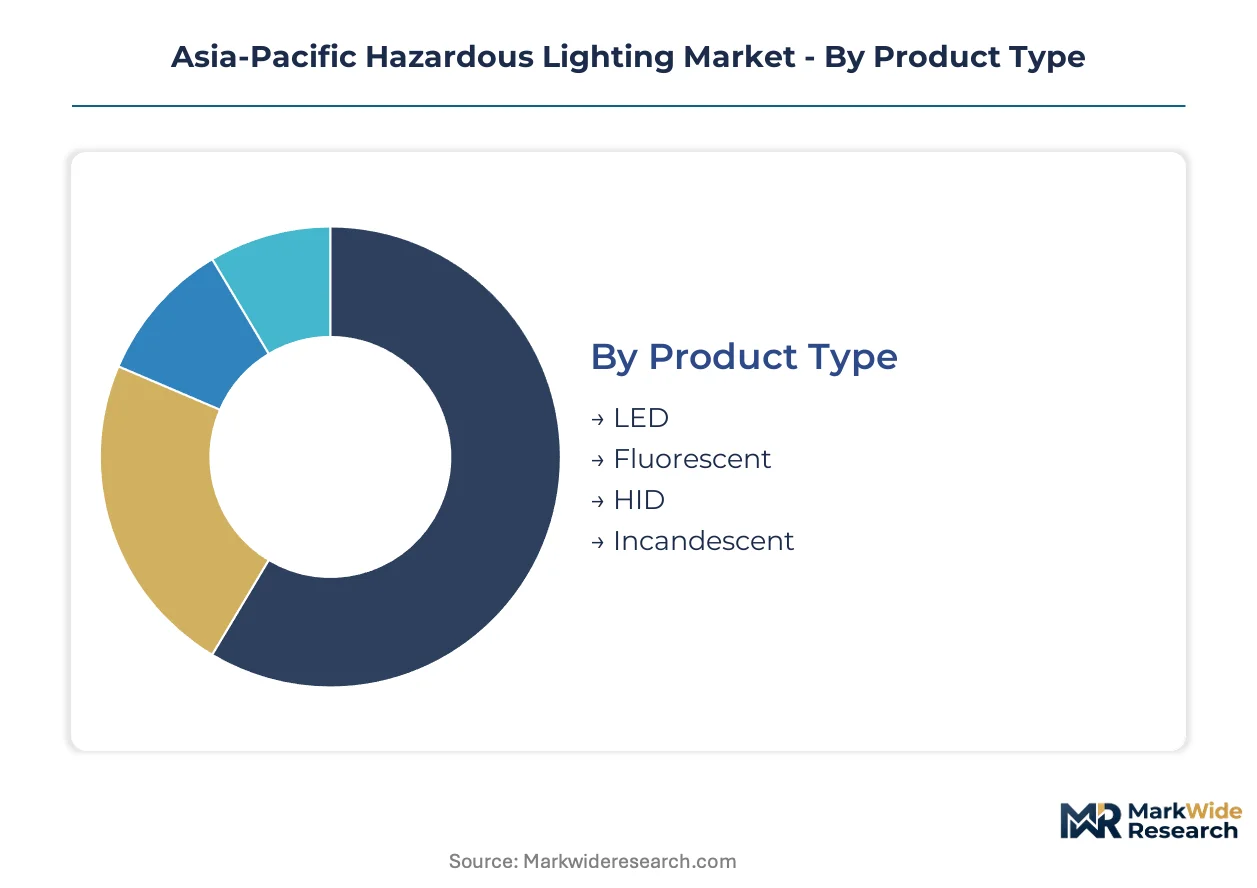
Segmentation in hazardous lighting reveals how certification requirements and procurement channels fragment demand across Asia-Pacific. Product specifications diverge sharply between Australian mining procurement offices and Chinese state-owned petrochemical tenders.
Product Type:
LED arrays dominate direct manufacturer channels serving Australian and Japanese operators, while fluorescent and HID lines persist through electrical distributors in Southeast Asian retrofit markets.
- LED:Solid-state emitters with ceramic substrates achieve T6 temperature codes and IP66/67 ratings through cast aluminum housings. Australian Pilbara iron ore operators specify these for haul road illumination where legacy sources failed within months, compressing replacement cycles from seven years to three.
- Fluorescent:Linear fixtures with explosion-proof enclosures remain specified in intermittently occupied Taiwanese chemical processing units where capital budgets constrain immediate LED conversion. SAMR enforcement of GB 3836 flameproof testing is accelerating phase-out timelines in Chinese state-owned facilities.
- HID:High-pressure sodium and metal halide sources retain installed base in Japanese LNG terminals requiring high-lumen output in cryogenic zones. Iwasaki Electric sustains technical leadership in this transitional category.
- Incandescent:Tungsten-filament emergency lighting persists in legacy marine installations across Indonesian archipelago operations where salt-corrosion resistance demands frequent fixture replacement regardless of source technology.
By volume, LED leads. By growth pace, smart-enabled LED arrays with integrated sensors are expanding most quickly.
Application:
Cost tier stratification separates premium-certified fixtures for Australian mining from standard-grade products serving Southeast Asian government infrastructure.
- Mining:Dust-ignition protection ratings command premium positioning in Queensland coal basins and Western Australia's Pilbara corridor. Cast aluminum housing specifications from Tier 1 manufacturers absorb primary metal price volatility through long-term procurement contracts.
- Oil & Gas:Offshore platform electrification across Southeast Asian oilfields demands IECEx Zone 1 certification for drilling rig illumination. R. Stahlin leverages its Singapore engineering base to dominate retrofit schedules.
- Chemical Processing:Smart-enabled systems with motion sensors reduce energy consumption in South Korean and Taiwanese facilities with intermittent occupancy patterns. Central procurement functions with total-cost-of-ownership mandates now control specification authority.
- Pharmaceuticals:Cleanroom-compatible hazardous lighting with sealed ingress protection serves sterile manufacturing environments in India's pharmaceutical clusters near Hyderabad and Ahmedabad. BIS certification requirements reshape supplier qualification protocols.
By margin contribution, oil and gas leads. By specification velocity, chemical processing is accelerating fastest.
Technology:
Customer type fragmentation separates integrated EPC contractors specifying full smart systems from maintenance departments purchasing standalone replacements.
- Smart Lighting:Digital twin integration with embedded condition monitoring enables predictive maintenance contracts in South Korean smart factories. Shenzhen CESP anchors high-volume production through backward integration into driver electronics.
- Motion Sensors:Occupancy-activated dimming systems integrate into hazardous-rated housings for energy reduction in intermittently occupied units. Retrofit complexity into existing DCS architectures demands specialized commissioning expertise.
- Remote Control:Centralized monitoring platforms serve Singapore's Jurong Island chemical cluster where integrated project delivery models dominate capital expenditure. Direct manufacturer relationships with EPC contractors consolidate specification control.
- Wireless:Mesh network architectures reduce cabling costs in greenfield Vietnamese refinery complexes at Vung Tau and Binh Duong. Complete hazardous lighting infrastructure requirements attract system-level bids.
By installed base, remote control leads. By deployment momentum, wireless is gaining share fastest.
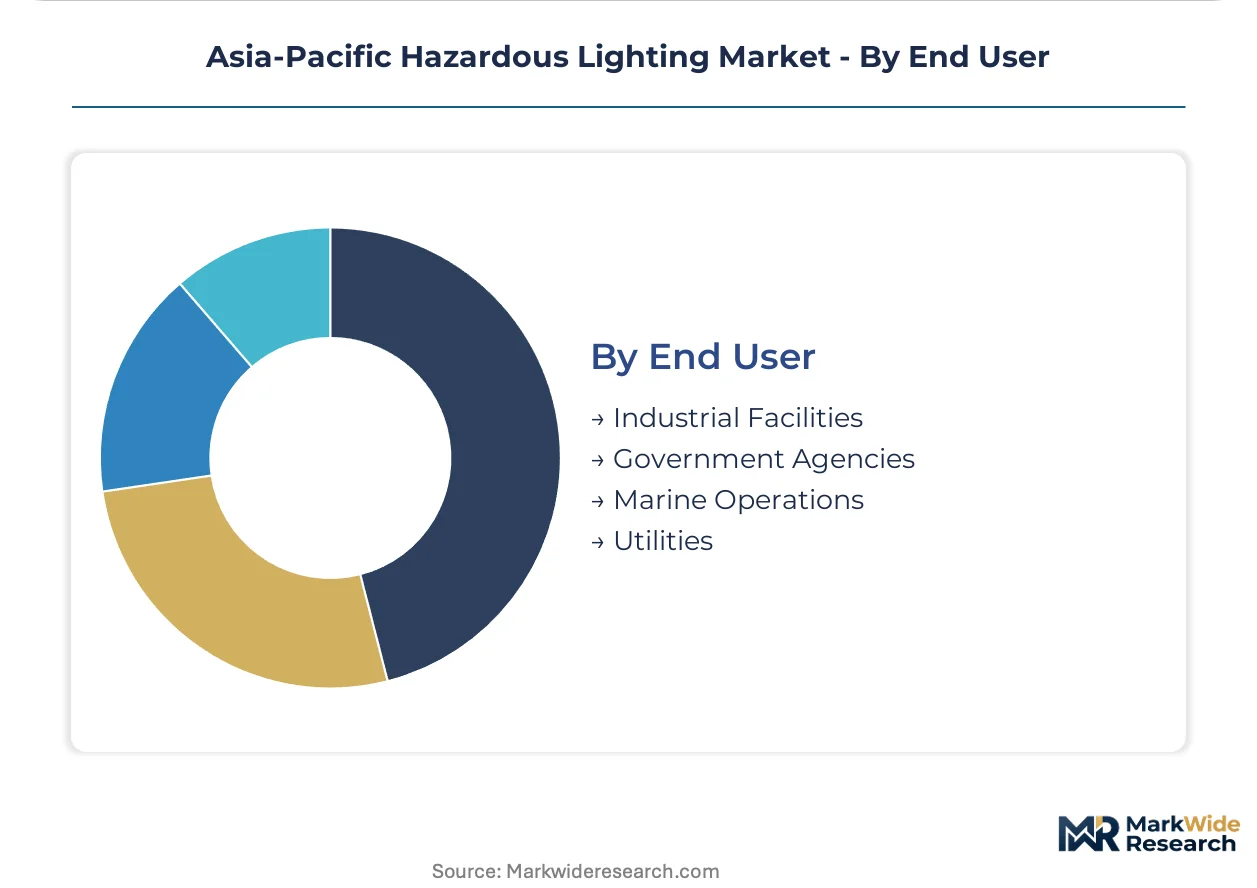
End User:
Supply concentration shapes channel access, with industrial facilities procuring direct from manufacturers while government agencies route through authorized distributors.
- Industrial Facilities:Petrochemical complexes in Zhejiang and Shandong provinces face compressed compliance timelines under NMPA and SAMR enforcement. Dual-certification product platforms address both Chinese national and international acceptance requirements.
- Government Agencies:Public infrastructure procurement across Indonesia and Thailand channels through electrical distributors losing influence to direct manufacturer relationships. Specification authority migration accelerates channel consolidation.
- Marine Operations:Salt-corrosion resistance and shock compliance justify substantial price premiums over standard industrial grades in Japanese LNG terminal retrofits for ammonia co-firing. T6-rated fixtures serve cryogenic zone requirements.
- Utilities:Power generation and distribution infrastructure in Australia's regulated markets requires IECEx certification administered by the central regulatory body. Extended processing timelines stretch product qualification cycles beyond eighteen months.
By revenue scale, industrial facilities lead. By margin expansion, marine operations is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape competitive positioning across Asia-Pacific hazardous lighting, with Chinese manufacturers supplying LED arrays throughout Southeast Asian petrochemical buildouts while Australian mining procurement absorbs premium-certified fixtures from regional engineering bases.
China
Zhejiang and Shandong petrochemical complexes drive fixture replacement demand as NMPA and SAMR tighten GB 3836 flameproof testing protocols. The Yangtze River Delta concentration of state-owned refineries faces compressed compliance timelines under dual-certification requirements. Shenzhen anchors high-volume LED production through backward integration into driver electronics.
Australia
Western Australia's Pilbara iron ore corridor and Queensland coal basins absorb dust-ignition protection fixtures at premium price points. TGA-administered IECEx certification stretches product qualification cycles beyond eighteen months. Perth-based procurement offices specify cast aluminum housings through long-term contracts absorbing metal price volatility.
Japan
LNG terminal retrofits for ammonia co-firing create demand for T6-rated fixtures in cryogenic zones. METI industrial safety directives shape specification standards for high-pressure sodium replacements. Osaka-Kobe industrial corridor facilities integrate smart-enabled systems with motion sensors for energy reduction.
South Korea
Ulsan petrochemical complex operators specify smart-enabled LED arrays with embedded condition monitoring for predictive maintenance contracts. MFDS pharmaceutical manufacturing regulations extend hazardous lighting requirements to sterile production environments. Daegu-Gyeongbuk industrial belt chemical processors adopt digital twin integration for intermittently occupied units.
Vietnam
Greenfield refinery complexes in Vung Tau and Binh Duong provinces require complete hazardous lighting infrastructure for IECEx Zone 1 compliance. Government infrastructure procurement channels through electrical distributors facing consolidation pressure. Ho Chi Minh City-based EPC contractors consolidate specification authority through integrated project delivery models.
Asia-Pacific Hazardous Lighting Market Competitive Environment
Listed leaders compete with private specialists across certification depth and channel access, creating a tiered structure where scale advantages clash with technical specialization. The vendor base fragments across three strategic archetypes: diversified electrical conglomerates with hazardous lighting divisions, pure-play explosion-proof specialists with regional engineering bases, and integrated LED manufacturers with backward control over driver electronics. Dominant competitive moves include geographic expansion through Singapore-based engineering hubs and portfolio diversification into smart-enabled sensor integration.
Among Singapore-based engineering specialists, R. Stahlin Pte Ltd exemplifies the regional retrofit-focused archetype serving offshore platform electrification. Chinese LED manufacturers represented by Shenzhen CESP Co Ltd occupy positions anchored in high-volume production for domestic petrochemical compliance cycles. Japanese electrical conglomerates including Iwasaki Electric Co., Ltd. represent the transitional technology tier sustaining relevance in high-pressure sodium replacement segments.
| Leading Market Players |
|---|
| R. Stahlin Pte Ltd |
| Shenzhen CESP Co Ltd |
| Eaton Corporation plc |
| Glamox Pte. Ltd. |
| Iwasaki Electric Co., Ltd. |
| Dialight plc |
| ABB Asia Pte. Ltd. |
| Wolf Safety Lamp Co Ltd |
| Hubbell Incorporated |
| Others |
Value Chain & Pricing Dynamics
GB 3836 flameproof certification administered by SAMR gates supplier qualification while simultaneously enabling three-tier pricing stratification across premium IECEx-grade, standard GB-compliant, and economy non-certified tiers in Chinese petrochemical procurement.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where certification grade and volume scale drive price differentiation. Premium IECEx/ATEX dual-certified fixtures command substantial positioning over domestic GB-only alternatives. Cost compression in standard-grade tiers is intensifying because Shenzhen-based LED driver oversupply erodes assembly margins. State-owned refinery procurement teams exhibit lowest price sensitivity while Southeast Asian electrical distributors serving government infrastructure face acute margin pressure.
Supply Chain Analysis
China and Japan anchor cast aluminum housing fabrication and ceramic substrate LED emitter production respectively. Supply chains draw from Australian bauxite ore, Malaysian aluminum smelting, and Taiwanese semiconductor packaging for driver electronics. Single-source vulnerability concentrates in Shenzhen-based semiconductor packaging for explosion-proof driver modules. Distribution runs through Singapore-based engineering hubs serving offshore platform retrofits and direct manufacturer relationships with Australian mining procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified explosion-proof engineering talent scarcity constrains product development velocity across Asia-Pacific, creating defensive moats for incumbent specialists with established thermal modeling and pressure-purged enclosure capabilities.
For Market Incumbents: Compound certification depth advantages by securing dual IECEx and GB 3836 approval for core LED platforms before NMPA enforcement timelines compress. Add captive supply of ceramic substrate emitters through backward integration into Taiwanese packaging partnerships. Channel control consolidation with Singapore-based EPC contractors defends against direct manufacturer bypass threats in Jurong Island chemical cluster procurement. For New Entrants and Emerging Players: Lead with wireless mesh-enabled hazardous lighting systems for greenfield Vietnamese refinery complexes at Vung Tau and Binh Duong where complete infrastructure requirements attract system-level bids. Target marine operations serving Japanese LNG terminal retrofits for ammonia co-firing, a margin-rich segment where salt-corrosion resistance specifications justify premium positioning. Pursue digital twin integration partnerships with South Korean smart factory operators as the primary go-to-market angle. For Investors and Strategic Acquirers: GB 3836 enforcement milestone reshapes the acquisition landscape by compressing compliance timelines and elevating certified engineering teams above commodity assembly capacity. Five-to-ten year viability favors pure-play explosion-proof specialists with regional engineering bases over diversified electrical conglomerates with hazardous lighting divisions. Monitor IECEx certification processing delays at Australia's central regulatory body as the signal indicating qualification bottleneck severity and margin expansion potential for approved suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | GB 3836 and IECEx alignment accelerates market access across Chinese state-owned and Australian mining procurement simultaneously. |
| Backward Integration into Driver Electronics | Shenzhen-based semiconductor packaging control mitigates logistics disruption exposure for LED array manufacturers. |
| Singapore Engineering Hub Expansion | Jurong Island chemical cluster proximity consolidates specification authority with EPC contractors in integrated project delivery models. |
| Smart Sensor Convergence Development | Motion-activated dimming integration captures energy reduction mandates in South Korean and Taiwanese chemical processing facilities. |
| Marine Operations Specialization | T6-rated fixture development for Japanese LNG ammonia co-firing retrofits accesses cryogenic zone premium pricing pools. |
Study Parameters
Operator-level perspectives from maintenance directors at Australian Pilbara mining operations, procurement leads at Zhejiang petrochemical complexes, Singapore-based EPC contractor specification engineers, and Japanese LNG terminal facility managers anchored the qualitative base. Primary interview insights triangulated against SAMR regulatory filings, IECEx certification registry data, Australian Bureau of Statistics mining capital expenditure records, and customs import manifests for explosion-proof electrical equipment. Bottom-up fixture demand modeling and top-down petrochemical sector lighting intensity benchmarks cross-validated volume estimates.
Sensitivity analysis tested forecast robustness across aluminum price volatility scenarios, certification timeline compression assumptions, and LED adoption curve variations. Segmentation dimensions spanned product type, application vertical, certification tier, and end-user procurement channel throughout the projection horizon. CAGRs derived from historical replacement cycle compression patterns and petrochemical capacity expansion pipelines. Industry-specific inputs incorporated GB 3836 enforcement phase-in schedules and Australian mining procurement contract renewal calendars.
Forecasts assume regulatory continuity in SAMR flameproof testing protocols and TGA-administered IECEx certification; material policy shifts would require re-modeling. Supply chain disruption scenarios and extended qualification timeline risks inform confidence interval construction. Recalibration cycles align with material shifts in NMPA enforcement intensity and Southeast Asian offshore platform electrification schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
North America Outdoor Lighting Market
Lighting
Solar Lights Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Human Centric Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
Germany Indoor LED Lighting Market
Lighting
Display Light Control Film Market
Lighting
Xenon Headlights Market
Lighting
Smart Lights Market
Lighting
Global Machine Vision Lighting Market
Lighting
North America Street Lighting Market
Lighting
Industrial Lighting Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Ambient Lighting Market
Lighting
Ring Lights Market