
 Global Lighting Control System Market | 2026-2036
Global Lighting Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lighting Control System Market Outlook
Lighting-as-a-service and performance contracting models are reconfiguring capital deployment across the installed base. Signify Holding leverages captive financing arms to bundle hardware with ongoing optimization services. Acuity Brands Lighting, Inc. anchors its position through deep backward integration into LED driver manufacturing. Lutron Electronics Co., Inc. differentiates via proprietary RF spectrum management that sustains premium positioning in high-end commercial fit-outs.
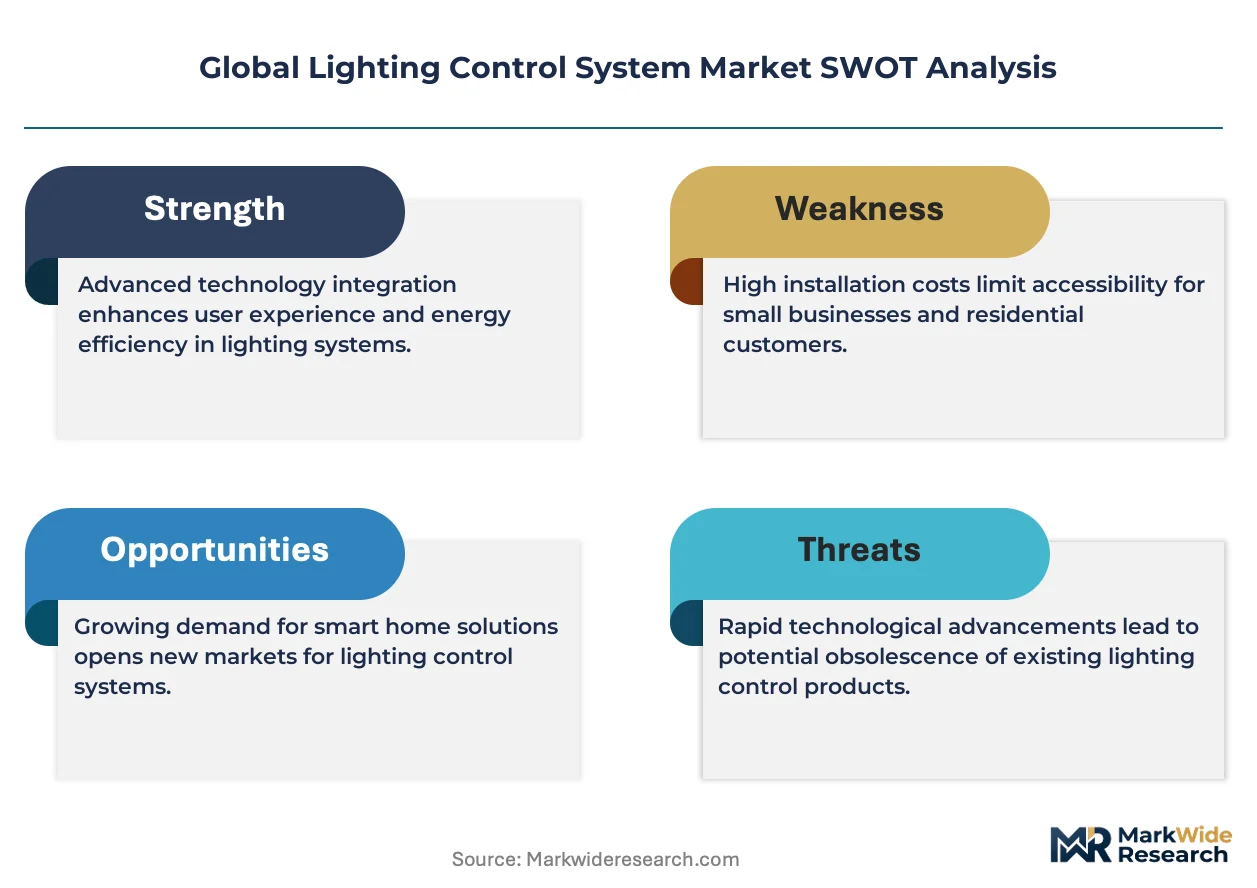
A lighting control system integrates sensors, controllers, and network interfaces to modulate artificial illumination based on occupancy patterns, ambient daylight availability, and scheduled programming across 0-10V, DALI, or wireless mesh protocols. These systems primarily reduce commercial building energy consumption while extending luminaire operational life through demand-responsive dimming. Wired DALI installations still dominate retrofit-heavy European office spaces where building codes mandate circuit-level monitoring. Wireless Zigbee and Bluetooth LE segments are expanding fastest in North American retail stores seeking rapid reconfiguration without conduit runs. Smart technology layers that combine daylight harvesting with HVAC interoperability command the widest margin pools in hospitality new-build specifications.
The EU Green Deal and F-Gas Regulation are tightening embodied carbon thresholds for building systems sold across member states, while the US DOE appliance standards program pushes minimum efficacy requirements upward. India's BIS certification and China's GB standards create divergent compliance pathways that fragment product platform strategies. Stakeholders must monitor which regulatory jurisdiction sets the binding technical floor for their target export markets.
Market Dynamics
Wireless mesh protocols are compressing installation timelines and rewiring competitive advantage away from incumbent wiring specialists toward RF engineering capabilities.
Growth Catalysts
- EU Green Deal building performance standards:Tightening embodied carbon thresholds in Germany and France are accelerating commercial retrofit specifications for circuit-level monitoring and demand-responsive controls.
- Smart city streetlight deployments:Municipal infrastructure programs in India, Brazil, and Saudi Arabia are converting legacy sodium vapor networks to networked LED systems with remote dimming and fault detection.
- Bluetooth LE and Zigbee mesh stacks:North American retail chains are specifying wireless-native controls to enable rapid floor-plan reconfiguration without conduit demolition or electrical permitting delays.
Market Restraints
- Silicon carbide MOSFET supply concentration:LED driver manufacturing depends on power semiconductor substrates sourced from a concentrated East Asian foundry base, creating input cost volatility and allocation risk.
- Fragmented national certification regimes:Divergent BIS, GB, and FCC electromagnetic compliance pathways force product platform fragmentation and inventory duplication for multi-territory suppliers.
- Legacy 0-10V analog infrastructure:European office retrofits face sunk-cost drag from existing wiring that lacks digital addressability, slowing DALI migration despite regulatory pressure.
Strategic Opportunities
- HVAC-lighting interoperability:Converged building management protocols that merge daylight harvesting with climate control are commanding specification preference in hospitality new-builds across the United Arab Emirates and Singapore.
- Lighting-as-a-service financing:Performance contracting models that bundle hardware, installation, and ongoing optimization are unlocking capital-constrained municipal and educational sector demand in Brazil and Mexico.
- India smart city mission:Central government urban infrastructure funding is concentrating deployment of networked streetlight controls in Mumbai, Delhi, and Bangalore metropolitan clusters.
Industry Challenges
- RF spectrum management expertise scarcity:Wireless control deployment requires specialized radio frequency engineering talent that remains concentrated in semiconductor and telecommunications sectors, creating hiring bottlenecks for lighting specialists.
- Multi-protocol integration complexity:Specification teams must reconcile DALI-2, Zigbee 3.0, Bluetooth Mesh, and proprietary RF stacks within single building footprints, escalating commissioning timelines and warranty exposure.
- CSRD-aligned carbon accounting:Upcoming European sustainability reporting mandates are forcing controls manufacturers to document supply-chain embodied carbon at component level, requiring supplier audit infrastructure that many mid-tier players lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lighting Control System Market |
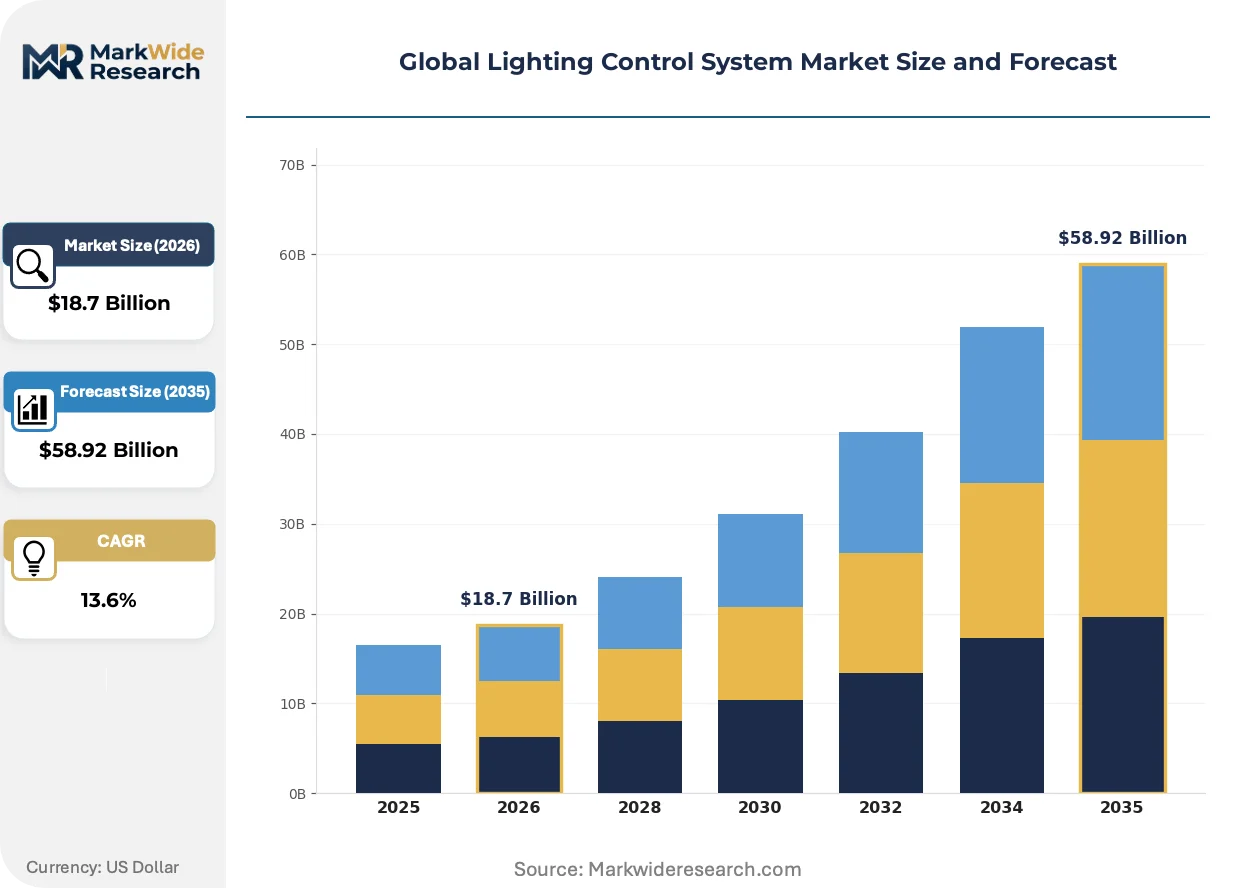
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
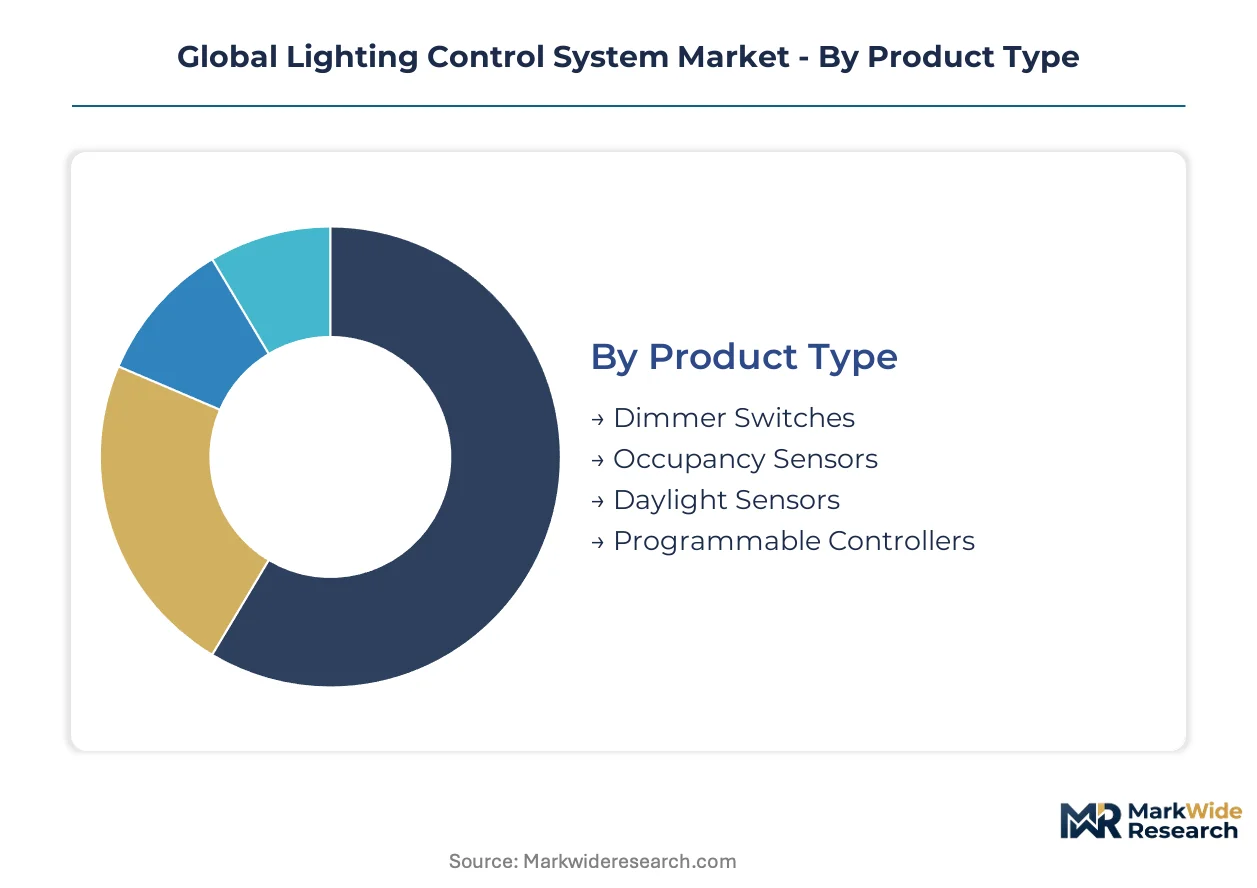
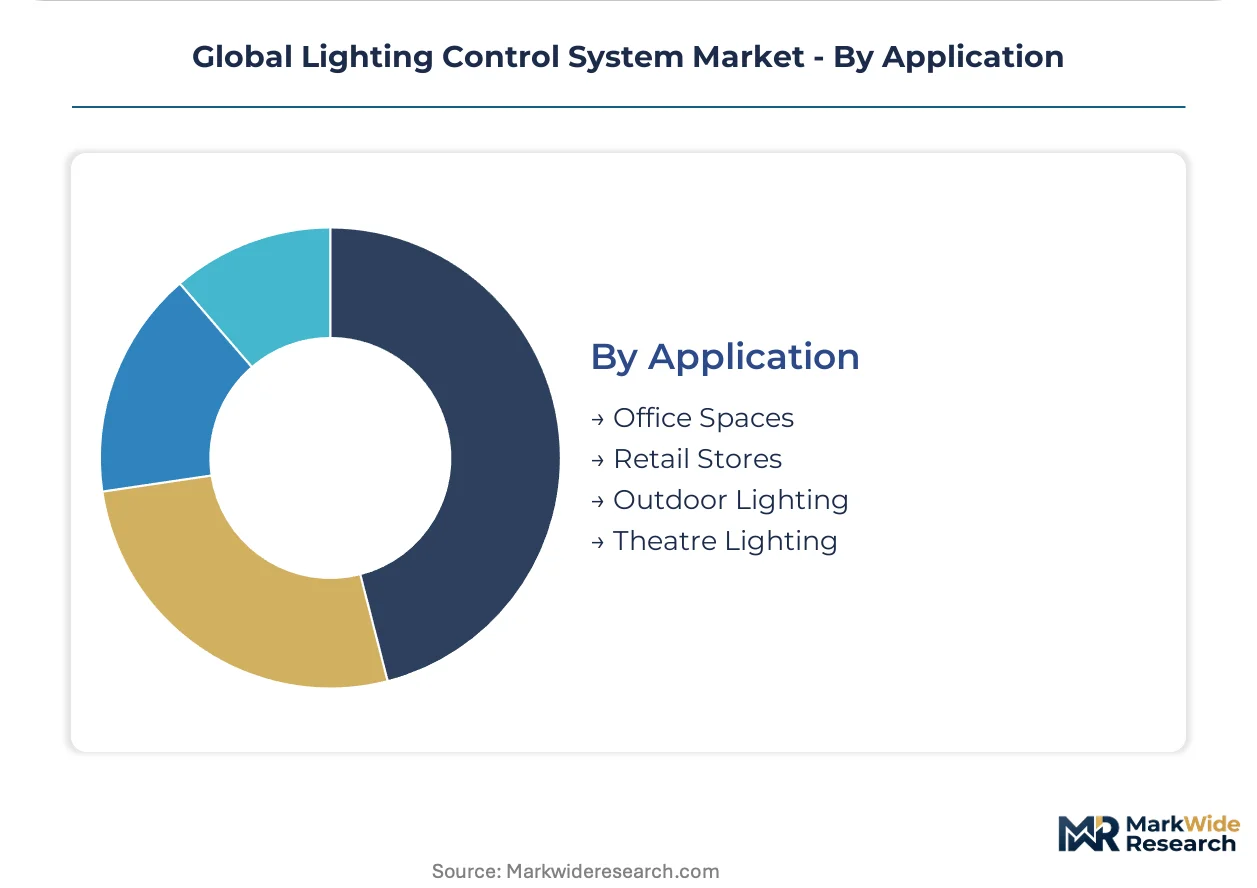
| Segmentation | Product Type: Dimmer Switches, Occupancy Sensors, Daylight Sensors, Programmable Controllers End User: Residential, Commercial, Industrial, Hospitality Technology: Wired, Wireless, Hybrid, Smart Application: Office Spaces, Retail Stores, Outdoor Lighting, Theatre Lighting |
| Companies Covered | Signify Holding, Acuity Brands Lighting, Inc., Lutron Electronics Co., Inc., Schneider Electric, Eaton Corporation, Honeywell International Inc., Legrand S.A., General Electric Company, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lighting Control System Market Strategic Shifts
Digital twin integration and AI-driven predictive maintenance are layering software value atop hardware commoditization, compressing traditional equipment margin pools while expanding recurring revenue attachment.
Power-over-Ethernet lighting control is hybridizing building infrastructure by converging data and electrical distribution onto single cable plant. Corporate campus developers in the United States are specifying PoE-native luminaires to collapse separate low-voltage and line-voltage contractor scopes. This convergence is enabling granular per-fixture energy metering and occupancy analytics that wired analog architectures cannot support.
The EU F-Gas Regulation and accompanying Ecodesign requirements are phasing down fluorinated greenhouse gases in building systems while mandating minimum efficacy thresholds for connected lighting. Manufacturers serving European member states must redesign thermal management and driver architectures to maintain compliance. German and French specification consultants are now embedding these thresholds as disqualifying criteria in public tender documentation.
Facility managers are unbundling after-sales service contracts from initial equipment procurement, creating standalone recurring revenue pools for controls optimization and firmware lifecycle management. North American university and healthcare campus buyers are separating hardware capital budgets from ongoing system tuning and energy performance guarantees. This shift is most visible in California and New York State where utility incentive programs reward verified savings over equipment installation.
Global Lighting Control System Market Segmentation
Lighting control system architectures vary sharply across installation contexts, from legacy analog retrofits requiring backward compatibility to greenfield smart buildings demanding protocol convergence. Segmentation reveals how technology choices cascade through hardware specifications, commissioning complexity, and lifecycle service models.
Product Type:
Use-case spectrum spans manual override devices through fully autonomous environmental response systems, with cost-per-node and commissioning burden as the primary trade-off dimensions.
- Dimmer Switches:Analog and digital phase-cut or 0-10V modules providing manual or scheduled intensity reduction. European office retrofits in Germany and France specify these for circuit-level compliance with EU Green Deal monitoring mandates while avoiding full DALI infrastructure replacement.
- Occupancy Sensors:Passive infrared, ultrasonic, or dual-technology detectors triggering automatic on/off or dimming responses. North American retail chains in the United States deploy these most aggressively to qualify for utility demand-response incentives and reduce unoccupied-hour energy waste.
- Daylight Sensors:Photodiode or photovoltaic arrays measuring ambient illuminance for closed-loop dimming control.
- Programmable Controllers:Microprocessor-based units executing scheduled scenes, astronomical clock functions, and network integration.
Established volume favors dimmer switches; emerging adoption favors occupancy sensors.
End User:
Cost tier stratification separates capital-rich new construction from retrofit-constrained installed base upgrade cycles.
- Commercial:Office, healthcare, and educational facilities specifying circuit-level monitoring and demand-responsive controls. Smart city streetlight deployments across India, Brazil, and Saudi Arabia concentrate municipal procurement within this segment, driven by remote fault detection and energy accountability requirements.
- Hospitality:Hotels, resorts, and entertainment venues prioritizing scene-setting aesthetics alongside energy compliance. HVAC-lighting interoperability commands premium specification in United Arab Emirates and Singapore new-builds, where converged building management protocols reduce operational staffing overhead.
- Residential:Single-family and multi-unit dwellings adopting wireless-native consumer-grade systems.
- Industrial:Manufacturing, warehousing, and logistics facilities requiring high-bay controls with extended temperature tolerance and EMI resistance.
Commercial applications dominate current procurement volume; hospitality commands the widest margin pools.
Technology:
Supply concentration in RF engineering talent and semiconductor substrates is compressing installation timelines while elevating commissioning risk.
- Wireless:Zigbee 3.0, Bluetooth Mesh, and proprietary RF stacks eliminating conduit requirements. North American retail stores specify these for rapid floor-plan reconfiguration without electrical permitting delays, though RF spectrum management expertise scarcity creates hiring bottlenecks for lighting specialists.
- Smart:AI-driven predictive maintenance, digital twin integration, and cloud-based optimization layers. These systems are expanding recurring revenue attachment as facility managers unbundle service contracts from initial hardware procurement in California and New York State.
- Wired:DALI-2, 0-10V, and power-line carrier architectures with deterministic reliability.
- Hybrid:Dual-path installations combining wired backbone with wireless edge extension for phased upgrade scenarios.
Wired infrastructure retains retrofit dominance; smart technology layers are climbing the fastest trajectory.
Application:
Geography-specific regulatory pressure and infrastructure age dictate protocol selection and procurement channel.
- Outdoor Lighting:Street, highway, and area luminaire networks with remote monitoring and adaptive dimming. India's smart city mission concentrates deployment in Mumbai, Delhi, and Bangalore metropolitan clusters, where central government urban infrastructure funding accelerates networked LED conversion.
- Office Spaces:Open-plan and private workspace illumination with daylight harvesting and occupancy response. German and French specification consultants embed EU F-Gas Regulation and Ecodesign efficacy thresholds as disqualifying criteria in public tender documentation.
- Retail Stores:Merchandise-focused lighting with rapid reconfiguration requirements and sales-floor analytics integration.
- Theatre Lighting:Performance venues requiring DMX512 or proprietary entertainment protocols with precise cue execution and color temperature control.
Outdoor lighting concentrates municipal procurement scale; office spaces drive regulatory compliance innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German specification channels where EU Green Deal mandates drive circuit-level monitoring requirements, while Chinese manufacturing clusters compete on volume economics for wireless-native hardware exports.
United States
North American retail chains specify Zigbee and Bluetooth Mesh stacks to enable rapid floor-plan reconfiguration without electrical permitting delays. The FCC governs RF spectrum allocation for unlicensed wireless controls. California and New York State utility incentive programs reward verified energy savings, concentrating smart technology deployment in university and healthcare campus procurement.
Germany
Commercial building retrofits in Frankfurt and Munich accelerate DALI-2 adoption as the EU Green Deal tightens embodied carbon thresholds. The KBA collaborates with federal building codes on energy performance standards. Specification consultants in Baden-Württemberg embed F-Gas Regulation efficacy thresholds as disqualifying criteria in public tender documentation.
China
Wireless mesh protocols displace legacy wired infrastructure in new construction across Shenzhen and Shanghai metropolitan clusters. GB standards create divergent compliance pathways that fragment product platform strategies for export markets. The MIIT oversees industrial policy for smart city infrastructure deployment.
India
Central government urban infrastructure funding concentrates networked streetlight controls in Mumbai, Delhi, and Bangalore. BIS certification requirements force component-level redesign for domestic market entry. The smart city mission drives municipal procurement scale for remote dimming and fault detection capabilities.
Brazil
Performance contracting models unlock capital-constrained municipal demand in São Paulo and Rio de Janeiro metropolitan areas. ANVISA regulates electromagnetic compliance for imported control systems. Lighting-as-a-service financing expands procurement access for educational sector buyers seeking bundled hardware and optimization services.
Global Lighting Control System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in LED driver and sensor manufacturing. The vendor base stratifies across three tiers: diversified electrical conglomerates with captive financing arms, lighting-native specialists with deep backward integration, and RF engineering boutiques with proprietary spectrum management. Consolidation pressure runs highest where wireless protocol stacks require semiconductor and telecommunications talent pools outside traditional lighting recruitment channels. Dominant competitive moves include strategic partnerships with HVAC controls vendors and geographic expansion through lighting-as-a-service financing subsidiaries.
Among diversified electrical conglomerates, Schneider Electric, Siemens AG, and Legrand S.A. occupy positions spanning building automation integration. Signify Holding and Acuity Brands Lighting, Inc. exemplify lighting-native specialists with captive supply chain control. Lutron Electronics Co., Inc. sits within the premium-tier RF engineering segment. These anchors illustrate how competitive positioning diverges between scale-driven platform breadth and specialization-driven margin capture.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands Lighting, Inc. |
| Lutron Electronics Co., Inc. |
| Schneider Electric |
| Eaton Corporation |
| Honeywell International Inc. |
| Legrand S.A. |
| General Electric Company |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in silicon carbide MOSFET foundry capacity across East Asian manufacturing clusters is compressing LED driver input costs and forcing tiered supplier pricing that separates volume-committed buyers from spot-market purchasers. German specification channels maintain premium positioning through EU Green Deal compliance bundling, while Chinese wireless-native exporters compete on standard hardware economics.
Pricing Analysis
Configured-to-order pricing for DALI-2 systems with circuit-level monitoring commands a 35-50% premium over standard Zigbee mesh hardware in North American retail deployments. Three-tier pricing structure across premium, standard, and economy levels separates hospitality new-build specifications from municipal streetlight procurement and residential retrofit segments. Cost compression in standard wireless nodes is intensifying because semiconductor substrate allocation favors automotive and consumer electronics buyers. Municipal buyers in Brazil and India exhibit highest price sensitivity; UAE hospitality developers show lowest sensitivity when HVAC interoperability is bundled.
Supply Chain Analysis
Export-control restrictions on wide-bandgap semiconductor manufacturing equipment limit capacity expansion outside East Asian foundry zones, constraining LED driver supply diversification. Manufacturing gravity centers on China for wireless control assembly, Germany for DALI-2 system integration, and Taiwan for power semiconductor substrates. Silicon carbide wafers, RF transceiver modules, and photodiode sensors constitute critical input dependencies. Single-source vulnerability in 6-inch SiC substrate supply creates allocation risk during automotive demand surges. Distribution runs through electrical wholesale channels in Europe, direct OEM relationships in North America, and government tender aggregators in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protocol fragmentation across DALI-2, Zigbee 3.0, Bluetooth Mesh, and proprietary RF stacks is fragmenting competitive space, creating specialist niches for RF engineering boutiques and HVAC convergence integrators.
For Market Incumbents: Harden supply chain positioning through captive silicon carbide sourcing agreements or long-term foundry offtake contracts to offset semiconductor allocation risk. Deepen backward integration into LED driver manufacturing to defend margin pools against commoditizing wireless hardware, while embedding CSRD-aligned carbon accounting infrastructure ahead of supplier audit mandates. For New Entrants and Emerging Players: Establish a beachhead in Brazil's lighting-as-a-service municipal segment where performance contracting models unlock capital-constrained demand without upfront hardware procurement. Target India's smart city streetlight deployments through BIS certification partnerships with domestic electrical contractors. Lead with HVAC-lighting interoperability solutions in UAE and Singapore hospitality specifications where converged building management protocols command premium positioning. For Investors and Strategic Acquirers: Capital is best deployed toward RF engineering boutiques with proprietary spectrum management capabilities and established hospitality specification relationships, as wireless protocol dominance remains unresolved across the analysis window. Watch for inflection when Bluetooth Mesh or Zigbee 3.0 achieves de facto standardization in North American retail chains, triggering consolidation of protocol-agnostic platform players.| Strategic Initiative | Industry Significance |
|---|---|
| HVAC Controls Partnership | Converged building management protocols merge daylight harvesting with climate control in UAE hospitality specifications. |
| Lighting-as-a-Service Subsidiary | Performance contracting unlocks capital-constrained municipal demand in Brazil and Mexico educational sectors. |
| Silicon Carbide Supply Agreement | Long-term foundry offtake secures LED driver substrate allocation against automotive demand competition. |
| BIS Certification Investment | Component-level redesign enables domestic market entry for India's smart city mission procurement. |
| RF Engineering Acquisition | Proprietary spectrum management capabilities address hiring bottlenecks in wireless control deployment. |
Study Parameters
Desk research of regulatory filings from the EU F-Gas Regulation documentation, BIS certification requirements, and FCC RF spectrum allocations preceded structured interviews with lighting controls product managers, electrical specification consultants, municipal procurement officers, and semiconductor supply chain directors. Primary fieldwork combined with secondary validation from SEC 10-K disclosures, customs trade data, and smart city mission tender documents. Bottom-up node counting across installation types triangulated against top-down market sizing from building stock databases and retrofit penetration assumptions.
Assumptions held fixed include current EU Green Deal implementation timelines, existing FCC unlicensed spectrum allocations, and prevailing East Asian foundry capacity expansion plans; variables included wireless protocol adoption rates, HVAC convergence specification velocity, and municipal financing access in emerging economies. Segmentation modeling spanned product architecture, end-use vertical, connectivity technology, and geographic regulatory cluster. CAGRs derived from installation volume trajectories weighted by average system value and service attachment rates. Forecast inputs incorporated LED luminaire replacement cycles, building code revision schedules, and utility incentive program budgets.
Sensitivities concentrate around silicon carbide substrate allocation shifts, EU CSRD supplier audit enforcement timing, and Bluetooth Mesh standardization velocity in North American retail. Forecasts reflect documented assumptions on protocol migration timelines and foundry capacity expansion. Material shifts in wide-bandgap semiconductor export controls or EU building performance standard acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Xenon Headlights Market
Lighting
Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
North America Street Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Circadian Lighting Market
Lighting
Street and Roadway Lighting Market
Lighting
Lighting Product Market
Lighting
Vintage Bulb Market
Lighting
Human Centric Lighting Market
Lighting
Dimmer and Color Tunable Market
Lighting
Specialty Lighting Market
Lighting
Global Work Lights Market
Lighting
Intelligent Lighting Controls Market
Lighting
Global Flame Proof Lighting Market
Lighting
Global Machine Vision Lighting Market