
 System on Module (Som) Market | 2026-2036
System on Module (Som) Market Size, Share, and Industry Trends Forecast 2026-2036
System on Module (Som) Market Analysis
The EU Ecodesign Directive is broadening efficiency requirements for networked industrial equipment, compelling OEMs to specify lower-power compute modules. Kontron AG leverages its German manufacturing footprint to supply energy-optimized x86 and ARM modules that meet these thresholds. Advantech Co. Ltd. anchors Asia-Pacific demand through extensive embedded module portfolios serving factory automation integrators. Toradex AG differentiates with long-lifecycle product commitments that sustain design-win retention across medical and transportation verticals.
A System on Module integrates core computing components—processor, memory, power management, and I/O interfaces—onto a compact carrier board, typically measuring 55mm by 84mm or smaller, enabling rapid product development without full custom PCB design. The primary purpose is to reduce time-to-market for embedded systems by abstracting hardware complexity. Processor modules based on ARM architecture dominate volume shipments due to their power-performance balance in IoT and consumer applications, while FPGA-based variants command premium positioning in telecommunications infrastructure where deterministic signal processing matters. Industrial automation as an end-user segment generates the deepest margin pools because buyers prioritize supply continuity and technical support over unit cost.
The EU RoHS and REACH frameworks restrict hazardous substances in electronics manufacturing, directly influencing SoM solder compositions and substrate material selections. Japan's METI enforces Top Runner standards that push module vendors toward incremental efficiency gains in standby and active power modes. The FCC in the United States governs electromagnetic emissions for modules incorporating wireless connectivity, shaping pre-certification strategies for IoT-facing product lines. Stakeholders must monitor how divergent efficiency and material regulations across these jurisdictions affect platform consolidation strategies and regional sourcing decisions.
Market Dynamics
Energy efficiency mandates from Brussels and Tokyo are compressing power budgets for industrial compute modules, forcing ARM-based designs into legacy x86 strongholds across factory automation and medical imaging platforms.
Growth Catalysts
- EU Ecodesign thresholds:Networked equipment efficiency rules now cover industrial controllers, compelling OEMs to specify modules below 15W active consumption.
- East Asian manufacturing clusters:Contract electronics builders in Taiwan and South Korea integrate SoM units into collaborative robotics at volumes that sustain dedicated module SKUs.
- Long-lifecycle commitments:Medical device and transportation OEMs demand 10-15 year supply guarantees that lock in design wins and deter second-source substitution.
Market Restraints
- Substrate material constraints:REACH restrictions on halogenated flame retardants limit laminate choices and extend qualification timelines for new module variants.
- Foundry concentration:Leading-edge ARM SoC production concentrates at TSMC facilities in Taiwan, creating geographic supply risk for volume module programs.
- FPGA cost premiums:Deterministic signal processing modules based on programmable logic carry 3-4x unit costs versus ARM equivalents, capping addressable market in price-sensitive segments.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and testing attract module vendors to establish local production for domestic industrial automation demand.
- Edge AI inference:Convergence of neural processing units with traditional SoM form factors opens medical imaging and predictive maintenance applications requiring on-device intelligence.
- Japan Top Runner standards:METI efficiency mandates for standby power create specification pull for modules with sub-500mW sleep states in building automation and instrumentation.
Industry Challenges
- Embedded Linux talent scarcity:Module vendors struggle to hire kernel engineers capable of maintaining decade-long software support commitments across customer programs.
- Wireless pre-certification timelines:FCC emissions testing for IoT-facing modules adds 4-6 months to product launch schedules, compressing competitive windows.
- Legacy fieldbus integration:Industrial customers demand native PROFINET and EtherCAT interfaces that require specialized ASIC partnerships and extended driver development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System on Module (Som) Market |
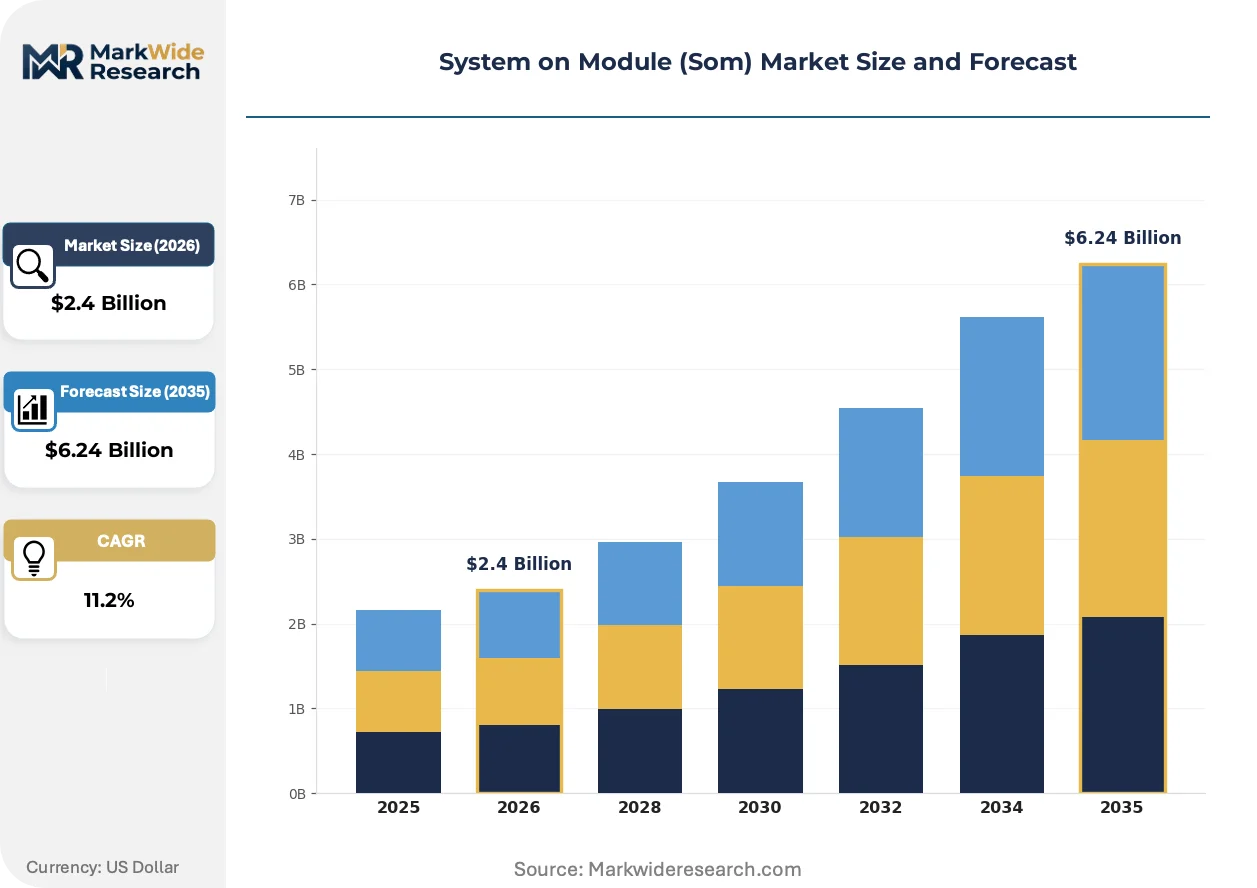
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Module, Processor Module, Interface Module, Memory Module Technology: ARM, FPGA, SoC, x86 End User: Industrial Automation, Medical Devices, Telecommunications, Consumer Electronics Application: IoT Devices, Smart Home, Robotics, Automotive |
| Companies Covered | Advantech Co. Ltd., Kontron AG, Congatec AG, Toradex AG, AAEON Technology Inc., Axiomtek Co. Ltd., Eurotech S.p.A., SECO S.p.A., Variscite Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System on Module (Som) Market Emerging Trajectories
Module form factors are fragmenting as application-specific power-performance requirements diverge, while regulatory pressure on embodied carbon and standby consumption accelerates material and architecture choices.
Heterogeneous compute architectures combining ARM cores with dedicated neural processing units are rewriting the performance-per-watt benchmark for edge inference workloads. Medical imaging OEMs in Germany and Japan now specify these modules for real-time pathology screening and radiological analysis. The technology is compressing the traditional gap between embedded controllers and GPU-accelerated edge servers.
EU F-Gas Regulation phase-down schedules are pressuring thermal management designs in sealed industrial enclosures. Module vendors must now specify passive cooling or low-profile vapor chambers rather than traditional forced-air solutions. Factory automation integrators in Northern Europe are qualifying fanless designs first, creating specification precedence that spreads southward.
Direct procurement relationships between OEM engineering teams and module vendors are displacing traditional distribution channels for volumes above 10,000 units annually. Large industrial automation houses in Germany now negotiate frame contracts covering five-year supply horizons. The pattern is most visible in robotics and semiconductor equipment verticals where design continuity carries premium value.
System on Module (Som) Market Segmentation
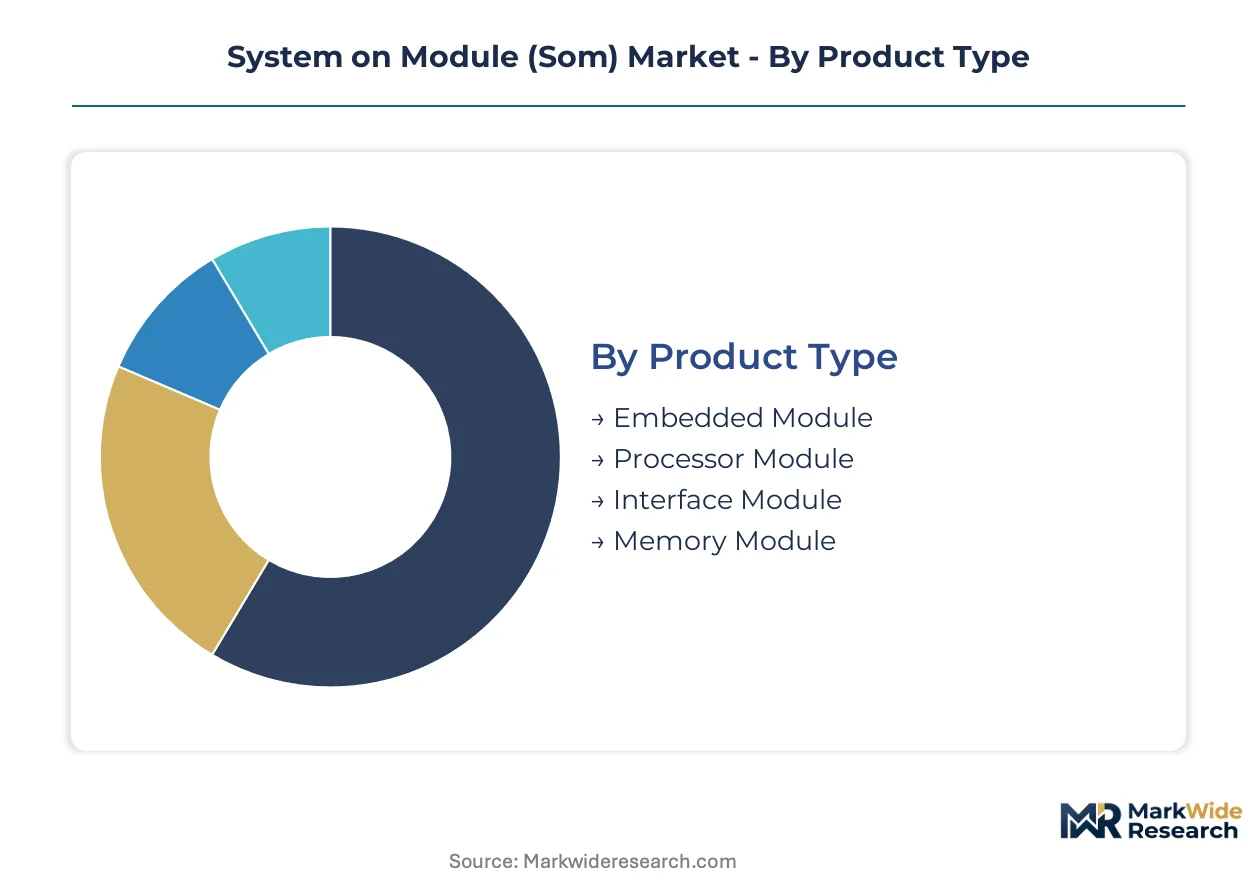
SoM procurement patterns diverge sharply across compute architectures and end-use requirements, with upgrade cycles in industrial automation compressing from seven years to four as efficiency mandates accelerate obsolescence. Module vendors must align product roadmaps with these heterogeneous replacement rhythms to sustain design-win retention.
Product Type:
Replacement urgency varies by module complexity, with processor-intensive categories facing shorter upgrade windows as thermal and power budgets tighten under EU Ecodesign and Japan METI standards.
- Processor Module:Integrates CPU, memory controller, and power management onto a single substrate, typically occupying 55mm by 84mm or smaller footprints. Demand concentrates in German and Japanese industrial automation OEMs replacing legacy x86 controllers with ARM-based alternatives to meet sub-15W active consumption thresholds.
- Embedded Module:Pre-validated compute platform with standardized pinout enabling carrier board reuse across product generations. Medical device manufacturers in Japan specify these for imaging equipment requiring decade-long supply continuity under PMDA lifecycle regulations.
- Interface Module:Specialized I/O expansion boards adding fieldbus connectivity or sensor aggregation.
- Memory Module:Discrete RAM or storage expansion units stacking atop base compute modules.
Processor Module sits at the top of the volume ranking, with Embedded Module climbing the fastest.
Technology:
Architecture selection directly determines power-performance positioning and qualification timelines, with cost tiers separating commodity IoT deployments from premium deterministic systems.
- ARM:RISC-based instruction set dominating volume shipments through power-performance balance in battery-constrained and thermally restricted applications. East Asian contract electronics builders in Taiwan and South Korea integrate ARM SoMs into collaborative robotics and medical imaging platforms at production scales sustaining dedicated SKUs.
- FPGA:Field-programmable gate arrays enabling deterministic signal processing with nanosecond latency guarantees. Telecommunications infrastructure OEMs absorb 3-4x unit cost premiums for these modules in baseband processing and network timing applications where deterministic behavior is non-negotiable.
- SoC:System-on-Chip designs integrating application processors with graphics, video, and neural acceleration.
- x86:CISC architecture retaining foothold in legacy industrial PCs and edge servers requiring binary compatibility.
ARM commands the dominant revenue share, with FPGA gaining share fastest in telecommunications and medical imaging verticals.
End User:
Customer type dictates margin structure and support intensity, with industrial buyers prioritizing supply guarantees over unit economics while consumer-facing segments emphasize cost minimization.
- Industrial Automation:Factory controllers, robotics, and process instrumentation requiring 10-15 year supply commitments. German OEMs negotiate frame contracts covering five-year supply horizons, locking in design wins and deterring second-source substitution through technical support depth.
- Medical Devices:Diagnostic imaging, patient monitoring, and surgical equipment regulated by FDA, EMA, and PMDA lifecycle requirements. Long qualification timelines and firmware stability mandates favor module vendors with proven kernel maintenance capabilities across decade-long support windows.
- Telecommunications:Baseband processing, network timing, and edge compute in carrier infrastructure.
- Consumer Electronics:Smart appliances, wearables, and portable devices with compressed development cycles and aggressive cost targets.
Industrial Automation generates the deepest margin pools, with Medical Devices expanding most quickly as edge AI inference penetrates diagnostic imaging.
Application:
Use-case thermal and connectivity requirements fragment form factor roadmaps, with sealed enclosure mandates from EU F-Gas Regulation driving passive cooling architectures into previously fan-cooled categories.
- Robotics:Collaborative and autonomous systems requiring real-time motion control with deterministic latency. Northern European factory automation integrators qualify fanless designs first, creating specification precedence that spreads southward as REACH restrictions on thermal management fluids tighten.
- IoT Devices:Networked sensors and edge nodes demanding sub-500mW sleep states for battery or energy-harvesting operation. Japan METI Top Runner standards for standby power create specification pull in building automation and instrumentation segments.
- Smart Home:Connected appliances and environmental controls with wireless pre-certification requirements.
- Automotive:In-vehicle infotainment and driver assistance systems with AEC-Q100 qualification demands.
Robotics leads current procurement volumes, with IoT Devices showing the steepest expansion trajectory as efficiency mandates penetrate building automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial computing module production originated in German precision engineering clusters and Japanese electronics manufacturing districts during the 1990s embedded systems wave. These foundations established the technical standards and supply chain relationships that persist in today's procurement patterns. Module demand now concentrates in manufacturing corridors where factory automation OEMs and contract electronics builders operate in close geographic proximity.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg specify ARM-based modules to replace legacy x86 controllers under EU Ecodesign sub-15W active consumption thresholds. REACH restrictions on halogenated flame retardants extend qualification timelines for new laminate variants. Stuttgart and Nuremberg engineering clusters host system integrators qualifying fanless thermal designs for sealed factory enclosures.
Japan
Medical device manufacturers in the Kanto region demand decade-long supply continuity for imaging equipment under PMDA lifecycle regulations. METI Top Runner standards for standby power below 500mW reshape module specifications in building automation. Nagoya industrial corridors integrate these components into robotics platforms for automotive manufacturing lines.
United States
Telecommunications infrastructure OEMs absorb FPGA module premiums for deterministic signal processing in baseband applications. FCC emissions testing adds 4-6 months to wireless-enabled module launch schedules. Austin and Boston technology corridors host edge AI developers converging neural processing units with traditional embedded form factors.
Taiwan
Contract electronics builders in Hsinchu and Taichung integrate ARM SoMs into collaborative robotics at volumes sustaining dedicated SKUs. TSMC foundry concentration creates geographic supply risk for leading-edge ARM SoC production. New Taipei City module assemblers serve East Asian manufacturing clusters with shortened logistics loops.
India
PLI scheme incentives for semiconductor assembly and testing attract module vendors establishing local production for domestic industrial automation demand. Karnataka and Tamil Nadu electronics manufacturing zones target supply chain redundancy for German and Japanese OEMs. Gujarat industrial corridors develop captive module capabilities for textile and pharmaceutical machinery builders.
System on Module (Som) Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the module landscape, with foundry-dependent vendors outsourcing silicon fabrication while maintaining in-house carrier board and thermal engineering capabilities. The vendor base organizes around three strategic archetypes: integrated industrial computing houses with captive manufacturing, specialized embedded module pure-plays with long-lifecycle commitments, and diversified electronics conglomerates leveraging component sourcing scale. Competitive positioning depends on securing foundry allocation for ARM SoC variants and maintaining kernel engineering teams capable of decade-long software support. Consolidation pressure intensifies as direct procurement relationships between OEM engineering teams and module vendors displace traditional distribution above 10,000-unit annual volumes.
Among German-based industrial computing specialists, Kontron AG and Congatec AG exemplify the integrated archetype with domestic manufacturing footprints optimized for EU regulatory compliance. Toradex AG represents the pure-play specialist model with Swiss organizational roots and focused embedded module portfolios. Advantech Co. Ltd. anchors the diversified conglomerate tier with Asia-Pacific demand coverage through extensive embedded portfolios serving factory automation integrators. These three patterns—integrated manufacturing, specialist focus, and diversified scale—capture the competitive structure governing design-win retention across medical and transportation verticals demanding supply continuity.
| Leading Market Players |
|---|
| Advantech Co. Ltd. |
| Kontron AG |
| Congatec AG |
| Toradex AG |
| AAEON Technology Inc. |
| Axiomtek Co. Ltd. |
| Eurotech S.p.A. |
| SECO S.p.A. |
| Variscite Ltd. |
| Others |
Supply Flow & Price Mechanics
Substrate laminate costs cascade through three distinct pricing tiers as REACH-compliant halogen-free materials displace legacy flame-retardant formulations across German and Japanese procurement channels. ARM SoC wafer pricing at TSMC feeds into module cost structures that separate premium FPGA-based units for telecommunications from economy ARM variants serving IoT volume deployments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts above 10,000-unit annual volumes. Premium tiers capture FPGA modules with deterministic latency guarantees for baseband processing, while standard tiers serve industrial automation with decade-long support bundles. Cost compression in economy ARM modules is intensifying because East Asian contract electronics builders negotiate direct frame contracts that bypass distribution markups. Medical device OEMs exhibit lowest price sensitivity due to PMDA and FDA requalification costs, whereas consumer IoT buyers prioritize unit economics over technical support depth.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Austin maintain hub-and-spoke patterns that position pre-certified modules within 48-hour delivery windows of major OEM engineering clusters. Leading-edge ARM SoC production draws from TSMC facilities in Taiwan, while substrate laminates source from Japanese and South Korean chemical suppliers. Single-source vulnerability concentrates at the 7nm and 5nm foundry nodes where alternative qualified capacity remains limited. Distribution runs through direct procurement relationships for volumes above 10,000 units annually, with traditional electronics distributors serving smaller program sizes and prototype quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier modules where long-lifecycle commitments and kernel engineering capabilities command 40-60 percent price premiums over commodity alternatives. Efficiency mandate compliance costs are compressing economy-tier margins while rewarding vendors with pre-certified, fanless thermal designs.
For Market Incumbents: Anticipate displacement risk from India-based module assemblers leveraging PLI scheme incentives to undercut European manufacturing costs for sub-15W ARM variants. Defensive consolidation should prioritize backward integration into carrier board manufacturing and captive kernel engineering teams capable of sustaining decade-long Linux support commitments. Certification investment in pre-scanned FCC modules compresses customer launch timelines and locks out second-source substitution.
For New Entrants and Emerging Players: Capture white-space in edge AI inference modules combining neural processing units with traditional SoM form factors for medical imaging and predictive maintenance applications. India electronics manufacturing zones offer the most penetrable geography, with Karnataka and Tamil Nadu targeting supply chain redundancy for German and Japanese OEMs. Go-to-market positioning should emphasize sub-500mW sleep state compliance for Japan METI Top Runner standards and EU Ecodesign networked equipment rules.
For Investors and Strategic Acquirers: Roll-up economics work for specialized embedded module pure-plays because long-lifecycle customer commitments generate predictable recurring revenue streams and deter competitive entry. Platform consolidation across kernel engineering capabilities and foundry allocation contracts sustains viability across a 5-10 year window. Acquisition target archetypes include ARM-based module vendors with proven PMDA and FDA support track records. The signal to watch is direct procurement contract announcements from German automotive and robotics OEMs exceeding five-year supply horizons.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Lifecycle Supply Commitment | Ten-to-fifteen year guarantees lock in design wins at German medical device OEMs under PMDA regulations. |
| Fanless Thermal Design Certification | Passive cooling qualification creates specification precedence spreading from Northern European factory automation integrators. |
| Edge AI Module Integration | Neural processing unit convergence opens real-time pathology screening for German and Japanese imaging equipment vendors. |
| India Manufacturing Footprint | PLI scheme incentives enable local assembly serving domestic industrial automation demand and export redundancy. |
| Pre-Certified Wireless Module Launch | FCC emissions pre-testing compresses customer product development schedules by 4-6 months in IoT segments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with embedded systems procurement managers at German industrial automation OEMs, kernel engineering directors at module vendors, contract electronics manufacturing executives in Taiwan, and medical device regulatory affairs leads in Japan. Secondary validation drew from EU Ecodesign implementation documents, METI Top Runner standard filings, FCC equipment authorization databases, and TSMC foundry capacity disclosures. Bottom-up module shipment estimates and top-down industrial computing market sizing were cross-referenced for triangulation.
Segment-weighting approaches distributed total addressable value across processor module, embedded module, interface module, and memory module categories, with further disaggregation by ARM, FPGA, SoC, and x86 technology architectures. End-user segmentation applied differential margin assumptions for industrial automation, medical devices, telecommunications, and consumer electronics verticals. CAGRs were derived from replacement cycle compression analysis and efficiency mandate adoption curves. Forecast inputs incorporated foundry allocation constraints for leading-edge ARM SoCs and REACH-compliant substrate material transition timelines.
Foundry capacity reallocation, REACH substance restriction expansions, and METI efficiency threshold revisions are the dominant revision risks that could alter module availability and pricing trajectories across the projection horizon. Forecasts reflect assumptions documented in the segmentation weighting and stakeholder interview protocols. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market