
 Solid-State Lighting Source Market | 2026-2036
Solid-State Lighting Source Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-State Lighting Source Market Analytics
The EU Green Deal's phased fluorescent lamp ban is realigning procurement patterns across European commercial and industrial sectors. Nichia Corporation leverages its phosphor technology leadership to sustain premium positioning in high-CRI applications. Seoul Semiconductor anchors its competitive stance through patented Wicop chip-scale packaging that eliminates wire bonds. Samsung Electronics dominates the backlighting segment for display panels, extending its semiconductor fabrication advantages into epitaxial wafer production.
Solid-state lighting sources convert electrical energy directly into visible light through semiconductor electroluminescence, typically operating at forward voltages between 2.5V and 3.5V for gallium nitride-based devices with luminous efficacies exceeding 150 lumens per watt in commercial packages. LED product types command the dominant revenue share due to mature supply chains and economies of scale in sapphire and silicon carbide substrates. OLED applications occupy premium architectural and automotive interior niches where emissive surface uniformity justifies higher unit costs. Smart lighting technology segments are expanding fastest as building management systems integrate occupancy sensing and daylight harvesting protocols.
The US Department of Energy's SSL program coordinates with EPA ENERGY STAR certification to establish minimum efficacy and color quality thresholds that shape product eligibility for utility rebate programs. China's GB standards administered by SAMR mandate specific luminous efficacy tiers for domestic market access, creating differentiated compliance pathways for local versus export-oriented manufacturers. Japan's METI Top Runner program continuously ratchets efficiency benchmarks, forcing technology transitions ahead of voluntary adoption curves. Stakeholders must monitor how evolving flicker metrics and circadian lighting standards reshape specification requirements in healthcare and education verticals.
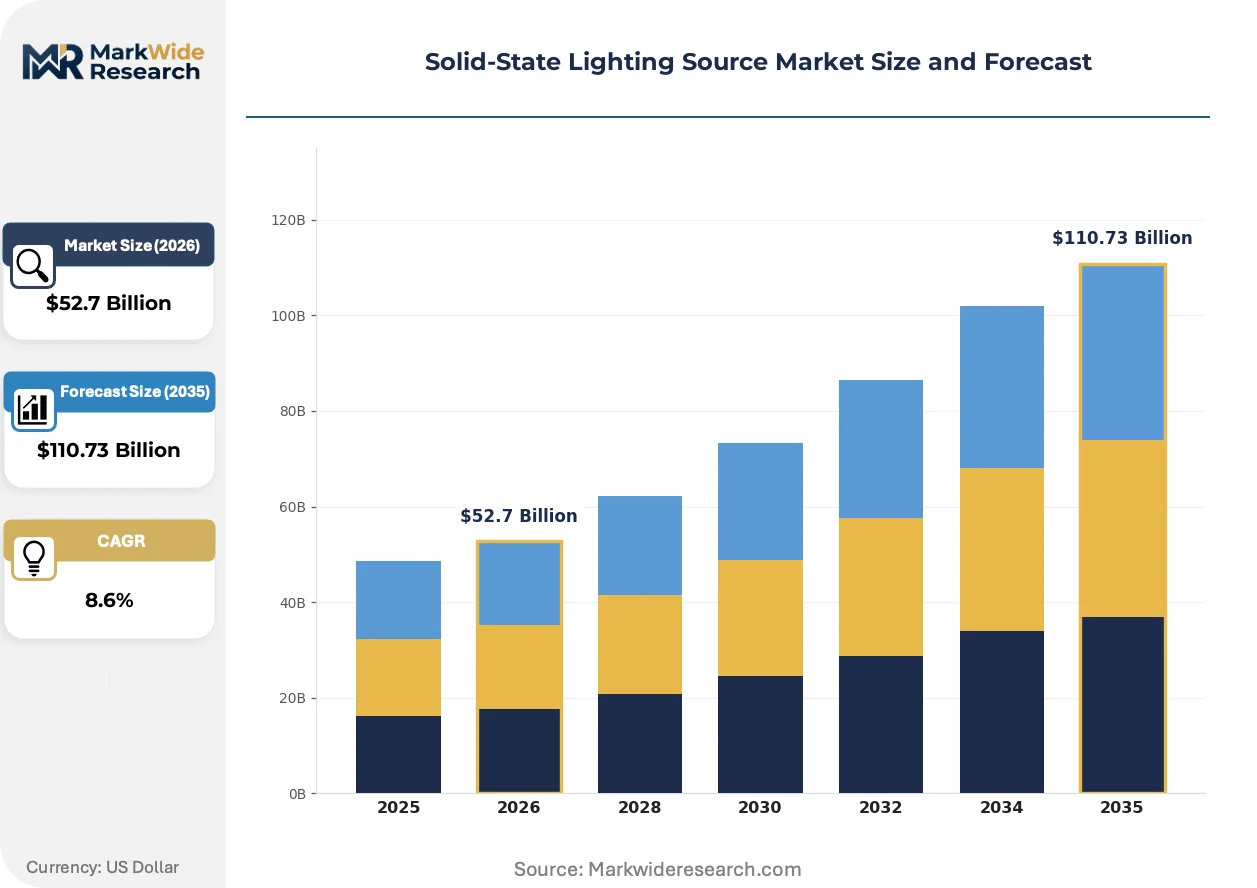
Market Dynamics
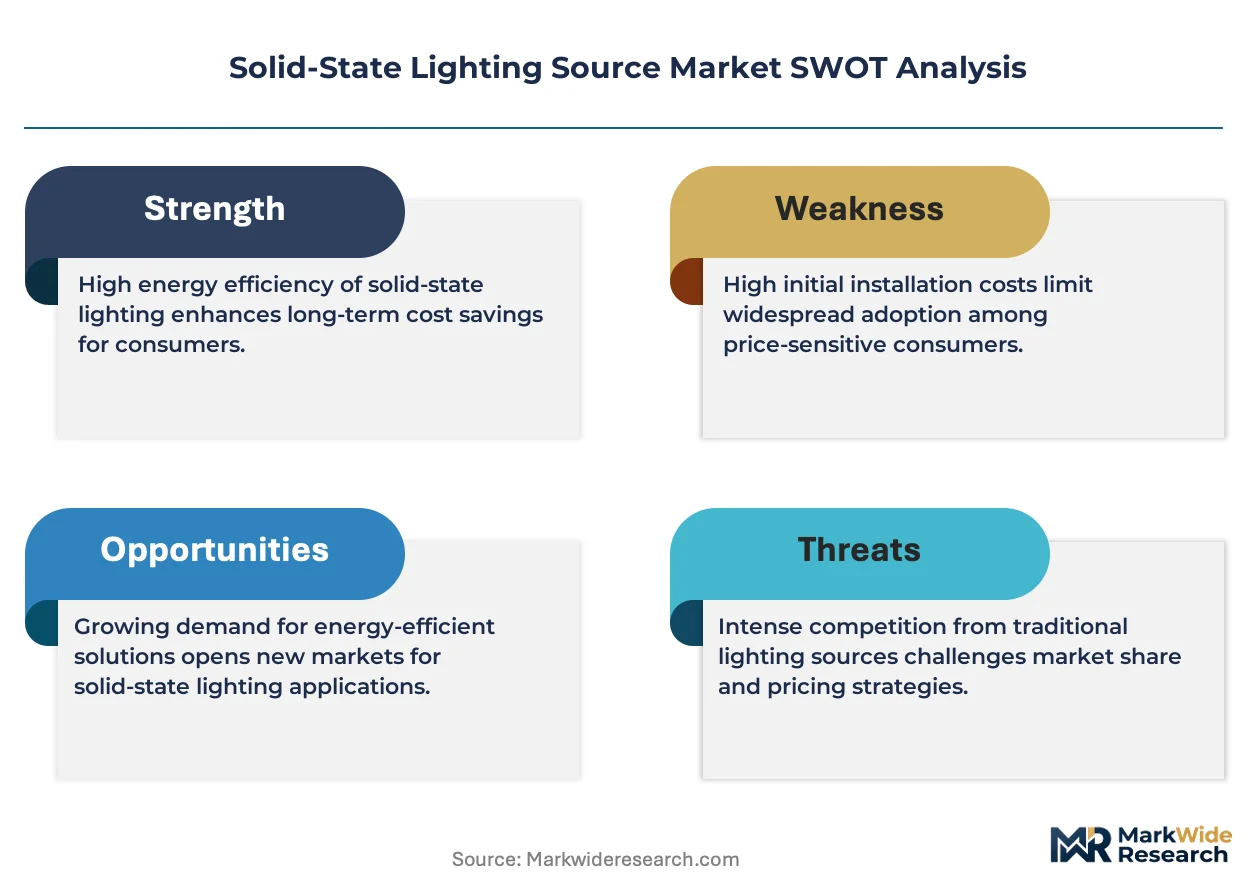
The EU Green Deal's phased fluorescent lamp ban is forcing immediate procurement pivots across European commercial and industrial sectors, while automotive LED adoption accelerates simultaneously.
Growth Catalysts
- EU Green Deal lamp ban:The phased prohibition on fluorescent lighting is compelling facility managers across Germany, France, and Italy to accelerate solid-state retrofits ahead of compliance deadlines.
- Automotive exterior LED adoption:Headlamp and taillight manufacturers are specifying higher-luminance packages as adaptive driving beam systems proliferate in premium vehicle segments.
- Urban lighting retrofits:Chinese municipal procurement concentrated in tier-one cities is driving volume demand for high-efficacy street and tunnel luminaires.
Market Restraints
- Sapphire substrate supply concentration:Limited qualified wafer suppliers in East Asia create input bottlenecks during demand surges, constraining LED die availability.
- OLED manufacturing yield limitations:Organic vapor deposition inconsistency elevates unit costs above acceptable thresholds for general illumination applications.
- Legacy fixture incompatibility:Existing fluorescent troffer infrastructure requires complete luminaire replacement rather than lamp substitution, extending payback periods for building owners.
Strategic Opportunities
- Human-centric lighting protocols:Circadian rhythm-optimized spectral tuning is penetrating healthcare and education verticals where wellness certification drives specification.
- Building management system convergence:Integration of occupancy sensing, daylight harvesting, and networked controls creates bundled value propositions for commercial real estate operators.
- India's Smart Cities Mission:Municipal street lighting tenders incorporating remote monitoring and energy performance contracting are opening deployment pathways for system integrators.
Industry Challenges
- Epitaxial wafer engineering talent scarcity:Compound semiconductor fabrication expertise remains concentrated among a limited pool of process engineers, constraining capacity expansion timelines.
- Flicker metric compliance complexity:Evolving IEEE standards and healthcare-specific requirements demand redesigned driver architectures, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid-State Lighting Source Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, MicroLED, Quantum Dot Application: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, RGB, White Light, Tunable White Installation: New Construction, Retrofit, Fixture Integration, Stand-Alone |
| Companies Covered | Koninklijke Philips N.V., Osram Licht AG, Samsung Electronics Co. Ltd., GE Lighting, Mitsubishi Electric Corporation, Nichia Corporation, Acuity Brands, Signify, Seoul Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-State Lighting Source Market Evolving Landscape
Miniaturization of light-emitting surfaces is converging with intelligent control architectures, redefining how luminaires integrate into built environments and connected infrastructure systems.
Chip-scale packaging architectures are eliminating wire bonds and expanding into automotive forward lighting modules where thermal cycling durability and optical precision are paramount. Tier-one headlamp suppliers in Germany and Japan are qualifying these packages for adaptive driving beam matrices that require millimeter-scale emitter spacing. The technology is expanding into high-beam segments previously reserved for discrete high-power LEDs.
The EU Green Deal's fluorescent lamp prohibition is restructuring commercial procurement across member states, with facility managers now bundling LED retrofits with building automation upgrades to capture utility incentives. Germany's KBA and France's national energy agency are coordinating enforcement timelines, compressing decision windows for industrial lighting specifiers. The regulation is accelerating warehouse and manufacturing sector transitions where operating hours maximize energy savings returns.
Performance-based energy service contracts are displacing capital purchase models in North American commercial real estate, with lighting-as-a-service providers retaining ownership of installed assets and guaranteeing luminous output maintenance. Building owners in California and New York are prioritizing vendors offering circadian lighting compliance bundled with ongoing spectral tuning adjustments. This reconfiguration concentrates specification authority with energy service companies rather than traditional electrical distributors.
Solid-State Lighting Source Market Segmentation
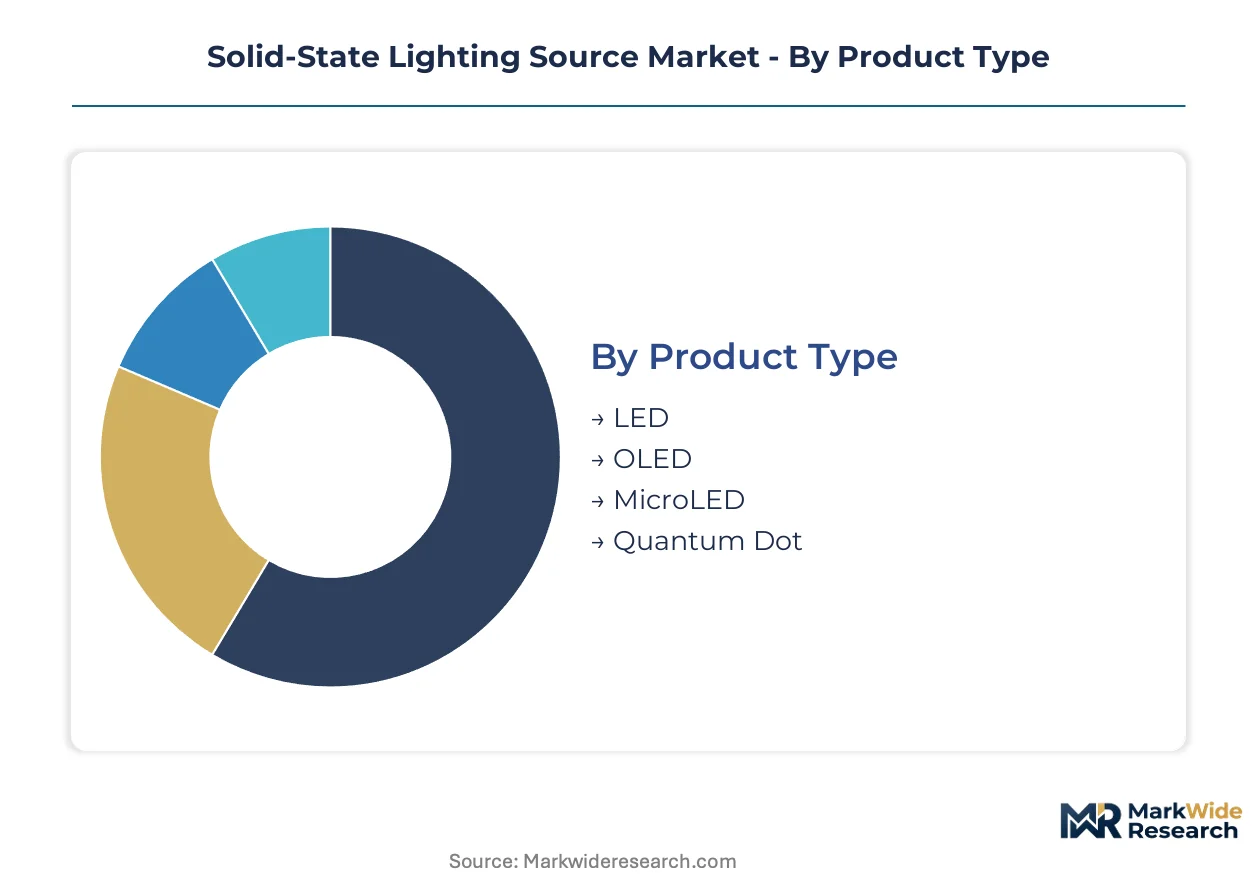
Segmentation in solid-state lighting reveals how technical specifications, application environments, and installation constraints reshape procurement criteria across divergent customer workflows. Product architecture and connectivity requirements fragment demand patterns in ways that reward specialized manufacturing capabilities over undifferentiated volume production.
Product Type:
The customization-to-standardization spectrum runs from commodity LED packages to precision-engineered MicroLED arrays requiring bespoke epitaxial growth protocols.
- LED:Gallium nitride-based devices fabricated on sapphire or silicon carbide substrates dominate volume shipments with luminous efficacies exceeding 150 lumens per watt. Chinese municipal street lighting retrofits and German automotive headlamp specifications concentrate demand for high-reliability packages with ceramic substrate thermal management.
- OLED:Organic vapor deposition creates emissive surface layers delivering uniform illumination without secondary optics, commanding premium positioning in Japanese automotive interior ambient lighting and Korean display panel backlighting where form factor flexibility outweighs unit cost sensitivity.
- MicroLED:Chip-scale emitters below 50 micrometers enable pixel-dense displays with self-emissive characteristics.
- Quantum Dot:Nanocrystal phosphors tune emission spectra with narrow full-width half-maximum for enhanced color gamut in display applications.
Leading the category by volume: LED. Expanding most quickly: MicroLED.
Application:
Cost tier stratification separates specification-intensive industrial deployments from price-sensitive residential retrofit markets.
- Commercial:Office and retail installations prioritize networked controls with occupancy sensing and daylight harvesting protocols integrated into building management systems. California and New York building codes mandate circadian lighting compliance in healthcare and education verticals, reshaping luminaire specification toward tunable white capabilities.
- Industrial:High-bay warehouse and manufacturing facilities demand 50,000-hour minimum rated life with IP65 ingress protection. German KBA enforcement of EU Green Deal fluorescent bans compresses decision windows for facility managers seeking energy performance contracting arrangements.
- Residential:Consumer retrofit purchases concentrate through electrical distributors and big-box retail channels.
- Outdoor:Street, tunnel, and area lighting applications require thermal cycling durability and photocell compatibility.
Dominant by installed base: Commercial. Gaining share fastest: Industrial.
Technology:
Customer type segmentation distinguishes specification-driven building automation integrators from component-focused fixture manufacturers.
- Smart Lighting:Networked luminaires with embedded sensors and wireless connectivity enable remote commissioning and predictive maintenance. India's Smart Cities Mission tenders incorporate these capabilities with energy performance guarantees, opening deployment pathways for system integrators competing on operational outcomes rather than hardware margins.
- Tunable White:CCT adjustment from 2700K to 6500K supports circadian lighting protocols in healthcare and education settings where wellness certification drives specification authority toward energy service companies.
- RGB:Red-green-blue emitter mixing enables dynamic color rendering for architectural and entertainment applications.
- White Light:Fixed CCT packages serve cost-optimized general illumination with minimal control complexity.
Highest volume deployment: White Light. Steepest expansion trajectory: Smart Lighting.
Installation:
Supply concentration patterns differentiate captive vertical integration strategies from distributed component sourcing models.
- Retrofit:Lamp-level LED substitution for existing fluorescent and HID fixtures addresses immediate EU Green Deal compliance deadlines across German, French, and Italian commercial estates. Complete luminaire replacement requirements extend payback periods where legacy troffer infrastructure lacks LED-compatible thermal management.
- Fixture Integration:LED modules and drivers specified by original equipment manufacturers concentrate procurement authority with tier-one lighting brands controlling optical and thermal design.
- New Construction:Integrated lighting design from building commissioning enables optimized daylight harvesting and control zoning.
- Stand-Alone:Portable and task lighting products bypass permanent electrical infrastructure requirements.
Maximum current volume: Fixture Integration. Climbing the fastest: Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan anchor the world's densest concentration of LED packaging and luminaire assembly operations, with municipal procurement in Guangzhou and Shanghai driving retrofit volumes through government-backed urban lighting programs.
China
Domestic production capacity in Jiangsu and Zhejiang provinces supplies the bulk of global LED die and package output. GB standards administered by SAMR mandate luminous efficacy tiers that create dual compliance tracks for local versus export-oriented manufacturers. Tier-one cities including Beijing and Chengdu are executing street and tunnel lighting retrofits with energy performance contracting mechanisms.
Germany
Automotive headlamp manufacturers in Stuttgart and Munich specify high-reliability LED packages for adaptive driving beam matrices. KBA enforcement of EU Green Deal fluorescent lamp prohibitions compresses decision windows for industrial facility managers. The Ruhr industrial corridor is witnessing accelerated warehouse lighting transitions tied to energy service contract structures.
United States
Commercial real estate operators in California and New York are bundling LED retrofits with building automation upgrades to capture utility incentives. EPA ENERGY STAR certification coordinated with DOE SSL programs establishes rebate eligibility thresholds. The Dallas-Fort Worth metroplex concentrates specification authority with energy service companies deploying lighting-as-a-service models.
Japan
Automotive interior ambient lighting demand from Toyota City and Yokohama manufacturing clusters sustains premium OLED sourcing. METI Top Runner programs continuously ratchet efficiency benchmarks ahead of voluntary adoption curves. The Kansai region around Osaka maintains phosphor technology leadership for high-CRI applications.
India
Municipal corporations in Mumbai and Delhi are tendering street lighting with remote monitoring capabilities under Smart Cities Mission frameworks. BIS standards create compliance pathways for domestic assembly operations. The Gujarat industrial corridor is attracting component packaging investments to serve South Asian retrofit demand.
Solid-State Lighting Source Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive semiconductor fabrication capabilities. Market concentration remains moderate, with tier-one lighting brands controlling optical and thermal design specifications while outsourcing die production to specialized epitaxial foundries. Three archetypes dominate: integrated electronics majors with display panel synergies, pure-play LED specialists with phosphor IP, and automotive-focused component suppliers with AEC-Q100 qualification expertise. Capacity expansion and strategic technology licensing represent the primary competitive vectors, with players securing long-term sapphire substrate supply agreements and acquiring circadian lighting software capabilities.
Among Japanese specialists, Nichia Corporation and Mitsubishi Electric Corporation exemplify the phosphor technology and diversified electronics archetypes respectively. Seoul Semiconductor anchors the Korean specialist tier with chip-scale packaging expertise. Koninklijke Philips N.V. and Signify occupy positions within the integrated lighting systems vector, while Samsung Electronics Co. Ltd. represents the display-backlighting synergies archetype. Osram Licht AG and GE Lighting sit within the automotive-forward and industrial-commercial specification channels. Acuity Brands exemplifies the North American building automation convergence play.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Osram Licht AG |
| Samsung Electronics Co. Ltd. |
| GE Lighting |
| Mitsubishi Electric Corporation |
| Nichia Corporation |
| Acuity Brands |
| Signify |
| Seoul Semiconductor |
| Others |
Value Network & Pricing Analysis
Sapphire wafer price indices cascade through epitaxial growth, packaging, and luminaire assembly stages, concentrating cost pressure where Chinese substrate suppliers face German automotive headlamp specifications demanding AEC-Q100 qualification premiums.
Pricing Analysis
Energy performance contracting anchors value-based pricing in commercial real estate, with lighting-as-a-service providers guaranteeing luminous output maintenance rather than selling hardware. Three-tier pricing structure across premium, standard, and economy levels separates circadian-certified healthcare luminaires from basic retrofit tubes. Cost compression in commodity LED packages intensifies as Chinese municipal procurement consolidates volume around domestic manufacturers. Residential retrofit buyers exhibit highest price sensitivity, while German automotive Tier 1s accept premium positioning for adaptive driving beam reliability.
Supply Chain Analysis
End-of-life luminaire take-back programs and phosphor recovery flows remain underdeveloped, constraining circular material re-entry into epitaxial wafer production. Manufacturing gravity centers on China, Japan, and South Korea, with Jiangsu province hosting the densest LED die fabrication clusters. Compound semiconductor fabrication draws from sapphire substrates, metal-organic precursors, and specialized MOCVD equipment. Single-source vulnerability concentrates in qualified sapphire wafer suppliers serving AEC-Q100 automotive qualifications. Distribution runs through tier-one lighting brands controlling optical and thermal specifications rather than commodity component traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxial wafer engineering talent scarcity props pricing power for qualified manufacturers, with capacity expansion timelines stretching beyond typical procurement cycles.
For Market Incumbents: Acquire circadian lighting software capabilities to bundle spectral tuning with hardware maintenance contracts. Secure long-term sapphire substrate supply agreements with East Asian wafer suppliers before German KBA enforcement compresses decision windows. Defensive consolidation around phosphor IP protects premium positioning against Korean chip-scale packaging specialists. For New Entrants and Emerging Players: Human-centric lighting protocols offer technology-first entry into healthcare and education verticals where wellness certification displaces traditional electrical distributors. India's Smart Cities Mission tenders present the most penetrable geography, with municipal energy performance contracting opening deployment pathways for system integrators. Position around remote monitoring capabilities and predictive maintenance software rather than commodity luminaire manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-focused component suppliers with AEC-Q100 qualification expertise in Japan and Germany, where OEM consolidation creates acquisition targets. Long-term viability hinges on captive semiconductor fabrication capabilities spanning gallium nitride epitaxy through packaged emitters. Monitor EU Green Deal enforcement timelines across German KBA and French national energy agency coordination as inflection indicators for retrofit demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sapphire Substrates | Captive wafer supply secures AEC-Q100 qualification pipelines for Stuttgart automotive headlamp manufacturers. |
| Circadian Lighting Software Acquisition | Spectral tuning capabilities capture California and New York healthcare compliance mandates driving specification authority. |
| Chip-Scale Packaging Scale-Up | Wicop architecture elimination of wire bonds penetrates adaptive driving beam matrices requiring millimeter-scale precision. |
| Smart Cities Mission Partnership | Remote monitoring integration opens Mumbai and Delhi municipal tenders with energy performance guarantees. |
| Phosphor Technology Licensing | High-CRI IP monetization sustains premium positioning against commoditized gallium nitride die competition. |
Research Methodology
Independent corroboration across MOCVD equipment suppliers, tier-one automotive headlamp manufacturers, and municipal procurement officers underwrites the qualitative findings. Primary interviews with epitaxial process engineers, lighting specification consultants, and energy service company executives combined with secondary validation from SAMR GB standard filings, EPA ENERGY STAR certification databases, and KBA enforcement timelines. Bottom-up triangulation across packaged LED shipment data and top-down reconciliation with luminaire installation permits anchored volume estimates.
Comparable-period anchoring to pre-EU Green Deal fluorescent lamp baselines established retrofit demand trajectories across the projection horizon. Segmentation modeling spanned product architecture, application environment, installation type, and connectivity protocol dimensions. CAGRs derived from supply-side capacity expansion schedules and demand-side regulatory compliance deadlines. Industry-specific inputs incorporated METI Top Runner efficiency benchmark ratchets and Chinese dual carbon goal implementation timelines.
Several conditions sit outside the modeled scope, including potential IEEE flicker metric revisions and healthcare-specific circadian lighting standard evolutions. Forecasts reflect assumptions around sapphire substrate supply continuity and automotive LED adoption curves in premium vehicle segments. Practitioners should monitor German KBA enforcement coordination with France's national energy agency and evolving BIS standard implementations in India for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Cleanroom Lighting Market
Lighting
Intelligent Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
Industrial OLED Lighting Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Photography Light Box Market
Lighting
Street Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
Xenon Lights Market
Lighting
US Indoor LED Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
Flexible Lighting Foils Market
Lighting
Xenon Headlights Market
Lighting
Solar Spotlights Market
Lighting
Ambient Lighting Market
Lighting
OLED Lightening Panels Market