
 Wireless Lighting Market | 2026-2036
Wireless Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Lighting Market Outlook
The EU Green Deal is restructuring procurement priorities for wireless lighting across European commercial real estate. Signify leverages its Hue ecosystem and professional channels to sustain dominance in connected luminaires. Acuity Brands anchors North American project activity through its Atrius building intelligence platform. Schneider Electric competes on energy management integration, extending its EcoStruxure architecture into wireless lighting control.
Wireless lighting encompasses luminaires and control systems that communicate without dedicated wired data infrastructure, typically operating via mesh protocols such as Zigbee 3.0 or Bluetooth Low Energy 5.0 with latency below 250 milliseconds for real-time dimming and occupancy response. These systems serve primarily to reduce installation labor, enable granular energy metering, and support human-centric circadian tuning in commercial and healthcare environments. Control Systems command the deepest margin pools as software subscriptions and sensor analytics attach to hardware deployments. Zigbee retains technology leadership in large-footprint commercial projects, while Bluetooth is gaining fastest in residential retrofit scenarios where smartphone-native commissioning eliminates gateway requirements.
The EU F-Gas Regulation and Ecodesign Directive shape product compliance requirements for wireless lighting sold across Europe, with CE marking contingent on standby power thresholds and mercury-free construction. In the United States, the EPA ENERGY STAR program and DOE lighting efficiency standards influence specification decisions for federal and utility-rebate-funded projects. China's GB standards and dual carbon goals from MEE are accelerating domestic LED and smart lighting replacement timelines. Stakeholders must monitor protocol interoperability certification trajectories and evolving cybersecurity mandates for networked building systems.
Market Dynamics
Building automation convergence with energy management platforms is compressing procurement cycles and forcing control system vendors to bundle software subscriptions with hardware deployments.
Growth Catalysts
- EU Green Deal energy efficiency mandates:Tightening requirements for lighting systems across member states are accelerating retrofit timelines in commercial real estate.
- Smart city infrastructure scaling:Germany, China, and the United States are deploying municipal wireless lighting networks for street-level energy management.
- Zigbee 3.0 mesh protocol maturity:Sub-250 millisecond latency for real-time dimming is enabling occupancy-responsive systems in healthcare and office environments.
Market Restraints
- Silicon and rare earth supply concentration:Dependence on concentrated semiconductor foundry capacity in East Asia creates lead time volatility for wireless control modules.
- Cybersecurity compliance friction:Evolving mandates for networked building systems are extending certification timelines and raising engineering overhead.
- Legacy wired infrastructure substitution:Existing DALI and 0-10V installations in mature commercial buildings slow wireless adoption where rewiring costs are sunk.
Strategic Opportunities
- Residential Bluetooth retrofit expansion:Smartphone-native commissioning without gateway requirements is opening retrofit demand in single-family housing.
- Human-centric circadian tuning:Healthcare and education facilities are specifying tunable white systems for wellness applications.
- China dual carbon goals:MEE acceleration of domestic LED and smart lighting replacement is creating volume demand for control system exports.
Industry Challenges
- Protocol interoperability certification gaps:Fragmented mesh certification trajectories between Zigbee and Bluetooth are forcing vendors to maintain dual-stack development.
- Integration complexity with BMS legacy:BACnet and Modbus integration requirements in existing building management systems extend deployment engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Lighting Market |
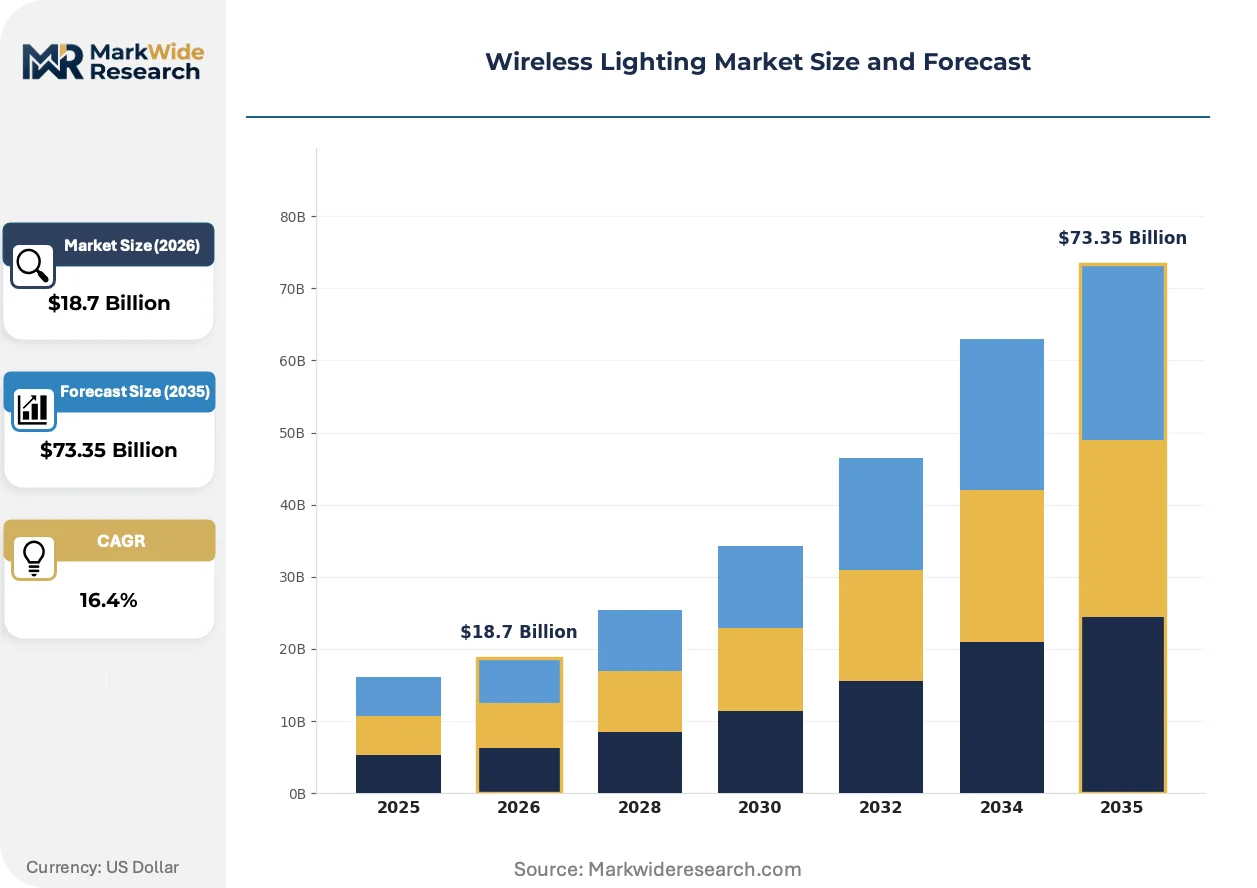
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bulbs, LED Fixtures, Control Systems, Adapters Technology: Zigbee, Wi-Fi, Bluetooth, Li-Fi Installation: Retrofit, New Construction, Surface Mount, Wireless End User: Residential, Commercial, Industrial, Outdoor |
| Companies Covered | Signify (Philips Lighting), Acuity Brands, Lutron Electronics, Legrand, Eaton Corporation, Hubbell Incorporated, Honeywell International, Schneider Electric, ams OSRAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Lighting Market Strategic Shifts
Wireless lighting control is shifting from hardware-centric sales to software-anchored platform models, with sensor analytics and energy metering becoming primary value drivers.
Bluetooth Low Energy 5.0 with direction-finding capabilities is automating asset tracking and occupancy verification in retail and logistics facilities. Big-box retailers are deploying these systems at scale for footfall analytics. This convergence is automating the unbundling of lighting infrastructure from pure illumination into spatial intelligence platforms.
The EPA ENERGY STAR program and DOE lighting efficiency standards are tightening federal procurement specifications. Federal and utility-rebate-funded projects now require networked metering capabilities. Commercial building operators in the United States are responding by specifying control systems with embedded energy analytics.
Facility managers are compressing vendor relationships toward single-source platform contracts. Traditional electrical distributors are losing specification influence to direct manufacturer engagements with ESCOs and systems integrators. This consolidation is most visible in German and US commercial retrofit markets where energy service companies bundle lighting upgrades with performance guarantees.
Wireless Lighting Market Segmentation
Wireless lighting segmentation reveals how procurement priorities diverge across buyer sophistication and infrastructure constraints. Control system vendors must align product architectures with distinct latency requirements, installation labor economics, and regulatory compliance obligations.
Product Type:
Commercial buyers prioritize energy metering granularity and software subscription attach rates; residential buyers emphasize smartphone commissioning simplicity and circadian tuning features.
- Smart Bulbs:Self-contained luminaires with embedded wireless radios and tunable white capabilities. Demand concentrates in Germany and US residential retrofit channels where ENERGY STAR rebates offset premium pricing and Bluetooth-native commissioning eliminates gateway friction.
- LED Fixtures:Integrated luminaire-control combinations with sensor bays for occupancy and daylight harvesting. Commercial real estate operators in China specify these for MEE dual carbon compliance, bundling hardware with performance contracting from energy service companies.
- Control Systems:Mesh gateways, scene controllers, and energy analytics platforms commanding recurring software revenue. Industrial facilities adopt these for BACnet integration with legacy building management systems.
- Adapters:Wireless retrofit modules converting existing luminaires to mesh-controllable endpoints. Healthcare facilities deploy these where full fixture replacement disrupts continuous operations.
Volume sits with LED Fixtures; growth tilts toward Control Systems.
Technology:
Protocol selection hinges on footprint scale, latency tolerance, and whether smartphone-native commissioning outweighs mesh reliability requirements.
- Zigbee:Mesh protocol with sub-250 millisecond latency optimized for large-footprint commercial deployments. German smart city infrastructure projects specify Zigbee 3.0 for street-level energy management and municipal occupancy analytics.
- Bluetooth:Low Energy 5.0 with direction-finding enabling asset tracking convergence. US big-box retailers deploy these systems for footfall analytics and spatial intelligence beyond pure illumination.
- Wi-Fi:IP-native connectivity leveraging existing enterprise infrastructure. Office environments with saturated Wi-Fi coverage adopt these to avoid dedicated gateway hardware.
- Li-Fi:Visible light communication offering electromagnetic interference immunity and bandwidth density. Defense and healthcare facilities in China pilot these for secure data transmission in restricted zones.
Bluetooth captures the steepest expansion trajectory in residential retrofit; Zigbee retains commercial project dominance.
Installation:
Labor economics and building age determine whether buyers absorb full fixture replacement costs or pursue lower-disruption retrofit paths.
- Retrofit:Wireless overlay installations minimizing electrical contractor time and permitting. US commercial buildings with sunk DALI infrastructure adopt these to defer rewiring capital.
- New Construction:Native wireless specification during electrical rough-in. German developers bundle these with KfW energy efficiency financing and EU Green Deal compliance documentation.
- Surface Mount:Exposed wireless luminaires for industrial and outdoor applications where ceiling plenum access is impractical. Chinese manufacturing facilities specify these for rapid deployment without production downtime.
- Wireless:Fully battery-powered or energy-harvesting endpoints eliminating line voltage entirely. Outdoor municipal deployments in the United States leverage these for street furniture lighting without trenching.
Retrofit commands current volume; new construction offers margin expansion as developers specify platform-native systems.
End User:
Procurement authority and energy cost exposure shape whether buyers prioritize hardware cost minimization or software-enabled energy savings verification.
- Commercial:Office, retail, and hospitality operators specifying networked metering for utility rebate capture and ESG reporting. EU Green Deal tightening drives retrofit acceleration across member state commercial real estate.
- Residential:Single-family and multifamily occupants prioritizing circadian tuning and voice assistant integration. German households adopt these for EEG renewable energy tariff optimization.
- Industrial:Manufacturing and warehouse facilities requiring high-bay wireless control with motion-responsive dimming. China's MEE enforcement pushes replacement timelines in heavy industry zones.
- Outdoor:Municipal street lighting and architectural facade systems with centralized energy management. US cities deploy these for EPA ENERGY STAR compliance and federal infrastructure funding eligibility.
Commercial generates the deepest margin pools; residential expands most quickly through Bluetooth retrofit penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors wireless lighting module production, supplying control chipsets to German smart city contractors and US commercial retrofit integrators.
United States
Commercial building operators in Chicago and New York accelerate wireless deployments to capture EPA ENERGY STAR rebates and federal infrastructure funding. The DOE lighting efficiency standards tighten procurement specifications for networked metering capabilities. ESCOs in California bundle lighting upgrades with performance guarantees, consolidating vendor relationships toward platform-native systems.
Germany
Municipalities in Munich and Hamburg specify Zigbee 3.0 mesh networks for street-level energy management and occupancy analytics. The EU Green Deal and F-Gas Regulation tighten energy efficiency requirements across member state commercial real estate. KfW energy efficiency financing drives native wireless specification in new construction developments across the Rhine-Ruhr metropolitan region.
China
Manufacturing facilities in Guangdong and Jiangsu provinces deploy surface-mount wireless luminaires to avoid production downtime during retrofit. The MEE dual carbon goals accelerate domestic LED and smart lighting replacement timelines in heavy industry zones. Beijing-Tianjin-Hebei corridor pilots Li-Fi systems for secure data transmission in restricted government and healthcare facilities.
Japan
Healthcare facilities in Tokyo and Osaka adopt tunable white systems for circadian wellness applications in patient recovery environments. METI efficiency standards shape procurement priorities for building automation convergence. The Kansai region's semiconductor fabrication plants specify electromagnetic interference-immune lighting controls for cleanroom operations.
United Kingdom
London commercial real estate operators restructure procurement priorities around EU Green Deal compliance documentation post-Brexit transition. The Ecodesign Directive and CE marking requirements influence standby power thresholds for imported control systems. Manchester and Birmingham retrofit markets concentrate demand for wireless overlay installations minimizing electrical contractor time.
Wireless Lighting Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with building automation portfolios. Control system vendors compete on software subscription attach rates and energy analytics integration rather than hardware differentiation alone. Three archetypes dominate: lighting-native specialists with hue ecosystems, electrical infrastructure conglomerates with energy management platforms, and building automation integrators with BMS legacy compatibility. Consolidation pressure manifests through strategic partnerships with ESCOs and direct engagement models bypassing traditional electrical distributors.
Within the lighting-native tier, Signify and ams OSRAM represent ecosystem-driven positioning around connected luminaires and professional channels. Among diversified electrical infrastructure players, Schneider Electric and Legrand occupy positions bridging wireless lighting control with broader building intelligence architectures. Acuity Brands anchors the North American project activity vector through building intelligence platform integration.
| Leading Market Players |
|---|
| Signify (Philips Lighting) |
| Acuity Brands |
| Lutron Electronics |
| Legrand |
| Eaton Corporation |
| Hubbell Incorporated |
| Honeywell International |
| Schneider Electric |
| ams OSRAM |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal procurement mandates for networked metering capabilities are compressing buyer budgets toward control system vendors with embedded energy analytics, forcing suppliers to absorb software development costs and compress hardware margins.
Pricing Analysis
Outcome-based pricing anchored to verified energy savings dominates commercial retrofit contracts. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified systems with BACnet integration from basic Zigbee mesh kits and unbranded Bluetooth retrofit modules. Cost compression in economy tiers intensifies because Shenzhen-based control module producers compete on volume. Residential buyers exhibit highest price sensitivity, while healthcare facilities prioritize certification tiers over unit cost.
Supply Chain Analysis
Skilled electronics assembly labor availability in Guangdong province and the Yangtze River Delta anchors wireless control module production. Semiconductor foundry capacity in Taiwan and South Korea feeds mesh radio chipsets, while rare earth phosphor materials for LED emitters draw from Chinese separation facilities. Single-source vulnerability concentrates in 40nm BLE SoC fabrication. Distribution runs through electrical distributors losing ground to direct manufacturer engagements with ESCOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for sub-40nm wireless SoCs prop pricing power for vendors with secured wafer allocations, sustaining margin pools in control system tiers.
For Market Incumbents: Anticipate Bluetooth-native commissioning displacing Zigbee gateway architectures in residential channels by accelerating dual-stack firmware development. Prioritize backward integration into sensor semiconductor sourcing to defend against foundry allocation volatility. Lock long-term supply agreements with Taiwanese foundries before capacity tightens further. For New Entrants and Emerging Players: Enter via Li-Fi pilot deployments in Chinese government and healthcare restricted zones where electromagnetic immunity commands premium pricing. Target industrial surface-mount retrofit applications in Guangdong manufacturing corridors where production downtime avoidance justifies rapid deployment premiums. Partner with local ESCOs for performance-contracting channel access. For Investors and Strategic Acquirers: The window for entry favors building automation integrators with BACnet legacy compatibility and recurring software revenue streams. Acquisition target archetype: mid-cap control system vendors with municipal smart city deployment trackbacks in Germany or China. Monitor Zigbee-Bluetooth protocol convergence certification timelines as inflection signal for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Stack Protocol Development | Maintains Zigbee commercial dominance while capturing Bluetooth residential retrofit expansion. |
| ESCO Direct Engagement | Bypasses electrical distributors losing specification influence to platform-native contracts. |
| Sensor Semiconductor Backward Integration | Reduces dependence on concentrated East Asian foundry capacity for wireless control modules. |
| Li-Fi Pilot Scale-Up | Captures defense and healthcare demand for electromagnetic interference-immune secure transmission. |
| Energy Analytics Platform Licensing | Converts hardware-centric sales to recurring software revenue with utility rebate capture documentation. |
Study Parameters
Document review covered SEC filings from lighting and electrical infrastructure conglomerates, EU Ecodesign Directive compliance databases, and MEE dual carbon policy briefs, complemented by interviews with building automation engineers, ESCO procurement directors, electrical contractor project managers, and commercial real estate facility managers. Secondary validation drew from EPA ENERGY STAR certified products listings, Zigbee Alliance certification registries, and German KfW energy efficiency financing disbursement records. Bottom-up deployment volume estimates triangulated against top-down building stock retrofit penetration models.
Market sizing outputs reflect segment-level projections across the analysis window, with technology protocol, installation type, and end-user vertical as core segmentation dimensions. CAGRs derived from regression against historical retrofit cycle timing, regulatory mandate enforcement trajectories, and smart city infrastructure budget allocations. Forecast inputs incorporated semiconductor foundry capacity expansion announcements and EU F-Gas Regulation amendment pipelines.
Revisions become necessary when foundry capacity allocations shift, cybersecurity mandates for networked building systems tighten unexpectedly, or protocol interoperability standards fragment further. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Connected (Smart) Street Lighting Market
Lighting
Ultraviolet Lamps Market
Lighting
Lighting Product Market
Lighting
Solar Spotlights Market
Lighting
Global Stadium Lighting Market
Lighting
Cleanroom Lighting Market
Lighting
Photography Light Box Market
Lighting
US Indoor LED Lighting Market
Lighting
North America Smart Lighting Market
Lighting
Lighting Control Components Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Global Lighting Control System Market
Lighting
Photocell Market
Lighting
Indicator Lights Market
Lighting
Bacteriological Light Market
Lighting
Ultra Violet (UV) Lamps Market