
 System Basis Chip Market | 2026-2036
System Basis Chip Market Size, Share, and Industry Trends Forecast 2026-2036
System Basis Chip Market Outlook
Automotive-grade ASIL-D qualification is rotating from niche premium platforms to standard requirements across mid-range vehicle programs. Infineon Technologies leverages captive fab capacity in Dresden to sustain supply security for safety-critical SBC volumes. NXP Semiconductors anchors its position through integrated power management and transceiver combinations purpose-built for zonal E/E architectures. Texas Instruments competes on analog integration density, offering compact multi-rail SBCs that reduce BOM complexity for Tier-1 suppliers.
A system basis chip integrates power management, communication transceivers, and system monitoring functions into a single mixed-signal device, typically manufactured on BCD-on-SOI processes with operating junction temperatures up to 175°C to withstand under-hood automotive environments. Its primary purpose is to reduce external component count while ensuring reliable wake-up, voltage regulation, and network interfacing for electronic control units. Ethernet-based SBCs are capturing the fastest growth trajectory as automakers deploy 100BASE-T1 and 1000BASE-T1 zones for software-defined vehicle backbones, while LIN and legacy CAN segments retain volume dominance in body control modules where cost sensitivity limits technology migration. ISO 26262 compliant variants command concentrated margin pools due to qualification barriers and traceability requirements that lock in supplier relationships across vehicle program lifecycles.
FDA oversight of automotive-grade semiconductor reliability testing intersects with EPA fuel efficiency mandates that drive ECU consolidation, both indirectly amplifying SBC demand through module integration trends. Germany's KBA enforces type approval standards that embed functional safety requirements into homologation, compelling suppliers to maintain ISO 26262 certified production lines. Japan's METI promotes domestic semiconductor resilience through supply chain restructuring incentives that favor captive SBC design capabilities. Stakeholders must monitor how regional divergence in zonal architecture standards reshapes transceiver technology roadmaps and qualification investment priorities.
Market Dynamics
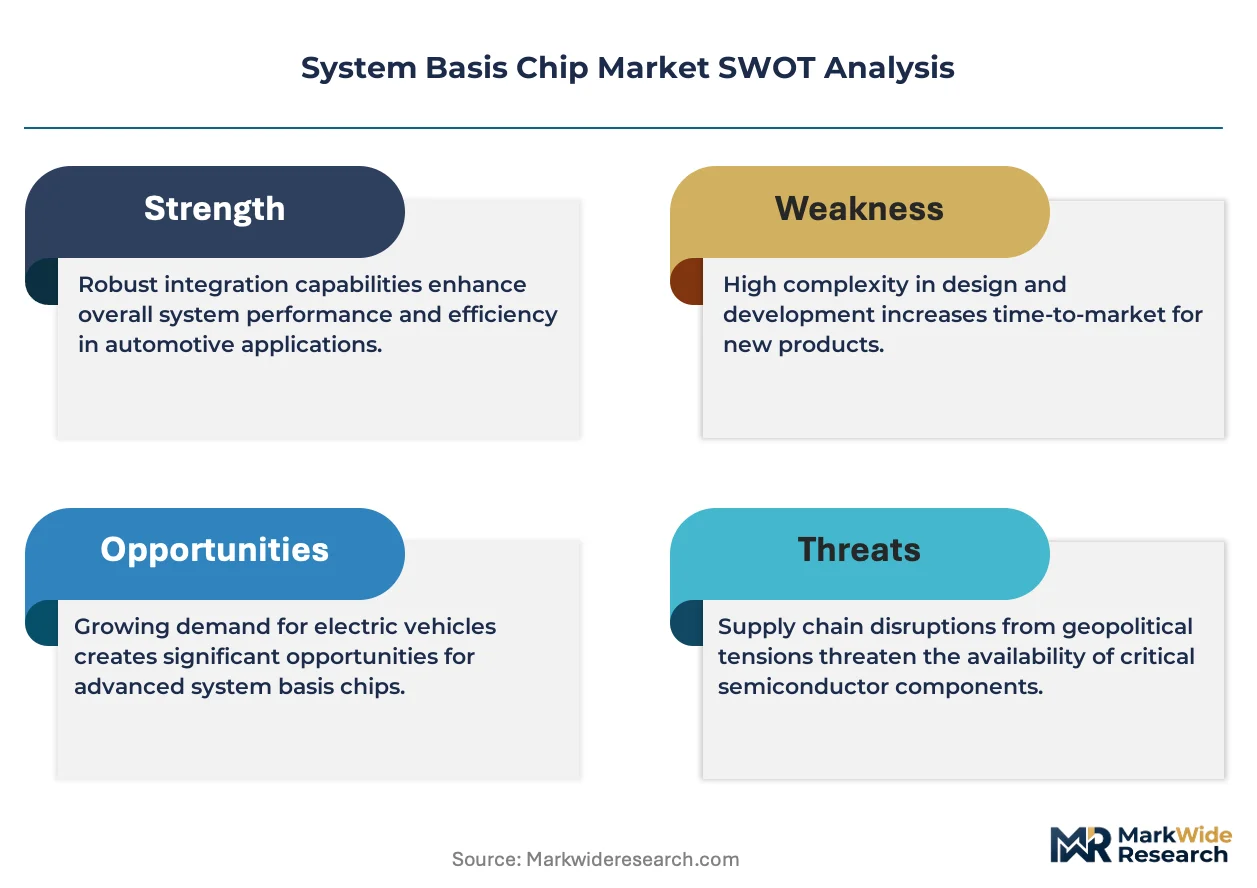
The automotive industry's pivot from distributed ECU architectures to centralized domain controllers is compressing component counts while elevating functional safety requirements for every remaining semiconductor node. This structural consolidation simultaneously reduces unit volumes per vehicle and increases value-per-chip, reshaping supplier economics across the SBC value chain.
Growth Catalysts
- ISO 26262 ASIL-D mandates:Functional safety certification has become a non-negotiable gate for SBC qualification in brake-by-wire and steer-by-wire modules, locking out uncertified competitors.
- Ethernet backbone deployment:1000BASE-T1 automotive Ethernet is displacing legacy CAN networks in zonal E/E architectures, demanding new transceiver-integrated SBC variants purpose-built for high-speed data aggregation.
- ECU consolidation wave:EPA fuel efficiency targets and packaging constraints are forcing module integration, with each consolidated node requiring more sophisticated power management and monitoring functions.
Market Restraints
- 200mm BCD-on-SOI capacity scarcity:Foundry constraints on mature-node mixed-signal processes limit SBC supply elasticity during demand spikes, with Dresden and Singapore facilities operating at committed utilization.
- ISO 26262 qualification timeline:The 18-24 month certification cycle for new SBC variants creates a structural lag between design win and revenue recognition, freezing out fast-follower strategies.
- Silicon carbide power module substitution:Discrete SiC gate drivers with integrated protection functions are capturing high-voltage applications above 800V, constraining SBC addressable market in electric powertrains.
Strategic Opportunities
- Software-defined vehicle platforms:Over-the-air update architectures require persistent wake-up and power sequencing capabilities that favor intelligent SBCs with embedded microcontrollers over discrete implementations.
- India automotive electronics corridor:Tata Motors and Mahindra's expanding EV programs lack established domestic SBC supply chains, creating first-mover advantages for qualified entrants.
- CE marking cybersecurity extension:UN R155 vehicle cybersecurity regulations are mandating hardware security modules integrated into SBCs, opening premium pricing tiers for certified variants.
Industry Challenges
- Functional safety architect scarcity:The shallow talent pool for ISO 26262 system design is elongating development timelines and inflating compensation costs for qualified engineers.
- Legacy CAN coexistence complexity:SBCs must maintain backward compatibility with 20-year-old vehicle networks while enabling Ethernet migration, multiplying validation matrices and test coverage requirements.
- Supply chain reconfiguration friction:Automaker mandates for dual-source qualification are forcing Tier-1 suppliers to validate second-source SBCs, duplicating engineering resources without incremental volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System Basis Chip Market |
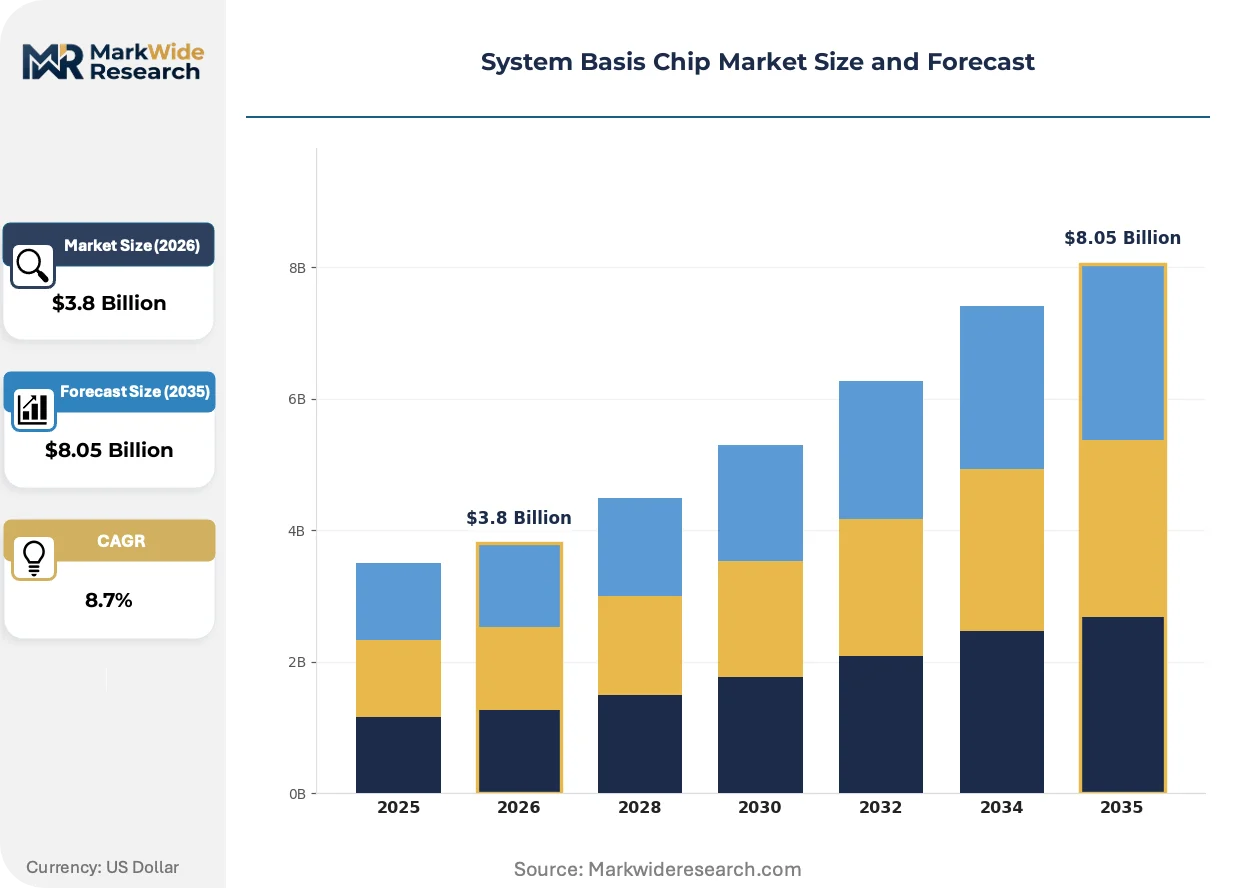
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ISO 26262 Compliant, Power Management IC, Transceiver, Microcontroller Technology: LIN, CAN, FlexRay, Ethernet End User: Automobile OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Body Control, Powertrain, Safety Systems, Infotainment |
| Companies Covered | Micron Technology Inc., Analog Devices, Robert Bosch GmbH, Infineon Technologies, Onsemi, Qualcomm Technologies Inc., Texas Instruments, NXP Semiconductors, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System Basis Chip Market Strategic Shifts
Mixed-signal integration is advancing faster than discrete scaling, with SBC architectures absorbing functions that previously required separate PMICs, transceivers, and watchdog controllers. This convergence is compressing board area and simplifying thermal management for space-constrained ECUs.
Multi-rail power management with adaptive voltage scaling is miniaturizing into single-package SBCs that sequence processor, memory, and peripheral supplies through firmware-configurable state machines. Tier-1 suppliers in Germany and Japan are adopting these compact variants for body domain controllers, collapsing BOM line items from twelve discrete components to one qualified device. The structural consequence is margin pressure on discrete PMIC specialists who lack integrated transceiver portfolios.
NHTSA's proposed updates to Federal Motor Vehicle Safety Standard 150 for automatic emergency braking are mandating deterministic latency bounds on safety-critical network traffic. This regulatory pressure is accelerating adoption of time-sensitive networking switches embedded within SBCs, with automotive OEMs demanding hardware-level IEEE 802.1Qbv time-aware shapers. The powertrain and chassis segments face the steepest compliance timelines, with 2027 model year vehicles requiring certified implementations.
Automotive OEMs are consolidating supplier panels and negotiating multi-year SBC supply agreements with indexed pricing mechanisms. Tier-1 module houses are responding by pre-qualifying second-source pin-compatible alternatives, shifting design authority from semiconductor vendors to system integrators. This pattern is most pronounced in Japan, where keiretsu relationships are formalizing into binding volume commitments with technology roadmapped through 2030.
System Basis Chip Market Segmentation
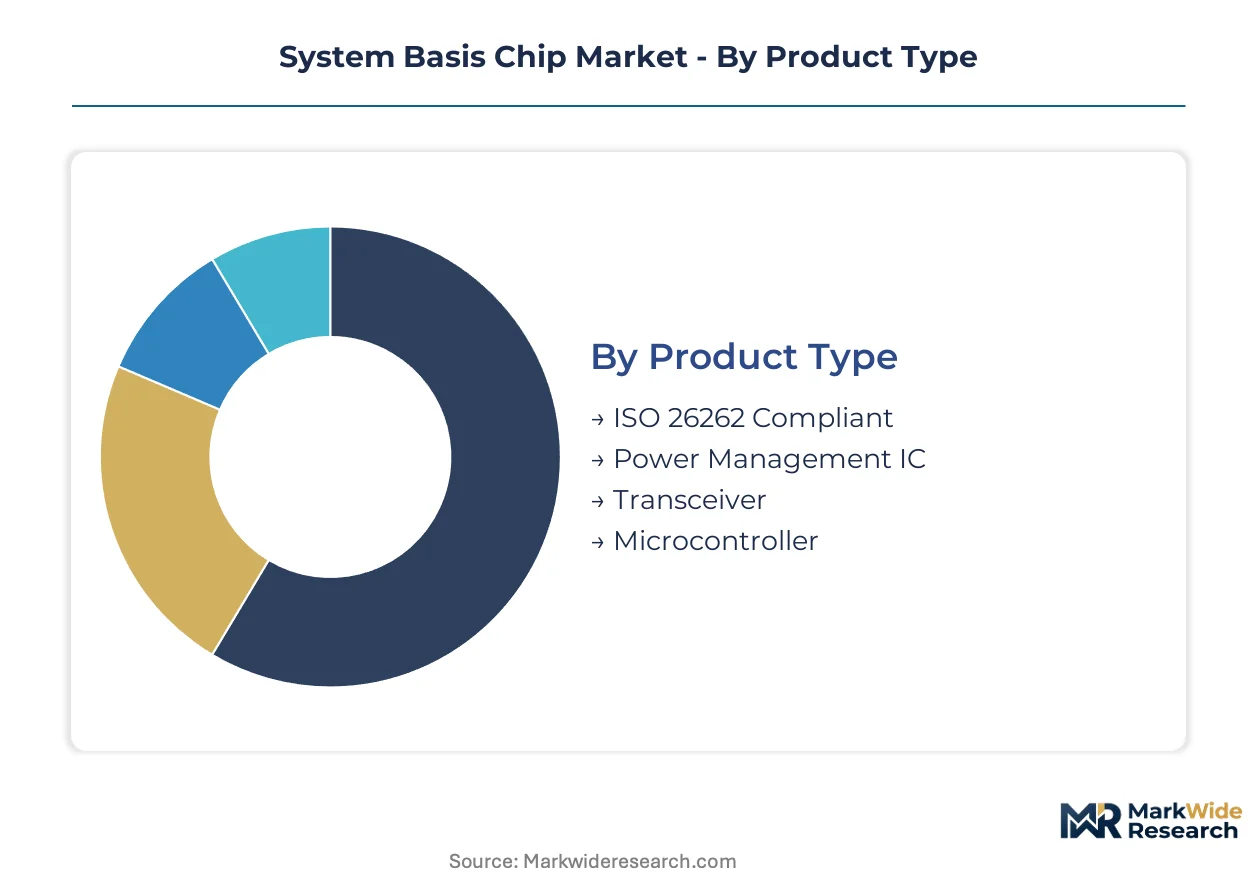
System basis chip architectures fragment across safety certification tiers, network protocols, and ECU integration levels. Segmentation discipline reveals where ASIL-D premiums concentrate versus cost-optimized legacy volumes, and which protocol transitions reshape supplier positioning.
Product Type:
Discrete power management ICs face the strongest substitution pressure as integrated SBCs absorb their functions into single-package solutions.
- ISO 26262 Compliant:ASIL-D certified variants integrate redundant voltage monitoring, watchdog timers, and failure-mode diagnostics for brake-by-wire and steer-by-wire modules. German OEMs mandate these for chassis domain controllers where functional safety gates lock out uncertified alternatives.
- Power Management IC:Standalone PMICs persist in body control modules where cost sensitivity outweighs integration benefits, though their addressable market contracts as multi-rail SBCs capture sequencing functions. Tier-1 suppliers in Japan continue specifying discrete PMICs for legacy platform continuity.
- Transceiver:CAN FD and Ethernet PHY integration into SBCs is collapsing standalone transceiver demand in zonal architectures.
- Microcontroller:Embedded MCU cores within intelligent SBCs enable persistent wake-up and power state management for software-defined vehicle platforms.
ISO 26262 Compliant variants retain volume leadership; Microcontroller-integrated SBCs hold the steepest expansion curve.
Technology:
Protocol migration intensity varies by vehicle electrical zone, with backbone networks demanding faster transceivers than body electronics.
- Ethernet:100BASE-T1 and 1000BASE-T1 automotive Ethernet SBCs aggregate sensor data across zonal E/E architectures. US OEMs deploying software-defined vehicle platforms specify these for central compute nodes requiring deterministic latency bounds.
- CAN:CAN FD variants maintain dominance in powertrain and chassis modules where backward compatibility with 20-year-old vehicle networks remains mandatory. German Tier-1 suppliers validate dual-protocol SBCs to bridge legacy and next-generation fleets.
- LIN:Cost-optimized LIN SBCs serve door modules and seat controllers where data rates below 20 kbps suffice.
- FlexRay:Deterministic timing applications in adaptive suspension systems preserve niche demand despite Ethernet encroachment.
CAN retains protocol volume leadership; Ethernet climbs the fastest as zonal architectures displace distributed ECU networks.
End User:
Procurement authority is shifting from semiconductor vendors to system integrators as Tier-1 suppliers consolidate supplier panels.
- Automobile OEMs:Direct SBC procurement concentrates among German, Japanese, and US manufacturers designing domain controller architectures in-house. These OEMs negotiate multi-year supply agreements with indexed pricing and technology roadmaps extending through 2030.
- Tier-1 Suppliers:Continental, Bosch, and Denso dominate module-level SBC specification, pre-qualifying second-source pin-compatible alternatives to satisfy automaker dual-source mandates.
- Aftermarket Providers:Repair and retrofit channels source legacy CAN and LIN SBCs for vehicle service life extension.
- Vehicle Assemblers:Contract manufacturers in emerging automotive corridors import qualified SBCs through established Tier-1 supply chains.
Tier-1 Suppliers control specification authority; Automobile OEMs are expanding direct procurement fastest as domain architectures consolidate.
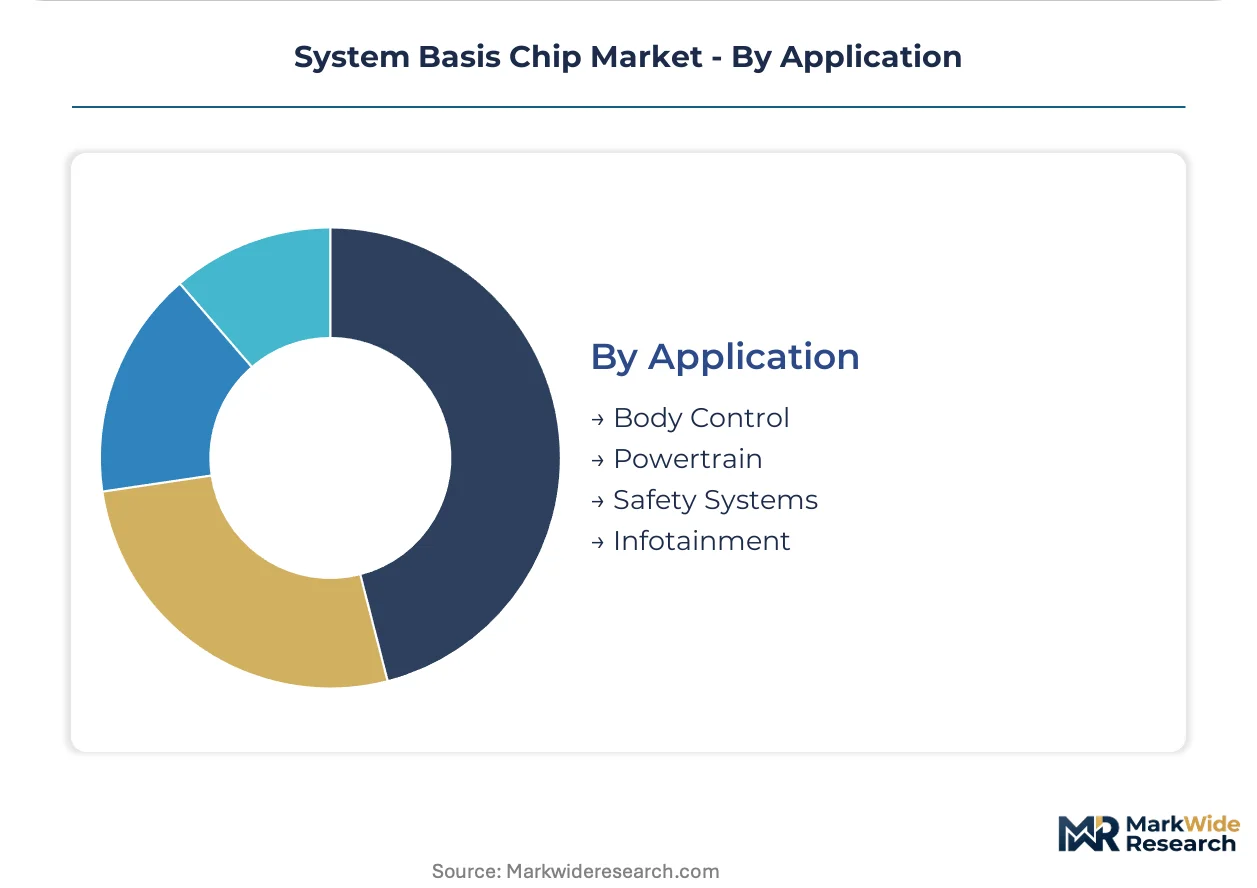
Application:
Safety-critical segments command qualification premiums while infotainment tolerates consumer-grade component substitution.
- Safety Systems:ASIL-D SBCs for automatic emergency braking and lane-keeping assistance require deterministic latency and fail-silent behavior. NHTSA proposed rulemaking on FMVSS 150 compliance is accelerating hardware-level time-sensitive networking adoption.
- Powertrain:Engine control and transmission modules demand 175°C junction temperature tolerance and load-dump protection, specifications that filter out non-automotive qualified suppliers.
- Body Control:Door, seat, and climate modules prioritize cost-optimized LIN and legacy CAN SBCs with minimal functional safety requirements.
- Infotainment:Ethernet SBCs for display and connectivity modules face competition from consumer-grade networking chips with relaxed automotive qualification.
Body Control retains application volume leadership; Safety Systems expand most quickly on regulatory mandate intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
System basis chip trade flows reveal persistent import dependence in automotive electronics corridors lacking captive fab capacity. Export strength concentrates where BCD-on-SOI process expertise and ISO 26262 certification infrastructure overlap.
Germany
Dresden anchors European SBC supply security through captive 200mm mixed-signal capacity serving Bosch and Continental module programs. KBA type approval standards embed functional safety into vehicle homologation, compelling suppliers to maintain certified production lines. Bavaria's automotive electronics cluster around Munich drives specification authority for ASIL-D variants in chassis domain controllers.
United States
Detroit-area OEMs and Austin semiconductor design centers shape demand for Ethernet-integrated SBCs in software-defined vehicle platforms. NHTSA proposed updates to FMVSS 150 mandate deterministic latency bounds on safety-critical network traffic, accelerating hardware-level time-sensitive networking adoption. The Southeast automotive corridor imports qualified SBCs through established Tier-1 supply chains lacking domestic mixed-signal fabrication.
Japan
Nagoya and Tokyo metropolitan areas concentrate Tier-1 module specification authority through keiretsu relationships formalizing multi-year volume commitments. METI promotes domestic semiconductor resilience through supply chain restructuring incentives favoring captive SBC design capabilities. Toyota City and surrounding industrial zones specify intelligent SBCs with embedded microcontrollers for persistent wake-up functions.
China
Shanghai and Yangtze River Delta automotive electronics clusters drive procurement for body control modules where cost-optimized LIN SBCs dominate. MIIT industrial policy accelerates local qualification of automotive-grade mixed-signal devices to reduce import dependence for safety-critical applications. Domestic OEMs in Shenzhen and Guangzhou specify Ethernet SBCs for zonal architectures in premium EV platforms.
India
Maharashtra and Tamil Nadu automotive corridors lack established domestic SBC supply chains as Tata Motors and Mahindra expand EV programs. BIS automotive electronics standards are evolving to incorporate functional safety requirements, creating qualification barriers for uncertified imports. Chennai and Pune manufacturing zones rely on Tier-1 imports for domain controller modules.
System Basis Chip Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and certification depth. The vendor base stratifies between diversified semiconductor conglomerates with captive automotive divisions and focused mixed-signal specialists serving niche safety-critical applications. Three archetypes dominate: integrated device manufacturers with BCD-on-SOI fab ownership, fabless design houses licensing automotive-qualified IP, and Tier-1 module suppliers backward-integrating into SBC specification. Competitive positioning hinges on multi-year supply agreements with indexed pricing and dual-source qualification mandates from automakers.
Within the integrated device manufacturer tier, Infineon Technologies and NXP Semiconductors exemplify archetypes combining captive fabrication with ASIL-D certification portfolios. Texas Instruments occupies a position emphasizing analog integration density for compact multi-rail implementations. These three entities represent distinct strategic postures: European fab ownership with regional supply chain anchoring, mixed-signal integration leadership through transceiver-power management combinations, and analog-centric miniaturization for BOM complexity reduction.
| Leading Market Players |
|---|
| Micron Technology Inc. |
| Analog Devices |
| Robert Bosch GmbH |
| Infineon Technologies |
| Onsemi |
| Qualcomm Technologies Inc. |
| Texas Instruments |
| NXP Semiconductors |
| Broadcom Inc. |
| Others |
Value Chain & Pricing Dynamics
Discrete PMIC substitution by integrated SBCs simultaneously redistributes supply geography toward BCD-on-SOI fabrication hubs and compresses pricing premiums for standalone power management components. German Tier-1 suppliers leverage captive Dresden capacity to secure ASIL-D qualified volumes while Asian module houses absorb cost-optimized LIN variants from Singapore foundries.
Pricing Analysis
Automotive OEM buyers anchor a contract-based long-term offtake pricing structure with indexed volume commitments extending through multi-year vehicle programs. Price differentiation separates ISO 26262 ASIL-D certified variants from consumer-grade alternatives based on qualification depth and traceability infrastructure. Cost compression in body control modules is intensifying because Tier-1 suppliers pre-qualify pin-compatible second sources to satisfy dual-source mandates. Aftermarket channels exhibit the highest price sensitivity, while chassis domain controller procurement tolerates premium positioning for fail-silent behavior guarantees.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery windows for European module assembly operations. BCD-on-SOI wafer supply concentrates in Germany, Singapore, and the United States, with 200mm capacity scarcity feeding from specialized automotive mixed-signal foundries. Raw material dependencies include SOI wafers, copper interconnects, and automotive-grade epoxy mold compounds. Single-source vulnerability around ISO 26262 certified production lines presents structural risk. Distribution runs through Tier-1 module houses rather than direct OEM procurement for legacy platform volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The System Basis Chip Market exhibits cyclical recovery characteristics driven by automotive production normalization following supply chain destocking. Inventory restocking across German and Japanese OEM programs is amplifying demand visibility for qualified SBC volumes.
For Market Incumbents: Fortify ASIL-D certification portfolios through captive fab investment in Dresden and Singapore to lock out fast-follower competition. Expand backward integration into BCD-on-SOI process development to secure capacity allocation during demand spikes. Silicon carbide power module substitution in 800V electric powertrains threatens high-voltage SBC addressable market.
For New Entrants and Emerging Players: ISO 26262 certification fast-track partnerships with German TÜV bodies enable qualification timeline compression for brake-by-wire module design wins. Target India's emerging automotive electronics corridor where Tata Motors and Mahindra lack established domestic SBC supply chains. Pursue joint development agreements with Tier-1 suppliers seeking second-source validation for zonal architecture programs.
For Investors and Strategic Acquirers: Capital is best deployed toward fabless design houses with automotive-qualified IP portfolios and established OEM design win traction. The five-to-ten year viability window favors entities combining Ethernet transceiver expertise with power management integration capabilities. Monitor NHTSA FMVSS 150 rulemaking finalization as inflection indicator for time-sensitive networking hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Locks out uncertified competitors from brake-by-wire and steer-by-wire module procurement. |
| Ethernet-Integrated SBC Development | Captures zonal architecture migration as 1000BASE-T1 displaces legacy CAN backbone networks. |
| India Manufacturing Footprint | Establishes first-mover position in Tata Motors and Mahindra expanding EV programs. |
| Second-Source Qualification Partnership | Satisfies automaker dual-source mandates while duplicating engineering validation resources. |
| Cybersecurity Hardware Module Integration | Opens premium pricing tiers under UN R155 vehicle cybersecurity regulation compliance. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, automotive semiconductor foundry operations managers, and aftermarket distribution channel heads; and secondary validation through SEC semiconductor filings, vehicle production databases, IHS Markit registration data, and ISO 26262 certification registry records. Bottom-up bill-of-materials modeling across ECU consolidation scenarios was triangulated against top-down automotive electronics spending forecasts.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning safety certification tier, network protocol type, ECU integration level, vehicle propulsion architecture, and regional production cluster. CAGRs were derived from vehicle program launch timelines and content-per-vehicle trajectories. Forecast inputs included semiconductor foundry capacity utilization disclosures and OEM domain controller architecture transition roadmaps.
The analysis sits within stated boundaries; outcomes outside sustained automotive production volumes, stable BCD-on-SOI capacity expansion, and unchanged ISO 26262 qualification timelines would require recalibration. Forecasts reflect documented assumptions regarding zonal architecture adoption rates and Ethernet backbone deployment schedules. Supply chain reconfiguration friction, functional safety architect scarcity, and legacy CAN coexistence complexity present specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
4D Radar Chip Market