
 CMOS Camera Market | 2026-2036
CMOS Camera Market Size, Share, and Industry Trends Forecast 2026-2036
CMOS Camera Market Analysis
The capital-intensity divergence between foundry-dependent and IDM-capable players is rotating competitive advantage toward vertically integrated manufacturers. Sony Semiconductor Solutions Corporation leverages captive wafer capacity to sustain pricing power in high-resolution mobile sensors. Samsung Electronics anchors supply for its internal smartphone division while competing for external foundry contracts. OmniVision Technologies specializes in compact-form-factor designs for automotive and medical niches.
A CMOS camera converts photons into electrical signals through an active-pixel sensor array fabricated on complementary metal-oxide-semiconductor substrates, typically achieving sensitivity below one lux for low-light operation and frame rates exceeding 120 fps in consumer configurations. Its primary commercial purpose spans image acquisition for computational photography, machine vision, and environmental sensing. Smartphone cameras dominate unit volume but compress margin pools, while industrial cameras command premium pricing through global shutter configurations that eliminate motion artifacts in automated inspection. Automotive systems represent the fastest-growing application as OEMs mandate multi-camera surround-view architectures for regulatory compliance.
FDA 510(k) pathways govern medical imaging subsystems in the US, while the EU AI Act imposes conformity requirements on vision-based decision systems deployed in European markets. REACH restrictions on hazardous substances in semiconductor packaging affect material selection across the supply chain. Stakeholders must monitor evolving automotive functional-safety standards and regional content mandates that could disqualify non-compliant sensor suppliers from qualified vendor lists.
Market Dynamics
Automotive ADAS mandates are forcing a step-change in sensor deployment density, with OEMs specifying multi-camera surround-view architectures as baseline equipment rather than premium options. This regulatory pull is compressing development cycles and redrawing supplier qualification criteria across passenger and commercial vehicle platforms.
Growth Catalysts
- EU AI Act conformity requirements:Vision-based decision systems deployed in European markets must now meet standardized certification protocols, creating certified-supplier premiums for compliant CMOS module manufacturers.
- China's industrial automation investments:Domestic smartphone OEM supply chain concentration and accelerating factory robot deployment are concentrating demand for compact, high-frame-rate sensors.
- Stacked backside-illuminated architectures:Advanced pixel designs achieving sub-lux sensitivity are expanding addressable use cases into medical endoscopy and nighttime automotive perception.
Market Restraints
- 300mm wafer supply concentration:Captive foundry capacity at leading IDMs limits second-source options for fabless design houses, concentrating pricing power with vertically integrated manufacturers.
- REACH substance restrictions:ECHA limitations on hazardous materials in semiconductor packaging constrain material selection for lead-free solder and mold compounds, elevating qualification costs.
- Global shutter cost premium:Industrial inspection applications requiring motion-artifact elimination face 3-4x unit cost multiples versus rolling-shutter consumer variants, capping addressable volume.
Strategic Opportunities
- Underpenetrated medical imaging subsystems:FDA 510(k) pathway familiarity gaps among consumer-oriented sensor suppliers create entry white space for dedicated healthcare CMOS platforms.
- Event-based sensor convergence:Integration of asynchronous dynamic vision sensors with conventional frame-based architectures enables sub-millisecond latency for robotic manipulation and drone navigation.
- India PLI scheme incentives:Production-linked incentive structures for electronics manufacturing are attracting module assembly investments to serve domestic smartphone and automotive demand.
Industry Challenges
- Automotive functional-safety certification timelines:ISO 26262 ASIL-B through ASIL-D qualification cycles extend 18-24 months, delaying revenue recognition for new sensor platforms.
- Image signal processor IP fragmentation:Proprietary color-science pipelines and auto-focus algorithms lock customers into incumbent suppliers, elevating switching costs for second-source qualification.
- Legacy fleet integration complexity:Retrofit ADAS installations in commercial vehicles require mechanical packaging adaptations and CAN-bus protocol bridging that compress margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMOS Camera Market |
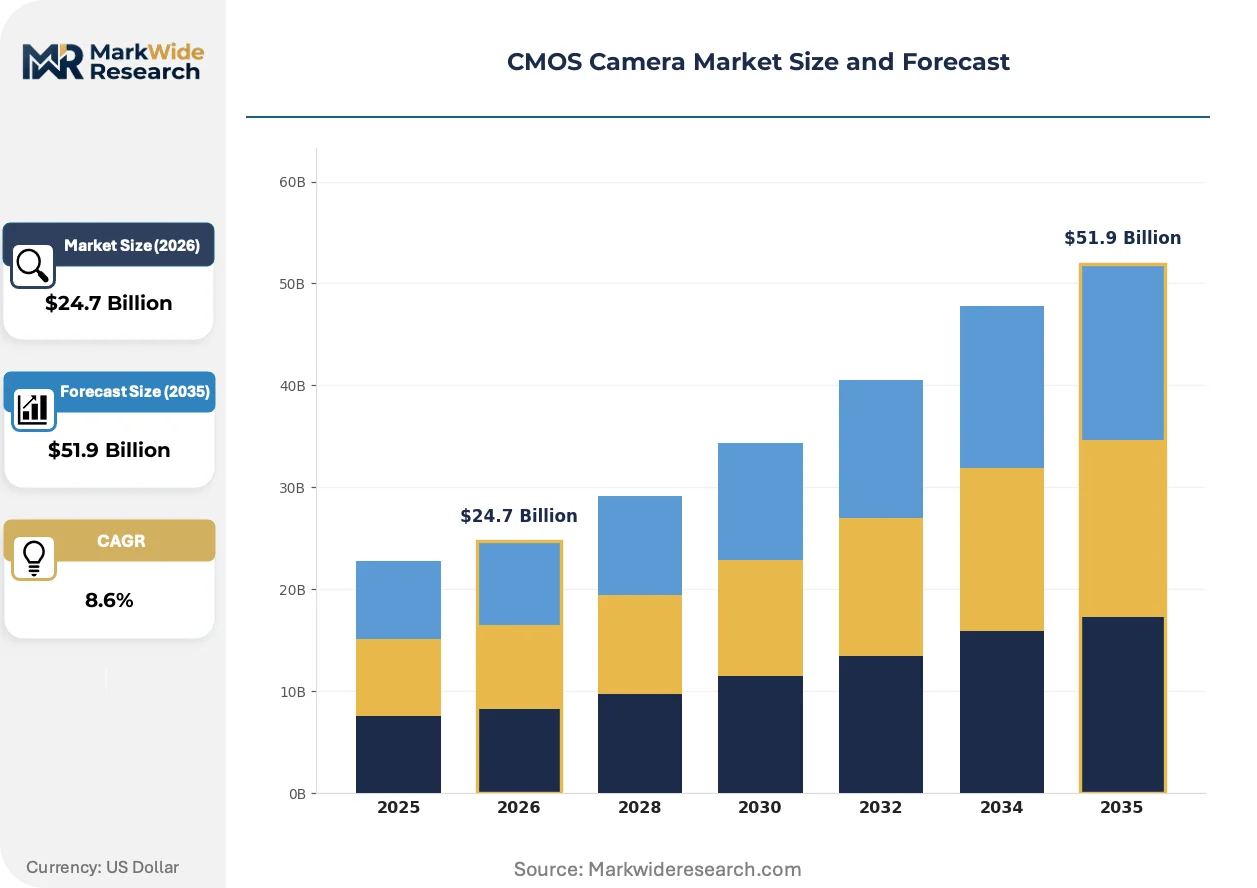
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Cameras, Smartphone Cameras, Embedded Cameras, Industrial Cameras Application: Surveillance, Mobile Photography, Automotive Systems, Medical Imaging End User: Retailers, Manufacturers, Consumers, Healthcare Providers Technology: Global Shutter, Rolling Shutter, Near Infrared, Foveon |
| Companies Covered | Sony Semiconductor Solutions Corporation, Samsung Electronics, OmniVision Technologies, Canon, STMicroelectronics, SK Hynix, GalaxyCore, ON Semiconductor, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMOS Camera Market Emerging Trajectories
Computational photography pipelines are migrating from application processors into sensor-integrated ISPs, redistributing value capture toward CMOS die-level integration. This architectural shift is compressing the traditional camera module supply chain while elevating firmware differentiation.
Stacked CMOS architectures with pixel-level memory are displacing conventional planar sensors in flagship smartphone and automotive applications. Tier-1 automotive suppliers have accelerated adoption timelines from 48-month to 24-month qualification cycles for these designs. The technology is displacing mid-tier rolling-shutter sensors in surround-view camera positions where dynamic range requirements now exceed 120dB.
EU AI Act algorithmic transparency mandates are imposing documentation burdens on vision-system deployers using European-trained machine-learning models. Industrial consequence includes mandatory conformity assessments for embedded imaging systems making safety-critical decisions. Medical and autonomous vehicle segments are responding by pre-certifying sensor subsystems to reduce downstream system-integration risk.
Buyer concentration among top-five smartphone OEMs has compressed component sourcing to annual framework agreements with quarterly price-down schedules. Direct procurement from sensor designers is replacing module-house intermediation in high-volume programs. This pattern is most visible in China and South Korea, where captive supply relationships dominate flagship product planning cycles.
CMOS Camera Market Segmentation
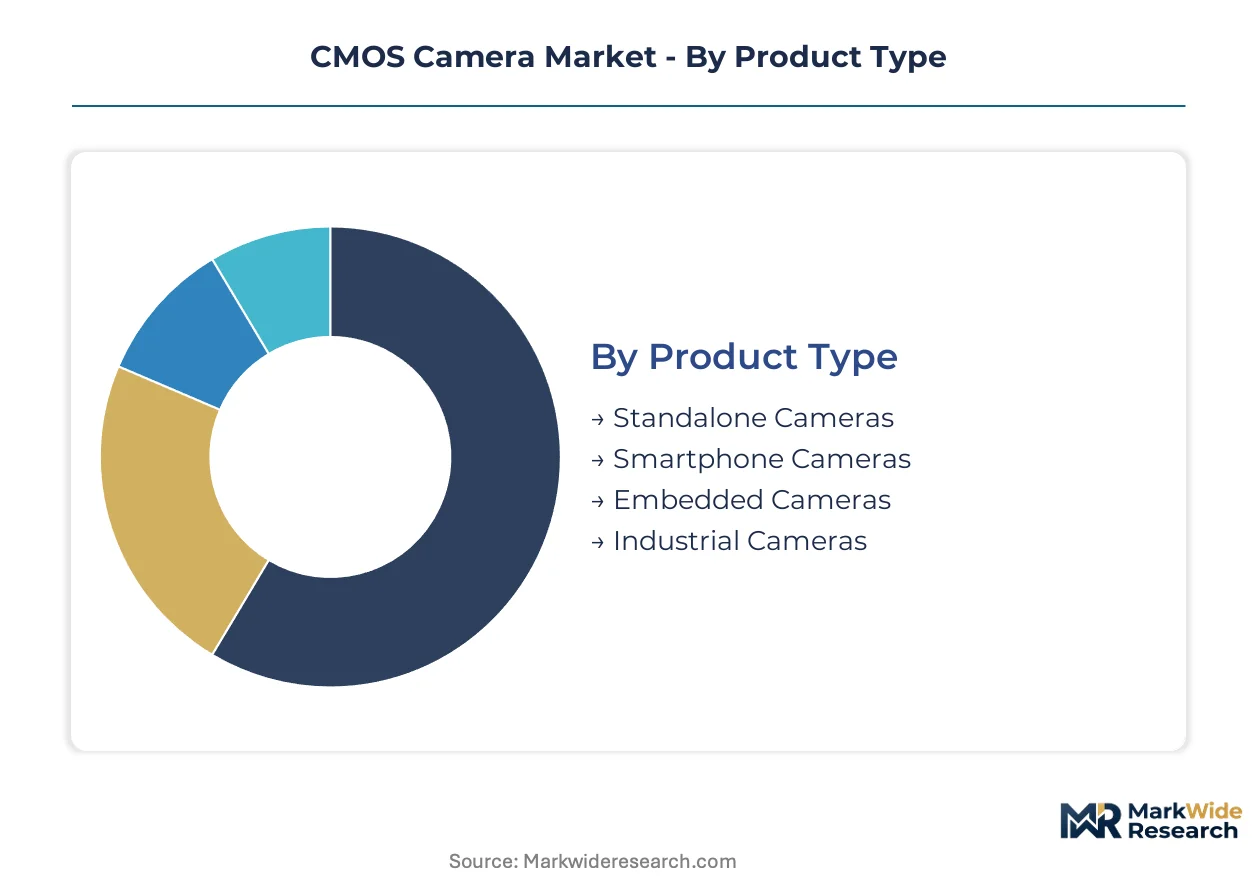
Segmentation in CMOS cameras reveals how technical specifications diverge across price-performance tiers. Each dimension—product form, application environment, buyer type, and pixel architecture—carries distinct supply chain and margin implications.
Product Type:
Domestic demand in China and South Korea concentrates on smartphone-integrated modules, while European and North American procurement tilts toward industrial and standalone variants for automation and security infrastructure.
- Standalone Cameras:Modular units with interchangeable optics and independent power management serve surveillance networks and content creation workflows. Demand clusters in Germany and the United Kingdom for smart city deployments, constrained by GDPR-compliant data handling requirements.
- Smartphone Cameras:Compact sensor-lens assemblies with fixed focal lengths dominate unit economics through billion-scale annual shipments. Chinese OEM supply chains absorb the majority of wafer output, with tier-1 flagships specifying stacked backside-illuminated designs.
- Embedded Cameras:Miniaturized modules for IoT gateways and robotics integrate fixed-focus optics with MIPI interfaces.
- Industrial Cameras:Ruggedized housings with PoE connectivity and hardware triggering support automated optical inspection lines.
Smartphone cameras command the established base. The steepest expansion runs through industrial cameras.
Application:
Cost tier stratification separates consumer-grade rolling-shutter implementations from premium global-shutter and near-infrared configurations in regulated environments.
- Surveillance:Fixed-position and PTZ architectures with wide dynamic range and low-light sensitivity secure perimeter monitoring and retail analytics. Deployment concentrates in urban China and the United Arab Emirates, where MOHAP safety certifications govern public-space installations.
- Mobile Photography:Computational photography pipelines leverage multi-sensor arrays for portrait segmentation and night-mode fusion. Flagship devices from South Korean and Chinese OEMs specify the most advanced pixel densities.
- Automotive Systems:ASIL-rated sensors for surround-view and forward-facing ADAS face ISO 26262 qualification cycles extending 18-24 months.
- Medical Imaging:Sterilizable endoscope modules and dermatology cameras require FDA 510(k) or CE-MDR conformity.
Mobile photography absorbs the highest wafer volume. Automotive systems are climbing the fastest.
End User:
Volume concentration sits with consumer-facing channels, while margin accretion concentrates in B2B procurement with certification requirements and long-term service contracts.
- Retailers:Security infrastructure buyers specify IP camera networks with edge analytics and cloud management platforms. Procurement frameworks in France and Spain emphasize ANSM-compliant data governance for customer-facing analytics.
- Manufacturers:Factory automation teams source global-shutter sensors for defect detection and robotic guidance. German automotive suppliers and Japanese electronics assemblers drive specification intensity.
- Consumers:Smartphone and action-camera purchasers prioritize megapixel marketing and social-media workflow integration.
- Healthcare Providers:Hospital systems and outpatient clinics demand ISO 13485-traceable supply chains for diagnostic and surgical imaging subsystems.
Manufacturers anchor the premium tier. Healthcare providers are gaining share fastest.
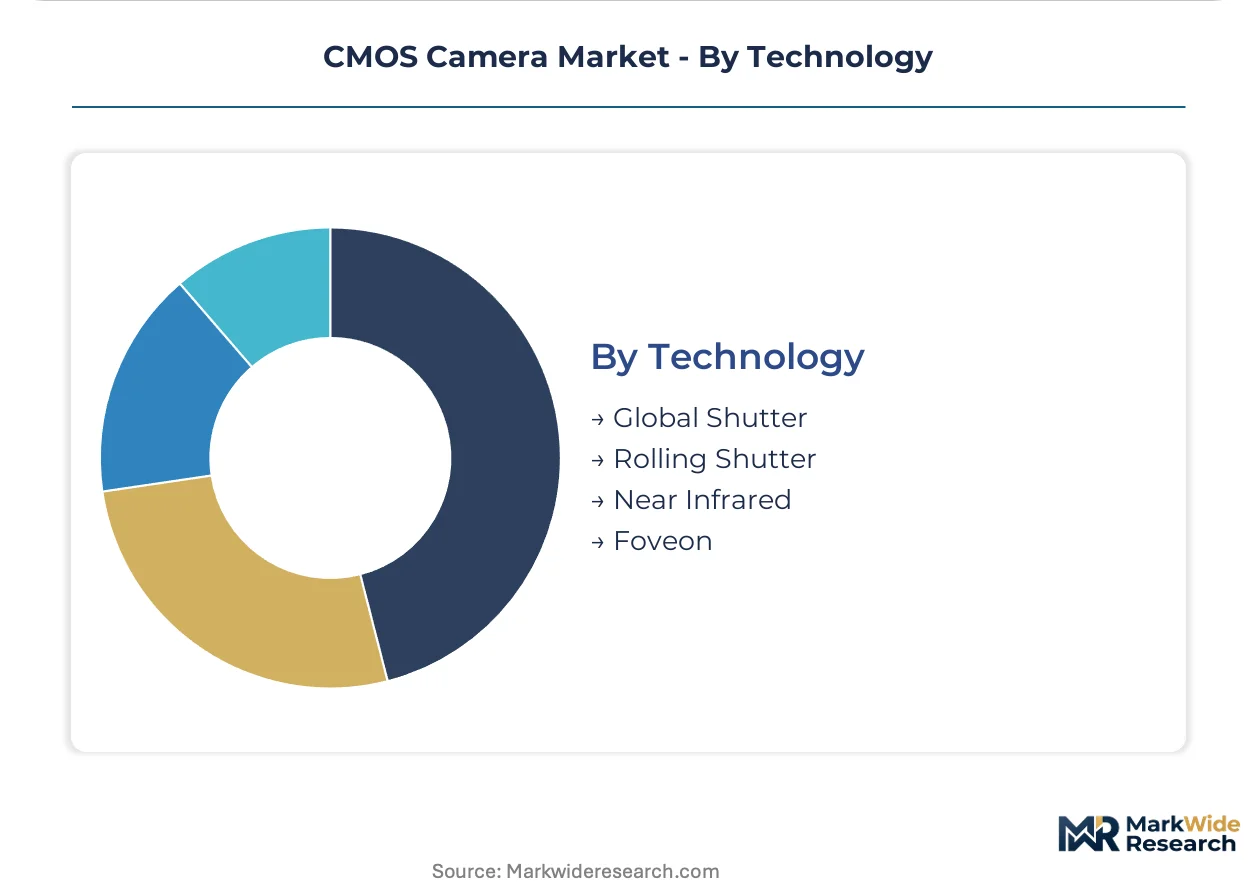
Technology:
Supply concentration for advanced architectures favors IDMs with captive wafer capacity, while rolling-shutter designs remain accessible through foundry partners.
- Global Shutter:Simultaneous pixel readout eliminates motion artifacts through storage nodes at each photosite. Industrial inspection and drone navigation in Japan and Germany specify these sensors despite 3-4x cost premiums over rolling-shutter alternatives.
- Rolling Shutter:Sequential row-by-row readout enables simpler pixel designs and higher fill factors for consumer applications. Chinese smartphone OEMs and Indian PLI-scheme assemblers absorb the majority of supply.
- Near Infrared:Extended spectral sensitivity beyond 700nm supports night vision and biometric authentication.
- Foveon:Stacked photodiode layers capture color at each spatial location without Bayer demosaicing.
Rolling shutter sensors command the established base. Global shutter configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Japanese and South Korean IDMs commanding wafer supply, while Chinese module assemblers operate on compressed margins. European industrial demand absorbs premium global-shutter sensors at 3-4x cost multiples. Indian PLI-scheme incentives are attracting assembly investments to serve domestic smartphone and automotive OEMs.
United States
Automotive ADAS mandates from NHTSA and state-level autonomous vehicle testing frameworks drive sensor procurement for Detroit-based OEMs and Silicon Valley robotaxi developers. FDA 510(k) pathways govern medical imaging subsystems, creating certification barriers for consumer-oriented suppliers. Austin and Phoenix anchor emerging LiDAR-camera fusion clusters for next-generation perception stacks.
China
Domestic smartphone OEM supply chains concentrate demand for compact, high-frame-rate sensors while MIIT industrial automation directives accelerate factory robot deployment. GB standards and SAMR market access rules shape local certification requirements. Shenzhen and Dongguan module houses dominate global assembly output through vertically integrated component ecosystems.
Germany
KBA automotive functional-safety requirements and ISO 26262 ASIL-D qualification protocols govern sensor deployment in Stuttgart and Munich premium vehicle platforms. REACH substance restrictions from ECHA constrain lead-free solder and mold compound selection. Stuttgart-Ostfildern and Ingolstadt host Tier-1 supplier engineering centers specifying surround-view architectures.
Japan
METI semiconductor industrial policy and PMDA medical device regulations shape dual-use sensor development for endoscopy and factory automation. JIS standards govern industrial camera interoperability. Kyushu and Nagoya manufacturing clusters sustain captive wafer capacity for high-resolution mobile and automotive pixel designs.
South Korea
MFDS medical device registration and internal smartphone division procurement anchor demand for stacked backside-illuminated architectures. Government semiconductor R&D subsidies under the K-Semiconductor Belt initiative sustain foundry competitiveness. Pyeongtaek and Hwaseong host advanced packaging facilities serving flagship mobile sensor programs.
CMOS Camera Market Vendor Landscape
Concentration sits with vertically integrated IDMs commanding captive 300mm wafer capacity, while fabless design houses face second-source limitations. The vendor base stratifies across three tiers: scale-driven memory conglomerates with sensor divisions, dedicated imaging semiconductor specialists, and regional module assemblers serving price-sensitive volume programs. M&A activity targets ISP IP portfolios and automotive qualification expertise. Strategic partnerships between sensor designers and Tier-1 automotive suppliers compress 48-month qualification cycles to 24 months.
Within the IDM tier, Sony Semiconductor Solutions Corporation and Samsung Electronics exemplify pricing power through backward integration into wafer fabrication. OmniVision Technologies occupies a specialist position in compact-form-factor automotive and medical niches. These three anchors illustrate how competitive advantage rotates toward upstream supply control and away from pure-play design capabilities.
| Leading Market Players |
|---|
| Sony Semiconductor Solutions Corporation |
| Samsung Electronics |
| OmniVision Technologies |
| Canon |
| STMicroelectronics |
| SK Hynix |
| GalaxyCore |
| ON Semiconductor |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term wafer offtake agreements between smartphone OEMs and Japanese IDMs lock in multi-year die supply while freezing quarterly price-down schedules that compress module-house margins. These contracts anchor volume visibility for 300mm foundry capacity but expose buyers to inflexibility when automotive qualification cycles demand rapid sensor platform switches.
Pricing Analysis
The customization-premium spread between ASIL-certified automotive sensors and consumer-grade rolling-shutter modules reaches 3-4x multiples, with ISO 26262 qualification tiers and pixel-level memory architectures driving differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and captive wafer access, with fabless design houses facing the steepest cost compression. Pricing pressure stems from Chinese smartphone OEM procurement consolidation into annual framework agreements with mandatory quarterly reductions. Retail consumers exhibit highest price sensitivity through megapixel-centric purchasing, while German automotive Tier-1 suppliers accept premiums for guaranteed second-source qualification.
Supply Chain Analysis
Inventory buffers for specialty glass substrates and molded leadframes stretch 16-20 weeks, constraining rapid scaling for automotive sensor platforms facing accelerated 24-month qualification timelines. Wafer fabrication concentrates in Japan, South Korea, and Taiwan, with advanced backside-illumination processes drawing from captive 300mm capacity at IDMs rather than open foundries. Critical dependencies include silicon epitaxy, specialty optical filters, and automotive-grade mold compounds restricted under REACH substance regulations. Single-source vulnerability runs through concentrated sputtering target supply for infrared-blocking coatings. Distribution runs through Shenzhen and Dongguan module houses for smartphone programs, while European industrial demand sources directly from sensor designers for global-shutter configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CMOS camera market sits at an inflection where EU AI Act conformity mandates are forcing certified-supplier premiums faster than second-source qualification cycles can adapt. Stacked backside-illuminated architectures and event-based sensor convergence represent the technological disruption vectors reshaping competitive positioning.
For Market Incumbents: Shield automotive revenue streams by accelerating ASIL-D pre-certification of sensor subsystems ahead of Tier-1 supplier consolidation, while deepening backward integration into wafer-level optics to defend margin position against Chinese module-house verticalization. The threat of fabless design houses securing foundry partnerships for stacked architectures demands preemptive capacity reservation at 300mm facilities. For New Entrants and Emerging Players: Post-processing ISP software gaps in medical endoscopy systems create entry white space where FDA 510(k) pathway expertise among incumbent consumer suppliers remains underdeveloped. Target Indian PLI-scheme module assembly for domestic smartphone OEM qualification, leveraging tariff-advantaged positioning against Chinese competitors. Go-to-market should anchor on event-based sensor fusion for drone navigation applications where latency requirements exceed incumbent frame-based capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated IDMs with captive 300mm capacity and established automotive qualification track records, as foundry-dependent fabless players face persistent second-source limitations. The 5-10 year viability window favors manufacturers with in-house pixel design, wafer fabrication, and module assembly spanning medical and automotive end-markets. Watch for EU AI Act conformity assessment bottlenecks creating certified-supplier premiums that outpace volume growth in uncertified segments.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional-Safety Pre-Certification | ASIL-D qualification reduces downstream system-integration risk for Tier-1 suppliers under EU AI Act mandates. |
| Stacked Backside-Illumination Capacity Expansion | Captive 300mm wafer output anchors pricing power in flagship smartphone and surround-view camera programs. |
| Event-Based Sensor Fusion Development | Sub-millisecond latency integration with conventional frame architectures enables robotic manipulation and drone navigation. |
| Medical Imaging Subsystem Platform Launch | FDA 510(k) pathway familiarity creates entry white space against consumer-oriented sensor suppliers. |
| India PLI-Scheme Module Assembly Investment | Production-linked incentives attract assembly capacity to serve domestic smartphone and automotive OEM demand. |
Methodological Framework
Cross-validation between primary interviews with automotive Tier-1 procurement officers, smartphone OEM sensor platform engineers, and medical device regulatory affairs leads anchors the qualitative findings against secondary validation from SEC semiconductor filings, MIIT industrial automation directives, and FDA 510(k) submission databases. Bottom-up triangulation across wafer shipment data, module assembly bill-of-materials, and end-equipment production volumes reconciles with top-down market sizing from foundry capacity announcements and OEM specification disclosures.
Sensitivity analysis across automotive ADAS penetration scenarios, smartphone camera content-per-device assumptions, and industrial automation capex cycles tests forecast robustness throughout the projection horizon. Segmentation dimensions span product architecture, application environment, end-user procurement channel, and pixel technology tier, with CAGRs derived from equipment shipment trajectories and content-value elasticity modeling. Industry-specific inputs include ISO 26262 qualification cycle duration distributions and REACH substance restriction compliance cost curves.
Underlying assumptions cover sustained EU AI Act enforcement timelines, continued China domestic OEM supply chain concentration, and stable 300mm wafer foundry pricing, with deviation risk concentrated in automotive functional-safety certification delays and smartphone demand volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Silent Scan Technology Market
Imaging
Visualiser Market
Imaging
Global Thermal Imager Market
Imaging
Infrared Imaging Market
Imaging
Global CMOS Image Sensors Market
Imaging
Facial Recognition Machine Market
Imaging
Cooled IR Camera Market
Imaging
Global Acoustic Cameras Market
Imaging
Thermal Camera Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Automotive Compact Camera Module Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
High-Power Objective Lens Market
Imaging
Microwave Imaging Market