
 Lighting Market | 2026-2036
Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Market Intelligence
The lighting industry is restructuring around a widening split between premium connected systems and commodity replacement lamps. Signify Holding leverages its Interact platform to capture recurring software revenue in commercial buildings. Acuity Brands, Inc. anchors its position through vertical control of LED drivers and controls manufacturing. OSRAM GmbH specializes in automotive and specialty emitter chips where thermal performance commands technical premiums.
Lighting encompasses electrically powered devices that produce visible illumination through electroluminescence, gas discharge, or thermal radiation, with LED modules typically operating at 2700K-6500K correlated color temperature and 80-95 CRI for commercial applications. The technology serves to enable human visual tasks, regulate circadian rhythms in healthcare and workplace settings, and provide safety signaling in transportation infrastructure. LED product type categories now dominate volume shipments while holding the majority of value pools due to longer lifespans and higher upfront pricing. Smart lighting technology segments are expanding fastest as sensor integration and wireless protocols enable occupancy-based energy management. Fluorescent and halogen product types remain structurally mature, contracting in regions with active phase-out regulations.
Efficiency mandates from the US Department of Energy, the EU Ecodesign Directive, and China's GB standards for solid-state lighting are collectively reshaping permissible product architectures and import requirements. These frameworks accelerate obsolescence of incandescent and halogen inventories while creating compliance barriers for uncertified manufacturers. Stakeholders must monitor regulatory harmonization between efficiency standards and material restriction protocols, as RoHS and REACH amendments increasingly target rare-earth phosphors and solder alloys in LED assembly.
Market Dynamics
Regulatory phase-out mandates across multiple jurisdictions are compressing replacement cycles for legacy lighting technologies while simultaneously elevating compliance costs for manufacturers serving fragmented national certification requirements.
Growth Catalysts
- EU Ecodesign Directive:The regulation's staged bans on halogen and fluorescent sources are forcing wholesale fixture upgrades across commercial and residential building stocks, creating replacement demand that bypasses normal economic cycles.
- Smart city infrastructure:Municipal deployments of connected street lighting with embedded environmental sensors are expanding addressable hardware-per-node value beyond illumination into data services.
- GB standards for solid-state lighting:China's national efficiency benchmarks are accelerating domestic LED adoption while creating export certification templates that neighboring markets emulate.
Market Restraints
- Rare-earth phosphor supply concentration:Processing capacity for europium and terbium derivatives concentrates in limited geographic corridors, exposing LED emitter manufacturers to input volatility and strategic supply interruptions.
- REACH amendments targeting solder alloys:The European regulation's evolving material restrictions are forcing reformulation of thermal interface materials in LED module assembly, extending qualification timelines and raising unit costs.
- Incandescent nostalgia demand:Aesthetic preference for warm dimming characteristics in hospitality and residential segments sustains niche demand for technically obsolete thermal radiation sources, fragmenting product planning.
Strategic Opportunities
- Human-centric lighting in healthcare:Circadian rhythm regulation protocols are penetrating hospital and aged-care facility specifications, creating premium positioning for tunable white systems with verified melanopic efficacy.
- Li-Fi convergence with wireless infrastructure:The integration of visible light communication into building automation backbones offers channel partners recurring service revenue streams beyond hardware margins.
- India's Smart Cities Mission:Central government funding for urban digital infrastructure is concentrating procurement authority at municipal levels, enabling direct vendor relationships that bypass traditional electrical distribution hierarchies.
Industry Challenges
- Embedded systems firmware expertise:The shift toward connected luminaires requires competencies in wireless protocol stacks and cybersecurity architecture that legacy lighting engineering organizations lack.
- Multi-protocol interoperability certification:Fragmentation across Zigbee, Thread, Matter, and proprietary building automation standards forces redundant testing expenditures and SKU proliferation for products targeting integrated smart building deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Market |
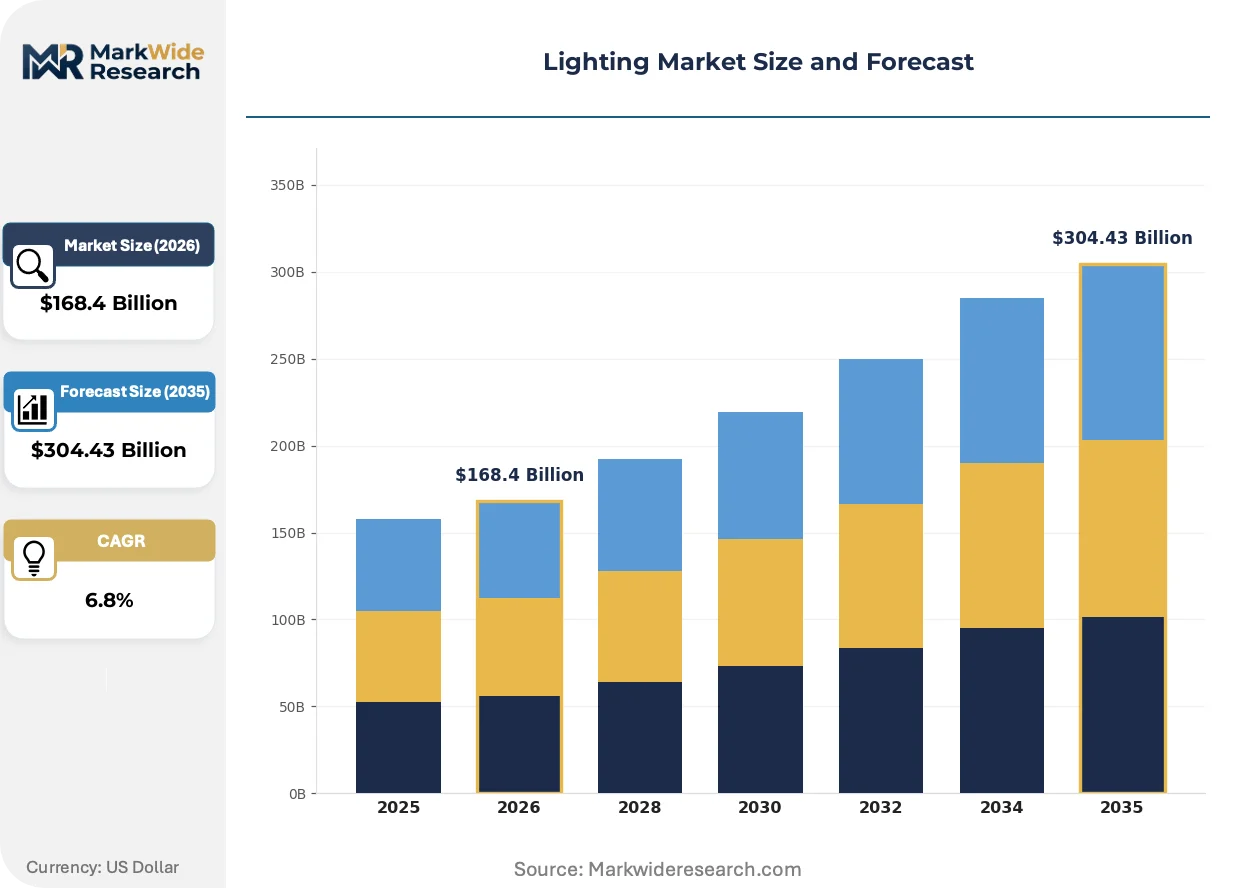
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $304.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Incandescent Application: Indoor, Outdoor, Automotive, Emergency Technology: Smart Lighting, Traditional, Solar, Dimming End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Signify Holding, Acuity Brands, Inc., OSRAM GmbH, Panasonic Holdings Corporation, Cree Lighting, GE Lighting, Eaton Corporation, Zumtobel Group, Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Market Strategic Shifts & Innovations
Power electronics miniaturization and wireless communication cost collapse are enabling illumination hardware to function as distributed sensor nodes, transforming fixture economics from capital equipment toward service-enabled platforms.
Power-over-Ethernet (PoE) lighting systems are decentralizing building-level electrical infrastructure by eliminating separate high-voltage distribution runs to each luminaire. Corporate real estate managers in North American Class A office stock are specifying PoE for new construction at accelerating rates. The technology is decentralizing the traditional division between electrical contracting and IT infrastructure deployment, compressing installation labor costs while elevating network security requirements.
The EU Green Deal's building renovation wave targets are mandating minimum efficiency thresholds for public and residential structure retrofits, with enforcement delegated to member state building codes. The policy is accelerating obsolescence of magnetic ballast fluorescent systems in commercial tenant improvements. Germany's KBA and France's national building regulators are interpreting these targets through divergent compliance timelines, creating fragmented product lifecycle planning for manufacturers.
Facility managers are unbundling lighting maintenance from comprehensive mechanical service contracts, creating standalone procurement for predictive replacement and remote diagnostics subscriptions. The behavior is disrupting traditional electrical distributor service revenue models in United States metropolitan markets. Healthcare and education verticals exhibit the strongest unbundling momentum, driven by capital budget separation between facilities and IT departments.
Lighting Market Segmentation
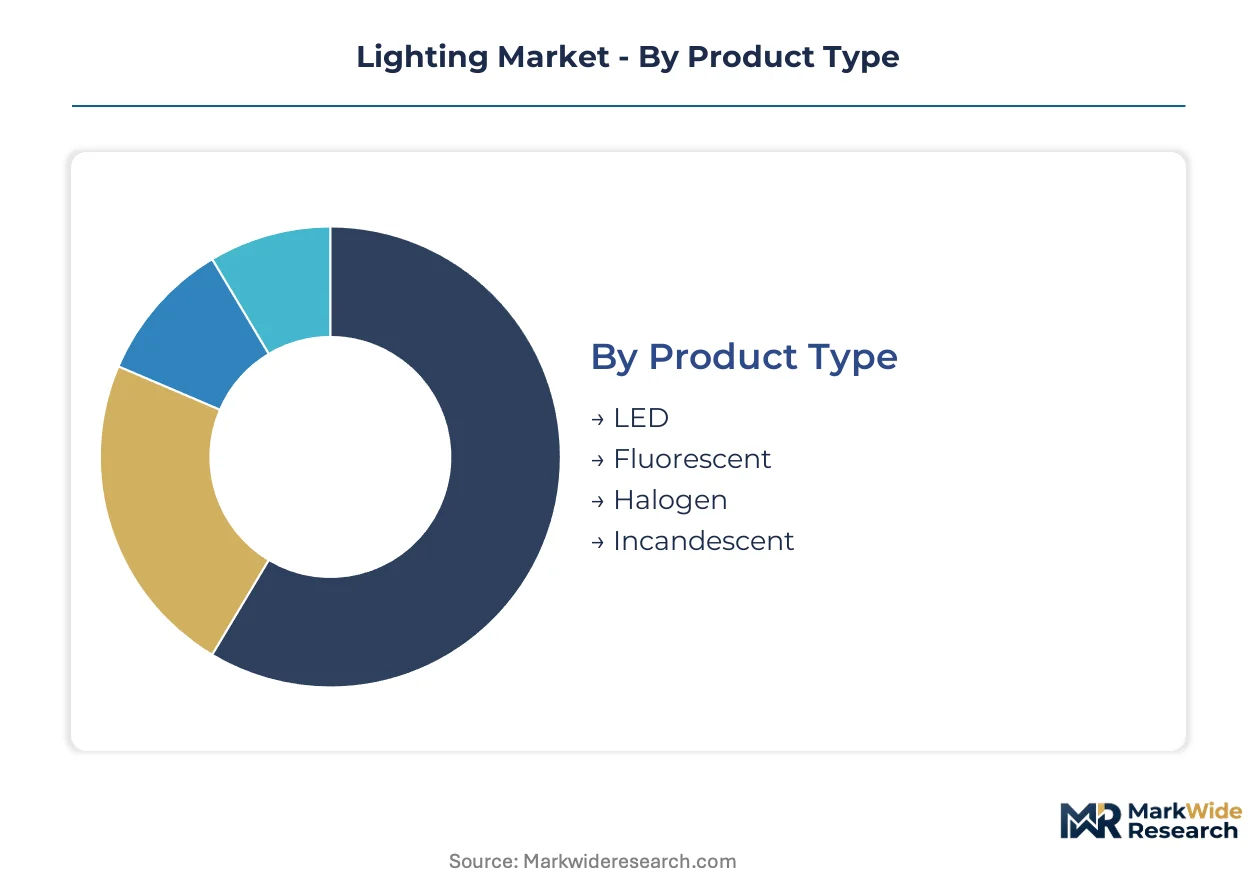
Lighting market segmentation reveals divergent margin profiles across hardware categories. Product architecture choices determine compliance burden, replacement cadence, and recurring revenue potential for fixture manufacturers.
Product Type:
Volume concentrates in LED modules while premium pricing persists in legacy specialty emitters.
- LED:Solid-state emitters operating at 2700K-6500K correlated color temperature with 80-95 CRI ratings. Demand concentrates in China's commercial building retrofits as GB standards enforcement accelerates fixture replacement timelines. The technology commands upfront premiums against operational savings from extended lifespans.
- Fluorescent:Gas-discharge sources utilizing mercury vapor excitation of phosphor coatings. Procurement persists in India's municipal infrastructure where budget constraints delay LED conversion programs. Regulatory phase-outs in the European Union and United States compress remaining commercial viability windows.
- Halogen:Tungsten-filament thermal radiation sources with iodine regenerative cycles. Niche demand sustains in hospitality dimming applications where aesthetic warmth overrides efficiency metrics.
- Incandescent:Simple resistive heating of tungsten filaments. Collector and restoration markets in Germany and France sustain minimal production volumes despite comprehensive retail bans.
Today's leader: LED. Tomorrow's challenger: None—consolidation is complete.
Application:
Outdoor infrastructure commands per-unit premiums while indoor volumes dominate shipment counts.
- Indoor:Commercial office, retail, and residential illumination systems. Specification authority in United States Class A real estate has shifted from electrical contractors to IT infrastructure teams.
- Outdoor:Street, area, and landscape luminaires with environmental hardening. Smart city deployments in India's municipal sectors embed air quality and traffic sensors, expanding hardware value per node.
- Automotive:Headlamp, interior, and signal lighting with vibration resistance and thermal management requirements. OSRAM and similar specialists capture premiums through emitter chip thermal performance leadership.
- Emergency:Battery-backed egress and safety illumination with regulatory-mandated testing protocols. Healthcare facility specifications in Germany and France require centralized monitoring integration.
Outdoor applications are climbing the fastest as municipal procurement digitizes.
Technology:
Connectivity features separate premium tiers from commodity replacement hardware.
- Smart Lighting:Sensor-integrated fixtures with Zigbee, Thread, or Matter protocol stacks. Corporate real estate managers specify occupancy-based energy management in United States metropolitan markets.
- Traditional:Hardwired on/off control without network connectivity. Residential replacement demand in India concentrates in price-sensitive segments.
- Solar:Photovoltaic-powered off-grid luminaires with battery storage. Rural electrification programs in India and distributed infrastructure in Germany deploy standalone systems.
- Dimming:Phase-cut or 0-10V analog control for illuminance modulation. Hospitality specifications in France and Germany sustain demand for warm-dimming characteristics.
Smart Lighting captures margin expansion while Traditional defends volume foundations.
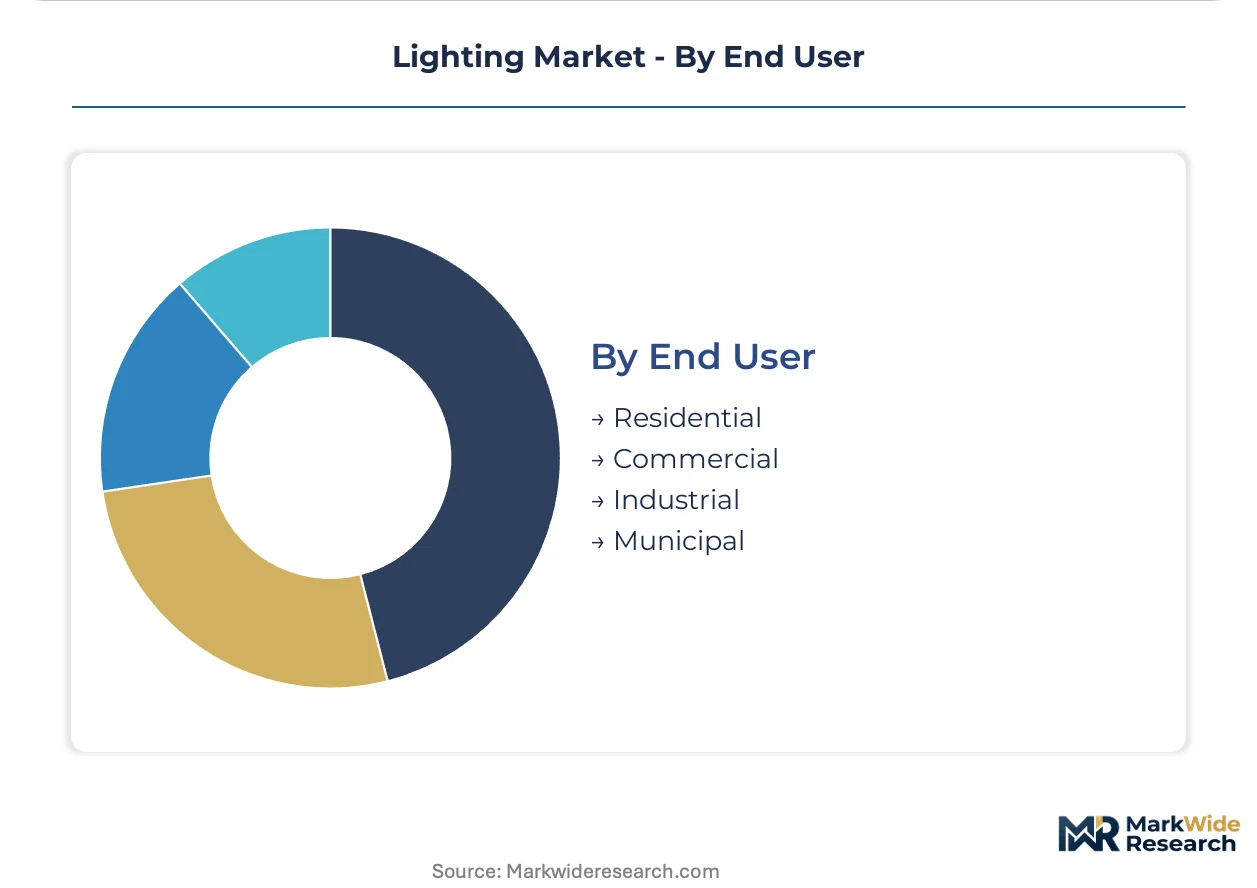
End User:
Municipal procurement centralization is disrupting traditional distribution hierarchies.
- Residential:Single-family and multi-unit dwelling installations. India's urbanization drives fixture demand as building code enforcement intensifies in metropolitan regions.
- Commercial:Office, retail, and hospitality facilities. Power-over-Ethernet specification in United States new construction compresses electrical installation labor costs.
- Industrial:Manufacturing, warehousing, and hazardous location illumination. High-bay LED retrofits in Germany's industrial corridors accelerate under EU Green Deal renovation targets.
- Municipal:Street lighting, parks, and public infrastructure. India's Smart Cities Mission concentrates procurement authority at city government levels, enabling direct vendor relationships.
Municipal verticals are gaining share fastest as infrastructure digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's municipal LED procurement volumes exceed India's commercial retrofit demand, though India's Smart Cities Mission concentrates authority differently than China's provincial tendering systems. Germany's building renovation wave compresses fluorescent viability faster than France's hospitality-driven halogen tolerance. The United States splits between IT-driven commercial specification and distributor-led residential replacement.
United States
Class A office construction specifies Power-over-Ethernet systems at accelerating rates as corporate real estate managers unbundle lighting from mechanical service contracts. The US Department of Energy enforces minimum efficacy standards that phase out legacy fluorescent magnetic ballast inventories. New York and San Francisco metropolitan markets exhibit the strongest procurement centralization, with IT infrastructure teams displacing electrical contractors in specification authority.
Germany
Industrial high-bay LED retrofits accelerate under EU Green Deal renovation targets as facility managers separate capital budgets between facilities and IT departments. The KBA interprets building efficiency mandates through divergent compliance timelines than France's national regulators. The Ruhr industrial corridor concentrates manufacturing modernization demand, with automotive suppliers driving specification for tunable white systems in quality inspection environments.
China
Commercial building retrofits concentrate in provincial capitals as GB standards enforcement accelerates fixture replacement timelines beyond normal economic cycles. The MIIT oversees national efficiency benchmarks that neighboring ASEAN markets emulate for export certification templates. The Yangtze River Delta anchors domestic LED module production, with Shenzhen-based fixture manufacturers capturing municipal smart street lighting procurement through direct city government relationships.
India
Urbanization in metropolitan regions intensifies building code enforcement as the Smart Cities Mission concentrates procurement authority at municipal levels. The BIS administers national standards that accelerate domestic LED adoption while creating compliance barriers for uncertified imports. Maharashtra and Gujarat state governments bypass traditional electrical distribution hierarchies, enabling direct vendor relationships for connected street lighting with embedded environmental sensors.
France
Hospitality dimming applications sustain niche halogen demand where aesthetic warmth overrides efficiency metrics in luxury hotel specifications. The national building regulator interprets EU Green Deal targets through extended compliance timelines than Germany's KBA. The Provence-Alpes-Côte d'Azur tourism corridor maintains collector market volumes for technically obsolete incandescent sources despite comprehensive retail bans.
Lighting Market Key Industry Players
Top-tier vendors anchor premium connected systems, while commodity replacement lamp specialists defend volume foundations through distributor relationships. The market exhibits tiered consolidation with three to five dominant players controlling smart lighting protocol stacks and recurring software revenue streams. Two strategic archetypes predominate: platform-integrated solution providers capturing building automation specification, and component-specialized emitters commanding thermal performance premiums in automotive and industrial segments. Competitive moves concentrate on backward integration into LED driver manufacturing and strategic partnerships for multi-protocol interoperability certification.
Within the platform-integrated tier, Signify Holding and Acuity Brands, Inc. occupy positions exemplifying software-enabled building automation capture, while OSRAM GmbH anchors the component-specialist archetype through emitter chip thermal performance leadership. These three entities represent the dominant competitive vectors: recurring service revenue, vertical manufacturing control, and specialty emitter premiums.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands, Inc. |
| OSRAM GmbH |
| Panasonic Holdings Corporation |
| Cree Lighting |
| GE Lighting |
| Eaton Corporation |
| Zumtobel Group |
| Hubbell Incorporated |
| Others |
Cost & Logistics Intelligence
The EU Ecodesign Directive gates qualified supply and premium-tier pricing access by mandating efficiency benchmarks that disqualify uncertified manufacturers from European procurement channels. Buyers in Germany and France now face tiered vendor pools where compliance documentation determines bid eligibility and margin capture.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for LED modules as domestic manufacturers scale emitter chip production. Three-tier pricing structure across premium, standard, and economy levels separates PoE-enabled smart fixtures from basic retrofit lamps from uncertified imports. Cost compression in economy-tier replacement lamps is intensifying because India's price-sensitive residential segment drives volume procurement at minimal margins. Municipal buyers in India's Smart Cities Mission exhibit lowest price sensitivity due to central government funding buffers, while residential replacement demand in India concentrates maximum price pressure.
Supply Chain Analysis
Dual-sourcing requirements from European fixture assemblers mandate multi-supplier qualification for rare-earth phosphors to mitigate europium and terbium concentration risk. Supply concentrates in China for LED module fabrication, in Germany for precision driver electronics, and in Japan for high-CRI emitter chips. Raw material dependencies center on rare-earth phosphors, aluminum thermal substrates, and copper winding stock. Single-source vulnerability in terbium processing corridors exposes manufacturers to strategic supply interruptions. Distribution runs through electrical wholesalers in United States metropolitan markets and direct municipal contracts in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from regulatory timing differentials: India's extended fluorescent compliance windows sustain legacy component demand while Germany's accelerated EU Green Deal enforcement compresses replacement cycles for premium LED retrofits.
For Market Incumbents: Extend software platform stickiness by embedding predictive maintenance subscriptions into Interact-style building automation deployments. Deepen backward integration into LED driver manufacturing to defend margin position against emerging Asian component suppliers. Capture specification authority before IT infrastructure teams fully displace electrical contractors in United States Class A office procurement.
For New Entrants and Emerging Players: Small-scale municipal governments in India's secondary cities represent an underserved buyer archetype bypassed by national distributors focused on state capitals. Target direct city relationships for connected street lighting with embedded air quality sensors, leveraging BIS certification as competitive moat against uncertified imports. Pursue white-label manufacturing partnerships with Shenzhen-based fixture producers to compress qualification timelines.
For Investors and Strategic Acquirers: Roll-up economics work for regional lighting maintenance specialists because facility managers are unbundling service contracts from comprehensive mechanical agreements across United States healthcare and education verticals. Acquisition target archetype: mid-scale service providers with predictive diagnostics capabilities and municipal client concentration. Watch India's Smart Cities Mission disbursement velocity as inflection indicator for hardware procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver Manufacturing | Acuity Brands' captive supply of drivers reduces component cost volatility and accelerates product development cycles. |
| Smart City Platform Integration | Signify's Interact deployment in India's municipal sectors embeds recurring software revenue beyond hardware margins. |
| Multi-Protocol Interoperability Certification | Matter and Thread compliance investment opens specification access in United States IT-driven commercial construction. |
| Human-Centric Lighting Product Line Extension | Tunable white systems with verified melanopic efficacy capture premium positioning in Germany's healthcare facility retrofits. |
| Rare-Earth Phosphor Supply Agreement | Long-term offtake contracts with Chinese processors mitigate europium concentration risk for OSRAM's automotive emitter production. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal procurement officers, facilities managers at United States Class A commercial real estate, LED driver manufacturing engineers, and electrical distribution channel heads with secondary validation. Sources included customs and trade flow databases, SEC 10-K filings from listed lighting manufacturers, BIS and MIIT regulatory filings, EU Ecodesign Directive implementation reports, and smart city tender documentation from India's Ministry of Housing and Urban Affairs. Bottom-up fixture shipment estimates triangulated against top-down construction spending and building stock replacement models.
Segment-weighting applied product type, application, technology tier, and end-user vertical dimensions across the modeling period. LED module volumes, smart lighting protocol adoption rates, and municipal procurement digitization indices served as industry-specific forecast inputs. CAGRs derived from regression analysis against historical replacement cycle compression and regulatory mandate implementation timelines.
Underlying measurement precision varies by segment; smart lighting technology and municipal end-use carry tighter precision than residential replacement demand due to tender documentation availability. Forecasts reflect documented assumptions about regulatory enforcement consistency and rare-earth supply stability. Deviation in India's Smart Cities Mission funding disbursement velocity or EU member state building code interpretation divergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Commercial Lighting Market
Lighting
Dimmers Market
Lighting
High-End Lighting Market
Lighting
North America Smart Lighting Market
Lighting
Lighting Management System Market
Lighting
Xenon Flashlamps Market
Lighting
Lamps and Lighting Market
Lighting
Ultraviolet Lamps Market
Lighting
Smart Lights Market
Lighting
COB Photo Light Market
Lighting
Global Plasma Lamp Market
Lighting
Solar Spotlights Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Gesture Control Light Market
Lighting
Explosion Proof Lighting Market
Lighting
US Indoor LED Lighting Market