
 Optical Component Tester Market | 2026-2036
Optical Component Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Component Tester Market Outlook
The divergence between premium and commodity tiers is hardening in the optical component tester landscape, with high-end instruments commanding five-figure price points for PAM4 and coherent signal analysis while entry-level power meters face commoditization. Keysight Technologies leverages its software-defined instrumentation platform to dominate R&D-intensive validation workflows. Viavi Solutions anchors its position through deep integration with fiber deployment and service assurance toolchains. EXFO Inc. specializes in portable field-test form factors that sustain recurring calibration and subscription revenue streams.
An optical component tester comprises precision instrumentation engineered to characterize parameters such as insertion loss, return loss, polarization-dependent loss, and wavelength accuracy across the 1260 nm to 1625 nm telecom window, serving the essential function of certifying optical subassemblies before network integration. Spectrometer segments command premium positioning as coherent transmission architectures proliferate, while optical power meters represent a mature, high-volume category where margin pools have shifted toward bundled software analytics. Fiber optic technology segments are expanding fastest, driven by hyperscaler data center buildouts requiring ribbon fiber and MPO connector validation at scale.
The FCC's equipment authorization rules shape market access for testers deployed in US telecommunications infrastructure, while REACH compliance in Europe constrains substance use in optical connector assemblies and test fixture manufacturing. China's GB standards and MIIT certification requirements create a parallel regulatory track that domestic equipment manufacturers must navigate for local market participation. Stakeholders must monitor how emerging 1.6T optical standards reshape calibration intervals and whether regional divergence in test protocols fragments instrument compatibility requirements.
Market Dynamics
The transition from 400G to 800G and 1.6T optical transceivers is compressing calibration cycles and forcing capital deployment into multi-channel PAM4 test platforms capable of validating 112Gbaud signaling.
Growth Catalysts
- Hyperscaler data center buildouts:Cloud operators in the United States and China are procuring ribbon fiber and MPO connector validation equipment at volume to support AI training clusters.
- F-Gas Regulation:The European Union's phasedown of fluorinated greenhouse gases is accelerating replacement of legacy cooling systems in test environments, creating pull for thermally efficient instrumentation.
- Coherent transmission architectures:Deployment of 400G+ coherent pluggables is expanding demand for optical spectrum analyzers and wavelength-tunable laser sources.
Market Restraints
- Precision optics input costs:Diffraction gratings and InGaAs detector arrays face supply concentration from Japanese and German specialty manufacturers, creating margin pressure.
- Technical limitation in single-test coverage:No single instrument currently validates both analog parameters and digital signal integrity for 1.6T modules, forcing multi-platform capital outlays.
- REACH substance restrictions:European constraints on lead and cadmium in optical connector assemblies complicate test fixture sourcing and extend qualification timelines.
Strategic Opportunities
- India's domestic optical module production:PLI scheme incentives are attracting contract manufacturers to Gujarat and Tamil Nadu, creating localized demand for validation equipment.
- Software-defined instrumentation convergence:FPGA-based measurement engines combined with cloud-native analytics platforms enable subscription revenue models and remote calibration services.
- Portable field-test form factors:5G fronthaul and midhaul deployment is expanding demand for battery-operated OTDR and power meter units in outdoor environments.
Industry Challenges
- Multi-physics simulation expertise:Test engineers must integrate optical, electrical, and thermal domain knowledge to validate co-packaged optics, creating hiring bottlenecks.
- MIIT certification timelines:China's type-approval process for telecom test equipment extends market entry by 6-12 months versus comparable FCC equipment authorization cycles.
- Interoperability fragmentation:Divergent 1.6T optical standards between IEEE 802.3dj and OIF implementations are forcing dual-protocol instrument development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Component Tester Market |
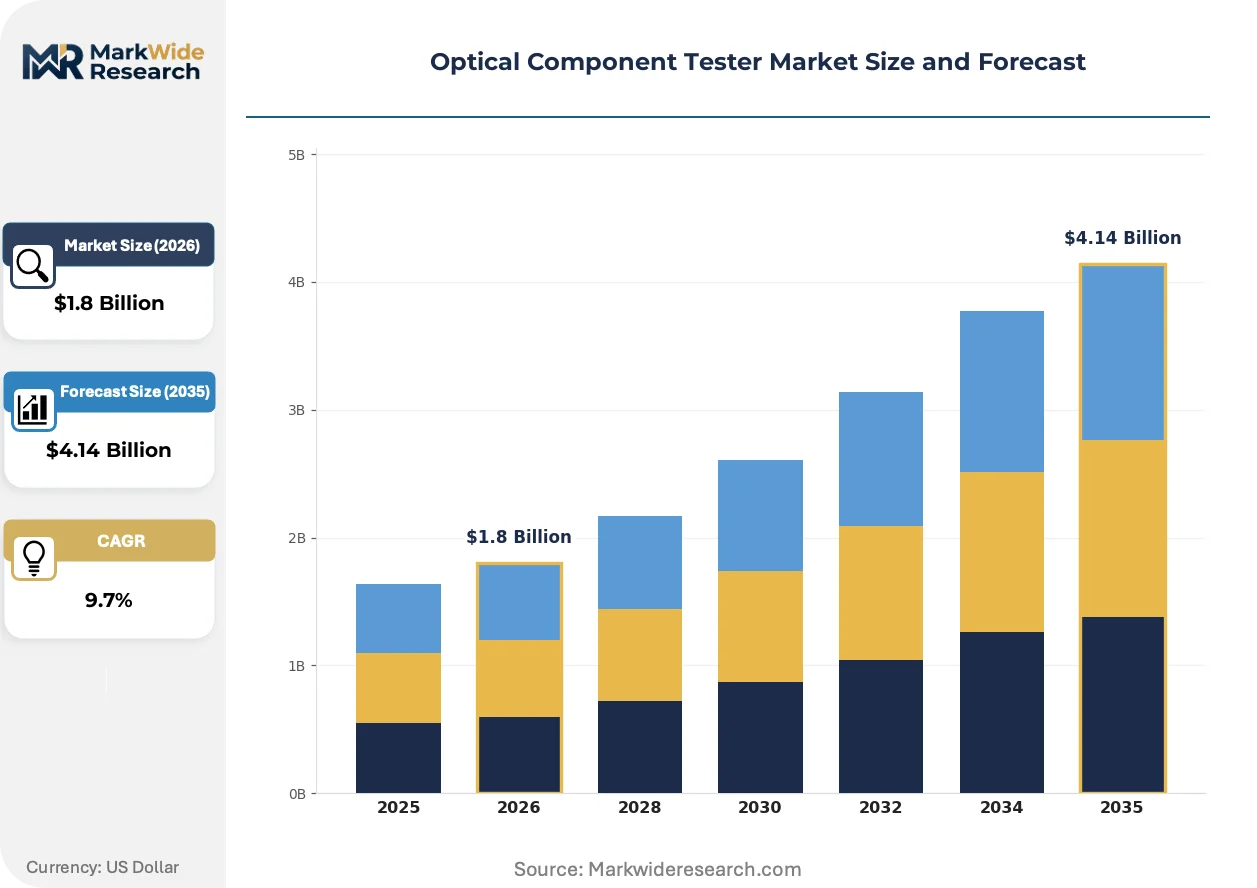
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeter, Optical Power Meter, Loss Test Set, Spectrometer Technology: Active Optical, Passive Optical, Fiber Optic, Photonics Application: Telecommunications, Data Centers, Laboratory Testing, Manufacturing End User: Telecom Operators, Government Agencies, Research Institutions, Equipment Manufacturers |
| Companies Covered | Keysight Technologies, Viavi Solutions, EXFO Inc., Anritsu Corporation, Yokogawa Electric Corporation, Tektronix Inc., Fluke Networks, Spirent Communications, General Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Component Tester Market Strategic Shifts
Instrumentation architectures are pivoting from fixed-function hardware toward software-defined measurement engines that reconfigure via firmware updates. This shift is compressing product obsolescence cycles and redistributing value toward analytics software layers.
Machine learning-enhanced eye diagram analysis is rewriting how transceiver manufacturers perform pass-fail screening. Keysight and Viavi have deployed neural network-based jitter decomposition algorithms that reduce test time by 40% for 800G modules. Hyperscalers are mandating these capabilities in procurement specifications, forcing mid-tier instrument vendors to license IP or exit the premium segment.
The European Union's F-Gas Regulation is mandating refrigerant transitions in thermal control units used within environmental test chambers. Manufacturers must redesign chiller systems to use R-513A or CO2-based cooling by 2030, adding engineering overhead but creating differentiation for early movers. German test equipment suppliers are leveraging this compliance lead to anchor positioning in sustainability-conscious European accounts.
Cloud-based test data management is displacing on-premise storage architectures in high-volume manufacturing environments. Contract manufacturers in Taiwan and Malaysia are adopting AWS- and Azure-hosted analytics platforms to enable real-time yield monitoring across geographically distributed facilities. This shift is unbundling hardware sales from software subscriptions, compressing upfront capital requirements while extending vendor revenue visibility.
Optical Component Tester Market Segmentation
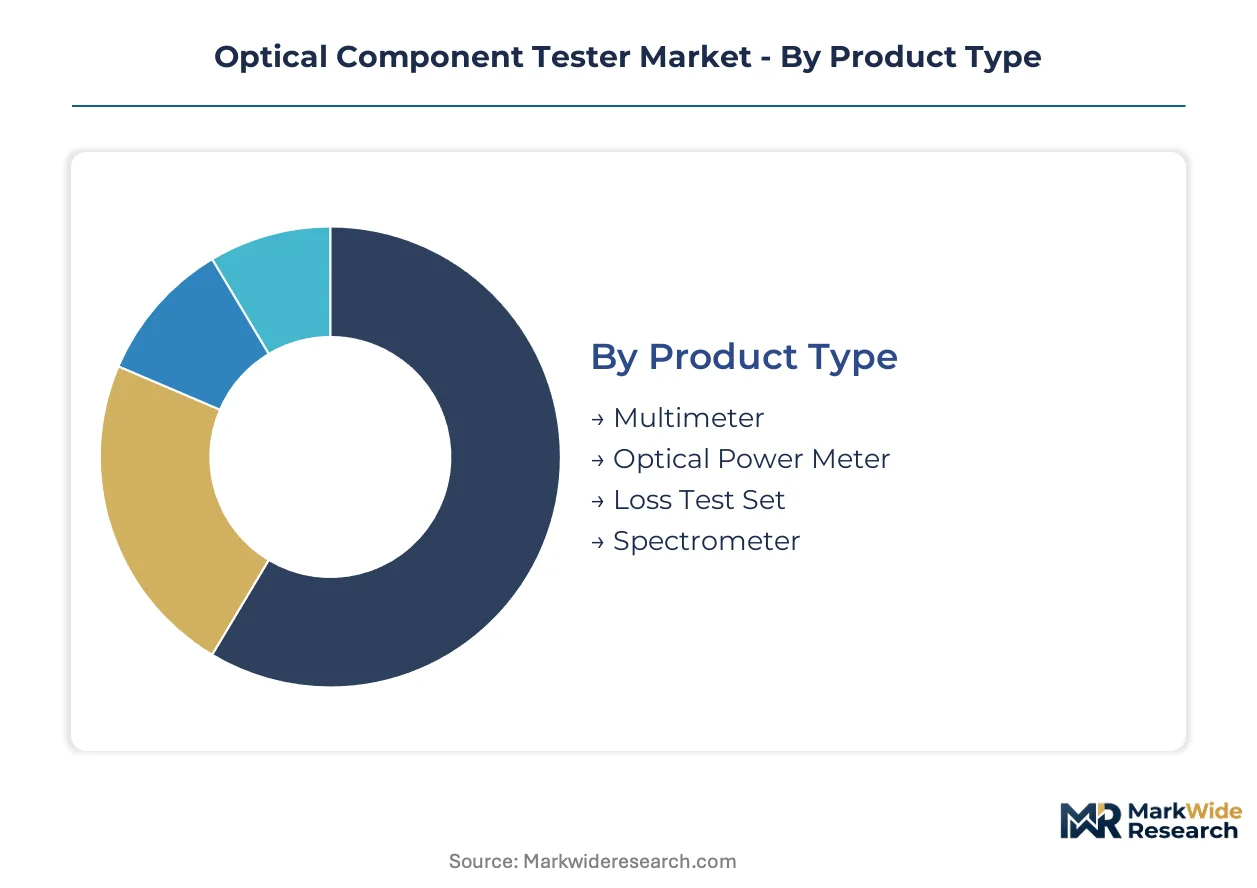
Segmentation in the optical component tester market reveals how technical specifications, deployment environments, and procurement authority distribute value across instrument categories. Buyers in data centers prioritize multi-channel PAM4 platforms, while telecom field operations demand portable, battery-operated form factors with ruggedized enclosures.
Product Type:
Supply concentration in precision optics and detector arrays concentrates margin capture in instruments requiring wavelength-tunable sources and high-resolution gratings.
- Spectrometer:Optical spectrum analyzers characterize wavelength accuracy, OSNR, and spectral purity across C-band and L-band telecom windows. Hyperscaler data centers in the United States and China procure these units to validate 400G+ coherent pluggables, though Japanese and German specialty manufacturers control diffraction grating supply.
- Optical Power Meter:These instruments measure absolute and relative power levels across the 1260 nm to 1625 nm range with calibrated InGaAs detector arrays. Entry-level units face commoditization as contract manufacturers in Taiwan and Malaysia bundle them into high-volume ribbon fiber validation workflows.
- Loss Test Set:Integrated insertion loss and return loss measurement platforms certify MPO and LC connector assemblies before network integration.
- Multimeter:Combined electrical-optical test functions address co-packaged optics requiring simultaneous voltage, current, and optical power validation.
Spectrometer segments absorb the bulk of installed capacity in R&D-intensive validation environments; loss test sets are expanding most quickly through hyperscaler procurement of ribbon fiber infrastructure.
Technology:
Cost tier stratification separates capital-intensive coherent test platforms from high-volume passive component screening equipment.
- Fiber Optic:Test systems for single-mode and multimode fiber, MPO connectors, and ribbon cable assemblies dominate volume procurement. Cloud operators building AI training clusters in Virginia, Oregon, and Guizhou province are driving demand for 12-fiber and 24-fiber MPO validation at scale.
- Active Optical:PAM4 and NRZ signal integrity testers for 800G/1.6T transceivers command premium positioning through software-defined measurement engines. Keysight and Viavi anchor this segment with FPGA-based architectures that reconfigure via firmware updates.
- Passive Optical:CWDM, DWDM, and splitter testing equipment serves fiber-to-the-home deployment and 5G fronthaul networks.
- Photonics:Silicon photonics and co-packaged optics test platforms integrate thermal, electrical, and optical domain characterization.
Fiber optic technology holds the largest installed base; active optical platforms are gaining share fastest through data center buildouts requiring 112Gbaud signal validation.
Application:
Customer type and procurement authority determine whether instruments sell through capital expenditure cycles or recurring calibration service contracts.
- Data Centers:Hyperscale and colocation facilities require automated, multi-channel test systems for 800G transceiver screening at production volumes. Procurement specifications from cloud operators in the United States and China now mandate machine learning-enhanced eye diagram analysis capabilities.
- Telecommunications:Carrier networks and 5G infrastructure deployment drive demand for portable OTDR and power meter units. Field technicians in outdoor environments prioritize battery-operated form factors with cloud-native data upload.
- Manufacturing:Contract optical module producers in Taiwan, Malaysia, and China adopt high-throughput screening platforms with AWS- and Azure-hosted analytics.
- Laboratory Testing:R&D facilities and standards bodies require reference-grade instrumentation with NIST-traceable calibration.
Data center applications command the highest revenue per unit; manufacturing adoption is climbing the fastest as contract producers scale domestic optical module output.
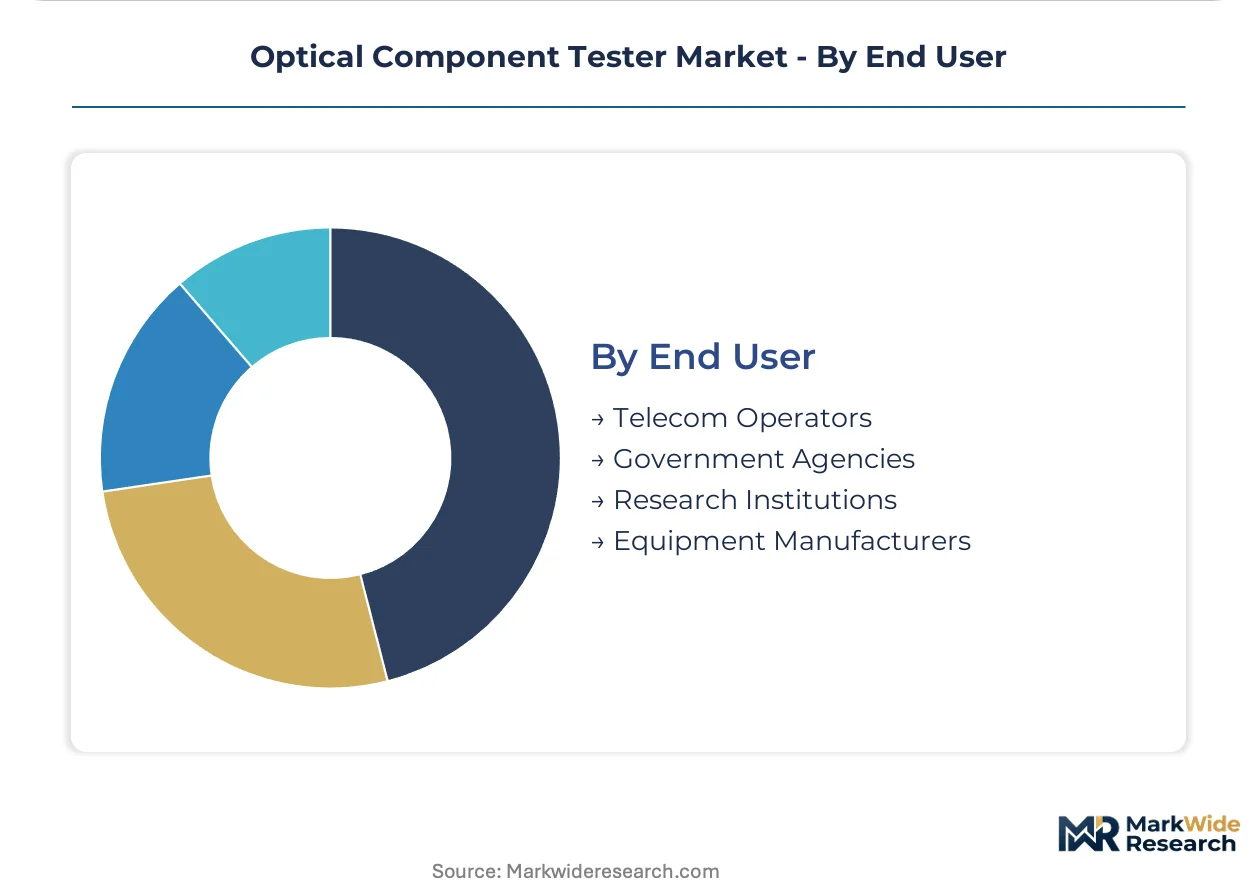
End User:
Volume concentration among hyperscale cloud operators and tier-1 contract manufacturers shapes instrument development roadmaps and feature prioritization.
- Equipment Manufacturers:Optical transceiver and fiber cable producers in China, Taiwan, and Malaysia represent the largest procurement volume. These buyers prioritize throughput, automation, and cloud-based yield analytics over absolute measurement precision.
- Telecom Operators:Verizon, AT&T, China Mobile, and Deutsche Telekom deploy field-test equipment across access, metro, and long-haul networks. Their procurement emphasizes ruggedization, battery life, and integration with service assurance platforms.
- Research Institutions:Universities and national laboratories acquire reference-grade spectrometers and tunable laser sources for standards development.
- Government Agencies:Defense and aerospace programs require ITAR-compliant test equipment with extended environmental operating ranges.
Equipment manufacturers account for the dominant share of unit shipments; telecom operators are expanding procurement most rapidly through 5G midhaul and fronthaul buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the global optical component tester procurement surge, with hyperscaler data centers in Guizhou and Jiangsu provinces driving multi-channel PAM4 platform demand. The United States, China, Germany, Japan, and India concentrate the bulk of validation equipment deployment.
United States
Cloud operators in Virginia and Oregon are scaling 800G transceiver screening for AI training clusters. FCC equipment authorization rules govern market access for telecom infrastructure deployments. Austin and Phoenix host the fastest-growing data center corridors where ribbon fiber validation equipment absorbs capital.
Germany
Industrial fiber deployment and 5G midhaul buildouts sustain demand for portable OTDR units. The EU F-Gas Regulation mandates refrigerant transitions in thermal test chambers by 2030. Munich and Stuttgart anchor precision instrumentation engineering for coherent transmission test platforms.
Japan
Diffraction grating and InGaAs detector array supply concentration supports domestic spectrometer manufacturing. METI industrial standards shape calibration protocols for optical module producers. Yokohama and Osaka host specialty optics suppliers that feed global test equipment value chains.
India
PLI scheme incentives are attracting optical module contract manufacturers to Gujarat and Tamil Nadu. BIS certification requirements and TRAI telecom regulations govern equipment type-approval. The Delhi-Mumbai Industrial Corridor is emerging as a validation equipment procurement node for export-oriented production.
China
Domestic optical module production scaling in Wuhan and Chengdu compresses instrument procurement cycles. MIIT certification timelines extend market entry by 6-12 months versus FCC equivalents. The Yangtze River Delta concentrates the highest density of cloud data center buildouts requiring MPO connector validation at scale.
Optical Component Tester Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-analytics integration, with five-figure price points separating PAM4 signal analysis platforms from entry-level power meters. The vendor base stratifies into three tiers: integrated instrumentation conglomerates with software-defined platforms, specialized fiber test suppliers with recurring service revenue, and regional component assemblers competing on unit cost. Consolidation pressure intensifies as hyperscalers mandate machine learning-enhanced capabilities in procurement specifications. Strategic moves center on FPGA-based measurement engine development and cloud-native analytics platform partnerships.
Within the integrated instrumentation tier, Keysight Technologies and Viavi Solutions exemplify archetypes that anchor premium positioning through software-defined architectures. EXFO Inc. occupies a distinct field-specialist position with portable form factors. Anritsu Corporation and Yokogawa Electric Corporation represent Japanese conglomerates that leverage precision optics supply chain proximity. These groupings illustrate how geographic clustering around detector array and diffraction grating suppliers reinforces competitive segmentation.
| Leading Market Players |
|---|
| Keysight Technologies |
| Viavi Solutions |
| EXFO Inc. |
| Anritsu Corporation |
| Yokogawa Electric Corporation |
| Tektronix Inc. |
| Fluke Networks |
| Spirent Communications |
| General Photonics |
| Others |
Value Chain & Pricing Dynamics
Hyperscaler procurement teams in Virginia and Guizhou province concentrate buying power for multi-channel PAM4 platforms, anchoring value-based pricing that ties instrument cost to transceiver screening throughput rather than hardware bill-of-materials alone. This buyer concentration feeds back into supply chain design, forcing vendors to prioritize detector array and diffraction grating partnerships that guarantee yield-analytics performance.
Pricing Analysis
Value-based pricing anchors on transceiver screening throughput and yield-analytics outcomes rather than hardware specifications alone. Three-tier pricing structure across premium, standard, and economy levels separates FPGA-based PAM4 platforms from fixed-function power meters and entry-level OTDR units. Cost compression in the economy tier intensifies because contract manufacturers in Taiwan and Malaysia bundle instruments into high-volume ribbon fiber workflows. Equipment manufacturers in China and Taiwan exhibit highest price sensitivity; hyperscaler data center operators in the United States and China show lowest sensitivity when machine learning-enhanced capabilities are specified.
Supply Chain Analysis
Workforce availability for precision optics assembly in Japan, Germany, and the United States constrains spectrometer production scaling despite demand acceleration. Diffraction grating manufacturing draws from specialty glassworks in Japan and Germany; InGaAs detector arrays rest on compound semiconductor foundries in Japan and the United States. Single-source vulnerability in precision optics inputs creates qualification bottlenecks when switching suppliers. Distribution runs through direct vendor relationships with hyperscaler procurement teams and contract manufacturer equipment buyers in Taiwan, Malaysia, and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical component tester market functions as a vertical-integration race where control over FPGA-based measurement engines and cloud-native analytics platforms determines margin capture. Players are pursuing backward integration into precision optics supply chains to secure diffraction grating and detector array allocation.
For Market Incumbents: Hedge against emerging software-defined instrumentation challengers by deepening captive supply of wavelength-tunable laser sources and high-resolution gratings. Accelerate certification investment for MIIT type-approval in China to compress market entry timelines relative to FCC-equivalent cycles. Defend premium positioning through exclusive cloud-analytics partnerships with AWS and Azure that mid-tier vendors cannot replicate.
For New Entrants and Emerging Players: The gap between five-figure PAM4 platforms and commoditized power meters creates white-space opportunity for mid-tier instruments with firmware-upgradeable measurement engines. Target India's PLI-subsidized optical module production in Gujarat and Tamil Nadu as the most penetrable geography. Pursue portable field-test form factors for 5G fronthaul deployment as the go-to-market angle, emphasizing battery-operated ruggedization and cloud-native data upload.
For Investors and Strategic Acquirers: The window for entry favors FPGA-based measurement engine specialists with existing cloud-analytics integration over hardware-only component assemblers. Long-term viability across the projection horizon hinges on software subscription revenue attachment rates rather than upfront instrument sales. Monitor divergence between IEEE 802.3dj and OIF 1.6T optical standards as the signal indicating whether dual-protocol instrument development becomes a competitive moat or capital drain.
| Strategic Initiative | Industry Significance |
|---|---|
| FPGA-Based Measurement Engine Development | Enables firmware reconfiguration that compresses product obsolescence cycles and extends revenue visibility through software subscriptions. |
| Cloud-Native Analytics Platform Partnership | AWS and Azure integration displaces on-premise storage in Taiwan and Malaysia contract manufacturing facilities. |
| Precision Optics Backward Integration | Captive supply of diffraction gratings and InGaAs arrays insulates margin from Japanese and German specialty manufacturer concentration. |
| MIIT Certification Pre-Investment | Early type-approval in China compresses 6-12 month market entry disadvantage versus FCC-authorized competitors. |
| Thermally Efficient Instrument Design | R-513A and CO2-based cooling compliance ahead of EU F-Gas Regulation deadlines anchors sustainability-conscious European accounts. |
Study Parameters
Document review covered SEC filings from test equipment vendors, hyperscaler capital expenditure disclosures, and MIIT certification databases, complemented by interviews with optical transceiver engineering directors, data center procurement managers, and precision optics manufacturing specialists. Secondary validation drew from FCC equipment authorization records, EU F-Gas Regulation implementation guidance, and Taiwan contract manufacturer equipment procurement patterns. Bottom-up unit demand modeling triangulated against top-down market sizing from instrument shipment aggregation.
Installed base projections across product type, technology, application, and end user segments fed into value estimates over the projection horizon. CAGRs were derived from segment-specific adoption curves calibrated against 800G and 1.6T transceiver deployment timelines and hyperscaler data center buildout acceleration in Virginia, Oregon, and Guizhou province.
Inputs from hyperscaler procurement specifications and contract manufacturer yield-analytics platforms were available through the study window; gaps in real-time pricing transparency for five-figure PAM4 platforms introduce uncertainty bands around premium segment value estimates. Forecasts reflect assumptions about coherent transmission architecture adoption and F-Gas Regulation compliance timelines. Material deviation in IEEE 802.3dj versus OIF 1.6T standardization or Japanese diffraction grating supply allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Waveguide Phase Shifter Market
Optical Components
Global Optical Diode Market
Optical Components
Europe Optical Imaging Market
Optical Components
Global Adaptive Optics Market
Optical Components
Quartz Glass Substrate Market
Optical Components
Passive Optical Component Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
North America Optical Film Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Display Optical Film Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Faraday Rotator Market
Optical Components
Prism Coupler Market
Optical Components
Mid-Infrared Laser Market