
 Smart Lamp Market | 2026-2036
Smart Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Lamp Market Analytics
Embedded firmware engineering talent scarcity is redrawing competitive boundaries across the smart lamp value chain. Signify Holding leverages its Amsterdam-based lighting software labs to sustain protocol leadership across Zigbee and Matter implementations. ams-OSRAM AG anchors the high-performance LED component tier through captive semiconductor fabrication in Austria and Malaysia. Legrand competes aggressively in the European commercial channel, where building automation integrators specify its connected downlight platforms for BREEAM-certified offices.
A smart lamp integrates solid-state illumination with embedded wireless transceivers, microcontrollers, and tunable drivers to enable remote intensity adjustment, color temperature modulation, and schedule-based operation via smartphone or voice assistant. LED product types dominate unit economics due to lumen-per-watt efficiency exceeding 150 lm/W and operational lifespans surpassing 25,000 hours. Wi-Fi and Zigbee technology segments split the connectivity architecture, with Wi-Fi capturing residential retrofit simplicity while Zigbee sustains mesh reliability in multi-node hospitality deployments. Home automation applications command the fastest expansion trajectory as platform ecosystems from Amazon Alexa, Google Home, and Apple HomeKit standardize lamp-level discovery and scene orchestration.
The EU Ecodesign Directive and REACH frameworks mandate recyclability disclosures and hazardous substance thresholds that filter non-compliant suppliers from European market access. The FCC in the United States enforces Part 15 emissions standards that constrain radio module selection and antenna design for Wi-Fi and Bluetooth implementations. China's MIIT administers SRRC certification for 2.4 GHz and sub-GHz radio configurations, adding a compliance gate for brands targeting mainland distribution. Stakeholders must monitor Matter protocol interoperability maturation and its potential to collapse technology fragmentation into a single commissioning experience.
Market Dynamics
Protocol fragmentation between Zigbee, Wi-Fi, and Matter implementations is forcing manufacturers to engineer multi-stack firmware architectures, raising R&D thresholds and compressing margins for single-protocol specialists.
Growth Catalysts
- EU Ecodesign Directive:Right-to-repair mandates and modularity requirements are accelerating consumer replacement cycles across Germany, France, and the United Kingdom as retrofit programs subsidize connected LED upgrades.
- Home automation platforms:Amazon Alexa, Google Home, and Apple HomeKit standardization is collapsing commissioning friction and enabling lamp-level scene orchestration in residential new construction.
- Tier-one Chinese urbanization:Xiaomi, Huawei, and Alibaba ecosystem penetration in Beijing, Shanghai, and Shenzhen is establishing connectivity as a default feature rather than premium add-on.
Market Restraints
- Semiconductor supply concentration:Captive LED fabrication in Austria and Malaysia creates geographic single-point vulnerability for high-performance component sourcing.
- FCC Part 15 compliance costs:Emissions testing and antenna redesign requirements for Wi-Fi and Bluetooth implementations add non-recoverable engineering overhead for US market entry.
- Incandescent substitution persistence:Price-sensitive residential segments in Eastern European and Southeast Asian markets continue deferring LED conversion, compressing addressable volume.
Strategic Opportunities
- Matter protocol maturation:Interoperability collapse into single commissioning experience creates white space for firmware-agnostic hardware platforms to capture multi-ecosystem households.
- Hospitality mesh deployments:Zigbee reliability in multi-node environments positions connected downlight platforms for BREEAM-certified office and hotel specification.
- SRRC certification arbitrage:MIIT's 2.4 GHz and sub-GHz radio gates filter competitor density for brands willing to navigate China's compliance timeline.
Industry Challenges
- Embedded firmware engineering scarcity:Multi-stack protocol expertise concentrates in Amsterdam, Shenzhen, and San Jose talent pools, inflating compensation and extending development cycles.
- Legacy building automation integration:BACnet and KNX backbone incompatibility with consumer-grade IoT stacks forces custom gateway development for commercial specification wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Lamp Market |
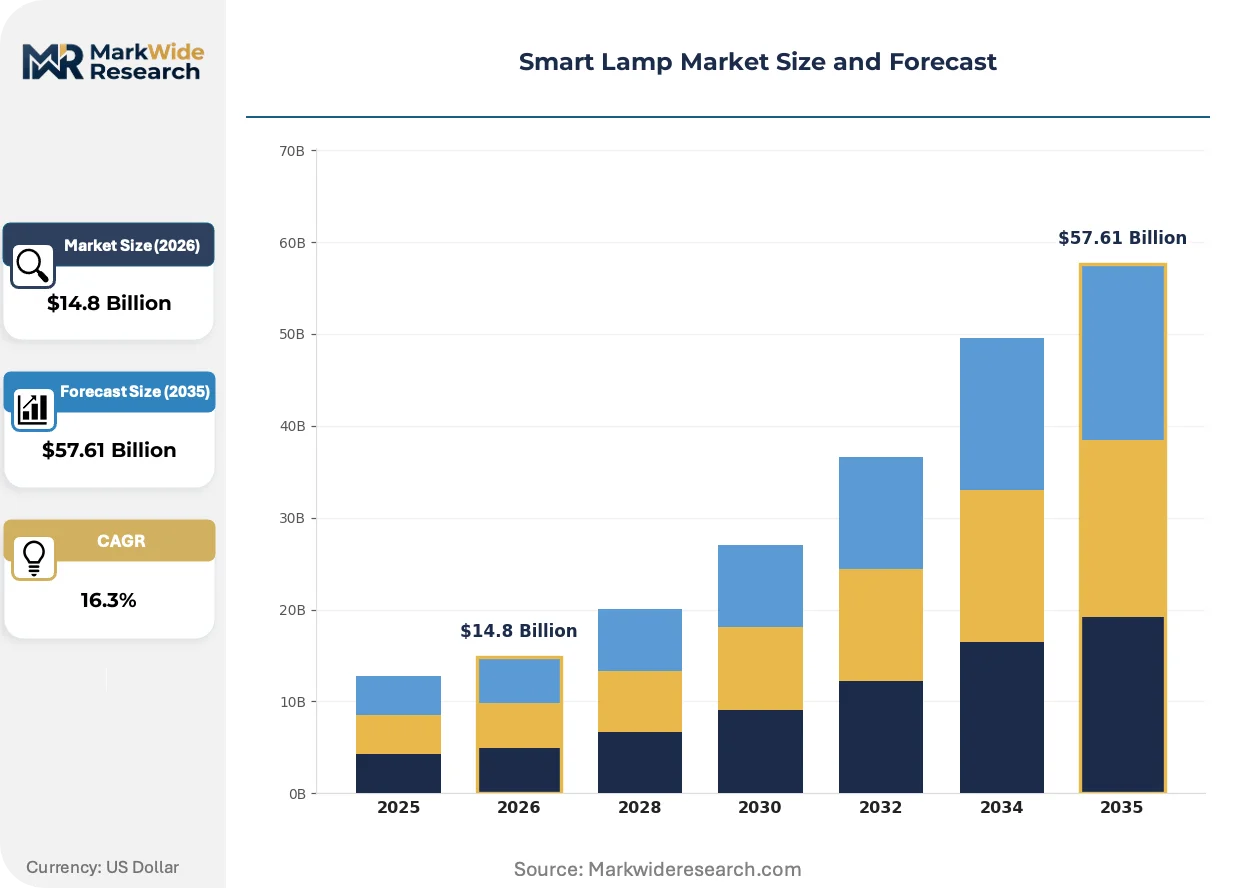
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $57.61 Billion |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Incandescent, Halogen, Fluorescent Technology: Wi-Fi, Bluetooth, Zigbee, Infrared Application: Home Automation, Office Use, Outdoor Lighting, Mood Lighting End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Signify Holding, Acuity Brands, Legrand, Panasonic Holdings Corporation, ams-OSRAM AG, GE Lighting, Lutron Electronics, LEDVANCE GmbH, Zumtobel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Lamp Market Evolving Landscape
Component integration and regulatory harmonization are compressing hardware footprints while expanding functional scope. Three developments are restructuring competitive requirements.
Multi-protocol system-on-chip architectures are consolidating Zigbee, Thread, and Bluetooth Low Energy transceivers onto single die configurations. Hospitality and commercial integrators in Dubai, Singapore, and London are specifying these unified modules to reduce BOM complexity and simplify sparing strategies. Silicon miniaturization is compressing radio subsystem costs and enabling tunable driver integration within standard A19 form factors.
REACH framework substance thresholds and recyclability disclosure mandates are filtering non-compliant suppliers from European market access. Industrial consequence includes forced reformulation of solder alloys and encapsulant chemistries, with compliance documentation now required at component rather than finished-goods level. German and French distributors are prioritizing suppliers with pre-validated material passports to accelerate customs clearance.
Platform-driven procurement is displacing standalone fixture specification as Amazon, IKEA, and homebuilder channel partners bundle connected lamps with ecosystem subscriptions. Professional electrical distributors in North American and Western European markets are responding by unbundling installation services from hardware margins. This shift is most visible in US new residential construction, where national homebuilders specify platform-compatible SKUs at master planning stage rather than leaving selection to subcontractor discretion.
Smart Lamp Market Segmentation
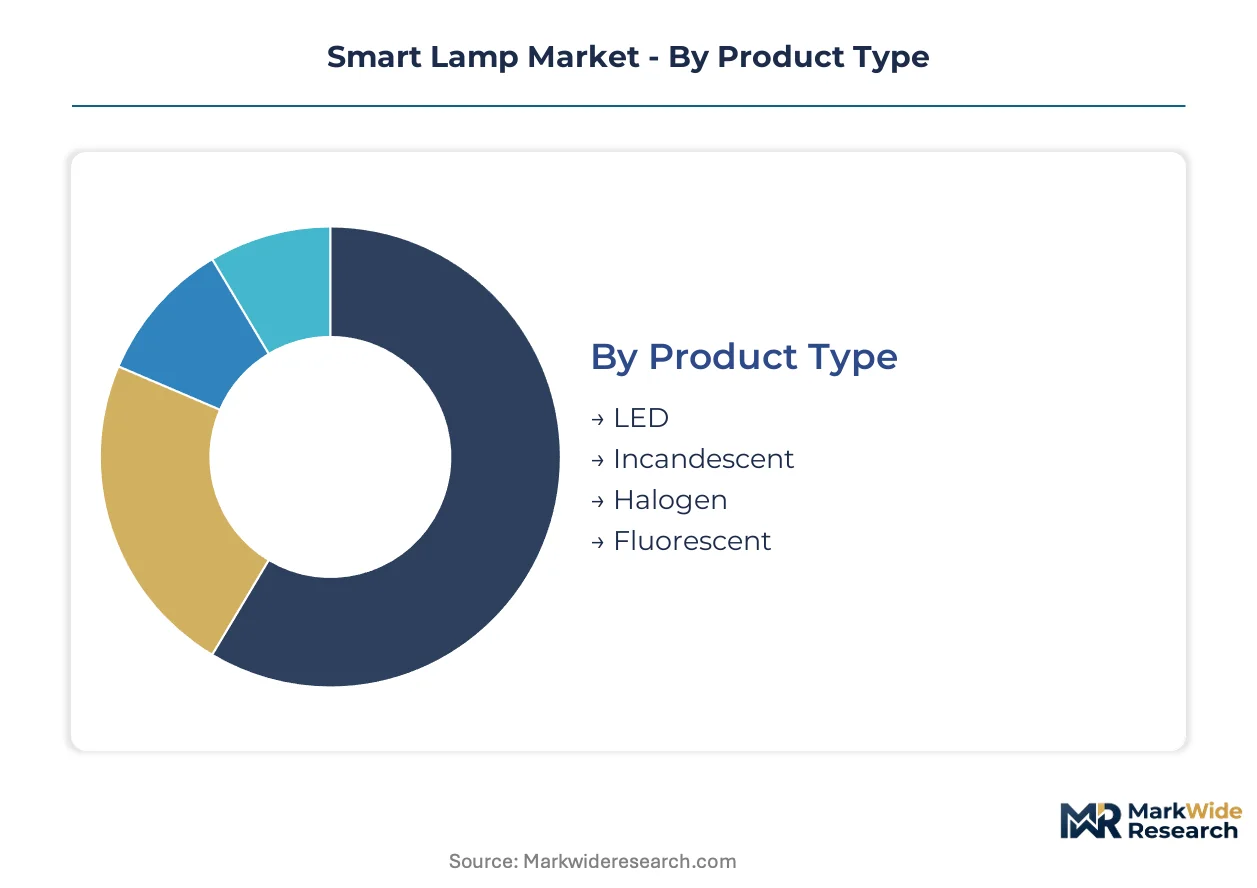
Smart lamp segmentation reveals divergent compliance pathways and technology maturities across product architectures. Manufacturers optimize portfolio allocation by matching protocol stacks to installation environments and regulatory jurisdictions.
Product Type:
EU Ecodesign Directive efficiency thresholds and REACH substance disclosures filter supplier eligibility by product chemistry and recyclability documentation.
- LED:Solid-state emitters achieving 150+ lm/W efficacy with 25,000-hour operational lifespans dominate retrofit economics. Demand concentrates in Germany, France, and the United Kingdom where right-to-repair mandates accelerate connected fixture upgrades.
- Incandescent:Resistive filament technology persists in price-sensitive Eastern European segments where deferred conversion cycles compress addressable volume. Austrian and Malaysian captive LED fabrication creates sourcing vulnerability for high-performance alternatives.
- Halogen:Tungsten-halogen cycle lamps retain niche specification in theatrical and display lighting requiring precise CRI performance.
- Fluorescent:Mercury-vapor discharge tubes face accelerating phase-out under EU RoHS amendments and state-level disposal restrictions.
Established volume favors LED; emerging adoption favors halogen in specialized applications.
Technology:
Radio module selection determines FCC Part 15 compliance burden and antenna engineering overhead for US market entry.
- Wi-Fi:IP-native connectivity eliminates gateway dependency for residential retrofit simplicity. Demand concentrates in North American single-family installations where smartphone commissioning dominates.
- Zigbee:Mesh networking protocol sustains multi-node reliability in hospitality and commercial deployments across Dubai, Singapore, and London. BREEAM-certified office integrators specify Zigbee downlights for building automation compatibility.
- Bluetooth:Low-energy beacon integration enables proximity-based scene triggering in retail and museum environments.
- Infrared:Line-of-sight control persists in legacy entertainment and security applications requiring deterministic latency.
Residential retrofit favors Wi-Fi; commercial specification favors Zigbee.
Application:
Platform ecosystem penetration reshapes procurement channels and margin structures by installation setting.
- Home Automation:Voice assistant and smartphone orchestration via Amazon Alexa, Google Home, and Apple HomeKit standardization. Tier-one Chinese cities establish connectivity as default in new construction.
- Office Use:Circadian lighting algorithms and occupancy-based dimming integrate with BACnet and KNX building management systems.
- Outdoor Lighting:IP-rated enclosures with cellular or LoRa backhaul serve municipal and campus infrastructure.
- Mood Lighting:Tunable white and RGBW color mixing address wellness and entertainment segments.
Platform bundling favors home automation; energy code compliance favors office use.
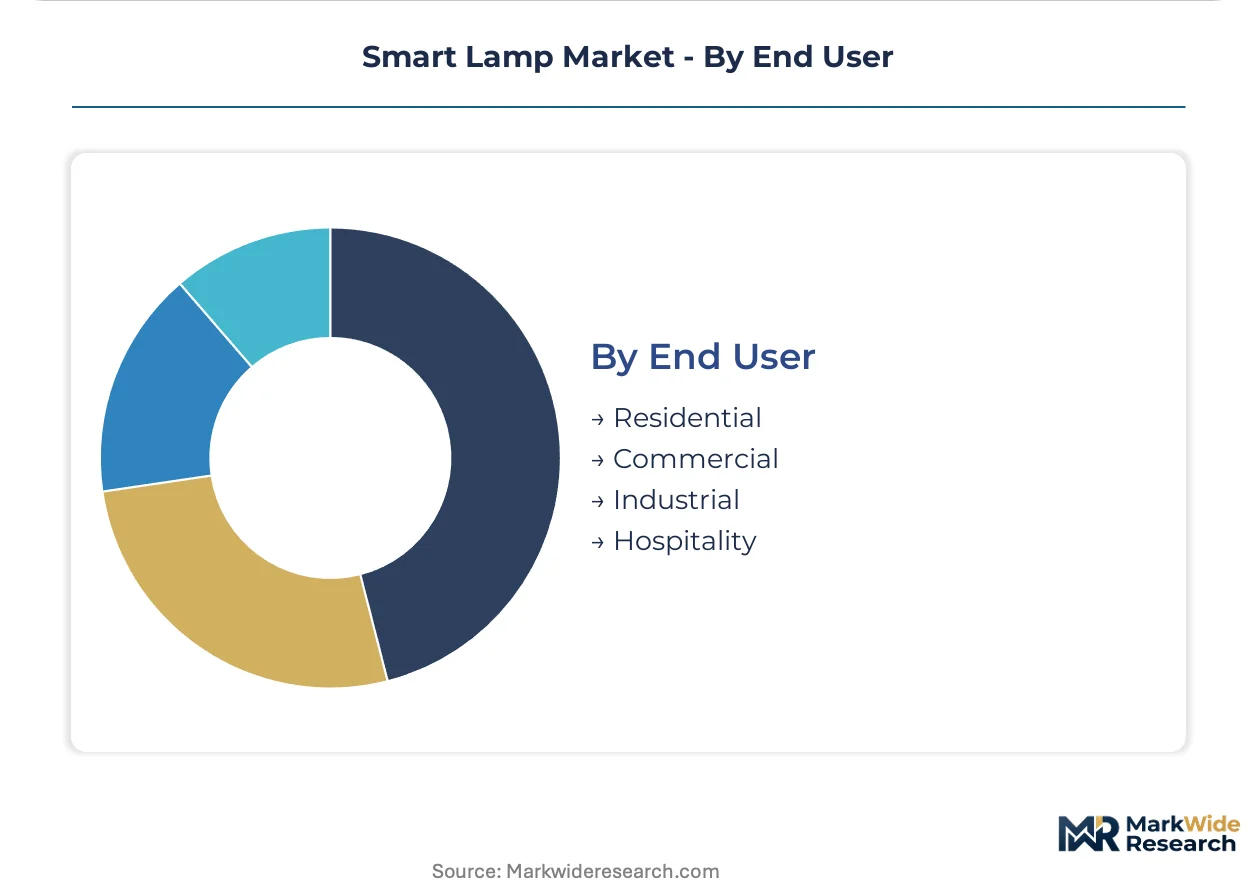
End User:
Customer procurement sophistication determines specification authority and service attachment potential.
- Residential:Consumer-directed purchasing through retail and direct-to-platform channels. National US homebuilders specify ecosystem-compatible SKUs at master planning stage.
- Commercial:Electrical contractor and facilities manager specification with energy performance contracting.
- Industrial:High-bay and hazardous location requirements with extended warranty and maintenance agreements.
- Hospitality:Brand-standard deployment across property portfolios with centralized scene management and guest room integration.
Volume scale favors residential; margin depth favors hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany and France prioritize right-to-repair modularity under EU mandates, while China's tier-one cities embed connectivity as a standard construction feature. The United States favors Wi-Fi retrofit simplicity over mesh complexity.
Germany
Residential retrofit programs in Berlin and Munich accelerate LED conversion cycles. The EU Ecodesign Directive mandates modularity disclosures that filter non-compliant imports. Bavarian industrial clusters around Munich and Nuremberg concentrate firmware engineering talent for Zigbee and Matter protocol stacks.
China
Xiaomi, Huawei, and Alibaba ecosystem penetration establishes lamp-level connectivity as default in Beijing, Shanghai, and Shenzhen new construction. MIIT administers SRRC certification gates for 2.4 GHz radio configurations. The Yangtze River Delta manufacturing corridor produces multi-protocol system-on-chip architectures for hospitality export markets.
United States
Single-family residential retrofit dominates volume through smartphone-commissioned Wi-Fi installations. FCC Part 15 emissions standards constrain antenna design and radio module selection for brands entering the market. California and Texas housing markets drive platform-compatible SKU specification at national homebuilder master planning stage.
France
Right-to-repair mandates accelerate replacement cycles in Paris and Lyon metropolitan areas. REACH framework substance thresholds force solder alloy reformulation for European market access. Île-de-France distributors prioritize suppliers with pre-validated material passports to expedite customs clearance.
United Kingdom
Building automation integrators in London specify connected downlight platforms for BREEAM-certified commercial offices. The EU Ecodesign Directive's efficiency thresholds persist in UK procurement standards post-Brexit. Southeast England logistics hubs channel hospitality mesh deployments to Dubai and Singapore markets.
Smart Lamp Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the smart lamp value chain. Signify Holding and ams-OSRAM AG anchor the upper tier through captive semiconductor fabrication and protocol leadership. The mid-tier fragments across firmware-agnostic hardware platforms and regional electrical distributors. Three archetypes dominate: vertically integrated component-to-fixture operators, multi-protocol firmware specialists, and platform-aligned ecosystem bundlers. Competitive moves concentrate on Matter protocol interoperability certification and hospitality channel specification wins.
Within the integrated component tier, ams-OSRAM AG anchors high-performance LED supply through Austrian and Malaysian fabrication positions. Signify Holding exemplifies protocol leadership archetype with Amsterdam-based lighting software labs sustaining Zigbee and Matter implementations. Legrand occupies a position in the European commercial channel where building automation integrators specify connected platforms for certified office deployments.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Legrand |
| Panasonic Holdings Corporation |
| ams-OSRAM AG |
| GE Lighting |
| Lutron Electronics |
| LEDVANCE GmbH |
| Zumtobel Group |
| Others |
Value Network & Pricing Analysis
Multi-protocol system-on-chip substitution for discrete radio modules simultaneously concentrates semiconductor sourcing in the Yangtze River Delta and compresses bill-of-material premiums for Wi-Fi and Zigbee implementations. This component consolidation reshapes pricing power toward firmware-agnostic hardware platforms while fragmenting margin capture between chip designers and fixture assemblers.
Pricing Analysis
Long-term offtake contracts dominate procurement between hospitality chains and connected downlight suppliers, insulating tier-one manufacturers from spot-market volatility in LED components. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified ecosystems from single-protocol Zigbee implementations and unbranded Wi-Fi retrofit units. Pricing pressure stems from platform bundling by Amazon and IKEA, which compresses standalone fixture margins. Residential retrofit buyers exhibit highest price sensitivity, while BREEAM-certified commercial integrators prioritize protocol reliability over unit cost.
Supply Chain Analysis
Strategic stockpiling of LED die and radio modules characterizes procurement behavior among European fixture manufacturers confronting REACH compliance timelines and material passport documentation requirements. Captive fabrication in Austria and Malaysia anchors high-performance component supply, while Yangtze River Delta facilities produce consolidated system-on-chip architectures for export markets. Solder alloy and encapsulant reformulation under EU substance thresholds creates raw material dependencies on pre-validated chemical suppliers. Single-source vulnerability concentrates in ams-OSRAM's Austrian LED fabrication position. Distribution runs through professional electrical distributors in Western Europe and North America, with direct-to-platform channels displacing traditional wholesale in residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national US homebuilders and Chinese ecosystem platforms, compressing specification authority for traditional electrical distributors and fragmenting procurement across multi-channel fulfillment models.
For Market Incumbents: Compound protocol leadership through Matter interoperability certification to defend against firmware-agnostic hardware platforms eroding Zigbee-specific margins. Deepen backward integration into semiconductor sourcing by securing long-term die supply agreements with Yangtze River Delta fabricators. Prioritize hospitality channel control through BREEAM-certified office specification wins that lock out retrofit competitors.
For New Entrants and Emerging Players: SRRC certification fast-track through MIIT's 2.4 GHz radio gates filters competitor density for brands willing to navigate China's compliance timeline, creating white space in tier-one city new construction. Target Eastern European price-sensitive segments where deferred LED conversion cycles persist. Pursue private-label manufacturing partnerships with platform-aligned ecosystem bundlers to bypass distributor margin capture.
For Investors and Strategic Acquirers: The market sits at a protocol-consolidation phase that favors firmware engineering specialists with multi-stack expertise. Long-term viability hinges on Matter interoperability maturation collapsing commissioning friction into single-ecosystem experiences. Acquisition target archetype: mid-tier hardware platforms with pre-validated REACH material passports and existing SRRC certification. Watch Matter protocol adoption rates across Amazon Alexa and Google Home ecosystems as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Interoperability collapse enables single-commissioning capture of multi-ecosystem households. |
| Backward Integration into LED Fabrication | Captive semiconductor supply insulates against Austrian and Malaysian geographic concentration risk. |
| Hospitality Channel Specification | BREEAM-certified office wins anchor recurring downlight procurement across property portfolios. |
| REACH Material Passport Pre-Validation | Compliance documentation accelerates customs clearance through German and French distribution hubs. |
| SRRC Certification Arbitrage | MIIT radio gates filter competitor density for brands targeting mainland China distribution. |
Research Methodology
The analysis maps LED efficacy tiers, protocol stack implementations, and ecosystem compatibility layers, each validated through building automation integrators, electrical distributor procurement managers, firmware engineering directors, and hospitality facilities executives. Primary fieldwork combined structured interviews with secondary validation against FCC Part 15 filings, EU Ecodesign Directive modularity disclosures, MIIT SRRC certification databases, and SEC 10-K component sourcing disclosures. Bottom-up fixture shipment aggregation triangulates against top-down construction spending and smart home penetration benchmarks.
Consistency checks against external construction data and semiconductor trade flows validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product architecture, radio technology, application setting, and end-user procurement sophistication dimensions. CAGRs derived from protocol adoption curves, regulatory mandate implementation schedules, and platform ecosystem expansion trajectories. Forecast inputs included EU right-to-repair replacement cycle acceleration and tier-one Chinese urbanization completion rates.
Decision-makers should treat outputs as directional under assumptions of Matter protocol interoperability maturation and sustained EU Ecodesign enforcement; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding semiconductor supply continuity and REACH substance threshold stability. Revision becomes warranted when platform bundling penetration or hospitality construction activity crosses thresholds outside modeled sensitivity bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Explosion Proof Lighting Market
Lighting
GCC Smart Lighting Market
Lighting
OLED Lightening Panels Market
Lighting
North America Outdoor Lighting Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
Tritium Light Source Market
Lighting
Specialty Lighting Market
Lighting
Xenon Flashlamps Market
Lighting
Solar Lights Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
Global Headlight Control Module Market
Lighting
India Lighting Market
Lighting
Battery Operated Lights Market
Lighting
UAE Smart Lighting Market
Lighting
Art and Museum Lighting Market
Lighting
Indicator Lights Market