
 Ultraviolet Lamps Market | 2026-2036
Ultraviolet Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Ultraviolet Lamps Market Analysis
The EU F-Gas Regulation is restructuring procurement criteria for UV lamps across European industrial plants, compelling manufacturers to phase out mercury-dependent systems. Signify N.V. leverages its semiconductor foundry partnerships to secure LED chip supply for UV-C arrays. Heraeus Holding GmbH anchors the medium-pressure arc lamp segment through captive quartz glass production in Hanau. Xylem Inc. competes in municipal water tenders by bundling UV reactors with sensor-based dose control.
Ultraviolet lamps generate electromagnetic radiation in the 100–400 nanometer wavelength band, with low-pressure mercury variants emitting monochromatic 254 nm output for nucleic acid disruption and medium-pressure systems producing polychromatic 200–400 nm spectra for advanced oxidation processes. Low-pressure lamps dominate installed base volume in drinking water facilities, though LED lamps represent the fastest-growing product category as solid-state sources eliminate warm-up latency and mercury handling protocols. Water treatment commands the largest application share, while surface disinfection in hospitality settings generates premium pricing for portable unit configurations.
EPA's Ultraviolet Disinfection Guidance Manual mandates validated dose monitoring for public water systems, compelling utilities to source NSF/ANSI 55 certified equipment. Japan's PMDA enforces sterility assurance levels for medical device manufacturers employing UV sterilization in cleanroom environments. ECHA's REACH restrictions on mercury additives accelerate LED substitution timelines across EU member states. Stakeholders must weigh quartz sleeve supply concentration against gallium nitride substrate availability when committing to lamp technology roadmaps.
Market Dynamics
LED UV-C solid-state sources are compressing replacement cycles across municipal and commercial installations as mercury vapor phase-outs accelerate under binding multi-jurisdictional mandates.
Growth Catalysts
- EPA Ultraviolet Disinfection Guidance Manual:Validated dose monitoring requirements compel US public water systems to upgrade aging low-pressure mercury infrastructure.
- EU F-Gas Regulation:Binding phase-out timelines for mercury-dependent industrial equipment force European manufacturing plants toward LED-based air and surface treatment systems.
- Quartz glass supply concentration:Captive production capabilities in Germany and Japan secure medium-pressure arc lamp availability for wastewater reuse megaprojects.
Market Restraints
- Gallium nitride substrate scarcity:LED UV-C chip fabrication depends on constrained 6-inch and 8-inch wafer supply from semiconductor foundries.
- Mercury waste handling protocols:Spent lamp disposal under ECHA REACH restrictions imposes recurring compliance costs on European facility operators.
- Warm-up latency in legacy infrastructure:Existing low-pressure mercury systems cannot match LED instantaneous output, creating technical lock-in for utilities with recent capital deployment.
Strategic Opportunities
- Japan's PMDA sterility assurance mandates:Medical device cleanroom specifications create premium demand for validated UV sterilization protocols.
- Hospitality surface disinfection:Portable unit configurations command pricing premiums in hotel and cruise ship applications.
- Sensor-integrated dose control:Real-time monitoring convergence with UV reactor systems enables performance-based service contracts in municipal tenders.
Industry Challenges
- NSF/ANSI 55 certification timelines:Third-party validation for drinking water equipment extends product launch schedules by 12-18 months.
- Quartz sleeve thermal degradation expertise:Specialized engineering talent for medium-pressure system maintenance concentrates among legacy arc lamp specialists.
- Legacy control system integration:SCADA compatibility requirements complicate LED retrofit deployments in aging municipal treatment plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultraviolet Lamps Market |
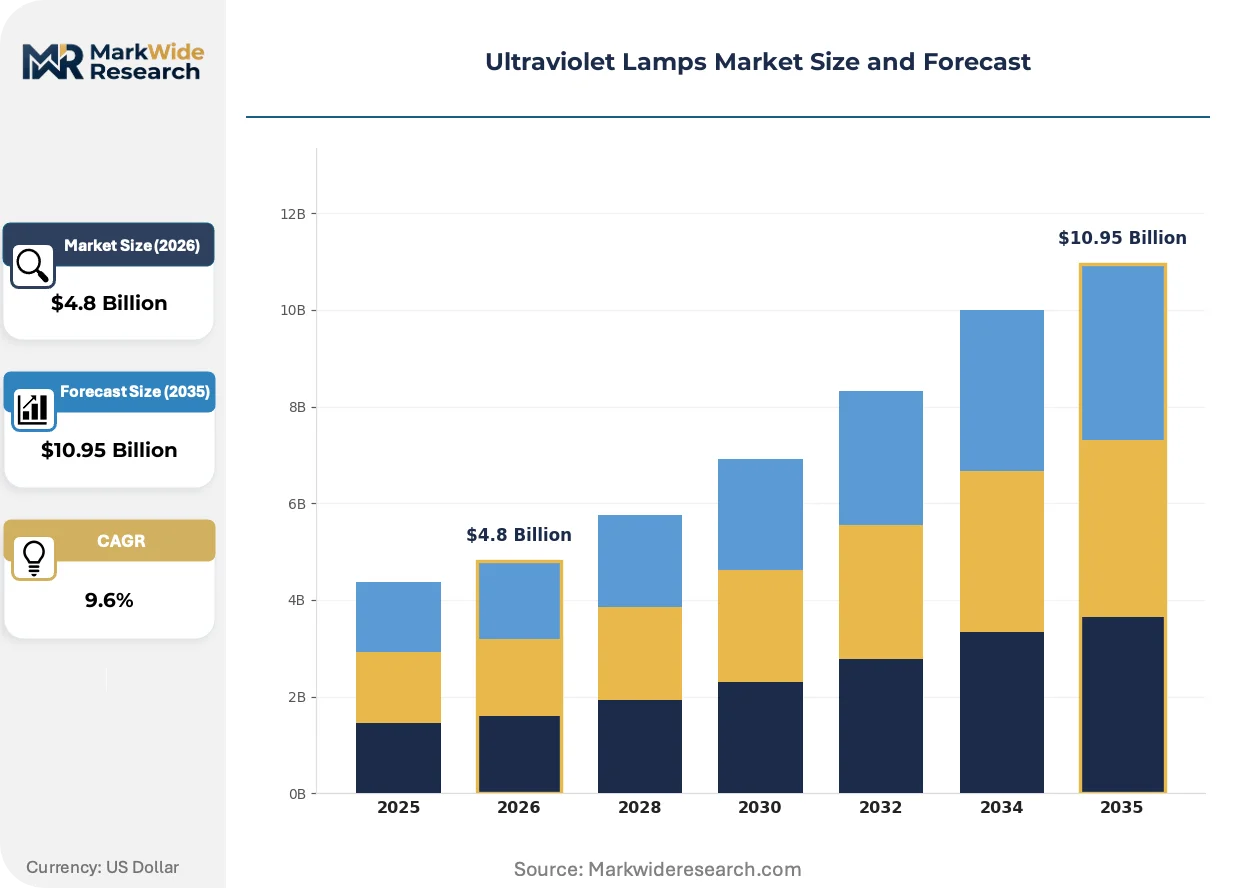
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Pressure Lamps, Medium-Pressure Lamps, Mercury Vapor Lamps, LED Lamps Application: Water Treatment, Surface Disinfection, Air Purification, Medical Equipment Sterilization End User: Healthcare Facilities, Educational Institutions, Industrial Plants, Hospitality Sector Installation Type: Fixed Installation, Portable Units, Wall-Mounted Systems, Ceiling-Mounted Systems |
| Companies Covered | Signify N.V. (Philips Lighting), Heraeus Holding GmbH, Xylem Inc., Atlantic Ultraviolet Corporation, American Ultraviolet, Ushio Inc., OSRAM GmbH, Nikkiso Co. Ltd., AlphaCure Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultraviolet Lamps Market Emerging Trajectories
Mercury-free solid-state emission sources are rewriting equipment procurement criteria across regulated end-uses, compressing technology substitution timelines and reconfiguring supply chain priorities.
Aluminum gallium nitride LED chips emitting at 265-280 nm wavelengths are expanding into nucleic acid disruption applications previously served by monochromatic mercury vapor lamps. Municipal utilities in Germany and Japan are piloting array-based systems for secondary disinfection. The technology is expanding into premium-priced portable configurations for hospitality and healthcare surface treatment.
Japan's Ministry of Health has tightened pathogen standards for recycled water in industrial processes, compelling medium-pressure system upgrades for advanced oxidation capability. Chemical plants in Osaka and Nagoya industrial corridors are retrofitting polychromatic UV reactors to meet effluent reuse specifications. Equipment vendors are bundling oxidation monitoring sensors to demonstrate compliance in facility audits.
Performance-based procurement models now dominate European municipal water tenders, displacing capital-purchase contracts with 10-year service agreements incorporating guaranteed dose delivery. Xylem and Heraeus are restructuring sales organizations around outcome metrics. Germany's Ruhr region utilities have adopted this structure for all UV disinfection infrastructure awards since 2024.
Ultraviolet Lamps Market Segmentation
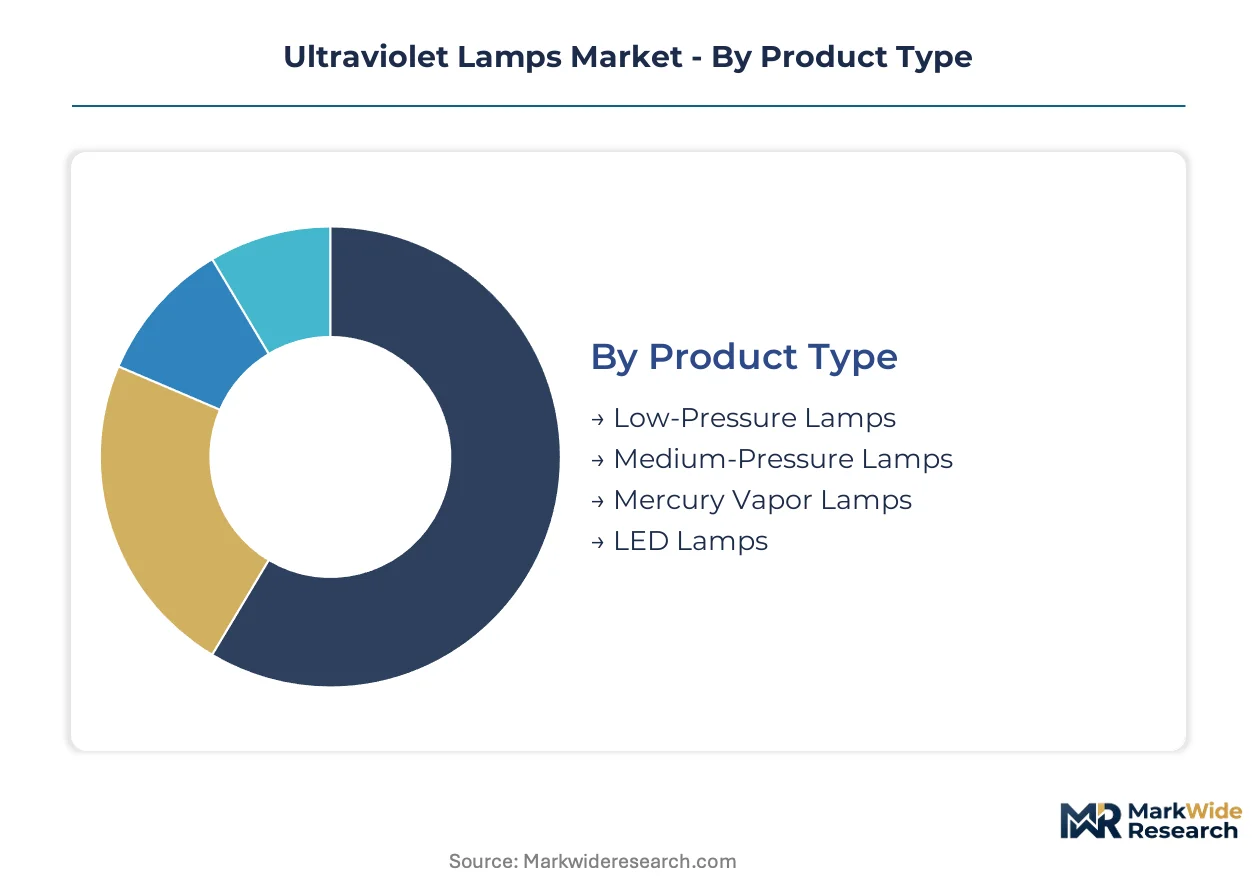
Technology substitution cycles and regulatory phase-outs are fragmenting procurement patterns across lamp categories. Equipment buyers now weight mercury compliance timelines against LED retrofit economics when segmenting capital budgets.
Product Type:
Replacement cycles accelerate where mercury-dependent systems face binding phase-out deadlines.
- Low-Pressure Lamps:Monochromatic 254 nm mercury vapor sources dominate installed base volume in municipal drinking water facilities. US utilities under EPA Ultraviolet Disinfection Guidance Manual mandates source these for validated dose compliance in legacy infrastructure.
- LED Lamps:Solid-state aluminum gallium nitride chips eliminate warm-up latency and mercury handling protocols entirely. Germany's Ruhr region utilities and Japan's Ministry of Health pilot sites are deploying 265-280 nm arrays for secondary disintraction.
- Medium-Pressure Lamps:Polychromatic 200-400 nm spectra serve advanced oxidation processes in wastewater reuse megaprojects.
- Mercury Vapor Lamps:Conventional arc technology retains residual share where ECHA REACH disposal protocols have not yet triggered replacement.
Volume placements concentrate in Low-Pressure Lamps; the faster expansion belongs to LED Lamps.
Application:
End-use specifications diverge sharply between continuous-flow infrastructure and intermittent surface treatment protocols.
- Water Treatment:Municipal utilities command the largest revenue share, with validated dose monitoring bundled into sensor-integrated reactor systems. China's industrial corridors and Germany's Ruhr utilities drive concentrated tender activity for secondary and tertiary disinfection.
- Surface Disinfection:Hospitality operators in cruise ship and hotel configurations pay premium pricing for portable, validated sterilization protocols. Japan's PMDA sterility assurance mandates create compliance-driven demand in medical device manufacturing cleanrooms.
- Air Purification:Commercial building retrofits favor LED-based systems to meet EU F-Gas Regulation timelines.
- Medical Equipment Sterilization:Cleanroom specifications require documented sterility assurance levels for device packaging and assembly environments.
Revenue gravity centers on Water Treatment; Surface Disinfection captures the steepest expansion trajectory.
End User:
Facility type dictates procurement structure, from capital-purchase municipal contracts to performance-based service agreements.
- Healthcare Facilities:Hospitals and clinics source UV-C systems for patient room turnover and surgical suite sterilization, with infection control committees driving specification authority.
- Industrial Plants:Chemical processors in Osaka and Nagoya corridors retrofit medium-pressure reactors for effluent reuse under tightened pathogen standards.
- Educational Institutions:Campus facilities balance first-cost constraints against maintenance staffing limitations when evaluating fixed versus portable configurations.
- Hospitality Sector:Hotel chains and cruise operators prioritize guest-visible disintraction protocols for brand differentiation.
Contract value concentrates in Industrial Plants; Hospitality Sector bookings are climbing the fastest.
Installation Type:
Physical mounting configuration determines integration complexity with existing HVAC and control infrastructure.
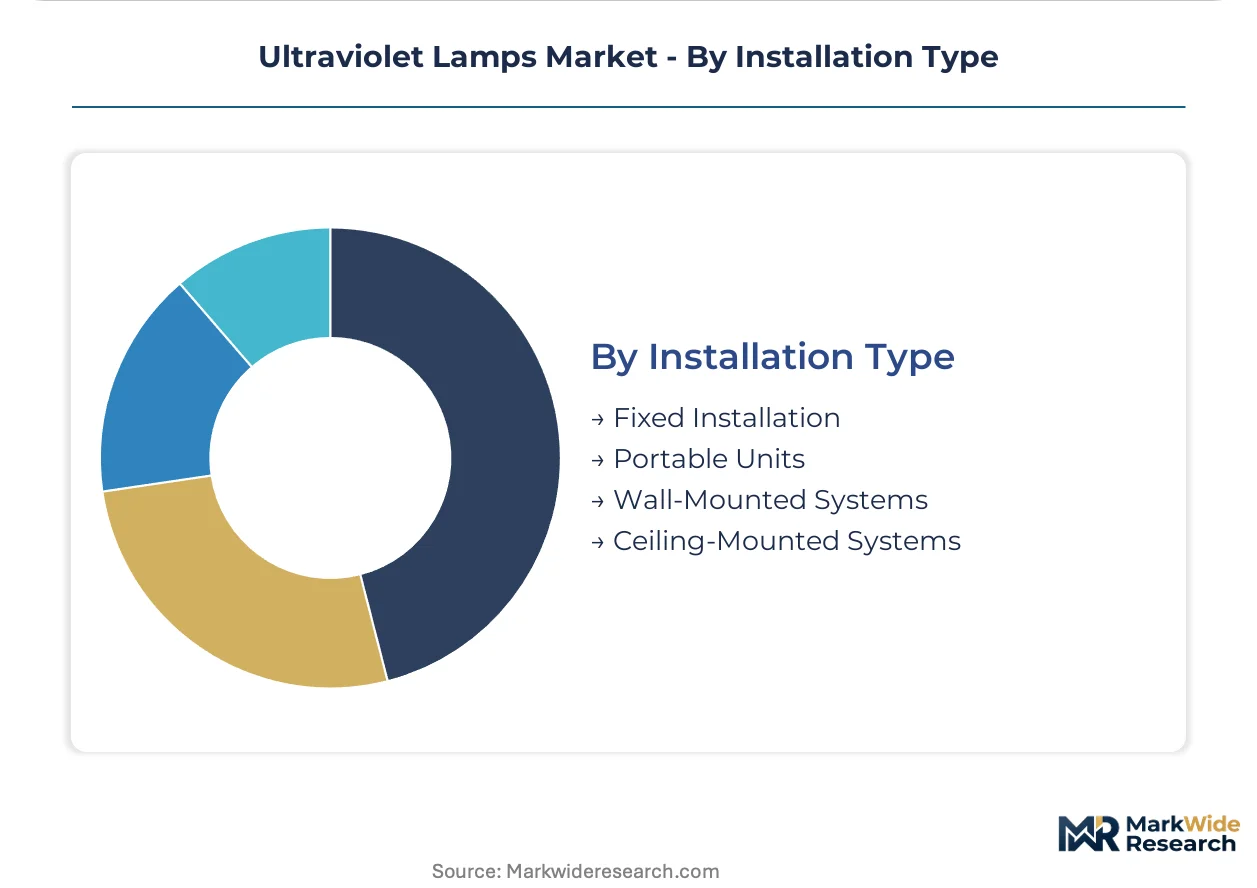
- Fixed Installation:Municipal water treatment reactors and commercial air handling systems require permanent duct or pipeline integration with SCADA compatibility.
- Portable Units:Battery-powered or corded configurations serve event-driven sterilization needs in hospitality and healthcare settings without infrastructure modification.
- Wall-Mounted Systems:Upper-room UVGI installations target airborne pathogen reduction in occupied spaces with constrained floor area.
- Ceiling-Mounted Systems:Recessed fixtures integrate with architectural lighting plans for continuous low-dose ambient treatment.
Deployment volume concentrates in Fixed Installation; Portable Units are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan for quartz glass and medium-pressure systems, while consumption spreads across municipal utilities in the United States, China, and industrial corridors in Japan.
United States
EPA's Ultraviolet Disinfection Guidance Manual drives validated dose monitoring upgrades across aging municipal infrastructure. The agency mandates NSF/ANSI 55 certification for public water systems. Utilities in California and Texas corridors source low-pressure mercury replacements under tightening pathogen standards.
Germany
Ruhr region utilities adopted performance-based procurement models for UV disinfrastructure awards since 2024. The EU F-Gas Regulation binds manufacturing plants to mercury phase-out timelines. Hanau's captive quartz glass production secures medium-pressure arc lamp availability for wastewater reuse megaprojects.
Japan
Osaka and Nagoya industrial corridors retrofit polychromatic UV reactors for effluent reuse under Ministry of Health pathogen standards. METI oversees industrial water recycling compliance frameworks. PMDA sterility assurance mandates create premium demand for medical device cleanroom sterilization protocols.
China
Industrial plants in Yangtze River Delta and Pearl River Delta drive concentrated demand for medium-pressure systems in wastewater reuse projects. MEE enforces effluent quality standards for chemical processors. Municipal utilities in Beijing-Tianjin-Hebei cluster pilot LED array deployments for secondary disinfection.
Ultraviolet Lamps Market Vendor Landscape
The competitive structure tilts toward technology specialists with captive material capabilities. Quartz glass supply concentration and semiconductor foundry partnerships create defensive moats for established players. Two strategic archetypes dominate: legacy arc lamp specialists with backward integration into quartz production, and LED array assemblers securing gallium nitride substrate supply. Competitive moves center on bundling sensor-integrated dose control systems and restructuring sales organizations around performance-based service contracts.
Among European-based manufacturers, Heraeus Holding GmbH exemplifies the captive-material archetype through in-house quartz glass production. Signify N.V. and Xylem Inc. represent divergent positioning strategies—Signify leverages semiconductor partnerships for LED chip supply, while Xylem competes through bundled reactor and monitoring systems in municipal tenders. These three occupy distinct competitive vectors rather than direct confrontation.
| Leading Market Players |
|---|
| Signify N.V. (Philips Lighting) |
| Heraeus Holding GmbH |
| Xylem Inc. |
| Atlantic Ultraviolet Corporation |
| American Ultraviolet |
| Ushio Inc. |
| OSRAM GmbH |
| Nikkiso Co. Ltd. |
| AlphaCure Ltd. |
| Others |
Supply Flow & Price Mechanics
Municipal water utilities in the United States and Germany anchor procurement volume and negotiate multi-year service contracts with embedded dose-performance guarantees. Their consolidated buying power compresses margins for equipment vendors while rewarding suppliers with captive quartz glass or semiconductor foundry partnerships.
Pricing Analysis
Margin tightening in LED UV-C arrays reflects gallium nitride substrate scarcity and foundry allocation constraints. Three-tier pricing structure across premium validated systems, standard municipal configurations, and economy-grade portable units separates buyers by certification tier and after-sales bundling. Cost-down pressure on mercury vapor replacements accelerates because ECHA REACH disposal protocols impose recurring compliance burdens. Industrial plants in Japan's Osaka corridor show least price sensitivity due to Ministry of Health enforcement timelines.
Supply Chain Analysis
Specialized quartz glass technicians in Hanau and semiconductor process engineers in Taiwan constrain capacity expansion for lamp manufacturers. Germany and Japan anchor medium-pressure arc lamp supply through captive quartz production, while Taiwan and South Korea feed LED chip fabrication. Raw material dependencies span high-purity synthetic quartz, aluminum gallium nitride wafers, and mercury amalgam for legacy systems. Single-source vulnerability concentrates in 6-inch and 8-inch gallium nitride substrate supply. Distribution runs through direct municipal tender channels and specialized industrial water treatment integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultraviolet lamps market rewards players securing upstream control over quartz glass or gallium nitride substrate supply as regulatory phase-outs compress technology substitution timelines.
For Market Incumbents: Extend backward integration into synthetic quartz production or semiconductor foundry partnerships to defend against LED substitution accelerating under EU F-Gas Regulation mandates. Lock in multi-year municipal service contracts with sensor-integrated dose monitoring to raise switching costs for utilities evaluating retrofit options. For New Entrants and Emerging Players: Portable surface disinfection units for hospitality operators in cruise ship and hotel configurations offer penetrable white space with premium pricing tolerance. Target medical device cleanroom sterilization protocols under Japan's PMDA sterility assurance mandates as a compliance-driven entry vector with documented validation requirements. For Investors and Strategic Acquirers: The window for entry favors specialists with captive material capabilities or validated sensor-integrated systems. Acquisition candidates include medium-pressure arc lamp specialists with Hanau-region quartz supply or LED array assemblers with locked gallium nitride wafer allocation. Watch ECHA REACH enforcement intensity and EPA Ultraviolet Disinfection Guidance Manual upgrade cycles as inflection signals for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quartz Glass Production | Hanau-based synthetic quartz capacity secures medium-pressure arc lamp availability for wastewater reuse megaprojects. |
| Semiconductor Foundry Partnership | Locked gallium nitride wafer allocation from Taiwan foundries insulates LED UV-C chip supply against substrate scarcity. |
| Sensor-Integrated Dose Control | Real-time monitoring convergence enables performance-based service contracts in German Ruhr region municipal tenders. |
| NSF/ANSI 55 Certification Investment | Third-party validation accelerates EPA-mandated equipment approvals for US public water system upgrades. |
| Medical Device Cleanroom Validation | Documented sterility assurance protocols unlock Japan PMDA-compliant sterilization equipment premiums. |
Methodological Framework
Trade association filings, customs import records, and municipal procurement databases formed the secondary backbone for demand quantification. Primary interviews with water utility procurement officers, semiconductor foundry supply managers, quartz glass production engineers, and industrial wastewater treatment plant operators validated capacity and pricing assumptions. Bottom-up and top-down triangulation cross-checked segment-level estimates against aggregate market boundaries.
Bottom-up modeling built from utility capex disclosures, industrial facility audit records, and equipment shipment tracking across lamp technology categories. Segmentation dimensions included product type, application end-use, installation configuration, and geographic regulatory cluster. CAGRs derived from replacement cycle analysis and regulatory phase-out timeline alignment. Forecast inputs incorporated EPA Ultraviolet Disinfection Guidance Manual enforcement schedules and EU F-Gas Regulation compliance deadlines.
Revisions become necessary when gallium nitride substrate supply disruptions, ECHA REACH enforcement intensity shifts, or municipal budget freeze triggers materialize. Forecasts reflect documented assumptions about regulatory timeline adherence and technology substitution elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
GCC Smart Lighting Market
Lighting
Lighting Fixture Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Global Work Lights Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Europe Lighting Control Systems Market
Lighting
Programmable Stage Lighting Market
Lighting
Gesture Control Light Market
Lighting
Global Headlight Control Module Market
Lighting
Tritium Light Source Market
Lighting
Industrial Lighting Cybersecurity Market
Lighting
Digital Light Processing Technology Market
Lighting
North America Smart Lighting Market
Lighting
Bulb Market
Lighting
Explosion Proof Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market