
 Global Glass Flake Coatings Market | 2026-2036
Global Glass Flake Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Flake Coatings Market Intelligence
The International Maritime Organization's stricter regulations on ballast water treatment systems is consolidating demand for high-performance, long-life corrosion protection. Akzo Nobel N.V. leverages its extensive portfolio to serve demanding marine and offshore sectors. The Sherwin-Williams Company competes through its established distribution networks in the North American industrial maintenance market, while Jotun A/S specializes in advanced solutions for harsh environments.
Glass flake coatings are composite materials incorporating microscopic glass lamellae, typically C-glass or E-glass, within a polymer resin matrix. These flakes create a tortuous path for corrosive agents, significantly enhancing barrier properties against chemicals and moisture ingress. Epoxy glass flake systems lead the market for corrosion protection applications due to superior adhesion. Vinyl glass flake coatings represent a key segment for chemical barrier needs in storage tanks.
Compliance with standards from the US EPA regarding volatile organic compounds and the EU's REACH framework governs product formulation and market access. Furthermore, ISO 20340 specifies performance requirements for protective paint systems in offshore structures, influencing product development priorities. The critical decision for formulators is balancing enhanced protective performance with evolving environmental compliance mandates across different jurisdictions.
Market Dynamics
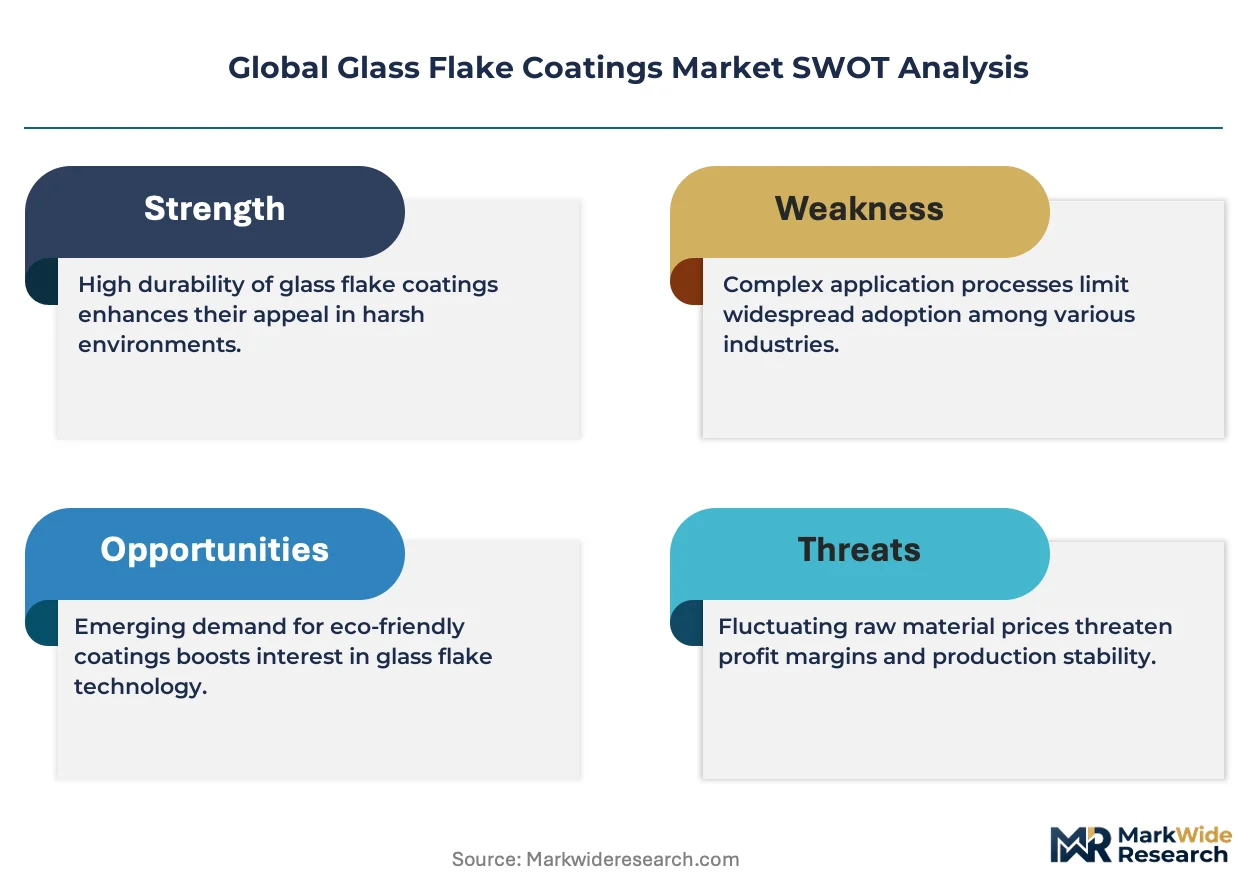
The central dynamic in the glass flake coatings market is the balance between achieving superior barrier performance for harsh environments and complying with increasingly stringent global environmental regulations on volatile organic compounds from bodies like the US EPA.
Growth Catalysts
- IMO Regulations:The International Maritime Organization's Ballast Water Management Convention requires high-performance coatings for treatment systems, directly stimulating demand for long-life corrosion protection in the marine sector.
- Offshore Wind Expansion:Growth in offshore wind energy necessitates extensive use of glass flake coatings for monopiles, transition pieces, and substations exposed to highly corrosive marine splash zones.
- Shipbuilding Concentration:Sustained investment in new vessel construction and repair, particularly within the major shipbuilding hubs of South Korea and China, provides a concentrated and continuous source of demand.
Market Restraints
- Raw Material Volatility:Price fluctuations for key inputs, especially epoxy resins and specialty glass types like C-glass and E-glass, create margin pressure and complicate long-term project bidding for formulators.
- Application Complexity:The requirement for specialized plural-component spray equipment and highly skilled, certified applicators limits adoption in general industrial maintenance where ease of use is prioritized.
- Substitution Threat:Advances in high-solid, flake-free epoxy and polyurethane systems offer comparable performance in moderately corrosive environments, presenting a viable alternative with simpler application protocols.
Strategic Opportunities
- Wastewater Infrastructure:Aging municipal water and wastewater treatment infrastructure in North America and Europe requires extensive refurbishment, creating an opportunity for coatings that resist chemical and microbial corrosion.
- Bio-Based Resins:Developing formulations that incorporate bio-based or recycled content for the polymer matrix can create a strong market differentiator, appealing to asset owners with corporate sustainability goals.
- Desalination Plants:Construction of new large-scale desalination facilities, especially in the Middle East, represents a significant opportunity due to the extreme corrosion and abrasion resistance required in their process vessels and piping.
Industry Challenges
- Regulatory Fragmentation:Formulators face the challenge of developing products that comply with a patchwork of different VOC emission standards, from the EU's overarching REACH framework to specific state-level rules in the United States.
- Applicator Skill Gap:A persistent shortage of technicians trained and certified in correct surface preparation and application techniques for glass flake systems can lead to coating failures and reputational risk.
- Certification Timelines:The lengthy and expensive process to achieve performance validation against standards like ISO 20340 for new, innovative formulations can act as a barrier to market entry and slow the pace of innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Flake Coatings Market |
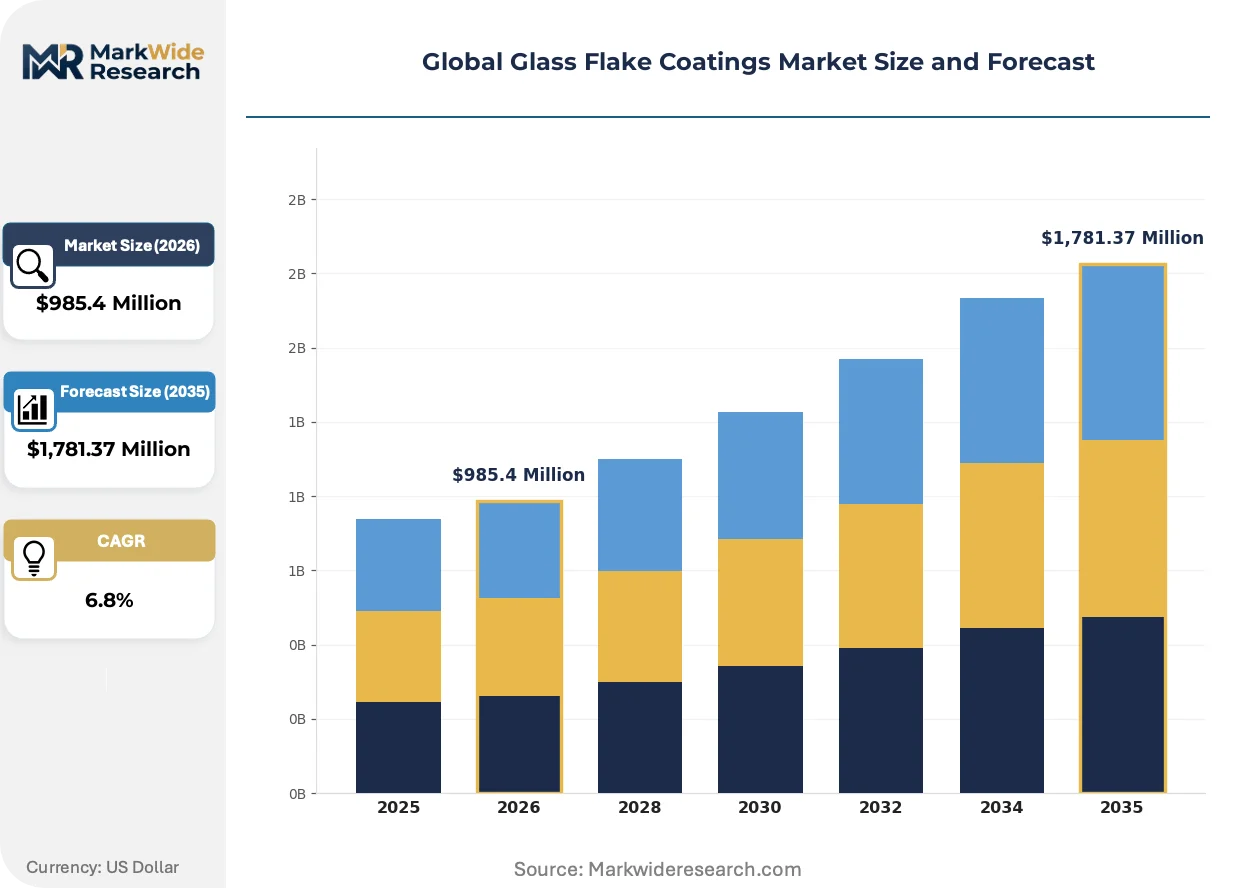
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,781.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Glass Flake, Polyester Glass Flake, Vinyl Glass Flake, Polyurethane Glass Flake Application: Corrosion Protection, Fire Resistance, Chemical Barrier, Waterproof Coating, Abrasion Resistance End User: Marine Manufacturers, Oil & Gas Facilities, Construction Firms, Infrastructure Developers Deployment: Brush Application, Spray Coating, Roll Coating, Dip Coating |
| Companies Covered | Jotun A/S, Nippon Paint Holdings Co., Ltd., The Sherwin-Williams Company, RPM International Inc., Kansai Paint Co., Ltd., PPG Industries, Inc., Hempel A/S, BASF SE, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Flake Coatings Market Strategic Shifts & Innovations
Material science advancements are pushing glass flake coatings beyond simple barrier protection. Formulations are evolving to incorporate new functionalities, while digital tools are improving application quality control and lifecycle management for critical infrastructure assets.
Nanomaterial enhancement, specifically the incorporation of graphene, offers improved mechanical strength and thermal conductivity in coatings. The aerospace and defense sectors are evaluating these next-generation composites for assets where performance gains justify the cost premium. This advanced material science is converging with traditional glass flake chemistry to create hybrid systems that provide unprecedented levels of durability.
The European Union's REACH regulation continues to restrict the use of certain chemical substances, impacting resin and additive choices. This is forcing a reformulation away from legacy solvents and toward lower-VOC or solvent-free epoxy and vinyl ester systems. The marine and protective coatings segments are most affected, responding by investing heavily in R&D to develop compliant systems without sacrificing performance.
Asset owners are moving away from time-based maintenance schedules toward condition-based monitoring for protective coatings. This shift de-emphasizes the initial coating cost in favor of total lifecycle cost, disrupting the traditional bid process based on price per liter. The trend is most prominent in the North Sea offshore oil and gas industry, where operators use sensor data to optimize maintenance intervals and extend asset life.
Global Glass Flake Coatings Market Segmentation
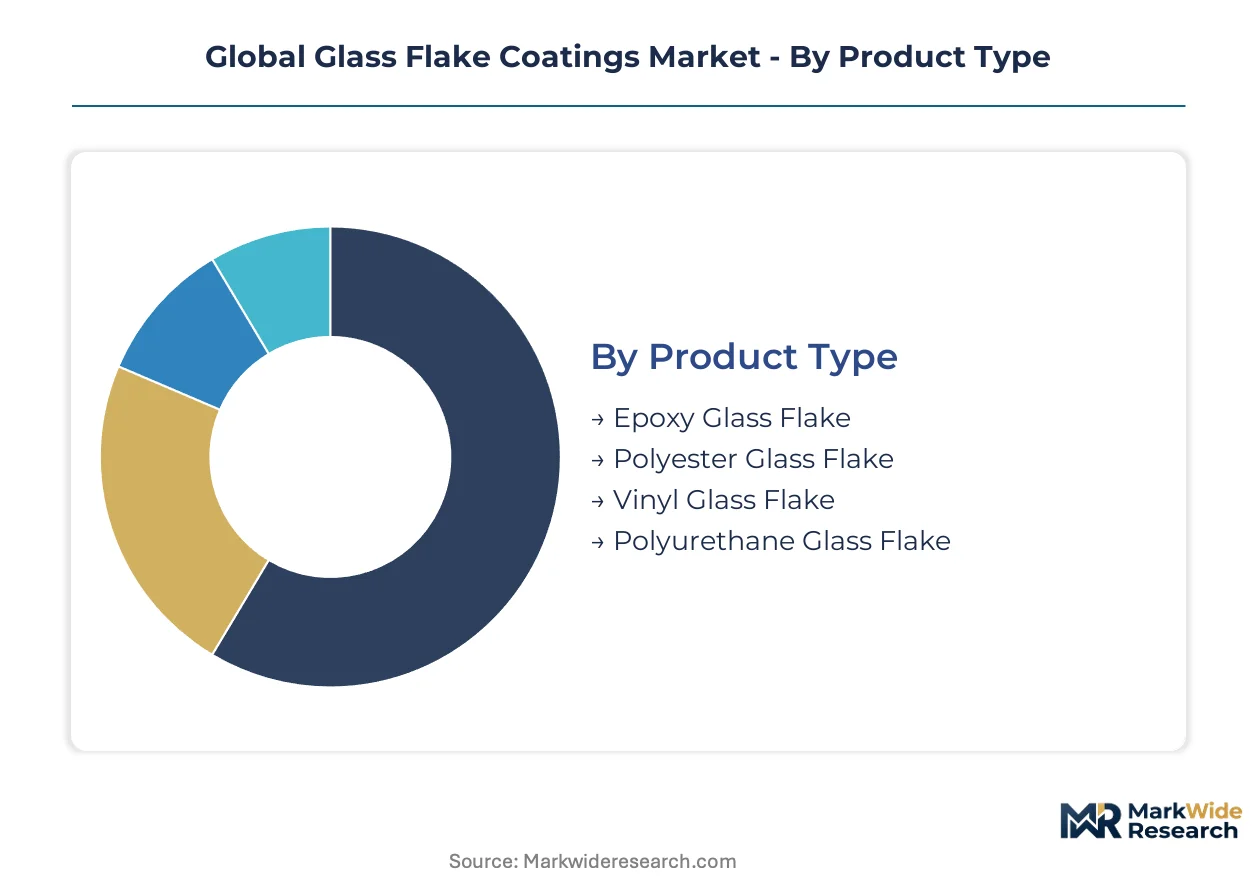
Understanding the varied applications and material compositions of glass flake coatings is crucial for market participants. The segmentation analysis provides a granular view of how different product types, end-user industries, and application methods influence demand and supply dynamics across diverse geographies.
Product Type:
Supply concentration for glass flake coatings often reflects the manufacturing capabilities and raw material availability for specific resin systems.
- Epoxy Glass Flake:These systems combine epoxy resins with glass flakes, offering exceptional adhesion and chemical resistance, making them a primary choice for corrosion protection in marine environments and offshore platforms globally. Demand concentrates in shipbuilding hubs like South Korea and China due to their superior performance in harsh conditions.
- Vinyl Glass Flake:Comprising vinyl ester resins and glass flakes, these coatings excel in chemical barrier applications, particularly for storage tanks and process vessels handling aggressive chemicals. The need for robust chemical containment in industrial facilities across Europe and North America drives their adoption.
- Polyester Glass Flake:Polyester-based glass flake coatings provide good water resistance and mechanical strength, finding utility in general industrial maintenance and some infrastructure projects.
- Polyurethane Glass Flake:Offering excellent abrasion resistance and flexibility, polyurethane glass flake systems are gaining traction in areas requiring both impact protection and corrosion resistance.
Today's leader: Epoxy Glass Flake. Tomorrow's challenger: Polyurethane Glass Flake.
Application:
The specific performance requirements of an application dictate the selection and formulation of glass flake coating systems.
- Corrosion Protection:This application segment dominates, utilizing glass flakes to create a tortuous path that significantly impedes corrosive agents from reaching the substrate. Marine vessels, oil and gas pipelines, and industrial infrastructure worldwide rely on these coatings for extended asset life.
- Chemical Barrier:Glass flake coatings form an impermeable layer against a wide range of aggressive chemicals, essential for lining storage tanks, chemical processing equipment, and wastewater treatment facilities. This functionality is critical in industrial zones across Germany and the United States.
- Fire Resistance:Certain glass flake formulations contribute to fire-resistant properties, enhancing the safety profile of structures in high-risk industrial settings.
- Waterproof Coating:The barrier properties of glass flake coatings make them effective waterproof solutions for concrete structures and foundations in various construction projects.
- Abrasion Resistance:Incorporating glass flakes significantly boosts the abrasion resistance of coatings, protecting surfaces from wear and tear in heavy-duty industrial environments.
Corrosion Protection holds the largest share, while Chemical Barrier applications are expanding most quickly.
End User:
The varied operational demands and regulatory landscapes of different end-user industries shape the adoption patterns for glass flake coatings.
- Marine Manufacturers:Shipyards and vessel maintenance operations require high-performance glass flake coatings for hulls, ballast tanks, and superstructures to combat severe saltwater corrosion. Major shipbuilding nations such as South Korea, China, and Norway represent significant demand centers.
- Oil & Gas Facilities:Offshore platforms, refineries, and pipelines in regions like the North Sea and the Middle East utilize glass flake coatings for extreme corrosion and abrasion protection. These environments necessitate coatings that withstand constant exposure to hydrocarbons and harsh weather.
- Construction Firms:Construction companies deploy glass flake coatings for long-term protection of concrete and steel structures in bridges, tunnels, and commercial buildings.
- Infrastructure Developers:Developers of critical infrastructure, including wastewater treatment plants and power generation facilities, integrate these coatings for durability and chemical resistance.
Marine Manufacturers drive substantial volume, with Infrastructure Developers showing the steepest expansion trajectory.
Deployment:
The method of application often dictates the formulation characteristics and influences the efficiency and quality of the coating process.
- Spray Coating:This method allows for rapid and uniform application over large surface areas, making it prevalent in shipbuilding, offshore construction, and large-scale industrial projects. Specialized plural-component spray equipment is common for these high-performance coatings.
- Brush Application:Used for smaller areas, touch-ups, or intricate geometries where spray application is impractical, brush application demands skilled labor for consistent film thickness. Maintenance operations in diverse industrial settings often employ this technique.
- Roll Coating:Roll coating provides an efficient application method for flat or gently curved surfaces, balancing speed with relative ease of use.
- Dip Coating:Suitable for small, complex parts that require complete and uniform coverage, dip coating ensures all surfaces are thoroughly encapsulated by the protective layer.
Spray Coating accounts for the largest application volume, while Brush Application is steadily gaining share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The widespread adoption of glass flake coatings first scaled in regions with significant marine and offshore industrial development. These advanced protective systems became critical for infrastructure durability in harsh environments. Early innovation concentrated where severe corrosion challenges demanded superior material science.
South Korea
Demand from South Korea's robust shipbuilding industry drives substantial glass flake coating consumption for new vessel construction and maintenance. The country's national maritime regulations often align with ISO 20340 standards for protective paint systems. Major shipyards in Ulsan and Geoje consistently require high-performance coatings for hulls and ballast tanks.
China
China's rapid expansion in both shipbuilding and offshore wind energy necessitates extensive use of glass flake coatings. Strict GB standards govern the quality and performance of industrial coatings in critical infrastructure projects. Coastal manufacturing hubs like Shanghai and Dalian are key centers for offshore wind component fabrication and large-scale shipbuilding.
Norway
Norway's prominent offshore oil and gas sector, alongside its growing offshore wind industry, creates consistent demand for durable glass flake coatings. Operators adhere to stringent environmental guidelines, often influenced by the EU Green Deal's sustainability objectives. The North Sea region, with cities like Stavanger and Bergen, remains a critical hub for offshore energy asset protection.
United States
The United States sees significant demand for glass flake coatings in its aging municipal water and wastewater treatment infrastructure. US EPA regulations on volatile organic compounds influence product reformulation towards lower-VOC systems. The Gulf Coast region, with its extensive oil and gas infrastructure and marine activity, utilizes these coatings for extreme corrosion protection.
Germany
Germany's advanced industrial base and chemical processing facilities require high-performance glass flake coatings for chemical barrier applications. The EU's REACH regulation heavily impacts the formulation and market access of these protective systems. The Rhine-Ruhr region, a major industrial cluster, shows consistent demand for corrosion and chemical resistant solutions in manufacturing plants.
Global Glass Flake Coatings Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the glass flake coatings market, which exhibits a tiered structure. Large chemical conglomerates and global paint manufacturers anchor the premium segment, offering integrated solutions. Specialized formulators often focus on niche applications or specific resin systems, acting as agile innovators. Competitive dynamics center on portfolio diversification and strategic partnerships to access new end-use sectors.
Within the specialized performance coatings tier, Jotun A/S exemplifies a focus on harsh marine and offshore environments, providing advanced solutions globally. This Norwegian company competes by offering highly engineered products for extreme conditions. The Sherwin-Williams Company, a US-based entity, represents broad industrial maintenance capabilities with extensive distribution networks across North America. Akzo Nobel N.V., a large European chemical group, leverages its diverse portfolio to serve demanding marine and protective sectors worldwide, emphasizing regulatory compliance. These entities showcase varied approaches to market penetration and product specialization, from deep niche expertise to broad market coverage.
| Leading Market Players |
|---|
| Jotun A/S |
| Nippon Paint Holdings Co., Ltd. |
| The Sherwin-Williams Company |
| RPM International Inc. |
| Kansai Paint Co., Ltd. |
| PPG Industries, Inc. |
| Hempel A/S |
| BASF SE |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
Reformulation towards lower-VOC epoxy and vinyl ester systems reshapes glass flake coating cost economics by demanding new resin chemistries, simultaneously concentrating specialized raw material supply in compliant regions.
Pricing Analysis
Project-based contract pricing dominates the glass flake coatings market, driven by the specific performance requirements of large-scale infrastructure and marine projects. Price differentiation stems from performance validation against standards like ISO 20340 and the level of customization for extreme chemical or corrosive environments. Pricing softness affects general industrial maintenance applications due to competition from advanced flake-free epoxy systems. Offshore oil and gas operators and marine manufacturers exhibit lower price sensitivity compared to construction firms seeking general waterproofing solutions.
Supply Chain Analysis
Direct sales channels handle demand from major shipbuilding hubs and offshore energy fabricators, ensuring specialized technical support. Geographic supply concentration for key resins and glass flakes centers in China, South Korea, and specialty chemical producers in Europe. The market draws from a limited base of epoxy resins, vinyl ester resins, and specific C-glass and E-glass flakes, making raw material price volatility a structural supply chain risk. Distribution runs through specialized applicators for complex projects, with industrial distributors serving general maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glass flake coatings market functions as a late-cycle quality story, driven by a demand shift towards premium specifications for extended asset life in critical infrastructure. Asset owners prioritize total lifecycle cost over initial application expense, requiring superior durability.
For Market Incumbents: Deploy advanced R&D into bio-based resins and graphene-enhanced formulations to counter the substitution threat from flake-free systems. Invest in applicator training and certification programs to mitigate the skill gap and ensure proper application, which is crucial for performance validation against ISO 20340. Control key raw material supply through long-term contracts to manage price volatility and secure competitive advantage against smaller formulators.
For New Entrants and Emerging Players: Aging municipal wastewater infrastructure represents an underserved buyer archetype in North America and Europe, requiring chemical and microbial corrosion resistance. Focus on developing lower-VOC vinyl ester systems tailored for these specific chemical barrier applications, leveraging regional environmental compliance mandates. Partner with specialized local applicators to overcome application complexity and deliver certified solutions, targeting specific utility districts with documented refurbishment needs.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized formulators with strong niche expertise in chemical barrier or abrasion resistance, offering long-term viability in critical industrial segments. These firms often possess unique intellectual property in compliant resin systems or application methodologies. An acquisition target archetype includes mid-sized companies with established certification portfolios for harsh environments. The signal to watch is the increasing adoption of condition-based monitoring, which favors suppliers of high-performance, long-life coatings.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint, aligning with EU Green Deal objectives for marine and offshore sectors. |
| Certification Investment | Validates performance against ISO 20340 standards, crucial for market access in shipbuilding and offshore wind. |
| Joint Venture | Accesses new geographic markets like the Middle East for desalination plants or specific industrial segments. |
| Product Development (Bio-based) | Creates market differentiation, appealing to asset owners with corporate sustainability goals. |
| Channel Expansion | Reaches underserved municipal wastewater infrastructure developers in North America and Europe. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining extensive interviews with industry stakeholders and secondary validation. Key stakeholders include R&D directors, procurement leads at marine manufacturers, specialized applicators, and regulatory compliance officers. Secondary data sources encompass national trade statistics, corporate annual reports, and technical publications from bodies like the IMO and US EPA. This approach ensures robust bottom-up and top-down triangulation.
Market sizing and forecasts were modeled at granular levels across product type, application, end-user industry, and deployment method. This framework integrates historical data with projected trends over the analysis window, specifically considering raw material price volatility and regulatory shifts. Compound Annual Growth Rates (CAGRs) were derived from a multi-factor analysis, incorporating demand drivers from marine construction and offshore wind expansion.
Underlying measurement precision varies by segment; marine and offshore oil & gas applications carry tighter precision than general industrial maintenance. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Low Temperature Laminated Glass Market
Glass
Laboratory Glassware Market
Glass
China Flat Glass Market
Glass
Fiberglass Window Market
Glass
Glass Polishing Powder Market
Glass
United States Flat Glass Market
Glass
Silica Sol Market
Glass
Patterned Glass Market
Glass
Europe Sapphire Glass Market
Glass
Spherical Silica Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Low-E Glass Market
Glass
Solar Control Glass Market
Glass
Optical Lens Material Market
Glass
Glass Block Market
Glass
Middle-East and Africa Flat Glass Market