
 Glass Polishing Powder Market | 2026-2036
Glass Polishing Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Polishing Powder Market Insights
Performance-based slurry formulations and technical support subscriptions is realigning how glass polishing powder vendors capture recurring revenue beyond commodity tonnage. Saint-Gobain leverages its fused minerals heritage to control premium cerium oxide supply chains across European optical hubs. Tongxiang Dingliang Polishing Material Co., Ltd anchors volume production of aluminum oxide grades for Chinese architectural glass processors. Fuji Chemifa Corporation specializes in ultra-high-purity slurries for Japanese electronics producers.
Glass polishing powder comprises engineered abrasive particles, predominantly rare-earth oxides and synthetic minerals, milled to controlled particle size distributions between 0.5 and 50 micrometers for precision surface modification. The material removes subsurface damage and achieves specified roughness values on soda-lime, borosilicate, and fused silica substrates used in lenses, displays, and architectural panels. Cerium oxide dominates optical lens polishing due to its chemical-mechanical action and superior removal rates on soft glasses. Electronic display processing represents the fastest-expanding application as OLED and microLED fabrication demands sub-nanometer surface quality. Powder form retains the largest volume share, though slurry and liquid suspension formats are gaining share in automated polishing lines where dosing consistency reduces process variance.
REACH registration requirements in Europe and China's GB standards enforced by SAMR are elevating traceability and heavy-metal content thresholds for polishing powders entering consumer electronics supply chains. The EPA and OSHA frameworks in the United States govern respirable crystalline silica exposure in powder handling operations, pushing end users toward pre-mixed slurry and paste formulations. Korean MFDS pharmaceutical-grade standards are crossing over into optical manufacturing as lens producers seek ISO 13485-adjacent process documentation. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape sourcing decisions for energy-intensive rare-earth processing.
Market Dynamics
Electronics manufacturers are consolidating procurement around performance-guaranteed slurry subscriptions, compressing spot-market volumes for commodity cerium oxide powders while elevating technical service contracts as the primary revenue anchor.
Growth Catalysts
- MicroLED fabrication scale-up:Panel producers in Korean manufacturing clusters are qualifying ultra-high-purity cerium oxide slurries for sub-nanometer surface finish requirements on next-generation displays.
- China's dual carbon goals:Domestic rare-earth processors are retrofitting energy-intensive calcination lines to secure preferential supply contracts with state-backed optical component fabricators.
- REACH registration enforcement:European electronics assemblers are demanding full substance traceability documentation, locking in compliant suppliers and excluding unregistered powder traders.
Market Restraints
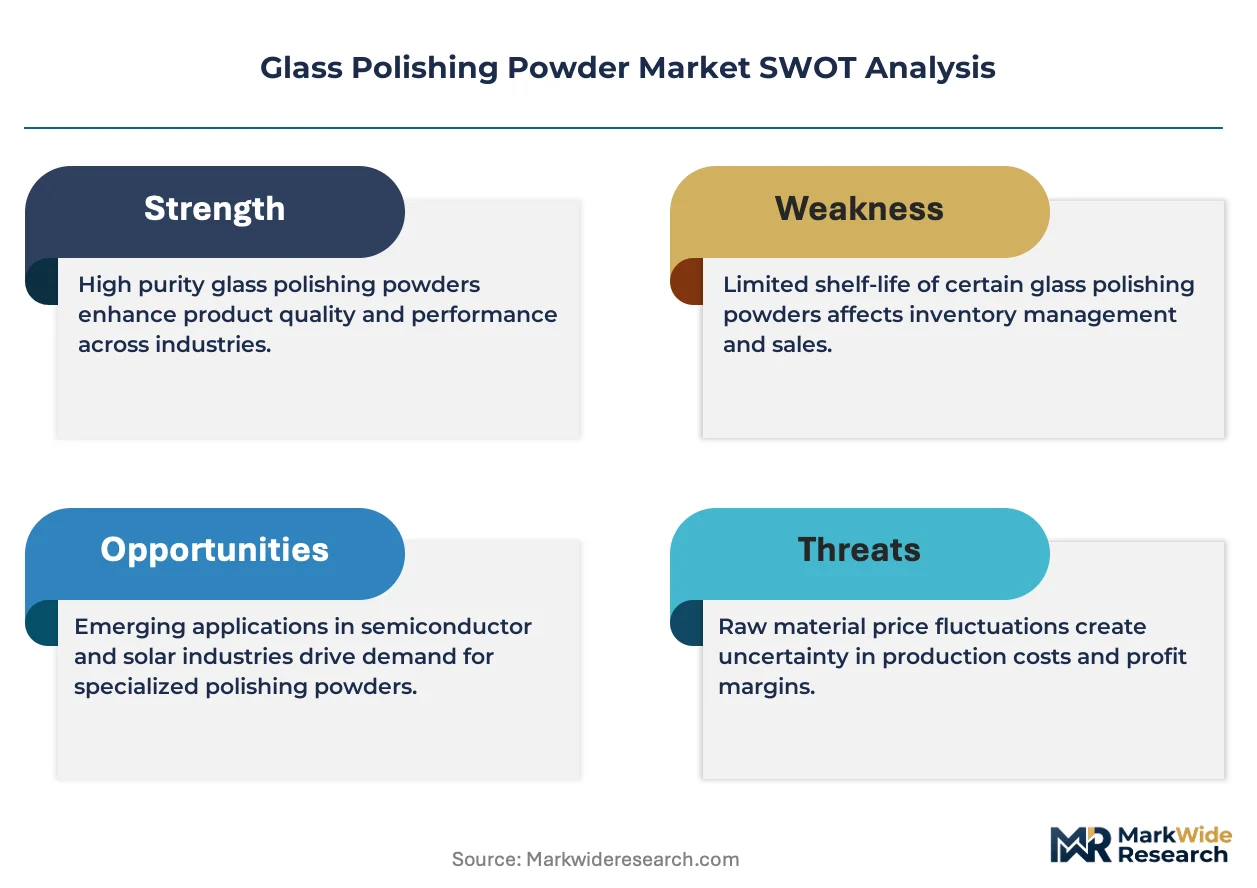
- Rare-earth oxide price volatility:Lanthanide concentrate costs swing with Chinese export quota announcements, squeezing margin predictability for formulated slurry producers.
- Single-source dependency:High-purity cerium oxide supply concentrates among three integrated processors controlling ion-adsorption clay refining capacity in southern Chinese provinces.
- Silica exposure liability:OSHA respirable crystalline silica permissible exposure limits are forcing architectural glass processors toward pre-mixed suspensions, eroding powder-form volume.
Strategic Opportunities
- Indian optical component fabrication:Domestic lens grinding operations for smartphone camera modules remain underpenetrated by formulated slurry suppliers, relying on legacy aluminum oxide compounds.
- EU Green Deal embodied carbon tracking:Polishing powder producers with verified low-carbon rare-earth processing can capture premium positioning in German automotive glass supply chains.
- Slurry-as-a-service models:Automated dosing system integration with Korean electronics fabs creates recurring revenue streams displacing bulk powder tenders.
Industry Challenges
- Particle size distribution control:Maintaining sub-micron consistency across batch scales requires specialized milling expertise scarce outside established Japanese and European equipment suppliers.
- Cross-border certification lag:MFDS pharmaceutical-grade documentation demanded by Korean lens exporters requires twelve-to-eighteen-month validation timelines, freezing new supplier entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Polishing Powder Market |
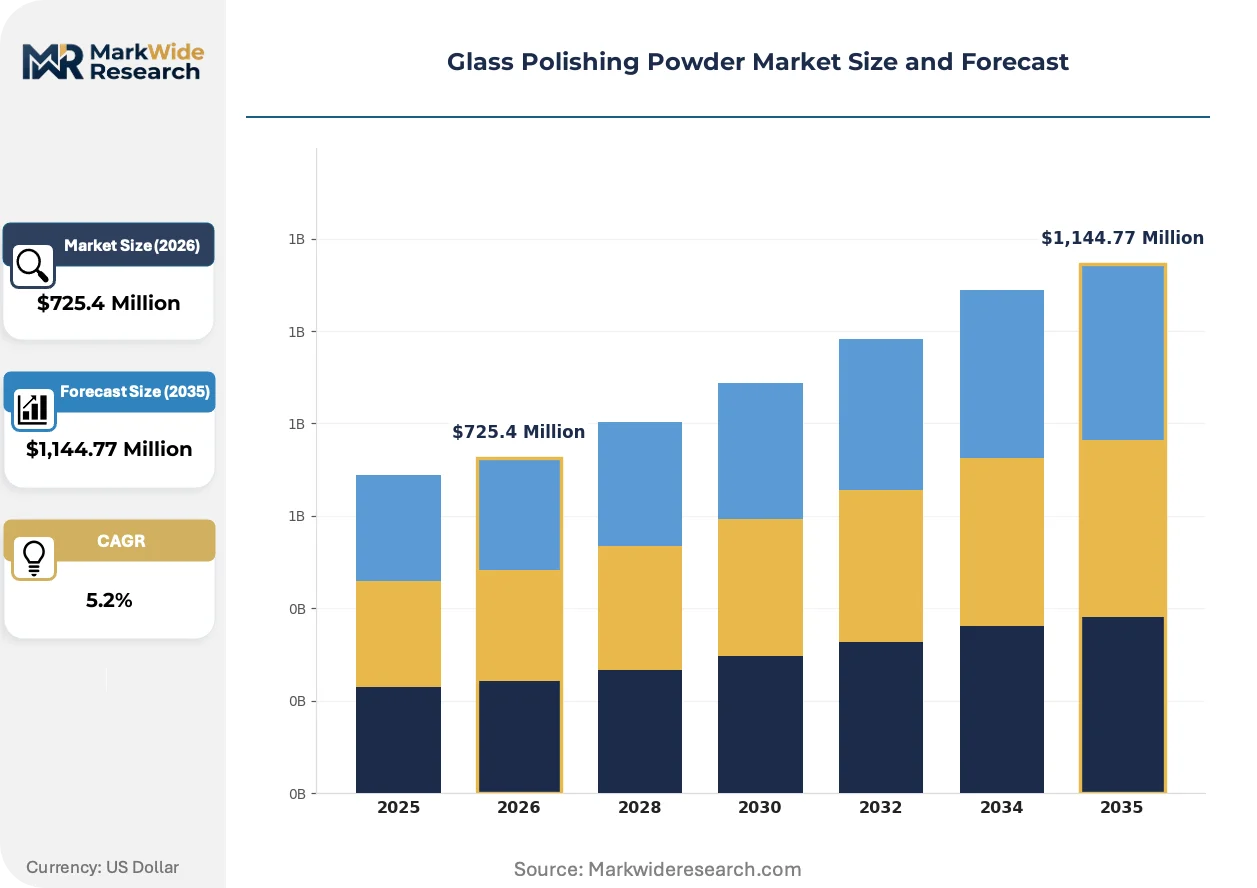
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,144.77 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cerium Oxide, Aluminum Oxide, Tin Oxide, Diamond Powder, Silica Abrasives Application: Optical Lens Polishing, Automotive Glass Refinishing, Architectural Glass Finishing, Electronic Display Processing, Decorative Glass Treatment End User: Lens Manufacturers, Vehicle Refurbishers, Construction Companies, Electronics Producers, Artisans Form: Powder, Slurry, Paste, Liquid Suspension |
| Companies Covered | Saint-Gobain, PPG Industries, AGC Inc., Solvay, Universal Photonics, 3M, Showa Chemical Industry Co., Ltd., Tongxiang Dingliang Polishing Material Co., Ltd, Fuji Chemifa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Polishing Powder Market Trends and Innovations
Precision surface finishing requirements are compressing acceptable process variance thresholds, forcing abrasive suppliers to embed real-time quality telemetry directly into slurry delivery systems rather than relying on end-user testing protocols.
Nano-engineered cerium oxide with tailored surface chemistry is integrating chemical-mechanical polishing action with selective material removal rates for heterogeneous glass substrates. Japanese electronics assemblers are adopting these formulations for fused silica waveguide fabrication. The technology is integrating process control software with abrasive chemistry, collapsing the traditional separation between consumable supply and equipment optimization.
China's GB standards for industrial chemicals are tightening heavy-metal content thresholds enforced by SAMR market surveillance inspections. Polishing powder shipments into semiconductor-adjacent supply chains now require third-party assay documentation. Electronics display processors in Guangdong and Jiangsu provinces are consolidating supplier lists to pre-qualified vendors with certified testing laboratories.
Buyer concentration among Korean and Chinese electronics fabs is compressing contract renewal cycles from annual to quarterly terms, with price and performance benchmarks reset against competitive slurry trials. Technical service responsiveness and on-site application engineering are displacing historical tonnage-based loyalty. This pattern is most visible in OLED panel polishing operations where single-fab procurement decisions redirect multi-ton annual volumes.
Glass Polishing Powder Market Segmentation
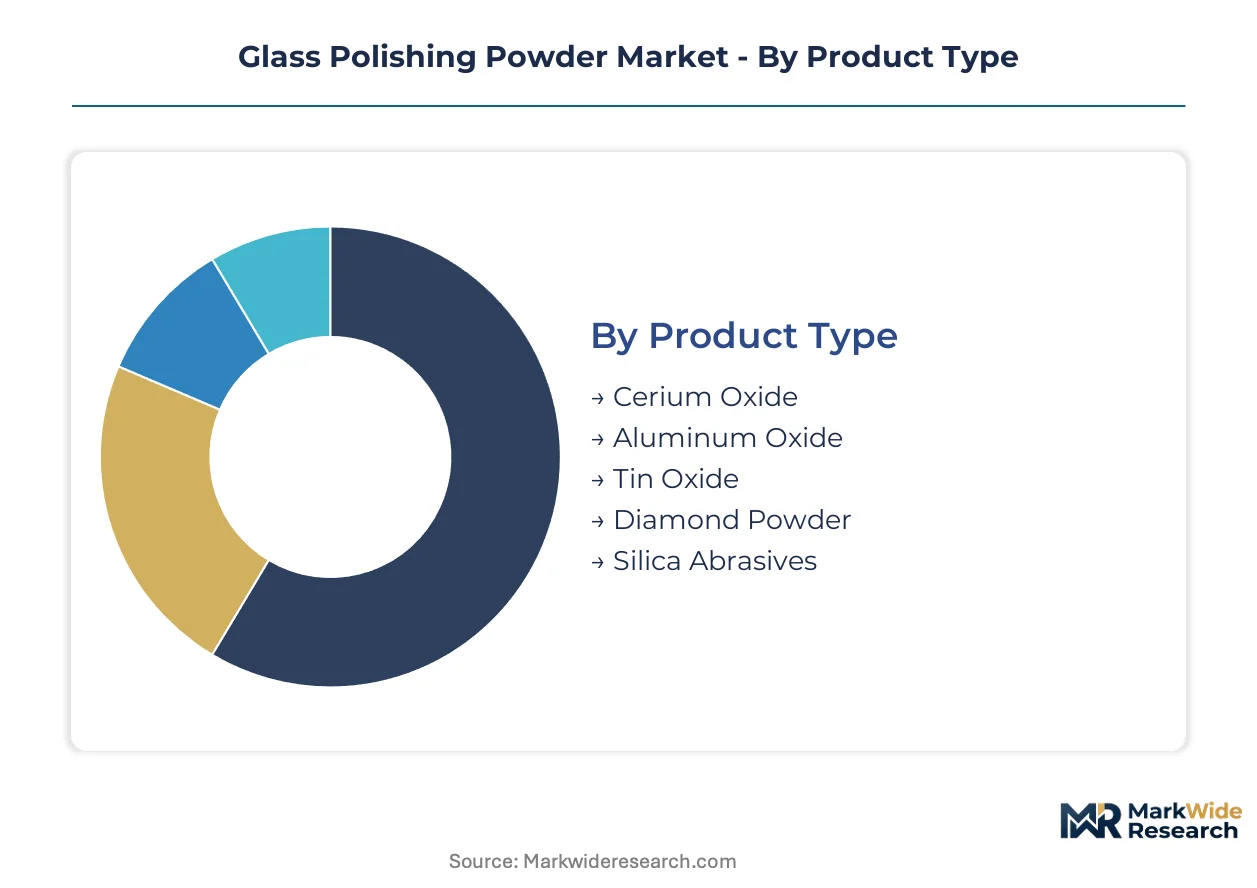
Glass polishing powder segmentation reveals how formulation chemistry and delivery format dictate regulatory burden, procurement patterns, and margin structure across precision manufacturing verticals. Certification requirements from SAMR, REACH, and MFDS fragment addressable markets by purity tier rather than geography alone.
Product Type:
Certification intensity varies sharply across oxide chemistries, with rare-earth formulations facing the heaviest documentation burdens from Chinese GB standards and European REACH registration.
- Cerium Oxide:Rare-earth oxide prized for chemical-mechanical polishing action on soft glasses. Electronics producers in Korean manufacturing clusters specify ultra-high-purity grades for sub-nanometer surface requirements, with SAMR third-party assay documentation now mandatory for semiconductor-adjacent supply chains.
- Aluminum Oxide:Synthetic corundum abrasive milled to controlled hardness for architectural and automotive substrates. Chinese construction glass processors drive volume procurement of medium-purity grades, though dual carbon retrofit costs are compressing margin pools for domestic calcination operators.
- Tin Oxide:Historical optical polishing compound retained for specialty fused silica applications.
- Diamond Powder:Superabrasive for hardened glass ceramics and precision edge finishing.
- Silica Abrasives:Cost-graded quartz derivatives facing OSHA respirable crystalline silica exposure limits in US powder-handling operations.
Cerium oxide sits at the top of the volume ranking, with aluminum oxide climbing the fastest as Chinese architectural glass capacity expands.
Application:
Surface quality specifications diverge by three orders of magnitude across applications, from architectural roughness tolerances to electronic display sub-nanometer thresholds.
- Electronic Display Processing:MicroLED and OLED fabrication demands sub-nanometer surface quality on fused silica and borosilicate substrates. Korean panel producers are consolidating procurement around performance-guaranteed slurry subscriptions with quarterly contract renewal cycles.
- Optical Lens Polishing:Precision ophthalmic and photographic lens grinding relies on cerium oxide chemical-mechanical action. Japanese equipment suppliers control specialized milling expertise for sub-micron particle distribution consistency.
- Automotive Glass Refinishing:Windshield scratch removal and edge finishing for vehicle refurbishers.
- Architectural Glass Finishing:Soda-lime panel surface preparation for construction markets.
- Decorative Glass Treatment:Artisan and specialty decorative surface modification.
Optical lens polishing retains the largest installed base, with electronic display processing expanding most quickly as microLED scale-up accelerates.
End User:
Buyer concentration and technical service expectations reshape competitive dynamics across end-user categories, with electronics fabs demanding on-site application engineering.
- Electronics Producers:Korean and Chinese display panel manufacturers with automated polishing lines. Pre-mixed slurry and liquid suspension formats are displacing powder form as dosing consistency reduces process variance.
- Lens Manufacturers:Optical component fabricators seeking ISO 13485-adjacent process documentation. MFDS pharmaceutical-grade standards require twelve-to-eighteen-month validation timelines, freezing new supplier entry.
- Vehicle Refurbishers:Automotive glass repair and refinishing operations.
- Construction Companies:Architectural glass installation and finishing contractors.
- Artisans:Small-scale decorative and specialty glass workers.
Electronics producers command the steepest pricing premiums, with lens manufacturers representing the most entrenched legacy supply relationships.
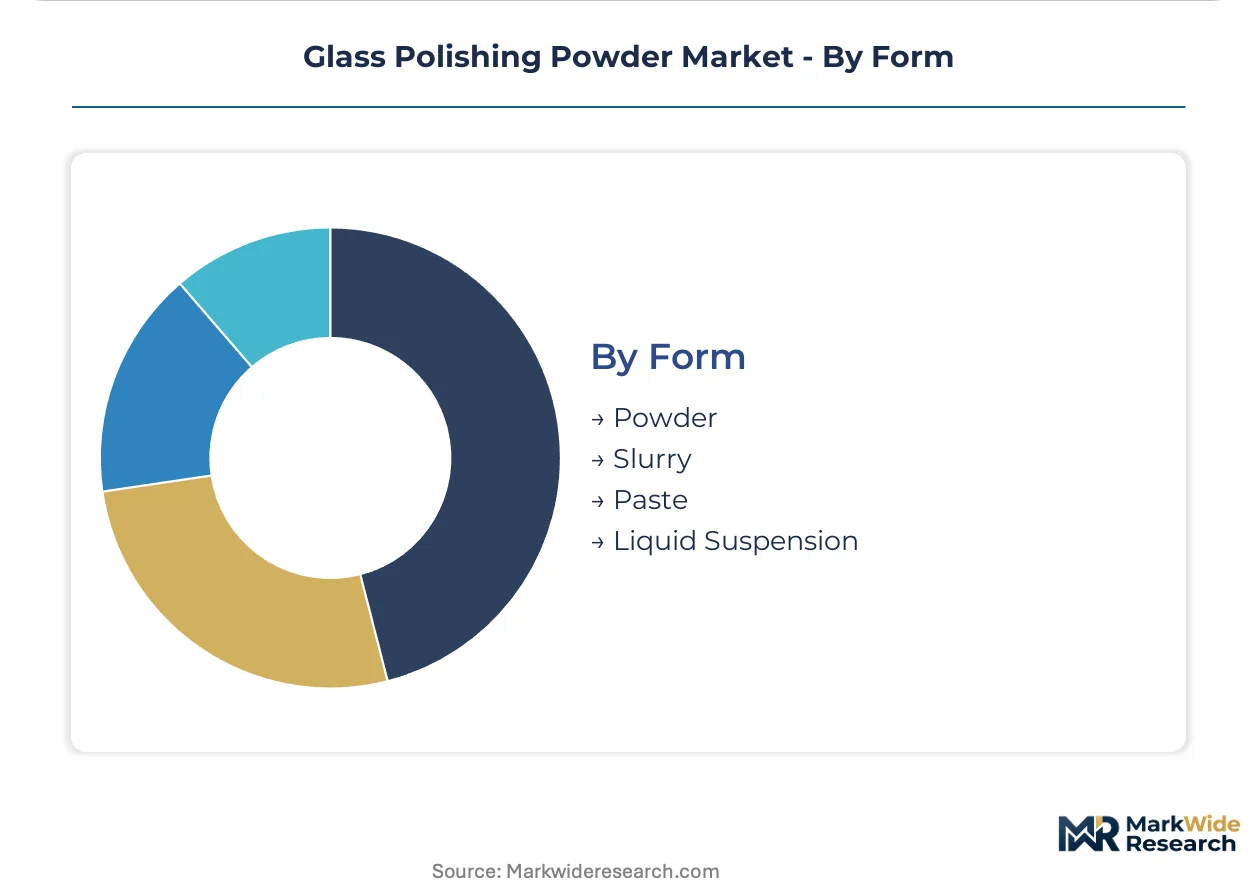
Form:
Delivery format selection tracks automation level and regulatory exposure, with pre-mixed suspensions eroding powder-form volume in OSHA-governed operations.
- Powder:Dry-milled abrasive retains volume leadership in legacy optical grinding and artisan applications. Respirable crystalline silica liability is forcing architectural glass processors toward alternative formats.
- Slurry:Pre-mixed aqueous suspension with controlled solids loading for automated dosing systems. Korean electronics fabs are integrating slurry-as-a-service models that displace bulk powder tenders.
- Paste:High-viscosity compound for manual application and spot repair.
- Liquid Suspension:Low-viscosity format for precision spray and flow-through polishing systems.
Powder form maintains volume leadership, with slurry gaining share fastest as automated polishing lines proliferate in East Asian manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cerium oxide processing capacity dwarfs German precision-milling capabilities, yet Korean electronics fabs command the steepest purity premiums for sub-nanometer display polishing requirements.
China
Domestic rare-earth processors retrofit energy-intensive calcination lines to meet dual carbon goals while securing state-backed optical component contracts. SAMR market surveillance inspections enforce GB standard heavy-metal thresholds on semiconductor-adjacent supply chains. Guangdong and Jiangsu province electronics display processors consolidate procurement around pre-qualified vendors with certified testing laboratories.
South Korea
Panel producers qualify ultra-high-purity cerium oxide slurries for microLED fabrication scale-up. MFDS pharmaceutical-grade documentation requirements impose twelve-to-eighteen-month validation timelines on new supplier entry. Seoul Capital Area and Busan-Ulsan manufacturing clusters drive quarterly contract renewal cycles with performance-guaranteed slurry subscriptions.
Japan
Electronics assemblers adopt nano-engineered cerium oxide formulations for fused silica waveguide fabrication. METI industrial standards intersect with JIS certification requirements for precision abrasive chemistry. Kanto and Kansai regions concentrate specialized milling expertise for sub-micron particle distribution control.
Germany
Automotive glass supply chains demand verified low-carbon rare-earth processing documentation under EU Green Deal embodied carbon tracking. ECHA REACH registration requirements lock in compliant suppliers and exclude unregistered powder traders. Bavaria and Baden-Württemberg anchor European optical hub demand for premium cerium oxide supply chains.
United States
Architectural glass processors shift toward pre-mixed suspensions under OSHA respirable crystalline silica permissible exposure limits. EPA frameworks govern powder handling operations while FDA documentation requirements cross into optical manufacturing quality systems. Midwest and Southeast manufacturing zones concentrate legacy aluminum oxide demand for construction glass finishing.
Glass Polishing Powder Market Competitive Landscape
Top-tier vendors anchor premium cerium oxide supply chains, while mid-scale specialists occupy formulation and regional distribution tiers. The vendor base stratifies across integrated rare-earth processors, precision-milling equipment operators, and slurry formulation houses. Three strategic archetypes dominate: fused minerals heritage players, volume-scale aluminum oxide producers, and ultra-high-purity electronics specialists. Competitive moves concentrate on backward integration into rare-earth refining and slurry-as-a-service model deployment.
Within the ultra-high-purity electronics tier, Fuji Chemifa Corporation exemplifies Japanese precision-chemical specialization, while Saint-Gobain occupies a position leveraging European fused minerals heritage across optical hubs. Tongxiang Dingliang Polishing Material Co., Ltd represents Chinese volume-scale production capacity for architectural glass processing grades. These three entities illustrate how geographic concentration of raw material access, milling expertise, and end-market proximity stratifies competitive positioning.
| Leading Market Players |
|---|
| Saint-Gobain |
| PPG Industries |
| AGC Inc. |
| Solvay |
| Universal Photonics |
| 3M |
| Showa Chemical Industry Co., Ltd. |
| Tongxiang Dingliang Polishing Material Co., Ltd |
| Fuji Chemifa Corporation |
| Others |
Pricing and Supply Chain Analysis
Ultra-high-purity certification tiers create divergent margin pools across electronics and architectural glass supply chains, with Korean display fabs paying premiums for SAMR-assayed cerium oxide while Chinese construction processors squeeze domestic aluminum oxide suppliers on spot tonnage. This bifurcation concentrates pricing power with ion-adsorption clay refiners in southern Chinese provinces and fragments procurement leverage among mid-scale slurry formulators lacking backward integration into rare-earth calcination.
Pricing Analysis
Capacity additions in Jiangxi and Guangdong are reshaping price floors for medium-purity aluminum oxide grades, though ultra-high-purity cerium oxide remains contract-anchored with quarterly renegotiation cycles. Three-tier pricing structure across premium, standard, and economy levels tracks SAMR certification status and particle size distribution consistency. Cost compression in architectural grades is intensifying because dual carbon retrofit expenses are eroding calcination margins. Electronics producers show the least price sensitivity due to sub-nanometer surface finish requirements, while vehicle refurbishers and construction contractors drive commodity spot-market volatility.
Supply Chain Analysis
Single-source vulnerability sits with Chinese ion-adsorption clay processors controlling high-purity cerium oxide refining, with Korean and Japanese electronics fabs drawing from concentrated southern provincial capacity. Rare-earth concentrate, specialized milling equipment from Japanese suppliers, and automated dosing system components constitute critical input dependencies. Tariff exposure on lanthanide exports creates margin unpredictability for formulated slurry producers. Distribution runs through pre-qualified vendor lists with certified testing laboratories, particularly for semiconductor-adjacent supply chains subject to SAMR market surveillance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glass polishing powder market functions as a stable compounder, with electronics display processing providing recurring revenue visibility through performance-guaranteed slurry subscriptions that reset quarterly.
For Market Incumbents: Hedge rare-earth oxide price volatility through long-term offtake agreements with Chinese ion-adsorption clay refiners before export quota announcements compress margin predictability. Deepen captive supply of calcination capacity to defend against emerging Indian optical component fabricators qualifying alternative aluminum oxide sources. Prioritize MFDS pharmaceutical-grade documentation investment to freeze new supplier entry into Korean lens export supply chains. For New Entrants and Emerging Players: Enter via Indian smartphone camera module lens grinding operations, where legacy aluminum oxide compounds dominate and formulated slurry penetration remains underdeveloped. Target Guangdong electronics display processors seeking second-source qualification for SAMR-certified testing laboratory capacity. Pursue slurry-as-a-service partnerships with automated dosing system integrators to bypass bulk powder tender competitions. For Investors and Strategic Acquirers: Consolidation pressure builds where sub-micron particle distribution milling expertise concentrates among Japanese and European equipment suppliers, creating acquisition premiums for precision-chemical specialists. Mid-scale slurry formulators with verified low-carbon rare-earth processing represent the priority target archetype for EU Green Deal positioning. Watch for Korean panel producer microLED fabrication scale-up announcements as inflection indicators for ultra-high-purity cerium oxide demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Calcination | Captive cerium oxide supply secures margin predictability against Chinese export quota volatility. |
| MFDS Pharmaceutical-Grade Certification Investment | Twelve-to-eighteen-month validation timelines create defensive moats around Korean lens export supply chains. |
| Slurry-as-a-Service Model Deployment | Automated dosing system integration with Korean electronics fabs displaces spot-market powder tenders. |
| Dual Carbon Retrofit Completion | State-backed optical component contracts favor calcination operators with verified low-carbon processing. |
| Indian Optical Component Market Entry | Smartphone camera module lens grinding operations remain underpenetrated by formulated slurry suppliers. |
Research Methodology
Coverage spans China, South Korea, Japan, Germany, and the United States, with primary inputs from each market cluster combining interviews with rare-earth processing plant managers, electronics fab procurement leads, optical component R&D directors, and slurry formulation technical specialists. Secondary validation draws from SAMR GB standard filings, ECHA REACH registration databases, Korean MFDS pharmaceutical-grade documentation records, and SEC 10-K disclosures from listed abrasive suppliers. Bottom-up demand modeling across end-use segments triangulates against top-down rare-earth oxide trade flow analysis.
Segmentation granularity spans oxide chemistry, application surface quality threshold, delivery format, and end-user automation level across the projection horizon. Cerium oxide, aluminum oxide, and tin oxide chemistries were modeled separately with purity tier distinctions. Electronics display processing, optical lens polishing, and architectural glass finishing applications incorporate distinct particle size distribution requirements. CAGRs derive from volume trajectory analysis calibrated to Korean panel producer microLED scale-up timelines and Chinese dual carbon retrofit completion rates.
Inputs from SAMR market surveillance inspection records and ECHA REACH registration databases were available through the study window; gaps in real-time Korean electronics fab slurry procurement contract terms introduce uncertainty bands around quarterly renewal cycle assumptions. Forecasts reflect modeling assumptions regarding rare-earth export quota stability and automated polishing line adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Self-Cleaning Glass Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Global Ultra-Thin Glass Market
Glass
Laboratory Glass Container Market
Glass
Asia-Pacific Glassware Market
Glass
Glass Tableware Market
Glass
Glass Prepreg Market
Glass
Europe Glass Insulators Market
Glass
Middle East and Africa Glassware Market
Glass
Fiberglass Window Market
Glass
Recycled Glass Aggregates Market
Glass
Global Anti-Reflective Glass Market
Glass
Glass Alternative Materials Market
Glass
Impact Resistant Glass Market
Glass
Foam Glass Granulate Market
Glass
Global Glass Flake Coatings Market