
 Solid State Resins Market | 2026-2036
Solid State Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Resins Market Intelligence
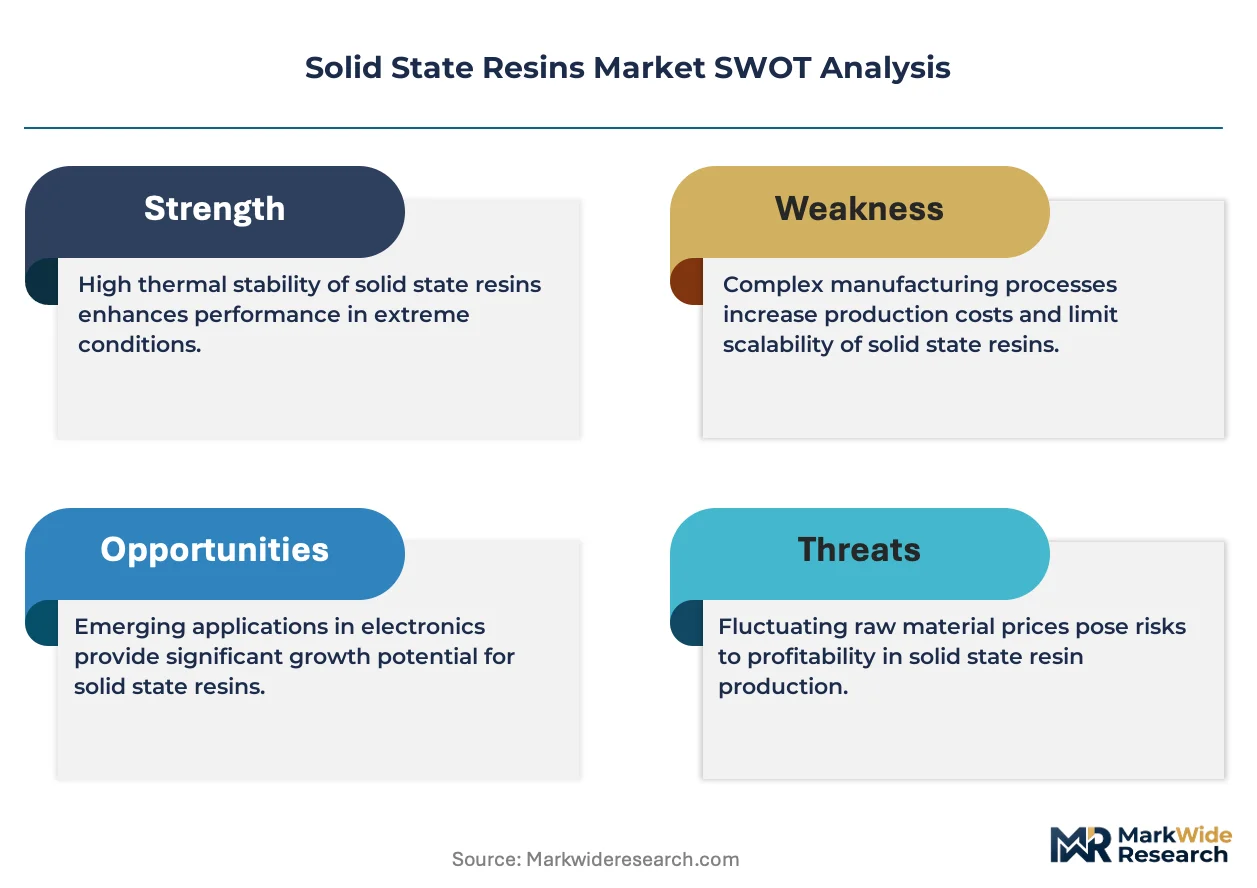
The European Union's REACH regulation, governing chemical substances, is hardening material selection criteria for industrial applications. This shift favors resins with documented safety profiles and lower volatile organic compound (VOC) content. BASF SE leverages its extensive R&D infrastructure to develop compliant polyurethane and epoxy systems. Dow Chemical Company specializes in polycarbonate resins for high-impact electronics casings. Arkema Group positions its specialty polymers for demanding aerospace and automotive components, navigating complex customer specifications across multiple jurisdictions.
Solid state resins are polymers cured or processed into a final, solid form without a solvent evaporation phase, often through thermosetting or thermoplastic processes. These materials provide structural integrity, chemical resistance, and thermal stability in finished goods. Polycarbonate and epoxy resins lead in value due to their performance in high-specification electronics and aerospace applications. Polyurethane resins, available in diverse forms like powders and granules, represent a high-volume segment driven by automotive and construction sector requirements.
Regulatory frameworks significantly influence market access and product formulation. In the United States, the EPA sets strict limits on VOC emissions, while in China, compliance with GB standards is mandatory for market entry. These regulations compel manufacturers to invest in low-emission and high-purity resin development. The critical decision for producers now revolves around balancing investment in sustainable, recyclable materials against the cost pressures of commoditized segments.
Market Dynamics
The central structural force shaping the solid state resins market is the direct conflict between escalating performance requirements from the automotive and electronics sectors and tightening environmental regulations, particularly concerning chemical composition and end-of-life recyclability under frameworks like the EU Green Deal.
Growth Catalysts
- Automotive Lightweighting:The push for extended battery range in electric vehicles drives adoption of high-strength, low-density polycarbonate and epoxy composites in body panels and battery enclosures, replacing heavier metals.
- EU Green Deal:This policy framework promotes circular economy principles, creating demand for novel resin formulations that are inherently recyclable or derived from bio-based feedstocks, especially within the packaging and consumer goods industries.
- Advanced Manufacturing in China:Concentrated demand from electronics and aerospace manufacturing clusters in regions like the Yangtze River Delta for high-performance resins fuels regional market expansion and specialized product development.
Market Restraints
- Feedstock Price Volatility:The market's reliance on petrochemical derivatives like bisphenol A and epichlorohydrin exposes resin producers to significant input cost fluctuations tied to global oil and gas prices.
- Substitution from Thermoplastics:High-performance engineering thermoplastics, such as PEEK and PPS, present a substitution threat in certain high-temperature aerospace and automotive applications traditionally dominated by thermoset epoxy resins.
- Energy-Intensive Curing:Many high-performance thermoset resins require prolonged, high-temperature curing cycles, representing a significant energy cost and processing bottleneck for manufacturers of large composite structures.
Strategic Opportunities
- Bio-Based Formulations:Development of resins derived from renewable sources like plant oils and lignin opens access to customers with strong corporate sustainability mandates and helps mitigate exposure to petrochemical price volatility.
- Additive Manufacturing Powders:Formulating resins into fine powders suitable for selective laser sintering (SLS) and other 3D printing technologies creates a new, high-value market for rapid prototyping and custom part production.
- Medical Device Encapsulation:Growing demand for implantable and wearable electronics requires biocompatible, durable solid state resins for encapsulation, representing a high-margin application with stringent performance requirements.
Industry Challenges
- Regulatory Divergence:Manufacturers face significant compliance costs and complexity navigating differing chemical safety standards, such as Europe's REACH framework versus China's mandatory GB standards for market entry.
- High-Purity Production:Achieving the purity levels required for semiconductor and optical-grade resins demands substantial capital investment in cleanroom environments and advanced filtration systems, creating high barriers to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Resins Market |
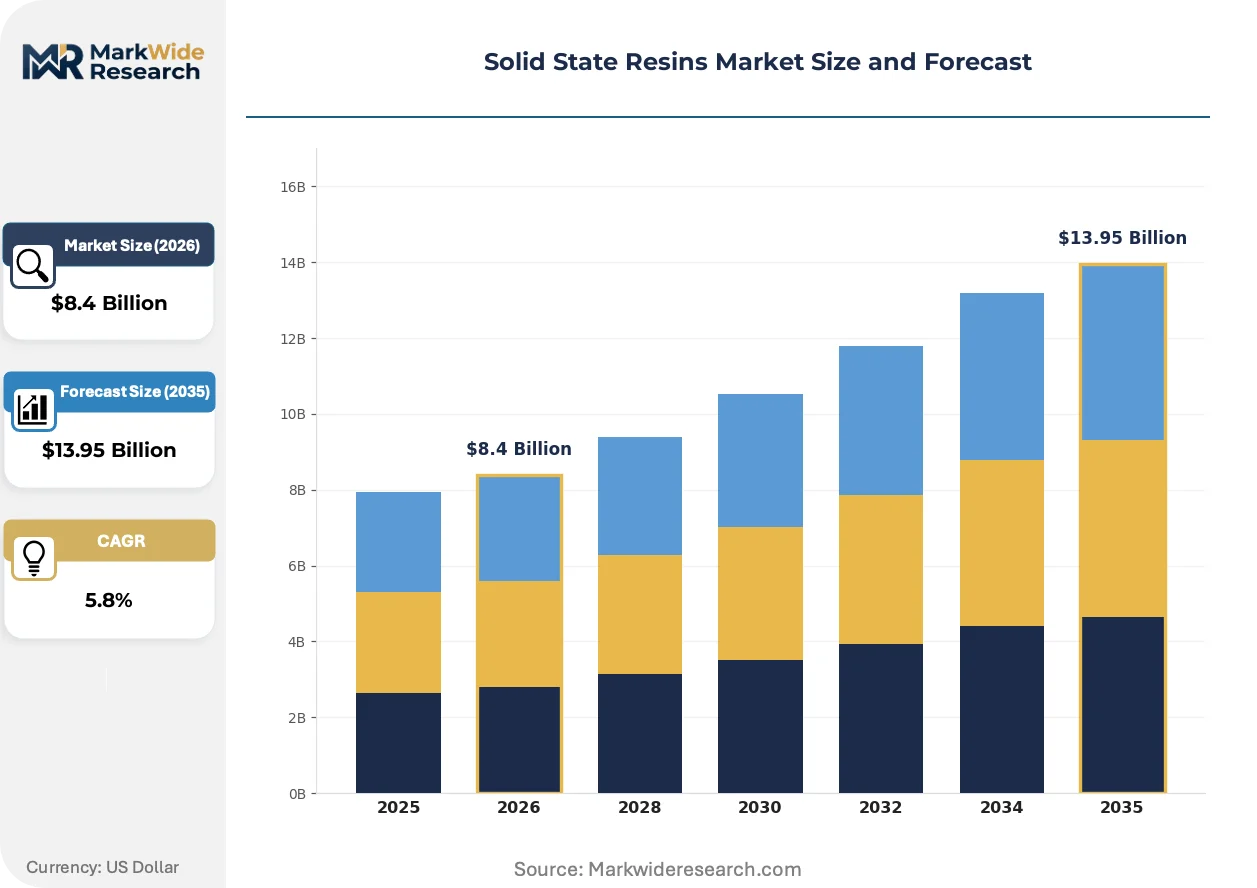
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Polycarbonate, Polyurethane, Epoxy Application: Aerospace, Automotive, Electronics, Construction Form: Liquid, Powder, Granules, Sheets End User: Manufacturers, Distributors, Retailers, Contractors |
| Companies Covered | BASF SE, Dow Chemical Company, Huntsman Corporation, 3M Company, DuPont, Arkema Group, SABIC, Mitsubishi Chemical Corporation, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Resins Market Strategic Shifts & Innovations
Product innovation is converging around dual-use capabilities, where resins must deliver superior physical properties while also meeting stringent environmental and safety criteria. This shift compels a focus on molecular engineering and advanced catalysis to achieve performance without relying on restricted substances.
Additive manufacturing-compatible resin powders provide a material foundation for 3D printing processes. The aerospace and medical device sectors are early adopters, using these materials for complex, low-volume parts. This technology is decentralizing component production away from centralized injection molding facilities toward on-demand, localized manufacturing networks.
The European Union's REACH regulation continues to exert significant pressure on chemical formulations globally. Its progressive restriction of substances of very high concern (SVHCs) forces the reformulation of established epoxy and polyurethane systems. Industrial coatings and adhesives segments are most affected, accelerating R&D into compliant, low-VOC alternatives to maintain market access in Europe.
A notable behavioral shift is the move from transactional, volume-based resin purchasing to specification-driven procurement tied to application performance. This trend disrupts traditional distributors, favoring material suppliers who offer deep application engineering support. This shift is most pronounced in the South Korean and Taiwanese electronics industries, where final device performance dictates material selection.
Solid State Resins Market Segmentation
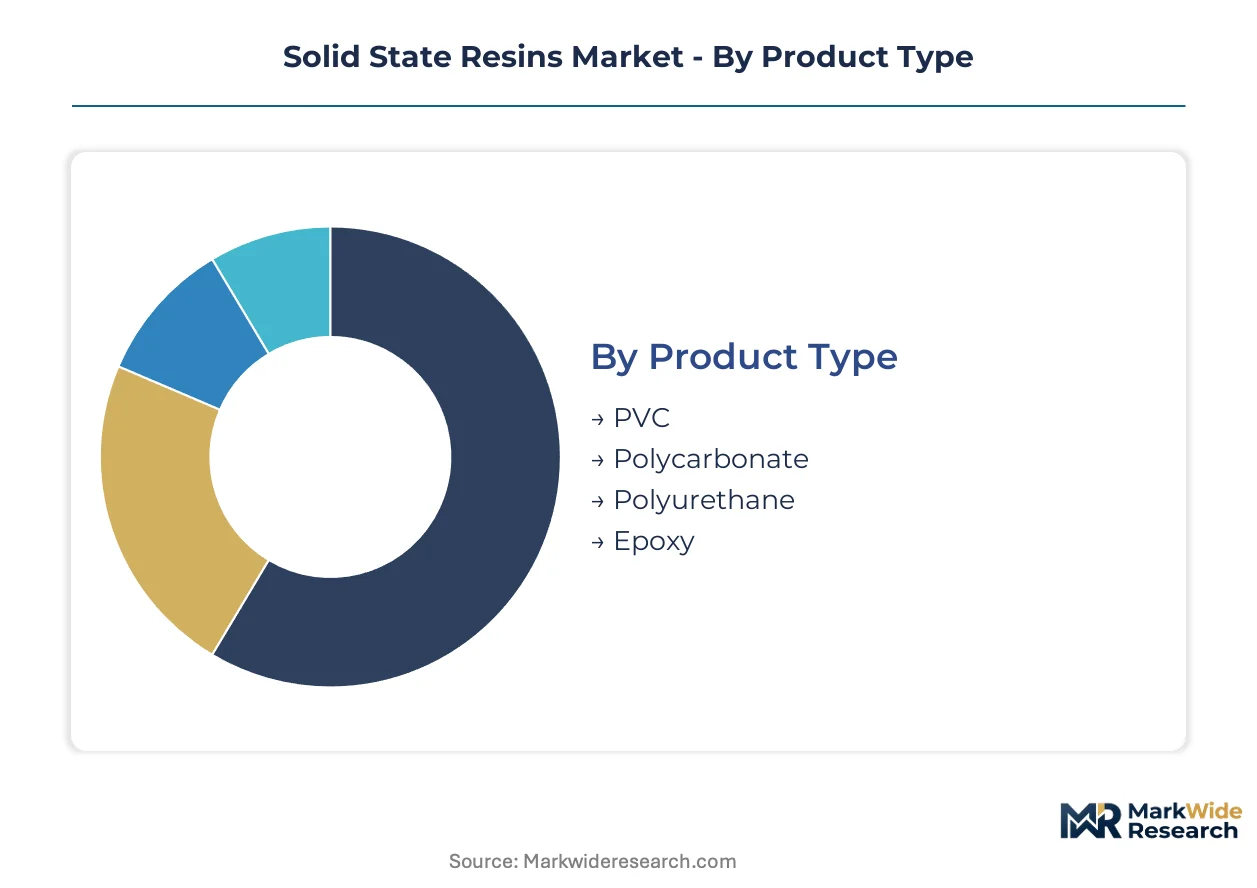
The solid state resins market exhibits diverse segmentation, reflecting varied material properties, application demands, and end-user requirements. Understanding these distinct segments is critical for producers to strategically align product development with specific industry needs and regulatory compliance. This granular view reveals where innovation in formulation and processing holds the most commercial value.
Product Type:
The product type segment spans highly customized, performance-driven formulations and more standardized, volume-oriented materials, catering to a broad spectrum of industrial needs.
- Polycarbonate:These amorphous thermoplastic polymers offer exceptional impact resistance, optical clarity, and dimensional stability, making them ideal for high-performance electronics casings and automotive lighting components. Demand concentrates in Asian electronics manufacturing hubs due to stringent performance specifications.
- Epoxy:As thermosetting polymers, epoxy resins provide superior adhesion, chemical resistance, and thermal stability, crucial for aerospace composites, high-voltage electrical encapsulation, and protective coatings. Their specification is driven by the need for structural integrity in demanding environments, particularly in European industrial applications.
- PVC:Polyvinyl chloride resins are cost-effective and versatile, widely used in construction for pipes, window frames, and flooring due to their durability and ease of processing.
- Polyurethane:These versatile polymers are available in various forms, offering excellent flexibility, abrasion resistance, and insulation properties for automotive interiors and construction sealants.
Leading the category by volume: Polyurethane. Growing fastest: Polycarbonate.
Application:
Applications for solid state resins range from premium, high-specification uses where material performance is paramount to more cost-sensitive, high-volume industrial deployments.
- Automotive:Solid state resins are vital for lightweighting electric vehicles, with advanced composites replacing traditional metals in body panels and battery enclosures to extend range and improve fuel efficiency. European automotive manufacturers drive significant demand for these materials due to emissions regulations.
- Electronics:These resins provide critical insulation, encapsulation, and structural support for sensitive electronic components, including circuit boards and semiconductor packaging, ensuring reliability and heat dissipation. Demand is particularly strong in South Korea and Taiwan for consumer and industrial electronics.
- Aerospace:High-strength, lightweight resins are indispensable for structural components and interiors in aircraft, enhancing fuel efficiency and meeting stringent safety standards.
- Construction:Solid state resins find extensive use in durable flooring, protective coatings, and structural adhesives, contributing to building longevity and performance.
The Automotive and Electronics sectors demonstrate the highest material specification requirements, while Construction consumes the largest volumes.
Form:
The physical form of solid state resins dictates their processing methods and suitability for either bulk manufacturing or specialized, precision-driven applications.
- Powder:Resin powders are increasingly critical for additive manufacturing technologies like selective laser sintering (SLS), enabling the production of complex geometries and custom parts for medical devices and aerospace prototypes. This form facilitates on-demand, localized manufacturing.
- Granules:Granular resins are the most common form for traditional polymer processing methods such as injection molding and extrusion, offering ease of handling and consistent feeding for high-volume production of consumer goods and industrial components. Their widespread use underpins much of the market's volume.
- Liquid:Liquid resins are primarily utilized in coatings, adhesives, and casting applications, allowing for precise application and curing to form solid, protective layers.
- Sheets:Resin sheets serve as precursors for thermoforming and composite laminates, providing structural integrity in applications ranging from automotive interiors to construction panels.
Granular forms dominate the market by volume, with powder forms showing significant expansion due to 3D printing adoption.
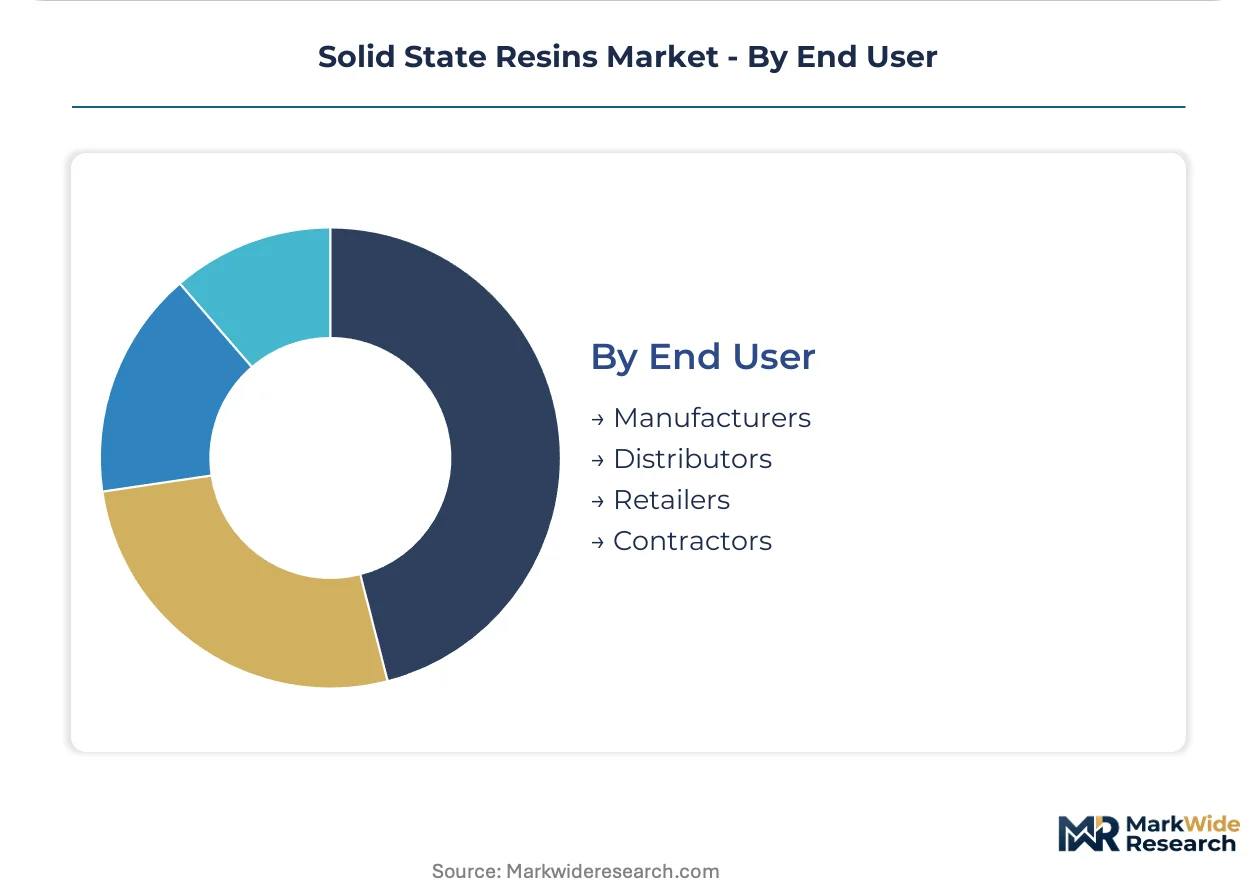
End User:
End users vary significantly, from large-scale industrial manufacturers integrating resins directly into their products to intermediaries facilitating broader market access and specialized application services.
- Manufacturers:These industrial entities directly purchase solid state resins as raw materials for their production processes, incorporating them into finished goods across automotive, electronics, and construction sectors. Their procurement is often driven by technical specifications and supply chain reliability.
- Distributors:Distributors serve as crucial intermediaries, managing logistics, inventory, and providing technical support to a diverse customer base, including smaller manufacturers and specialized fabricators who require flexible purchasing options. They often aggregate demand across various regions.
- Retailers:Retailers primarily sell finished products containing solid state resins, such as consumer electronics or automotive parts, to end consumers or smaller businesses.
- Contrators:Contractors in construction and infrastructure projects utilize solid state resins in forms like coatings, adhesives, and sealants for on-site application and structural enhancements.
Manufacturers represent the largest direct purchasing segment, while Distributors facilitate broad market penetration for resin producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global solid state resins market presents a clear production-consumption divide, with significant manufacturing capabilities concentrated in Asia, while high-value consumption centers exist across diverse geographies. Regional demand patterns are heavily influenced by local industrial specialization and evolving regulatory landscapes. This dynamic shapes investment priorities for resin producers.
China
Demand for solid state resins in China is driven by advanced manufacturing clusters specializing in high-performance electronics and aerospace components. Compliance with GB standards is mandatory for market entry, compelling manufacturers to develop high-purity formulations. The Yangtze River Delta region, a hub for electronics and automotive production, demonstrates strong localized demand for specialized resins.
Germany
Germany's solid state resins market benefits from robust automotive lightweighting initiatives and a strong industrial base. The EU Green Deal and REACH regulations influence material selection, favoring low-VOC and recyclable resin formulations. Automotive manufacturers in Bavaria and North Rhine-Westphalia are significant consumers of advanced polyurethane and epoxy systems.
United States
The United States market for solid state resins is propelled by stringent material specifications in aerospace and high-tech electronics applications. The Environmental Protection Agency (EPA) sets strict limits on volatile organic compound emissions, pushing for compliant product development. Aerospace component manufacturers across the Pacific Northwest and the Southern states require high-strength, thermally stable resins.
South Korea
South Korea exhibits concentrated demand for high-performance solid state resins, particularly within its advanced electronics and semiconductor industries. Strict local quality standards dictate material purity and reliability for device encapsulation and structural support. The Seoul Capital Area and Gyeonggi Province house major electronics manufacturers, driving innovation in specialized resin formulations.
Japan
Japan's market for solid state resins is characterized by high-specification requirements from its precision electronics and automotive sectors. METI policies encourage material innovation, especially for applications requiring extreme thermal stability and mechanical strength. The Kanto and Chubu regions, with their strong automotive and electronics industries, are key consumption areas for advanced polycarbonates and epoxies.
Solid State Resins Market Key Industry Players
The competitive structure tilts toward a mix of large, diversified chemical conglomerates and specialized polymer producers. Strategic archetypes include global material science giants, regional specialty chemical suppliers, and niche innovators focusing on specific application areas. Dominant competitive moves involve significant investment in R&D for compliant and high-performance formulations, alongside strategic partnerships to penetrate new end-use markets.
Within the global material science tier, BASF SE and Dow Chemical Company anchor market supply with extensive portfolios spanning multiple resin types and applications. These companies leverage their broad R&D infrastructure to meet diverse industry demands. Arkema Group exemplifies a specialized polymer producer, positioning its offerings for demanding aerospace and automotive components, navigating complex customer specifications across multiple jurisdictions.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Huntsman Corporation |
| 3M Company |
| DuPont |
| Arkema Group |
| SABIC |
| Mitsubishi Chemical Corporation |
| Solvay S.A. |
| Others |
Cost & Logistics Intelligence
Global crude oil price benchmarks, such as Brent and WTI, cascade through the solid state resins supply chain, directly influencing the cost of petrochemical feedstocks and subsequently impacting pricing tiers for various resin grades.
Pricing Analysis
Application performance outcomes anchor pricing for high-specification solid state resins. Contract-based long-term agreements dominate for specialized aerospace and medical-grade materials, ensuring supply stability for critical applications. Price differentiation stems from quality grade, particularly for optical clarity in polycarbonates and thermal stability in epoxies. Pricing softness affects commoditized segments like PVC due to feedstock price volatility. Electronics and aerospace manufacturers exhibit lower price sensitivity compared to high-volume construction sector buyers.
Supply Chain Analysis
Strict qualification and certification gating, such as ISO 9001 and aerospace-specific AS9100 standards, define access to high-value solid state resin supply chains. Production concentrates significantly in China, Germany, and the United States. The supply chain relies heavily on bisphenol A and epichlorohydrin as key raw materials. Single-source vulnerability for specialized additives presents a structural risk. Distribution runs through a dual model, with direct sales to large manufacturers and specialized distributors serving smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solid state resins market is poised for consolidation, with escalating regulatory compliance costs forcing smaller, less adaptable players out of the European market.
For Market Incumbents:
Hedge against petrochemical price volatility by accelerating R&D into bio-based resin formulations and securing long-term renewable feedstock contracts. Diversify geographic manufacturing footprints to mitigate region-specific regulatory threats, such as China's mandatory GB standards. The threat of high-performance thermoplastics substituting thermosets demands continuous innovation in composite strength. Invest in advanced R&D for compliant, low-VOC epoxy and polyurethane systems.
For New Entrants and Emerging Players:
Begin with niche applications requiring highly specialized properties, such as additive manufacturing powders for medical devices or biocompatible encapsulation for implantable electronics. The most penetrable segment lies within customized, low-volume parts where application-specific engineering support is paramount. A successful go-to-market angle involves offering deep technical collaboration and rapid prototyping services to early adopters in aerospace and medical sectors.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor specialized polymer producers with strong intellectual property in Europe, where the EU Green Deal is accelerating market shifts. Long-term viability centers on firms capable of developing inherently recyclable or bio-based resin formulations over the next decade. Acquisition targets should include mid-sized companies possessing proprietary technology for additive manufacturing powders. The signal to watch is successful commercialization of novel, high-performance sustainable resins.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Supports concentrated demand from China's electronics and automotive manufacturing clusters. |
| Green Manufacturing Transition | Aligns with EU Green Deal principles and reduces environmental footprint across production. |
| Long-term Bio-Feedstock Agreements | Mitigates exposure to petrochemical price volatility and secures renewable raw material supply. |
| Joint Venture for Additive Manufacturing | Accelerates development of specialized resin powders for 3D printing applications. |
| Technology Licensing for Recyclable Epoxies | Addresses regulatory pressure for circular economy solutions in industrial coatings. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market sizing. Primary research involved in-depth interviews with R&D directors, procurement leads at major automotive and electronics OEMs, material scientists, and distribution channel managers. This iterative process ensured bottom-up and top-down triangulation of market data.
Granularity at the product type, application, form, end-user, and regional regulatory impact levels defined the analytical framework over the projection horizon. Historical performance and projected demand across these dimensions informed the compound annual growth rates. Key industry-specific forecast inputs included electric vehicle production targets and trends in electronics component miniaturization.
Underlying measurement precision varies by segment; aerospace and high-performance electronics applications carry tighter precision than commoditized construction materials. Forecasts reflect assumptions regarding regulatory stability and technological advancements. A model refresh is warranted upon material change in global feedstock supply dynamics or major policy shifts like new REACH restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global PEEK Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
North America and Europe Phenolic Resin Market