
 Silica Sol Market | 2026-2036
Silica Sol Market Size, Share, and Industry Trends Forecast 2026-2036
Silica Sol Market Analysis
Project finance tied to green chemistry infrastructure is rewriting competitive entry barriers for mid-scale silica sol producers. Evonik Industries AG leverages its integrated precursor supply chain to sustain cost advantages across European and Asian markets. Nissan Chemical anchors its position through proprietary particle-size control technology serving semiconductor polishing demand. Cabot Corporation competes on manufacturing scale, operating multiple aqueous colloidal silica facilities with broad regional distribution coverage.
Silica sol is a stable dispersion of amorphous silicon dioxide nanoparticles in a liquid medium, typically ranging from 5 to 100 nanometers in particle diameter, produced through ion-exchange or hydrolysis of sodium silicate solutions. The material functions primarily as a surface-modifying agent, binder, and polishing abrasive across precision manufacturing processes. Colloidal silica leads product type revenue due to its dominance in electronics polishing and investment casting applications where particle uniformity commands premium pricing. Aqueous form concentrates volume demand, though powder formulations are gaining traction in coatings and adhesives requiring shelf-stable logistics. The automotive end-use segment represents a mature but steady outlet for silica gel in tire and rubber reinforcement.
REACH registration requirements in Europe, EPA chemical substance reporting in the United States, and China's GB standards for industrial chemicals collectively elevate compliance costs while favoring established producers with dedicated regulatory affairs capacity. ECHA's evolving nanomaterial guidance specifically targets colloidal silica classification, creating disclosure obligations that smaller traders struggle to meet. Stakeholders must monitor how semiconductor supply chain regionalization and shifting chemical registration timelines reshape both manufacturing location decisions and customer qualification protocols.
Market Dynamics
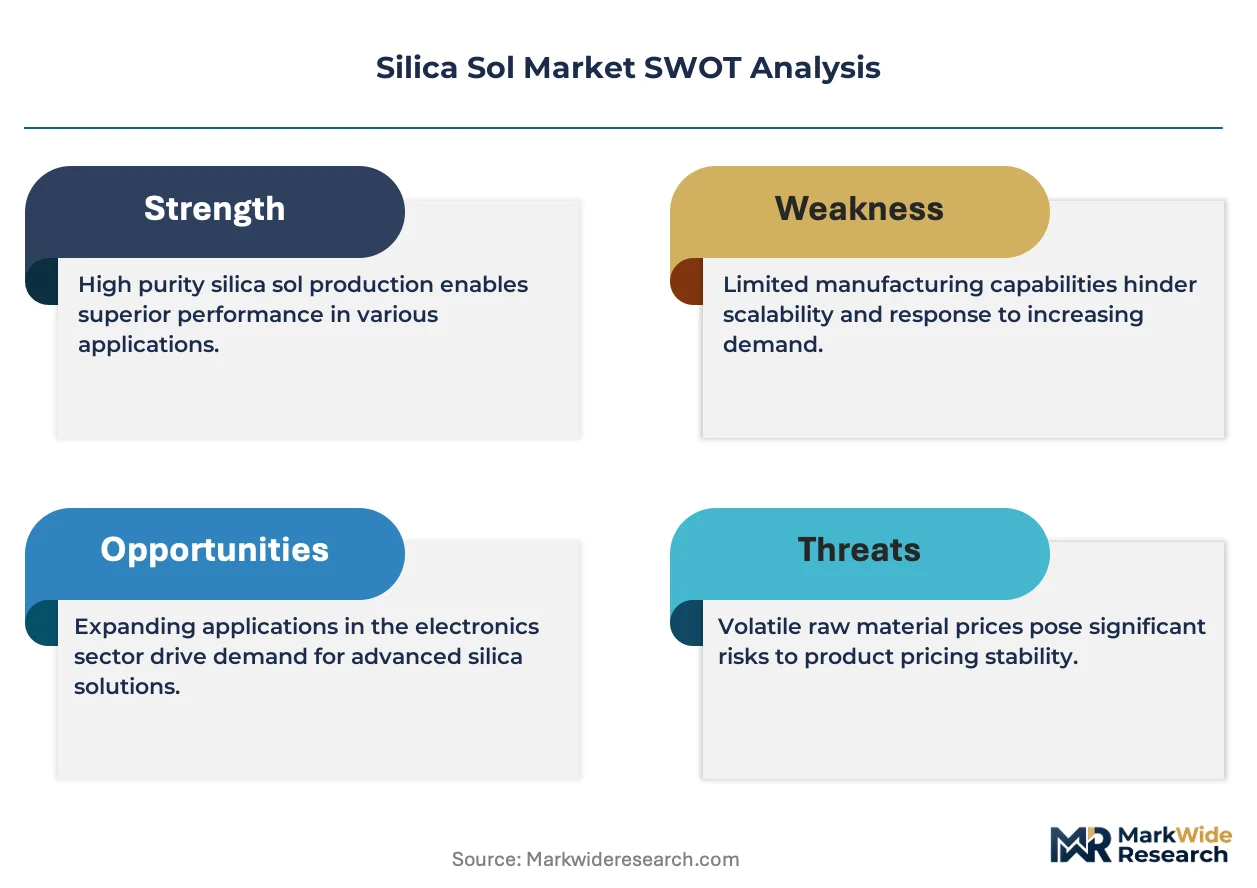
Semiconductor supply chain regionalization is fragmenting silica sol procurement patterns, as fabs in South Korea, Taiwan, and the United States diversify qualified supplier pools to mitigate geopolitical exposure.
Growth Catalysts
- Sub-10nm node expansion:Advanced logic and memory fabs in Taiwan and South Korea require ultra-high-purity colloidal silica for chemical mechanical planarization, tightening particle-size specifications.
- REACH nanomaterial registration:ECHA's evolving guidance on colloidal silica classification is accelerating disclosure standardization, favoring producers with established regulatory affairs infrastructure.
- Water-based coating mandates:China's tightening VOC regulations under MEE oversight are redirecting formulation choices from solvent-borne systems toward aqueous silica sol binders.
Market Restraints
- Sodium silicate feedstock volatility:Energy-intensive production of alkali silicates concentrates cost pressure on silica sol manufacturers when natural gas prices spike.
- East Asian supply concentration:Over half of global semiconductor-grade silica sol capacity clusters in Japan and South Korea, creating single-source vulnerability for European and North American fabs.
- Alumina slurry substitution:Cerium oxide and alumina-based polishing compounds retain cost advantages in legacy planarization applications where surface defect tolerance is higher.
Strategic Opportunities
- Indian semiconductor manufacturing:India's PLI scheme for electronics fabrication is attracting greenfield investments that will require localized silica sol supply chains.
- Solid-state battery casting:Next-generation lithium-metal and solid-electrolyte cell architectures employ colloidal silica in precision ceramic separator production.
- Carbon border adjustment mechanism:EU CBAM implementation creates competitive opening for low-carbon-intensity silica sol producers with verified Scope 3 emissions data.
Industry Challenges
- Particle-size metrology talent scarcity:Qualified analytical chemists capable of operating dynamic light scattering and electron microscopy systems command premium compensation in semiconductor clusters.
- Fab qualification timelines:Customer validation protocols for new silica sol sources extend 18-36 months, locking out agile entrants from high-margin electronics segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silica Sol Market |
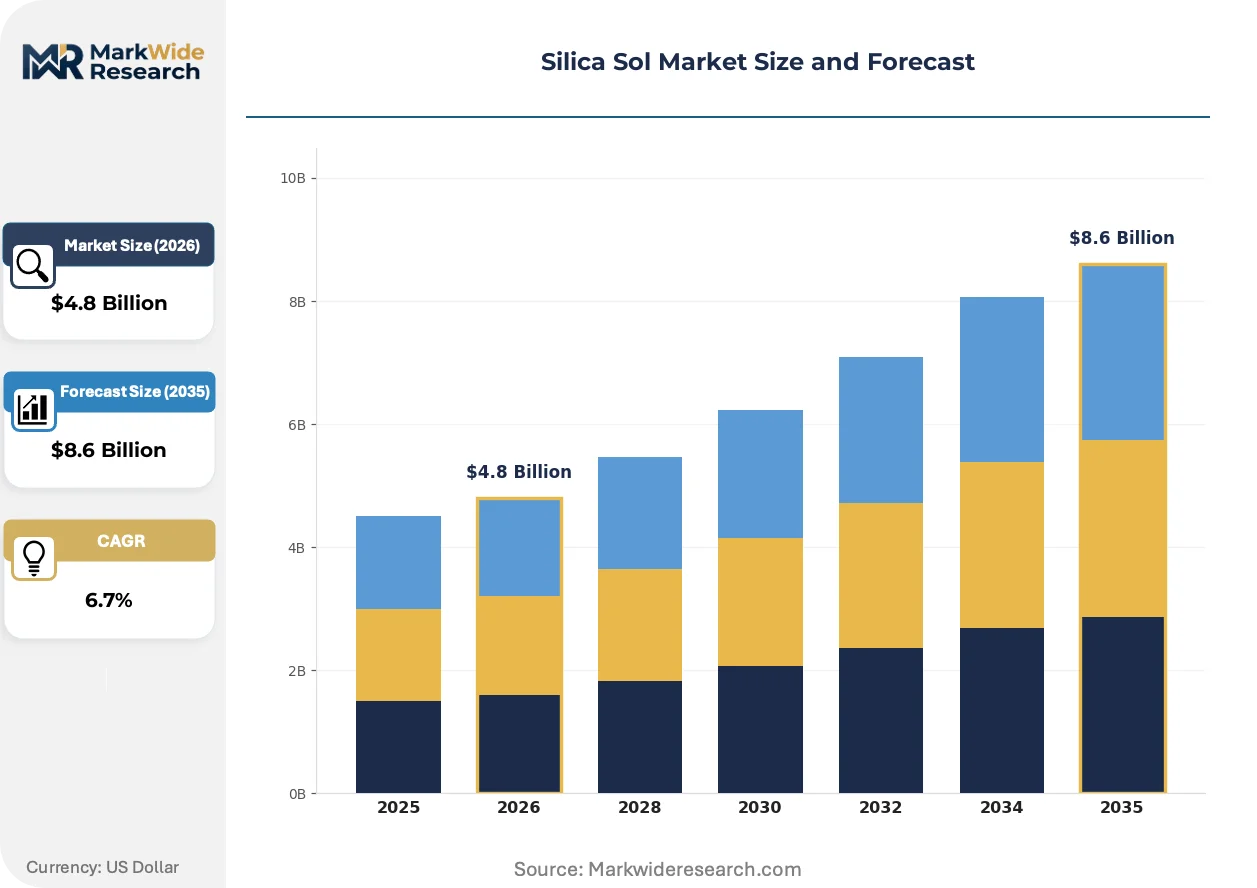
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colloidal Silica, Fumed Silica, Precipitated Silica, Silica Gel End Use Industry: Automotive, Electronics, Coatings, Food & Beverage Application: Adhesives, Paints, Sealants, Composites Form: Aqueous, Powder, Gel, Suspension |
| Companies Covered | Solvay SA, Fuso Chemical, Evonik Industries AG, Imerys, Nissan Chemical, Cabot Corporation, QEMETICA, Tata Chemicals Ltd., Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silica Sol Market Emerging Trajectories
Silica sol innovation vectors center on precision manufacturing demands, environmental compliance architecture, and supply chain resilience engineering across semiconductor and industrial coatings verticals.
Monodisperse particle synthesis via seeded growth hydrolysis is rendering obsolete legacy ion-exchange methods that produced broader size distributions unsuitable for sub-7nm node polishing. Samsung Foundry and TSMC have accelerated qualification of next-generation colloidal silica with sub-50nm coefficient of variation specifications. The technology compression is eliminating mid-tier producers lacking continuous-flow reactor capabilities.
ECHA's 2023-2024 nanomaterial guidance updates impose substance identification and exposure assessment obligations specifically targeting colloidal silica dispersions above 1% concentration. German and Dutch downstream users now demand full REACH Article 33 supply chain disclosures from Asian exporters. The compliance burden is forcing smaller traders to exit European electronics supply chains entirely.
Consolidated procurement through fab equipment OEMs is displacing direct chemical purchasing by semiconductor manufacturers. Applied Materials and LAM Research now bundle silica slurry supply into multi-year tool service agreements. The channel shift concentrates volume with colloidal silica producers holding OEM-qualified status, most visible in South Korean and Taiwanese foundry operations.
Silica Sol Market Segmentation
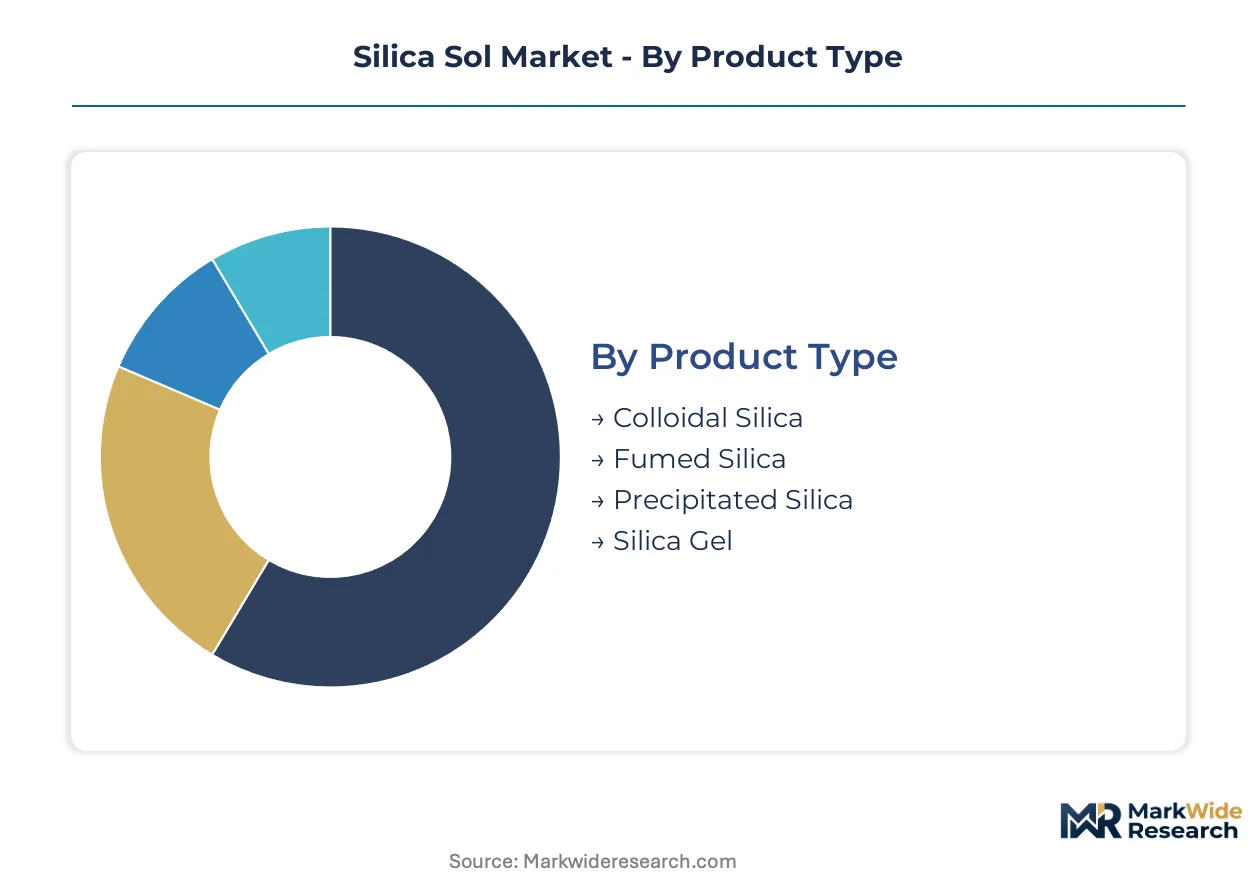
Silica sol procurement patterns diverge sharply across product types and end-use verticals, with semiconductor fabs demanding precision particle control while automotive buyers prioritize cost-stable volume contracts. Segmentation reveals where formulation expertise commands premium pricing versus commodity-scale manufacturing.
Product Type:
After-sales service intensity runs highest for colloidal silica, where fabs demand on-site particle-size validation and rapid technical response to planarization defects.
- Colloidal Silica:Stable aqueous dispersion of amorphous SiO₂ nanoparticles, typically 5-100nm diameter, produced via ion-exchange or hydrolysis. Demand concentrates in Taiwan and South Korea semiconductor clusters, where TSMC and Samsung Foundry enforce sub-50nm coefficient of variation specifications for sub-7nm node polishing. REACH nanomaterial registration burdens favor established producers with dedicated regulatory affairs infrastructure.
- Fumed Silica:Pyrogenic silica produced by flame hydrolysis of silicon tetrachloride, yielding high surface area aggregates for rheology control. Coatings formulators in Germany and the Netherlands drive specification tightening as ECHA disclosure obligations cascade through supply chains.
- Precipitated Silica:Produced by acidifying sodium silicate solutions, yielding controlled porosity for rubber reinforcement and carrier applications.
- Silica Gel:Highly porous amorphous silica with extensive internal surface area, serving desiccant and chromatography markets.
Colloidal silica holds the largest share; momentum sits with fumed silica as coatings producers accelerate water-based formulation transitions.
End Use Industry:
Margin structures vary dramatically, with electronics commanding fivefold pricing premiums over automotive tonnage due to qualification rigor and particle metrology requirements.
- Electronics:Chemical mechanical planarization consumes ultra-high-purity colloidal silica for wafer polishing, with fabs in South Korea and Taiwan diversifying qualified supplier pools to mitigate geopolitical exposure. Sub-10nm node expansion tightens particle-size specifications beyond legacy ion-exchange method capabilities.
- Automotive:Tire and rubber reinforcement represents mature volume demand, with precipitated silica serving tread compound formulations for rolling resistance reduction.
- Coatings:Water-based binder applications redirect from solvent-borne systems under China's MEE VOC regulations, with aqueous silica sol gaining share in architectural and industrial formulations.
- Food & Beverage:Silica functions as anti-caking agent and clarifying aid, with regulatory compliance varying across FDA, EFSA, and national food safety frameworks.
Electronics generates the steepest pricing premiums; coatings is climbing fastest as environmental mandates reshape formulation choices.
Application:
Volume concentration follows construction and automotive cycles, with adhesives and sealants showing countercyclical resilience through maintenance demand.
- Adhesives:Silica sol serves as reinforcing filler and rheology modifier, with demand clustering in automotive assembly and electronics bonding applications.
- Paints:Colloidal silica enhances scratch resistance and anti-corrosion performance, with waterborne architectural formulations expanding under European and Chinese environmental regulations.
- Sealants:Precipitated and fumed silica control viscosity and mechanical properties in construction and transportation sealing systems.
- Composites:Silica nanoparticles improve matrix reinforcement in advanced materials, with aerospace and wind energy applications driving specification evolution.
Paints holds the largest application share; composites is gaining share fastest as lightweighting imperatives spread across transportation sectors.
Form:
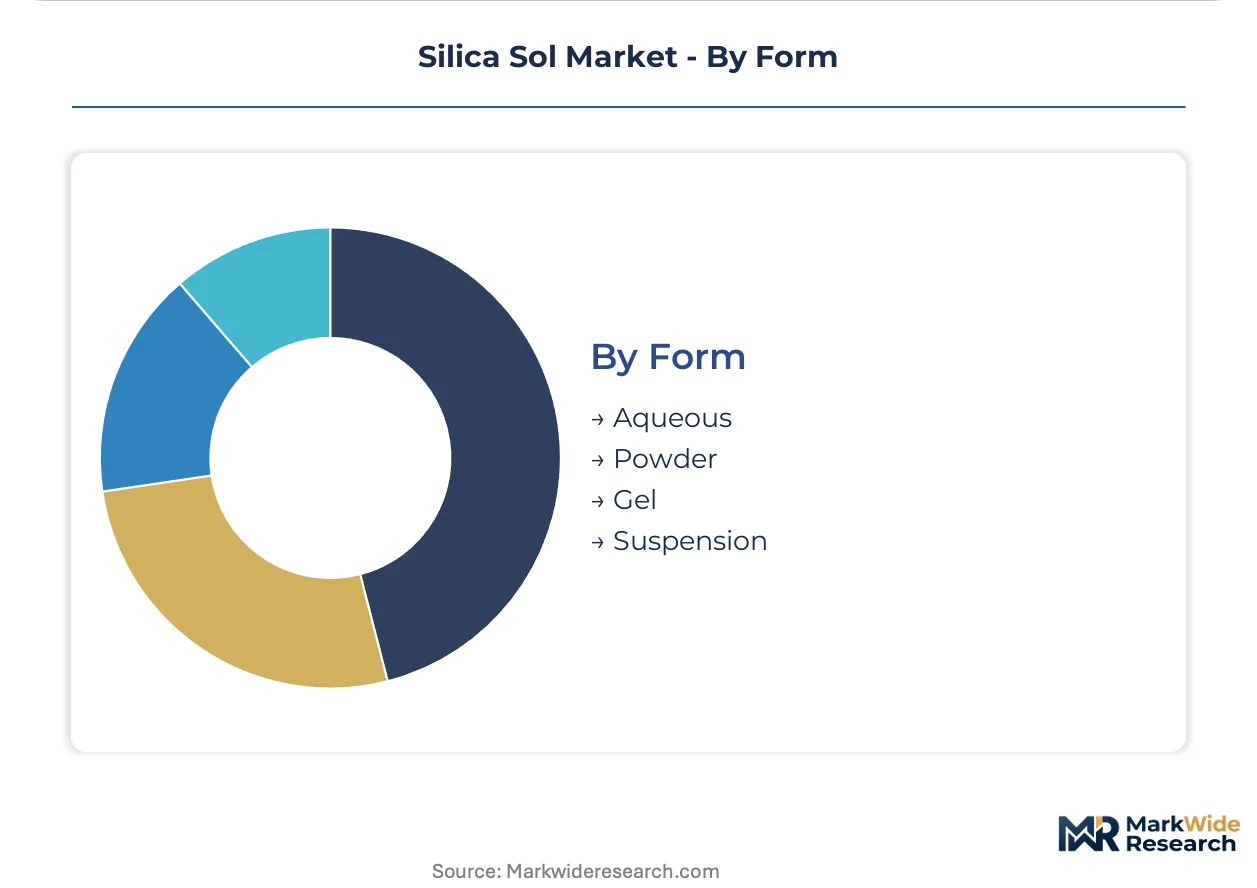
Supply chain configuration determines form preference, with aqueous dominating where manufacturing proximity permits and powder gaining where logistics costs outweigh formulation convenience.
- Aqueous:Liquid dispersion concentrates volume demand for electronics polishing and coatings binders, with regional production clustering reducing transport costs for high-water-content shipments. South Korean and Japanese producers anchor semiconductor-grade aqueous supply.
- Powder:Shelf-stable logistics enable long-distance supply to coatings and adhesives compounders, with spray-dried colloidal silica gaining traction in powder coating applications.
- Gel:Semi-solid consistency serves specific rheology requirements in personal care and specialized industrial formulations.
- Suspension:Concentrated non-aqueous dispersions address solvent-based coating systems transitioning toward compliance with tightening VOC frameworks.
Aqueous form dominates volume; powder is expanding most quickly as coatings producers seek supply chain flexibility across distributed manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and South Korean semiconductor clusters, while European coatings buyers absorb REACH compliance premiums without equivalent margin recovery. This asymmetry shapes where producers invest particle-size metrology capacity versus regulatory affairs infrastructure.
South Korea
Samsung Foundry and SK Hynix drive ultra-high-purity colloidal silica consumption for sub-7nm node polishing. The country's national industrial regulator enforces strict chemical substance reporting aligned with semiconductor supply chain security protocols. Pyeongtaek and Yongin host concentrated fab operations where local silica sol qualification timelines stretch 24-36 months.
Taiwan
TSMC's advanced logic production anchors regional demand for sub-50nm coefficient of variation specifications. The island's environmental protection administration implements nanomaterial disclosure rules mirroring ECHA frameworks. Hsinchu Science Park clusters precision chemical suppliers within 50 kilometers of leading-edge fabrication facilities.
Japan
Shin-Etsu and Showa Denko legacy operations supply legacy planarization chemistry alongside next-generation formulations. METI industrial standards govern particle-size distribution reporting for electronics-grade materials. Kanto and Kansai industrial corridors concentrate both precursor production and downstream colloidal silica manufacturing.
Germany
BASF and Evonik facilities serve European coatings and automotive rubber reinforcement demand. ECHA REACH registration requirements impose substance identification burdens specifically targeting colloidal silica dispersions above 1% concentration. Ludwigshafen and Marl chemical parks integrate silica sol production with adjacent sodium silicate supply chains.
China
Domestic semiconductor fab construction accelerates import substitution programs for polishing chemicals. MEE VOC regulations under tightening enforcement redirect coatings formulation toward aqueous silica sol binders. Yangtze River Delta and Pearl River Delta clusters concentrate both electronics manufacturing and water-based industrial coatings production.
Silica Sol Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where particle-size control and regulatory compliance create defendable positions. The vendor base stratifies between integrated chemical conglomerates with captive sodium silicate supply and focused colloidal silica producers relying on merchant feedstock. Three archetypes dominate: diversified materials giants with semiconductor-qualified status, regional specialists serving coatings and automotive tiers, and emerging Asian challengers building fab relationships through price aggression. Competitive intensity centers on OEM qualification bundling and backward integration into precursor production.
Among diversified materials conglomerates, Evonik Industries AG and Cabot Corporation exemplify the integrated archetype with European and North American manufacturing footprints. Nissan Chemical occupies a position representing Japanese precision chemical specialization serving foundry clusters in Taiwan and South Korea. Solvay SA anchors the European tier with Belgian-based operations extending into coatings and electronics verticals.
| Leading Market Players |
|---|
| Solvay SA |
| Fuso Chemical |
| Evonik Industries AG |
| Imerys |
| Nissan Chemical |
| Cabot Corporation |
| QEMETICA |
| Tata Chemicals Ltd. |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Pyeongtaek's concentrated semiconductor-grade colloidal silica capacity anchors Asia-Pacific pricing power, with Samsung Foundry and SK Hynix procurement contracts setting regional benchmarks that European coatings buyers struggle to match. Sodium silicate feedstock volatility and REACH nanomaterial compliance costs fragment margin structures across producer tiers.
Pricing Analysis
Configured-to-order pricing for sub-50nm coefficient of variation specifications commands fivefold premiums over standard aqueous colloidal silica tonnage. Three-tier pricing structure across semiconductor-qualified, industrial-grade, and commodity aqueous dispersions reflects particle metrology investment and fab qualification status. Pricing pressure stems from alumina slurry substitution in legacy planarization applications where surface defect tolerance permits lower-cost alternatives. Automotive rubber reinforcement buyers exhibit highest price sensitivity, while foundry procurement teams prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes targeting semiconductor manufacturing equipment constrain technology flows into Chinese domestic fab construction, redirecting precursor chemical trade patterns. Supply concentrates in Japan, South Korea, and Taiwan for electronics-grade material, with German and Belgian facilities serving European coatings demand. Sodium silicate, ion-exchange resins, and high-purity water feedstock dependencies tether production to industrial chemical clusters. Single-source vulnerability runs through South Korean and Japanese precursor supply. Distribution runs through fab equipment OEM bundling agreements and direct long-term offtake contracts with foundry operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against cerium oxide and alumina-based polishing compounds reclaiming share in cost-sensitive planarization tiers. Incumbents must fortify particle-size control capabilities and regulatory compliance infrastructure to sustain premium positioning.
For Market Incumbents: Harden fab qualification relationships through embedded technical service teams and rapid defect response protocols. Deepen backward integration into sodium silicate precursor production to insulate margin structures from natural gas price spikes. Prioritize ECHA REACH Article 33 disclosure infrastructure to defend European electronics supply chain position against regulatory exclusion.
For New Entrants and Emerging Players: Indian semiconductor manufacturing clusters under PLI scheme incentives represent the most penetrable entry point for greenfield silica sol qualification. Solid-state battery ceramic separator applications offer alternative demand anchoring outside semiconductor supply chain concentration. Pursue OEM equipment bundling partnerships rather than direct foundry sales to compress customer acquisition timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because ECHA nanomaterial guidance and REACH disclosure burdens compound competitive advantages for established producers with dedicated compliance infrastructure. Target acquisition profiles center on mid-scale aqueous colloidal silica producers holding semiconductor-qualified status in East Asian clusters. Monitor fab equipment OEM consolidation patterns as signal for channel control inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive sodium silicate production shields margins from energy price volatility in German and South Korean chemical parks. |
| Fab Equipment OEM Partnership | Applied Materials and LAM Research bundling agreements concentrate volume with qualified colloidal silica producers in Taiwanese foundry operations. |
| REACH Nanomaterial Compliance Investment | ECHA Article 33 disclosure infrastructure excludes smaller traders from European electronics supply chains entirely. |
| Monodisperse Particle Synthesis Scale-Up | Seeded growth hydrolysis capabilities meet TSMC and Samsung Foundry sub-7nm node specifications that ion-exchange methods cannot achieve. |
| Indian Manufacturing Localization | PLI scheme semiconductor investments require localized silica sol supply chains with 24-36 month qualification timelines. |
Methodological Framework
The analysis maps colloidal silica, fumed silica, precipitated silica, and silica gel sub-sectors, each validated through procurement leads at semiconductor fabs, coatings formulators, and tire manufacturers. Primary interviews with plant managers at sodium silicate facilities, technical R&D directors at precision chemical producers, and distribution channel partners in East Asian clusters combined with secondary validation from customs/trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Assumptions held semiconductor node transition timelines and REACH nanomaterial guidance enforcement as fixed conditions, while varying sodium silicate feedstock cost trajectories and regional fab construction schedules. The analytical framework segmented by product type, end-use industry, application, and form, with geographic production hub as cross-cutting dimension. CAGRs derived from installed capacity expansion rates and content-per-unit coefficients in planarization and coatings applications. Forecast inputs incorporated OEM equipment bundling penetration rates and water-based coating mandate enforcement intensity under China's MEE oversight.
Practitioners should monitor export-control regime expansion and carbon border adjustment mechanism implementation for early signals of supply chain restructuring. Forecasts reflect documented assumptions on semiconductor capital expenditure cycles and environmental regulation enforcement trajectories. Material shifts in alumina slurry substitution rates or ECHA nanomaterial classification stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Mat Thermoplastic Market
Glass
Mexico Flat Glass Market
Glass
Solar PV Glass Market
Glass
Soda Feldspar Market
Glass
Global Flat Glass Market
Glass
Decorative Glass Market
Glass
Laboratory Glass Container Market
Glass
France Silica Sand Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Low-E Glass Market
Glass
3D Glass Market
Glass
Europe Glassware Market
Glass
Impact Resistant Glass Market
Glass
UAE Silica Sand Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Glass Grade Dolomite Market