
 Asia-Pacific Fiberglass Window Market | 2026-2036
Asia-Pacific Fiberglass Window Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fiberglass Window Market Insights
China's dual carbon goals and Japan's building energy codes are consolidating demand around thermally efficient envelope materials. Owens Corning leverages its regional manufacturing footprint to serve high-performance commercial projects across East Asia. Nippon Electric Glass Co., Ltd. anchors the Japanese market through specialized low-emissivity fiberglass formulations. China Jushi Co., Ltd. dominates raw glass fiber supply, extending cost advantages to downstream window fabricators.
Fiberglass windows incorporate glass fiber reinforced polymer (GFRP) pultruded profiles with hollow multi-chamber designs achieving U-values below 0.9 W/m²K, engineered to eliminate thermal bridging in building envelopes. Casement windows lead product type margins due to superior compression sealing and hardware complexity, while sliding windows compete aggressively on replacement volume in dense urban corridors. Residential applications sustain the largest installation base, though commercial new construction commands premium pricing through architect-specified performance tiers.
China's MEE enforces building energy efficiency standards that mandate high-performance window assemblies in northern heating zones. Japan's METI administers the Top Runner program that escalates thermal performance benchmarks for commercial facades. Australia's NCC and India's BIS energy conservation codes are tightening U-value requirements, forcing import substitution toward certified regional suppliers. Stakeholders must monitor regulatory divergence between national building codes and emerging subnational green certification schemes to align capacity investments with enforceable compliance timelines.
Market Dynamics
China's dual carbon goals and Japan's METI building energy codes are tightening thermal performance mandates across East Asia, forcing window specification toward high-performance GFRP assemblies and compressing the competitive set around certified regional fabricators.
Growth Catalysts
- MEE envelope standards:China's Ministry of Ecology and Environment mandates high-performance window assemblies in northern heating zones, driving replacement cycles in Beijing and Tianjin residential towers.
- High-rise residential construction:Singapore and Australian developers specify fiberglass windows for thermal compliance in curtain wall systems, with procurement volumes concentrating in Sydney and Melbourne CBD projects.
- GFRP pultrusion advances:Hollow multi-chamber profile designs achieving sub-0.9 W/m²K U-values are eliminating thermal bridging in commercial facades, displacing aluminum in premium specifications.
Market Restraints
- Raw glass fiber concentration:China Jushi Co., Ltd. dominates upstream supply, creating single-source dependency for downstream window fabricators across the region.
- Petrochemical input volatility:Unsaturated polyester resin prices fluctuate with crude oil cycles, compressing margin stability for mid-tier profile extruders.
- PVC-u substitution threat:Vinyl windows retain cost advantages in mass-market residential replacement, particularly in Indian urban corridors where BIS energy codes remain loosely enforced.
Strategic Opportunities
- India's BIS code escalation:Tightening U-value requirements in the National Building Code create first-mover advantage for certified fiberglass suppliers establishing local fabrication partnerships.
- Low-emissivity coating convergence:Integration of solar control glazing with GFRP frames opens premium commercial specifications in Tokyo and Osaka high-rises.
- Direct-to-developer channels:Bypassing traditional distributor networks through architect-specified procurement platforms reduces margin leakage in Australian commercial new construction.
Industry Challenges
- Pultrusion technician scarcity:Skilled operators for continuous profile manufacturing remain concentrated in China's coastal provinces, constraining capacity expansion in Southeast Asia.
- Green certification timeline compression:China's GB/T green building standards and Australia's Green Star rating systems demand third-party thermal performance verification, extending project qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fiberglass Window Market |
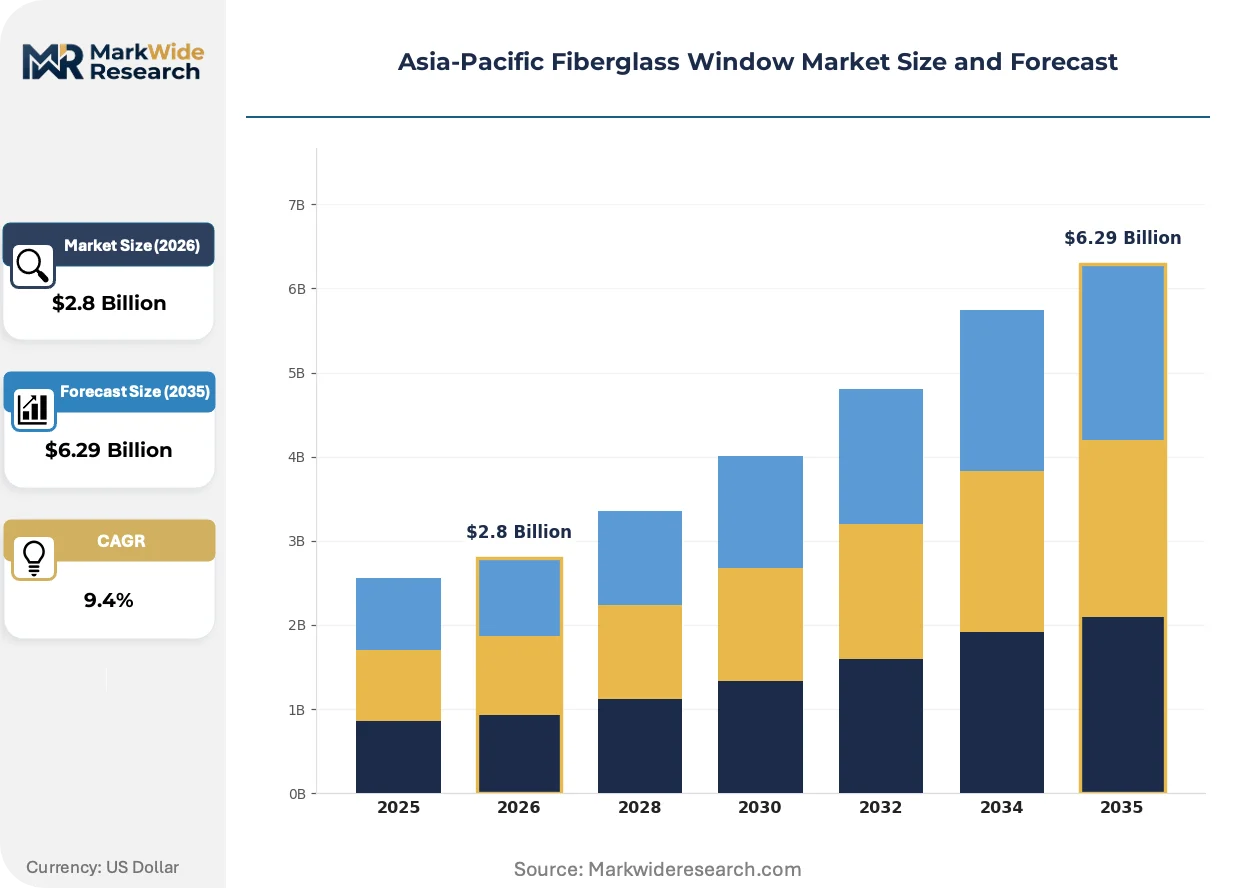
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Windows, Sliding Windows, Casement Windows, Awning Windows Application: Residential, Commercial, Institutional, Industrial End User: Homeowners, Builders, Contractors, Architects Installation Type: New Construction, Replacement, Renovation, Retrofit |
| Companies Covered | China Jushi Co., Ltd., Taishan Fiberglass Inc., Nippon Electric Glass Co., Ltd., Owens Corning, Chongqing Polycomp International Corp., Sichuan Weibo New Material Group Co., Ltd., Shandong Fiberglass Group Corp, Saint-Gobain, Johns Manville, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fiberglass Window Market Trends and Innovations
Material science advances and regulatory tightening are compressing specification cycles across the Asia-Pacific fiberglass window market, with thermal performance benchmarks becoming the primary competitive filter.
Thermally broken GFRP pultruded profiles with integrated polyamide strips are consolidating specification authority in high-performance commercial facades. Japanese developers in Tokyo's Minato ward specify these assemblies for METI Top Runner compliance, compressing aluminum's share in premium new construction. The technology is consolidating procurement decisions around fabricators with in-house thermal modeling capabilities.
Australia's NCC Section J energy efficiency provisions now mandate whole-window U-value disclosure, forcing import substitution toward certified regional suppliers. The code revision compresses specification timelines by requiring pre-submission thermal modeling. Commercial developers in Sydney and Melbourne now prioritize domestic fabricators with NCC-registered testing protocols over imported alternatives.
Architect-driven procurement platforms are disintermediating traditional distributor networks in Singapore and Australian commercial markets. Developers now specify fiberglass windows through digital specification tools that embed thermal performance data directly into BIM workflows. This pattern is most visible in Singapore's Marina Bay district, where green building certification rates exceed regional averages and procurement teams prioritize suppliers with digital-native technical documentation.
Asia-Pacific Fiberglass Window Market Segmentation
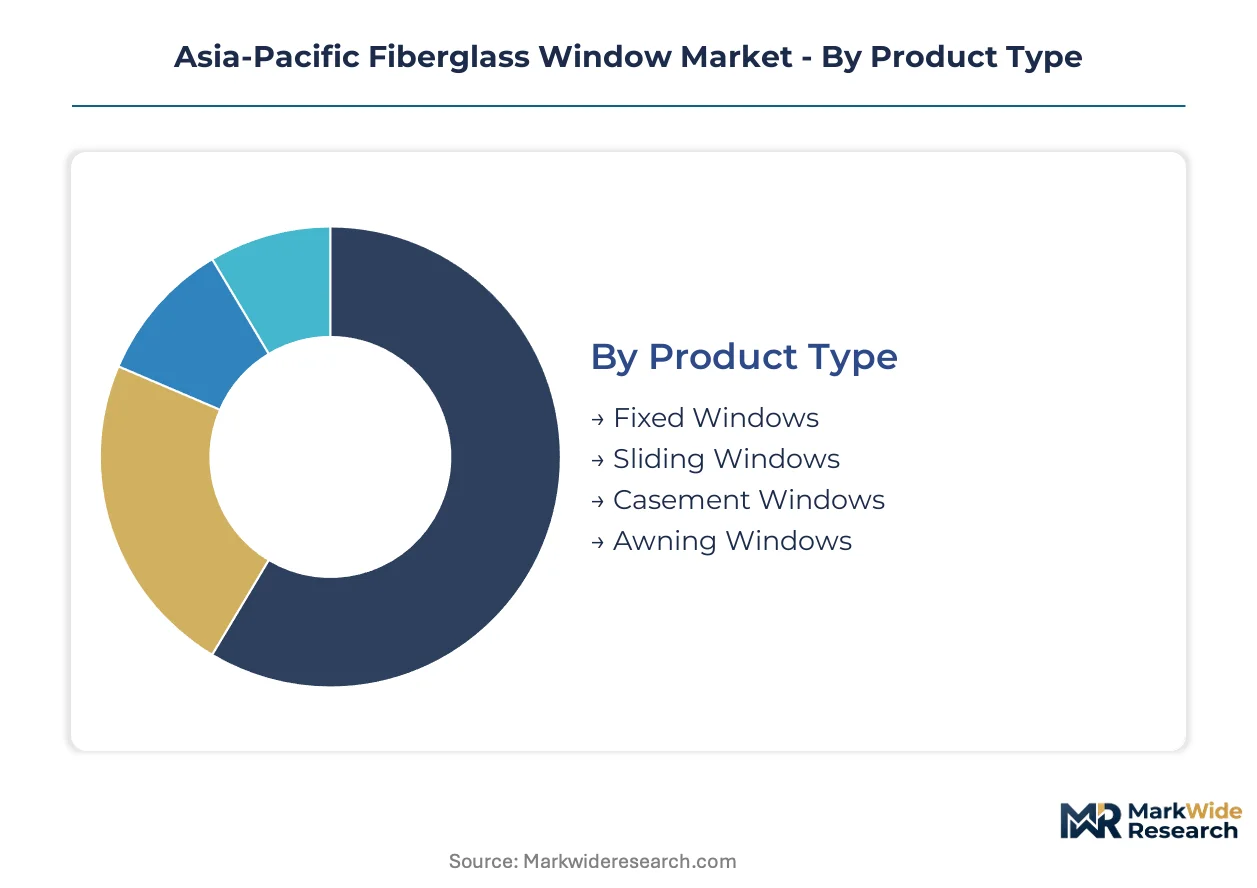
Product architecture, procurement authority, and project lifecycle stage each reshape competitive dynamics in Asia-Pacific fiberglass windows. Specification power concentrates with distinct buyer types across these four segmentation axes, forcing fabricators to align technical documentation and channel strategy accordingly.
Product Type:
Performance premiums diverge sharply between operable and fixed assemblies, with sealing complexity and hardware integration driving margin stratification.
- Casement Windows:Side-hinged designs with multi-point compression locks deliver superior air tightness for METI Top Runner compliance in Tokyo commercial towers. Singapore's Marina Bay high-rises specify these for curtain wall integration where thermal bridging elimination commands architect priority.
- Sliding Windows:Horizontal track systems dominate replacement volume in dense urban corridors across Sydney and Melbourne, competing aggressively on installed cost per square meter despite inferior U-values versus casement alternatives.
- Fixed Windows:Non-operable picture windows with simplified GFRP frames anchor the lowest cost tier in mass residential developments across India's tier-2 cities.
- Awning Windows:Top-hinged designs with integrated rain screens serve Australia's coastal humidity zones where natural ventilation compliance intersects with NCC envelope standards.
Volume sits with sliding systems; growth tilts toward casement specifications.
Application:
Code enforcement intensity and certification requirements fragment demand across building use categories, with commercial facades commanding the steepest performance premiums.
- Commercial:Curtain wall specifications in Sydney CBD and Osaka high-rises mandate third-party thermal modeling for NCC and METI compliance, consolidating procurement around fabricators with in-house simulation capabilities.
- Residential:High-rise towers in Singapore and Australian capital cities drive fiberglass penetration for green building certification, though cost sensitivity persists in India's mass housing segment.
- Institutional:Schools and hospitals across China's northern heating zones face MEE envelope standard mandates, creating replacement cycles in Beijing and Tianjin public building stock.
- Industrial:Warehousing and logistics facilities prioritize durability over thermal performance, with GFRP corrosion resistance winning specification in coastal chemical processing zones.
Commercial captures the highest unit margins; residential delivers the deepest installation base.
End User:
Specification authority and technical fluency separate professional buyers from consumer-direct procurement, reshaping channel economics.
- Architects:Design-led specification in Australian and Singapore commercial markets embeds thermal performance data directly into BIM workflows, disintermediating traditional distributor networks.
- Builders:Volume procurement for multi-unit residential developments across China's coastal provinces concentrates demand with fabricators offering certified GB/T compliance documentation.
- Contractors:Replacement market coordination in Indian urban corridors favors established PVC-u suppliers, compressing fiberglass penetration where BIS energy codes remain loosely enforced.
- Homeowners:Direct retail exposure remains limited to premium renovation segments in Tokyo and Sydney, with most residential volume flowing through developer-specified channels.
Builders control the largest transaction volumes; architects are expanding their specification influence fastest.
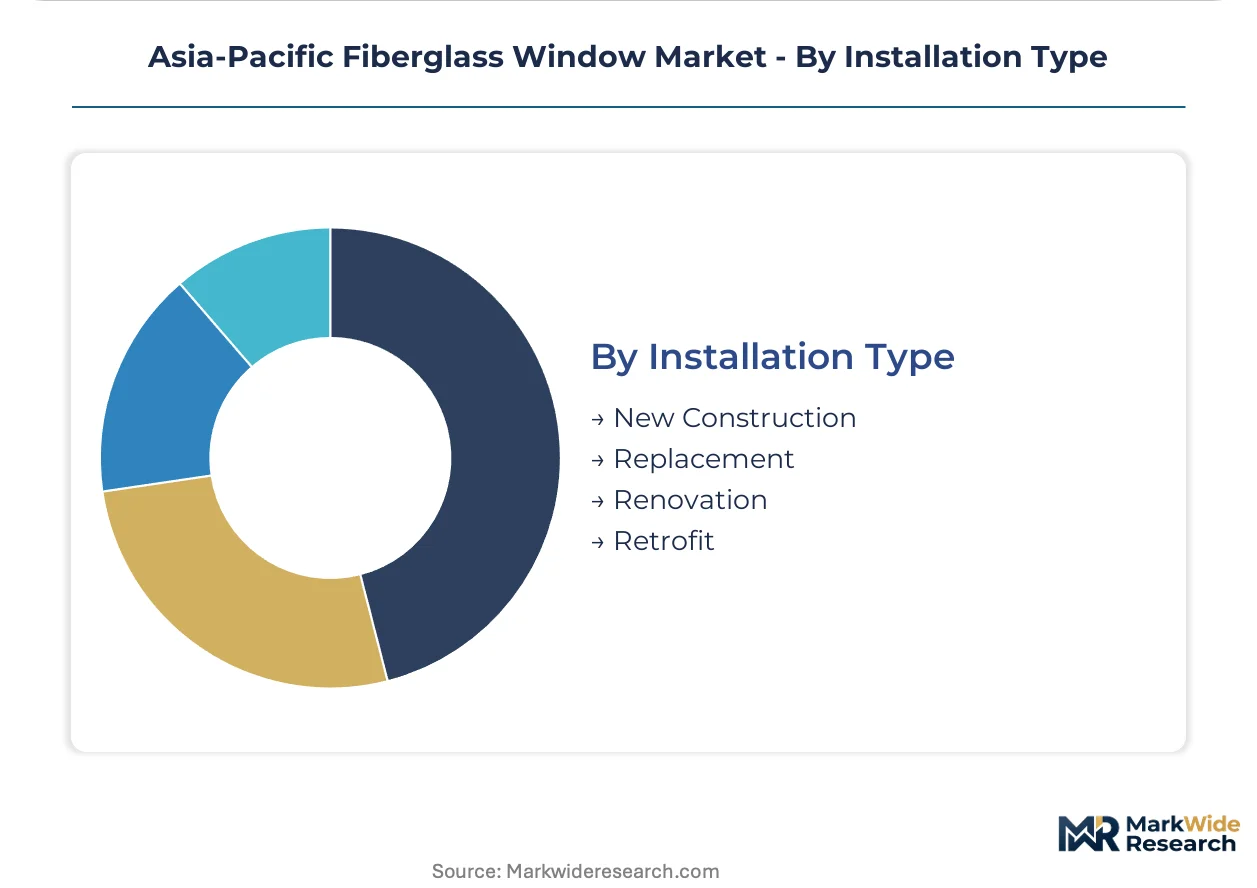
Installation Type:
Project timing and regulatory trigger points determine whether fiberglass windows enter through new construction specification or replacement retrofit.
- New Construction:Green building certification requirements in Singapore and Australian CBD projects embed high-performance GFRP assemblies from schematic design, locking in supplier relationships early.
- Replacement:Aging window stock in Beijing and Tianjin residential towers faces MEE-mandated efficiency upgrades, though PVC-u alternatives capture share on upfront cost.
- Renovation:Partial facade upgrades in Tokyo commercial buildings prioritize thermal performance improvements compatible with existing structural constraints.
- Retrofit:Deep energy retrofits of institutional buildings across China's northern provinces create demand for custom-profile GFRP solutions matching non-standard openings.
New construction commands the steepest pricing; replacement offers the most addressable volume opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta anchors fiberglass window fabrication capacity, with pultrusion facilities clustering along coastal logistics corridors to serve high-rise construction across East Asia.
China
Beijing and Tianjin residential towers drive replacement demand under MEE envelope standards for northern heating zones. The Ministry of Ecology and Environment mandates high-performance window assemblies, forcing specification toward certified GFRP fabricators. Coastal provinces from Jiangsu to Zhejiang concentrate green building certification activity, with Suzhou and Hangzhou emerging as procurement hubs for commercial facade projects.
Japan
Tokyo's Minato ward and Osaka high-rises specify thermally broken GFRP profiles for METI Top Runner compliance in commercial facades. The Ministry of Economy, Trade and Industry escalates thermal performance benchmarks annually, compressing aluminum's share in premium new construction. Nagoya's industrial corridor supplies specialized low-emissivity fiberglass formulations to domestic window fabricators.
Australia
Sydney and Melbourne CBD projects mandate NCC Section J whole-window U-value disclosure, forcing import substitution toward certified regional suppliers. The National Construction Code revision requires pre-submission thermal modeling, consolidating procurement around domestic fabricators with registered testing protocols. Brisbane's subtropical climate zone drives awning window specifications for natural ventilation compliance.
India
Mumbai and Delhi-NCR high-rise residential developments face tightening BIS energy conservation codes, creating first-mover opportunity for certified fiberglass suppliers. The Bureau of Indian Standards escalation in the National Building Code compresses specification timelines for envelope materials. Bangalore's technology corridor shows early green building adoption, though PVC-u retains cost advantage in mass-market segments.
Singapore
Marina Bay district developments specify fiberglass windows through architect-driven procurement platforms embedding thermal data into BIM workflows. The Building and Construction Authority's Green Mark certification exceeds regional compliance rates, prioritizing suppliers with digital-native technical documentation. Jurong industrial zone hosts regional distribution nodes serving Southeast Asian commercial projects.
Asia-Pacific Fiberglass Window Market Competitive Landscape
The competitive structure tilts toward upstream raw material suppliers with captive downstream integration. China Jushi Co., Ltd. dominates glass fiber supply, creating asymmetric leverage over window fabricators dependent on consistent GFRP feedstock. Three archetypes occupy distinct positions: state-linked material conglomerates controlling resin-to-fiber value chains, Japanese specialists in low-emissivity coating convergence, and Western multinationals with regional manufacturing footprints. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with fabricators securing long-term supply agreements to defend margin stability against petrochemical volatility.
Among Asia-Pacific material suppliers, China Jushi Co., Ltd. and Taishan Fiberglass Inc. exemplify the scale-driven upstream archetype, anchoring raw glass fiber availability for downstream window fabricators. Nippon Electric Glass Co., Ltd. occupies a specialization position within Japanese thermal performance compliance. Owens Corning represents the multinational manufacturing footprint model, with regional production assets serving East Asian commercial specifications. These three patterns—upstream concentration, technical specialization, and geographic diversification—structure competitive positioning across procurement channels.
| Leading Market Players |
|---|
| China Jushi Co., Ltd. |
| Taishan Fiberglass Inc. |
| Nippon Electric Glass Co., Ltd. |
| Owens Corning |
| Chongqing Polycomp International Corp. |
| Sichuan Weibo New Material Group Co., Ltd. |
| Shandong Fiberglass Group Corp |
| Saint-Gobain |
| Johns Manville |
| Others |
Pricing and Supply Chain Analysis
Unsaturated polyester resin costs cascade from crude oil benchmarks through three distinct pricing tiers for GFRP window fabricators, with China Jushi's glass fiber monopoly compressing margin buffers for mid-tier extruders serving Australia's NCC-certified projects.
Pricing Analysis
Thermal performance certification anchors value-based pricing for commercial facade specifications, with METI Top Runner compliance and NCC Section J registration commanding premiums over uncertified alternatives. Price differentiation separates architect-specified casement systems from mass-market sliding units, while volume-scale procurement in Singapore's Marina Bay district softens per-unit costs. Pricing pressure stems from PVC-u substitution in India's loosely enforced BIS code environment, where contractors prioritize upfront savings over lifecycle efficiency. Builders represent the most price-sensitive buyer archetype, whereas architects specifying green building certifications exhibit lowest sensitivity to unit cost premiums.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale commercial demand in Sydney and Melbourne CBD projects, bypassing traditional distributor markups. Raw glass fiber supply concentrates in China's coastal provinces, with unsaturated polyester resin and specialized low-emissivity coatings drawing from petrochemical feedstocks. Single-source dependency on China Jushi for GFRP feedstock creates asymmetric leverage over downstream fabricators. Distribution runs through architect-specified procurement platforms in Singapore and certified regional fabricators in Australia, with logistics corridors from Shanghai's Yangtze River Delta serving East Asian construction hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certified fabricators as regulatory divergence between national building codes and subnational green certification schemes eliminates specification-incompetent suppliers.
For Market Incumbents: Hedge against petrochemical input volatility through long-term resin supply agreements with state-linked material conglomerates. Secure captive glass fiber allocations from China Jushi to defend margin stability, while investing in in-house thermal modeling capabilities to capture architect-led specification authority in Australian and Singapore commercial markets.
For New Entrants and Emerging Players: Capture white-space opportunity in India's tightening BIS energy conservation code environment, where certified fiberglass penetration remains nascent against PVC-u dominance. Target Bangalore's technology corridor for early green building adoption, leveraging local fabrication partnerships to compress qualification timelines for National Building Code compliance.
For Investors and Strategic Acquirers: METI's annual escalation of Top Runner thermal benchmarks is the leading indicator that Japanese commercial facade specification will consolidate around thermally broken GFRP specialists. Acquisition targets should demonstrate in-house pultrusion capabilities and established METI compliance documentation, with Nagoya industrial corridor suppliers representing consolidation candidates for regional market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Supply | Captive raw material access insulates margin compression from China Jushi's pricing leverage. |
| Long-term Supply Agreement with Resin Producers | Fixed-price petrochemical contracts stabilize input costs for multi-year commercial project pipelines. |
| Joint Venture with Local Fabricators | India BIS certification partnerships accelerate market entry in tightening code enforcement zones. |
| Green Manufacturing Transition | Low-emissivity coating convergence opens premium Tokyo and Osaka high-rise specifications. |
| Capacity Expansion in Certified Testing Hubs | NCC-registered protocols in Australia capture import substitution from uncertified overseas suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews involving pultrusion technicians, commercial facade procurement managers, building energy code administrators, and architect specification leads. Bottom-up volume estimates from GFRP profile manufacturers reconciled with top-down construction spend data from China's MEE, Japan's METI, and Australia's NCC disclosure requirements.
Data-stream reconciliation across the projection horizon applied product-type segmentation by operable versus fixed assemblies, application-tier splits between commercial curtain wall and residential replacement, and end-user archetype differentiation by specification authority. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory compliance timelines and green building certification adoption rates, with thermal performance benchmark escalation serving as the primary demand driver input.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIS code enforcement intensity in India and petrochemical price volatility affecting unsaturated polyester resin costs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Antibacterial Glass Market
Glass
Antiglare Glass Market
Glass
Low Temperature Laminated Glass Market
Glass
Impact Resistant Glass Market
Glass
Europe Sapphire Glass Market
Glass
Europe Flat Glass Market
Glass
Global Self-Cleaning Glass Market
Glass
Foam Glass Market
Glass
3D Glass Market
Glass
Tempered Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
Soda Feldspar Market
Glass
Patterned Glass Market
Glass
Decorative Glass Market
Glass
Screen-Printing Glass Market
Glass
Insulating Glass Market