
 Low-E Glass Market | 2026-2036
Low-E Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Low-E Glass Market Outlook
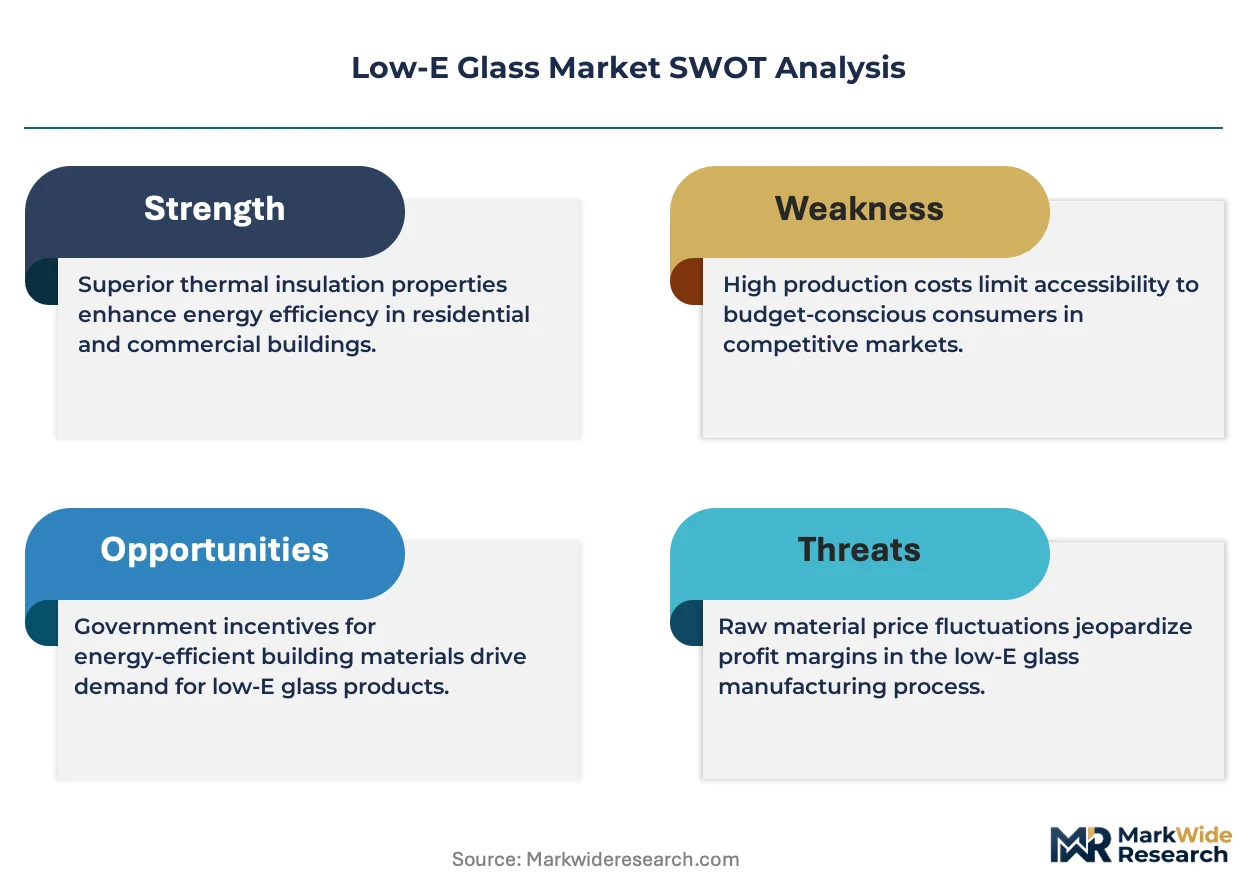
Performance-based glazing specification is hardening as the dominant sales model, shifting transactions from commodity glass to bundled energy-performance contracts. Guardian Glass leverages captive float-line capacity to anchor North American project pipelines. Saint-Gobain differentiates through integrated facade systems that extend beyond substrate supply. PPG Industries, Inc. competes on sputter-coating technology leadership for solar-control variants.
Low-E glass consists of soda-lime silica substrates bearing nanometer-scale metallic oxide coatings, typically silver-based multilayers deposited via magnetron sputtering, engineered to transmit visible light while reflecting infrared thermal radiation and thereby reducing building HVAC loads. Soft coat products dominate specification in commercial architecture due to superior thermal performance, though hard coat variants sustain share in residential retrofits where durability and handling tolerance outweigh peak efficiency. Triple glazing occupies the premium tier as passive-house standards proliferate, while double glazing retains volume leadership across mid-market residential and standard commercial applications.
EPA Energy Star certification, the EU Green Deal's building-performance directives, and evolving IECC model codes in the United States collectively mandate lower U-factors and solar heat gain coefficients, directly expanding addressable demand for coated substrates. China's GB standards and dual carbon goals from MEE further compress allowable thermal transmittance in new construction. Stakeholders must monitor regulatory divergence between performance-based and prescriptive compliance pathways as these determine coating technology selection and regional manufacturing investment priorities.
Market Dynamics
Energy-performance mandates are compressing specification timelines and forcing coating technology upgrades faster than manufacturing capacity can adapt. The gap between regulatory U-factor requirements and installed production capability is widening, creating structural bottlenecks for project delivery.
Growth Catalysts
- EU Green Deal building directives:The EU Green Deal's performance standards are mandating triple-glazed assemblies in new commercial construction across Germany, France, and the Netherlands, pulling demand for high-performance soft-coat substrates.
- Passive-house certification proliferation:Architects and developers pursuing passive-house standards in Austria, Switzerland, and Belgium are specifying quadruple-glazed units with advanced silver-based coatings, expanding the premium product tier.
- China MEE dual carbon enforcement:China's Ministry of Ecology and Environment is tightening thermal transmittance limits in the GB 50189 standard, forcing retrofit cycles in Shanghai and Beijing commercial stock.
Market Restraints
- Silver price volatility:Magnetron sputtering relies on silver oxide multilayers, and London Metal Exchange silver pricing swings directly compress coating margin structures for independent processors without captive metal supply.
- Float-glass supply concentration:High-quality soda-lime silica substrate production clusters in China and the United States, exposing coating specialists to freight cost spikes and import duty friction when sourcing base material.
- Hard-coat performance ceiling:Pyrolytic hard-coat variants cannot achieve the sub-1.0 U-factors now mandated in Nordic markets, structurally excluding this technology from premium specification pools.
Strategic Opportunities
- India commercial construction acceleration:India's Bureau of Energy Efficiency is finalising ECBC 2017 updates for high-rise commercial envelopes, opening specification windows for imported low-E assemblies in Mumbai and Bangalore.
- Facade-integrated photovoltaics convergence:Building-integrated PV manufacturers in Germany and South Korea are partnering with coating specialists to develop spectrally selective substrates that simultaneously manage thermal radiation and harvest electricity.
- Digital specification platforms:Cloud-based glazing calculators certified by PHI and NFRC are compressing the architect-to-manufacturer sales cycle, enabling direct-to-designer channels that bypass traditional distributor markups.
Industry Challenges
- Magnetron sputtering technician scarcity:Vacuum deposition expertise concentrates among aging workforces in Germany and Japan, constraining capacity expansion for new coating lines in emerging markets.
- NFRC/PHI certification timeline compression:Third-party thermal performance verification now takes 14-18 months for novel coating stacks, misaligning with construction procurement schedules and forcing speculative production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-E Glass Market |
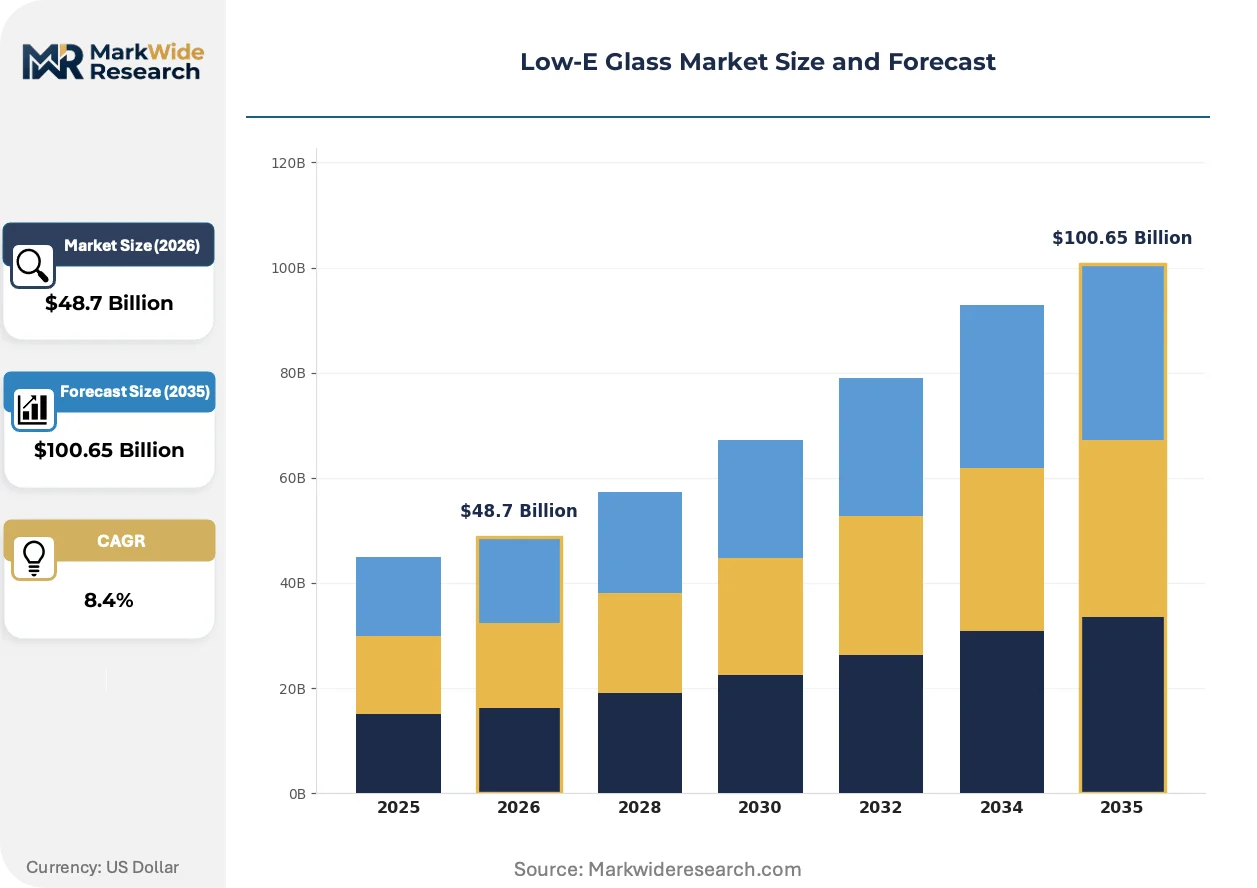
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Coat, Hard Coat, Double Glazing, Triple Glazing Application: Residential, Commercial, Automotive, Architecture End User: Contractors, Builders, Homeowners, OEMs Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | PPG Industries, Inc., CSG Holding Co., Ltd., AGC Inc., Vitro Architectural Glass, Nippon Sheet Glass Co., Ltd., Saint-Gobain, Central Glass Co., Ltd., Taiwan Glass Ind. Corp., Guardian Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-E Glass Market Strategic Shifts
Coating technology is diverging along thermal-performance versus durability axes as regulatory tiers split and end-use requirements sharpen. Manufacturers are forced to place simultaneous bets on sputter-coating refinement and alternative deposition methods.
Dynamic electrochromic glazing is electrifying the commercial facade segment by enabling real-time solar heat gain modulation. Large-scale office developers in California and New York are specifying these systems for net-zero targets. The technology is electrifying traditional static low-E specification by collapsing the distinction between glazing and building energy management systems.
REACH restrictions on fluorinated greenhouse gases are forcing coating manufacturers to abandon sulfur hexafluoride-based plasma cleaning in magnetron sputtering lines. German and French processors are retrofitting argon-based plasma systems at capital costs exceeding €2 million per line. The F-Gas Regulation is compressing process chemistry options and advantaging processors with earlier environmental compliance investments.
Performance-guarantee contracting is displacing commodity spot purchasing in commercial retrofit procurement. Building owners in Chicago, Toronto, and London are contracting facade upgrades on guaranteed energy-savings bases rather than capital expenditure schedules. This model concentrates buyer power among energy service companies and compresses supplier margins to performance-verified outcomes.
Low-E Glass Market Segmentation
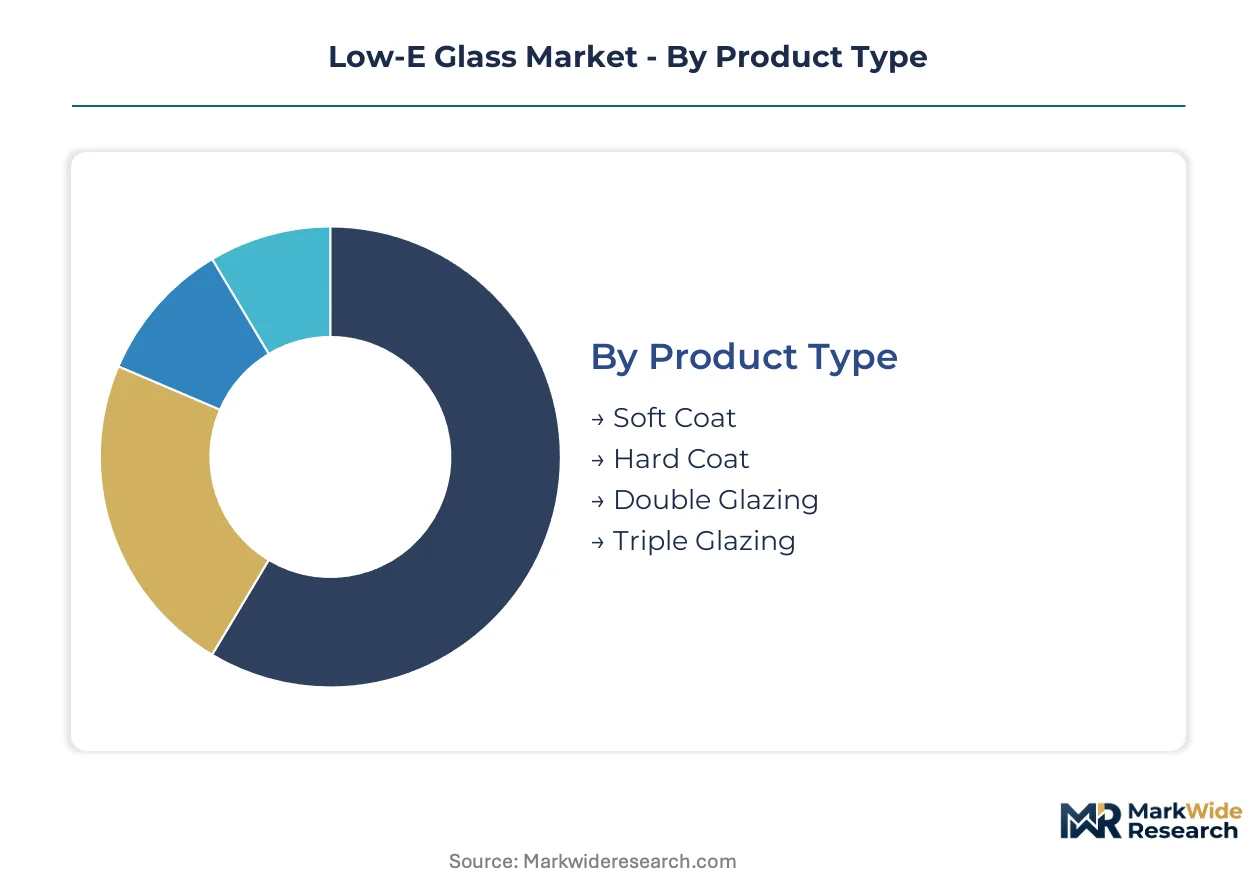
Low-E glass specification diverges sharply by thermal performance tier and installation context, with coating technology and glazing assembly depth determining regulatory compliance and project economics. Segmentation clarity enables manufacturers to align sputter-coating capacity with end-use certification requirements.
Product Type:
Soft-coat products command premium pricing for commercial architecture, while hard-coat variants sustain volume share in residential retrofits where durability outweighs peak efficiency. Double glazing anchors mass-market residential and standard commercial applications; triple glazing occupies the premium tier as passive-house standards proliferate.
- Soft Coat:Magnetron-sputtered silver-based multilayers deposited at ambient temperature deliver sub-1.1 U-factors. Demand concentrates in Germany, France, and Netherlands commercial new-builds where EU Green Deal performance standards mandate triple-glazed assemblies. Regulatory compression of allowable thermal transmittance is accelerating specification away from hard-coat alternatives.
- Hard Coat:Pyrolytic tin oxide coatings fused during float-glass manufacturing withstand handling abrasion and edge-deletion-free fabrication. Residential retrofits in United States Midwest and Southern states favor this variant for cost-sensitive replacement windows where installation speed matters more than peak thermal performance.
- Double Glazing:Two-pane assemblies with one low-E surface and argon fill retain volume leadership across mid-market applications.
- Triple Glazing:Three-pane configurations with dual low-E coatings and krypton fill achieve sub-0.8 U-factors for passive-house certification.
Today's leader: Double Glazing. Tomorrow's challenger: Triple Glazing.
Application:
Commercial building envelopes generate the highest per-project coating area, while residential replacement cycles provide recurring volume. Automotive and specialized architectural segments demand spectrally selective performance beyond standard thermal control.
- Residential:Single-family and multifamily window replacement drives steady demand for hard-coat and entry-level soft-coat products. Retrofit activity clusters in United States Northeast and Midwest where aging housing stock meets tightening state energy codes.
- Commercial:Office towers, healthcare facilities, and educational buildings specify high-performance soft-coat triple glazing for HVAC load reduction. Net-zero targets in California and New York are electrifying facade specification with dynamic glazing integration.
- Automotive:Windshield and side-lite applications require durable coatings compatible with laminated safety glass processing.
- Architecture:Curtain wall and skylight systems demand large-format coated substrates with precise optical uniformity.
Commercial applications expand most quickly; residential maintains the deepest installed base for retrofit conversion.
End User:
Procurement authority fragments across project delivery models, with contractors controlling new-build specification and homeowners driving replacement demand. OEMs impose stringent quality protocols for automotive and appliance integration.
- Contractors:Commercial general contractors and glazing subcontractors specify coated assemblies based on architect performance schedules. Their purchasing concentrates in Germany, China, and United States where construction volume and regulatory pressure intersect.
- Builders:Production homebuilders in United States Sun Belt prioritize cost-standardized hard-coat packages for volume window procurement.
- Homeowners:Retail replacement decisions favor visible clarity and warranty terms over U-factor optimization.
- OEMs:Automotive and appliance manufacturers require coating consistency across multi-year supply agreements.
Contractors dominate premium specification; builders anchor mid-market volume.
Distribution Channel:
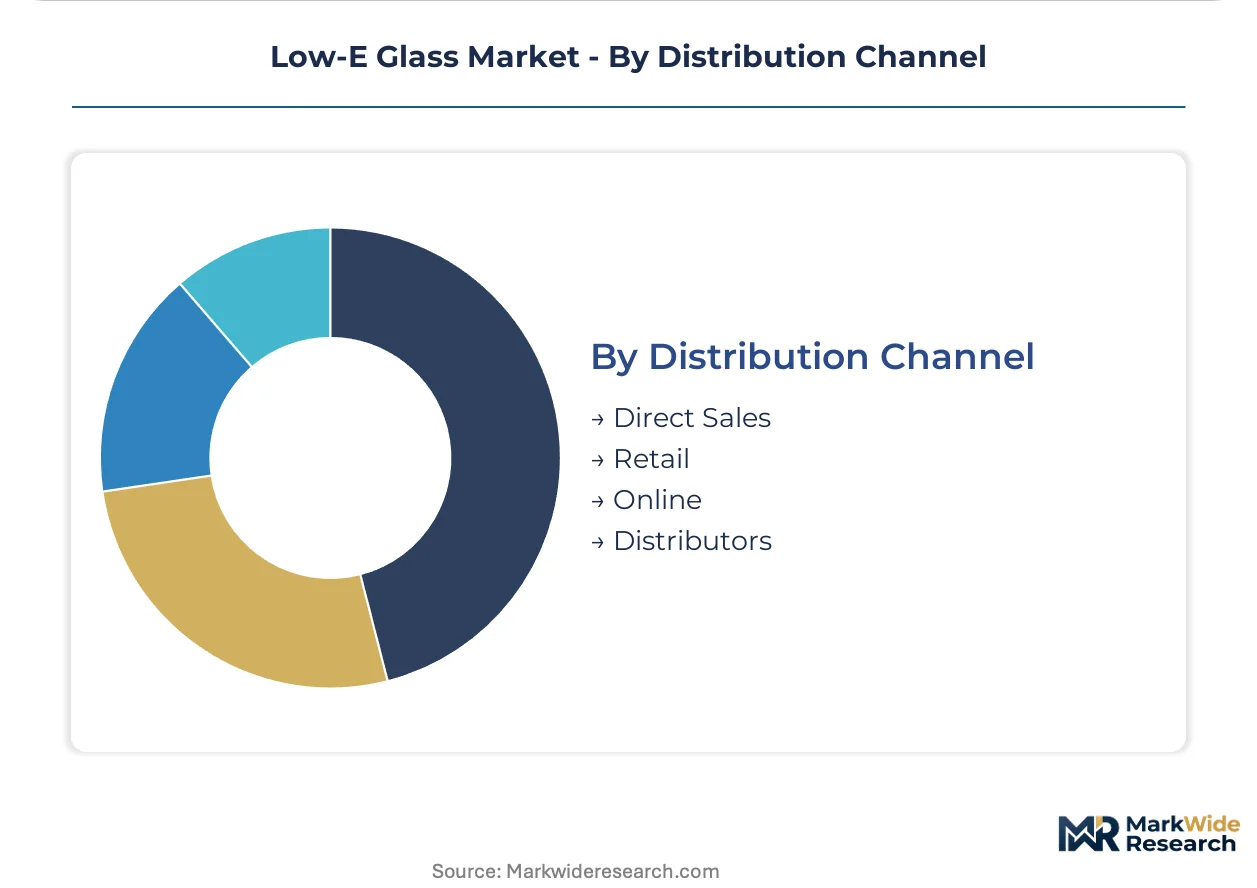
Channel structure reflects project scale and specification complexity, with direct sales capturing engineered facade contracts and distributors serving fragmented residential demand. Digital platforms are compressing architect-to-manufacturer sales cycles.
- Direct Sales:Coating manufacturers and integrated glass processors contract directly with commercial developers and energy service companies for guaranteed-performance facade upgrades. Chicago, Toronto, and London building owners increasingly procure on energy-savings contracting models.
- Distributors:Regional glass distributors inventory standard dimensions for residential contractors and small commercial fabricators. Their markup structures absorb freight cost volatility from concentrated float-glass production.
- Retail:Big-box home improvement channels serve homeowner self-directed replacement projects.
- Online:Cloud-based glazing calculators certified by PHI and NFRC enable direct-to-designer specification bypassing traditional distributor networks.
Direct sales capture margin in performance-contracting; online channels gain share fastest among early-adopter architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China exhibit divergent regulatory trajectories despite comparable construction volumes, with Berlin accelerating passive-house mandates while Beijing prioritizes retrofit enforcement over new-build standards.
United States
Commercial retrofit cycles in Chicago and New York drive specification of triple-glazed assemblies for net-zero targets. The EPA Energy Star certification and evolving IECC model codes compress allowable U-factors in new construction. Guardian Glass anchors North American project pipelines through captive float-line capacity concentrated in the Upper Midwest and Southeast manufacturing corridors.
Germany
Passive-house certification proliferation in Berlin and Munich pulls demand for quadruple-glazed units with advanced silver-based coatings. The EU Green Deal's building-performance directives mandate triple-glazed assemblies in new commercial construction. Saint-Gobain differentiates through integrated facade systems extending beyond substrate supply in the Rhine-Ruhr and Bavarian industrial clusters.
China
Shanghai and Beijing commercial stock face accelerated retrofit cycles under MEE dual carbon enforcement tightening thermal transmittance limits. GB 50189 standard revisions compress allowable U-factors faster than installed coating capacity can adapt. CSG Holding Co., Ltd. exemplifies domestic float-glass concentration that exposes coating specialists to freight cost spikes when sourcing base material.
India
Mumbai and Bangalore high-rise commercial envelopes open specification windows for imported low-E assemblies as the Bureau of Energy Efficiency finalises ECBC 2017 updates. The country's national building energy code mandates higher-performance glazing in new construction above 20,000 square meters. Regional glazing fabricators in Maharashtra and Karnataka lack magnetron sputtering expertise, constraining domestic capacity expansion.
Japan
Tokyo and Osaka commercial developers specify dynamic electrochromic glazing for real-time solar heat gain modulation in premium office towers. METI efficiency standards for building envelopes tighten faster than hard-coat technology can achieve. Nippon Sheet Glass Co., Ltd. and Central Glass Co., Ltd. occupy positions within an aging vacuum deposition workforce that limits coating line expansion in emerging markets.
Low-E Glass Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated glass processors capturing premium commercial specification while independent coaters serve fragmented residential demand. Three to five multinational conglomerates anchor the premium tier through captive raw material supply and certification infrastructure. Mid-scale regional fabricators compete on installation speed and distributor relationships in retrofit markets. Dominant competitive moves include backward integration into float-glass production and technology licensing partnerships for electrochromic coating stacks.
Among Japan-based fabricators, Nippon Sheet Glass Co., Ltd. and Central Glass Co., Ltd. exemplify the vacuum deposition expertise archetype concentrated among aging workforces. Guardian Glass represents North American integrated supply chain positioning with captive float-line capacity. PPG Industries, Inc. sits within the sputter-coating technology leadership archetype for solar-control variants. Saint-Gobain occupies a position as the integrated facade systems provider extending beyond substrate supply.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| CSG Holding Co., Ltd. |
| AGC Inc. |
| Vitro Architectural Glass |
| Nippon Sheet Glass Co., Ltd. |
| Saint-Gobain |
| Central Glass Co., Ltd. |
| Taiwan Glass Ind. Corp. |
| Guardian Glass |
| Others |
Value Chain & Pricing Dynamics
Magnetron sputtering technician scarcity in Germany and Japan drives labor-cost differentials that widen pricing-tier spreads between premium soft-coat and entry-level hard-coat products. Coating specialists with captive vacuum deposition expertise command margin premiums, while independent processors absorb silver price volatility and certification delays.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard double-glazing assemblies, compressing margins for mid-market fabricators. Three-tier pricing structure across premium, standard, and economy levels separates PHI-certified triple-glazed units from Energy Star-compliant double-glazing and uncoated commodity glass. Pricing pressure stems from EU F-Gas Regulation compliance costs, which add capital burden to European coating lines. Residential retrofit contractors in the United States Midwest exhibit highest price sensitivity, while passive-house developers in Germany accept premium positioning for sub-0.8 U-factor performance.
Supply Chain Analysis
NFRC and PHI certification timelines gate supply chain access, with 14-18 month verification cycles constraining new coating stack commercialization. Float-glass substrate production concentrates in China, the United States, and Germany, exposing coating specialists to freight cost spikes when sourcing soda-lime silica base material. Magnetron sputtering draws from silver oxide multilayers, argon process gases, and precision vacuum chambers. Single-source vulnerability concentrates in aging German and Japanese vacuum deposition workforces. Distribution runs through direct sales for commercial facade contracts and regional distributors for fragmented residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tightening into structural demand expansion, with the EU Green Deal's building-performance directives mandating triple-glazed assemblies that outpace installed coating capacity.
For Market Incumbents: Acquire captive float-glass production capacity to anchor substrate supply security against import duty friction and freight volatility. Expand magnetron sputtering certification infrastructure to compress PHI verification timelines and capture premium specification pools. Electrify product portfolios through electrochromic coating partnerships, defending against dynamic glazing substitution in California and New York net-zero developments. For New Entrants and Emerging Players: Capture specification windows in India's high-rise commercial envelope segment as ECBC 2017 updates mandate higher-performance glazing above 20,000 square meters. Target Mumbai and Bangalore project pipelines where domestic magnetron sputtering expertise remains scarce. Deploy cloud-based glazing calculators certified by PHI and NFRC to establish direct-to-designer channels bypassing traditional distributor markups. For Investors and Strategic Acquirers: Integrated glass processors with captive float-line capacity and established certification infrastructure are the most active acquirer in this space, consolidating independent coating specialists to secure project pipeline access. Long-term viability hinges on regulatory divergence between performance-based and prescriptive compliance pathways, with performance-based markets offering sustained premium pricing. Monitor silver price volatility and REACH F-Gas enforcement timelines as inflection indicators for coating margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float-Glass Production | Captive soda-lime silica supply secures substrate access against China-U.S. production concentration. |
| Electrochromic Coating Stack Partnership | Dynamic glazing integration captures California and New York net-zero office tower specification. |
| PHI-NFRC Certification Infrastructure Expansion | Compressed verification timelines align novel coating stacks with construction procurement schedules. |
| Argon-Based Plasma System Retrofit | REACH F-Gas compliance avoids sulfur hexafluoride restrictions in German and French processing lines. |
| Direct-to-Designer Digital Platform Launch | Cloud-based glazing calculators bypass distributor markups and accelerate architect specification cycles. |
Study Parameters
Direct dialogue with coating line engineers, commercial glazing contractors, facade system architects, and energy service company procurement directors grounded qualitative findings in operational reality. Secondary validation drew from EPA Energy Star certification databases, EU Green Deal directive filings, China MEE GB standard revisions, and SEC 10-K disclosures from publicly traded glass processors. Bottom-up project pipeline assessments and top-down regulatory mandate modeling were triangulated against trade flow data and construction permit tracking.
Market size and growth trajectory outputs across the analysis window reflect segmented modeling of soft-coat versus hard-coat technology splits, double-glazing versus triple-glazing assembly penetration, and commercial-residential-automotive end-use distribution. CAGRs were derived from regression analysis of historical construction activity correlated with regulatory U-factor compression timelines. Silver price volatility indices and magnetron sputtering capacity utilization rates served as industry-specific forecast inputs.
Silver price spikes, REACH F-Gas Regulation enforcement acceleration, and NFRC certification timeline extensions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding regulatory adoption trajectories and coating technology substitution elasticities. A model refresh is warranted upon material change in EU Green Deal implementation pace or China MEE dual carbon enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
3D Glass Substrate Market
Glass
3D Glass Market
Glass
Impact Resistant Glass Market
Glass
Latin America Flat Glass Market
Glass
Screen-Printing Glass Market
Glass
Technical Glass Market
Glass
Glazing Gel Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Glass Polishing Powder Market
Glass
Crystalware and Glassware Market
Glass
Glass Grade Dolomite Market
Glass
Mexico Flat Glass Market
Glass
Glass Lens Market
Glass
Global Glass Flake Coatings Market
Glass
North America Flat Glass Market
Glass
Pharmaceutical Glass Tubing Market