
 North America below Grade Waterproofing Membranes Market | 2026-2036
North America below Grade Waterproofing Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
North America below Grade Waterproofing Membranes Market Intelligence
EPA stormwater management mandates under the Clean Water Act is shifting specification priorities toward high-performance membrane systems in commercial and infrastructure builds. Sika AG leverages its integrated manufacturing footprint across the United States and Canada to sustain supply chain responsiveness for large-scale foundation projects. BASF SE anchors its position through advanced polymer chemistry R&D that differentiates its bituminous and synthetic membrane portfolios. RPM International Inc. competes through specialized channel control in the residential and light commercial basement segments.
Below grade waterproofing membranes are multi-layer synthetic or bituminous barriers installed beneath ground level to prevent hydrostatic pressure infiltration into structural foundations, basements, tunnels, and retaining walls, typically specified to withstand minimum 60 psi water head pressure and temperature cycling from -20°F to 180°F. Bituminous membranes occupy the largest installed base due to cost familiarity and contractor training density, though TPO segments are gaining specification share in green-certified commercial builds where heat-welded seam integrity and reflective surface properties align with LEED performance criteria. Self-adhered installation methods are expanding fastest among urban foundation applications where VOC restrictions and labor constraints limit torch-applied alternatives.
EPA regulations, ASTM D6134 standards for polymer-modified bitumen, and CSA S478 guidelines in Canada collectively shape product compliance, testing protocols, and market access requirements for membrane suppliers across North America. Municipal stormwater ordinances in Chicago, Toronto, and Houston are tightening subsurface drainage mandates that directly expand membrane specification scope for new commercial foundations. Stakeholders must monitor evolving state-level building code harmonization between the United States and Canada, as divergent adoption timelines for updated moisture protection standards will create competitive advantage for suppliers with dual-certification capabilities.
Market Dynamics
Self-adhered membrane technology is compressing installation timelines and reshaping contractor specification patterns across commercial foundation projects in the United States and Canada.
Growth Catalysts
- EPA Stormwater Mandates:The Clean Water Act's municipal separate storm sewer system regulations are expanding membrane specification scope for commercial basements and infrastructure builds in Houston and Chicago.
- Green Building Certification:LEED performance criteria for heat-welded seam integrity and reflective surfaces are accelerating TPO membrane adoption in certified commercial construction across California and Texas.
- Urban Labor Constraints:VOC restrictions and fire safety codes in dense metropolitan areas are displacing torch-applied methods with self-adhered bituminous systems.
Market Restraints
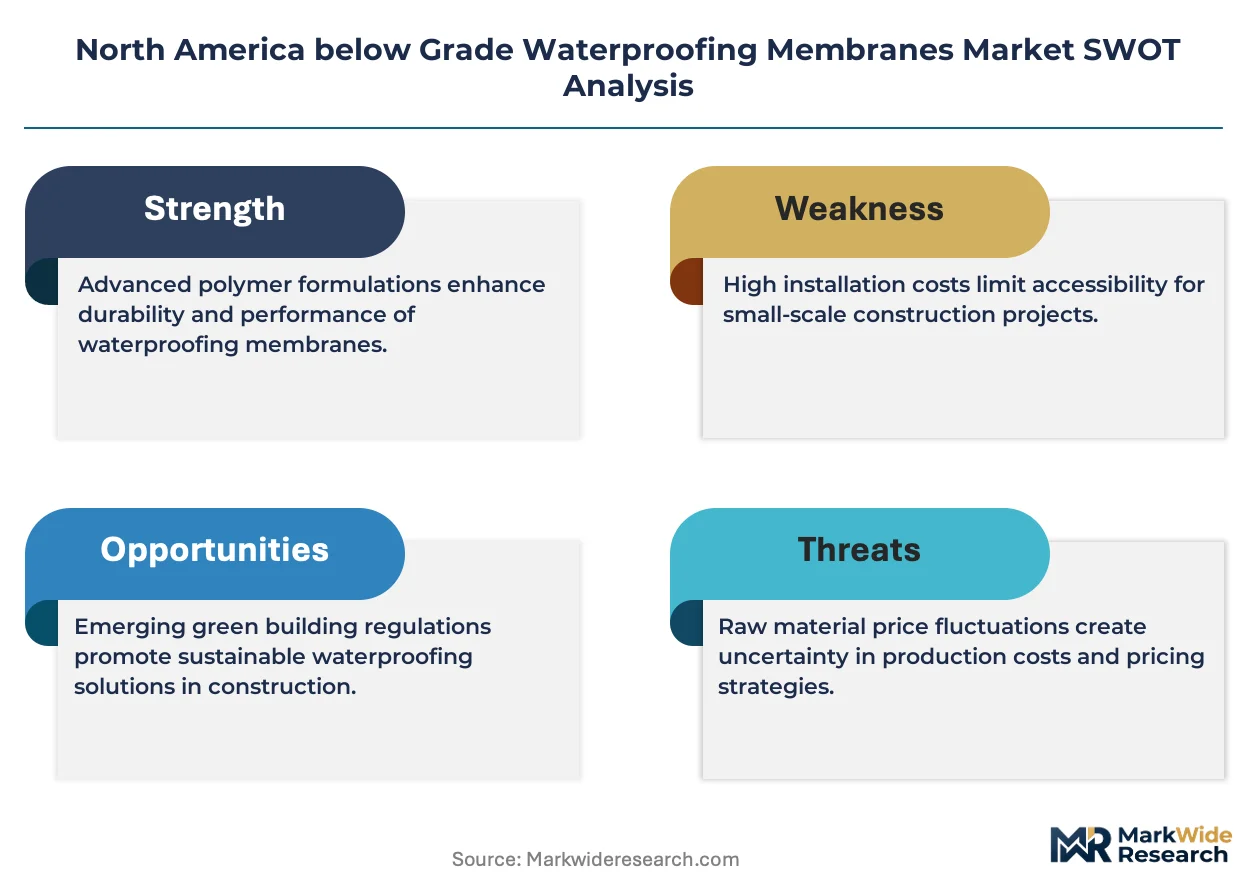
- Petroleum Feedstock Volatility:Asphalt and polymer modifier price swings compress margins for bituminous membrane producers dependent on crude oil derivatives.
- Contractor Training Density:Skilled applicator scarcity for TPO heat-welding techniques limits specification velocity in secondary metropolitan markets.
- Regional Code Fragmentation:Divergent adoption timelines for updated moisture protection standards between US states and Canadian provinces create certification complexity.
Strategic Opportunities
- Canadian Infrastructure Renewal:CSA S478 guideline harmonization with US standards creates dual-certification pathways for suppliers targeting cross-border foundation projects.
- Below-Grade Retrofit Segment:Aging commercial building stock in Toronto and Montreal presents membrane replacement demand outside new construction cycles.
- Prefabricated Drainage Integration:Convergence of membrane systems with composite drainage boards offers bundled specification opportunities in high-performance commercial builds.
Industry Challenges
- Certification Timeline Compression:ASTM D6134 testing protocols and EPA compliance documentation extend product launch cycles for modified bitumen innovations.
- Application Skill Migration:Experienced torch-applied specialists resist retraining for self-adhered and TPO systems, creating workforce transition friction in established contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America below Grade Waterproofing Membranes Market |
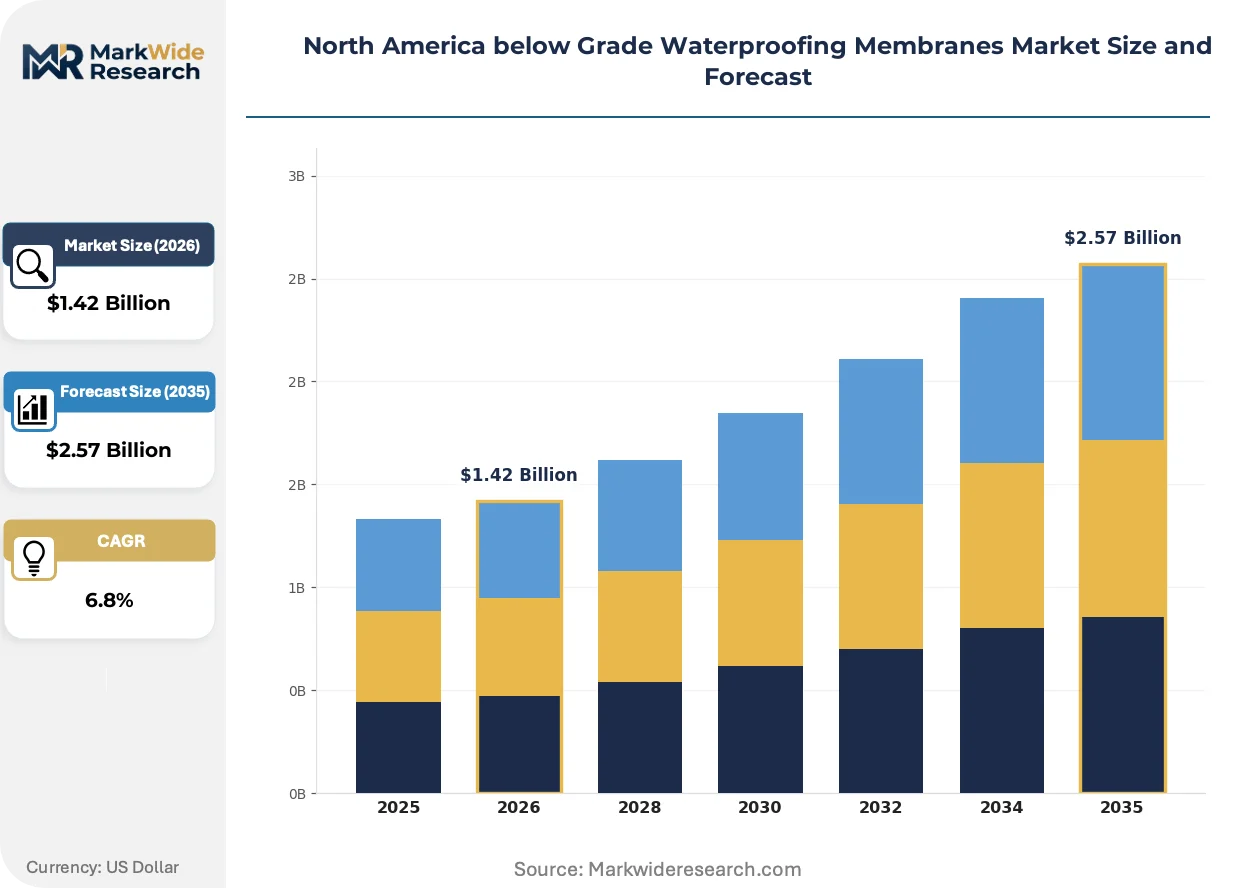
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous, PVC, TPO, EPDM Installation Method: Direct Bond, Mechanically Attached, Loose Lay, Self-Adhered End User: Residential, Commercial, Industrial, Infrastructure Application: Foundation, Basement, Tunnel, Retaining Wall |
| Companies Covered | Sika AG, BASF SE, RPM International Inc., MAPEI S.p.A., Carlisle Companies Inc., GCP Applied Technologies Inc., Minerals Technologies Inc., W. R. Meadows Inc., Tremco Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America below Grade Waterproofing Membranes Market Strategic Shifts & Innovations
Membrane chemistry and installation methodology are converging to address hydrostatic pressure performance while reducing field labor dependency and environmental compliance burden.
Polymer-modified bitumen formulations with SBS and APP elastomers are electrifying the performance envelope for self-adhered systems, enabling 60 psi water head resistance without torch application. Commercial contractors in Texas and California are specifying these materials for urban foundation projects where open-flame restrictions apply. The technology is electrifying competitive positioning among suppliers capable of delivering peel-and-stick performance parity with traditional heat-welded alternatives.
EPA enforcement of municipal stormwater ordinances under the Clean Water Act is mandating enhanced subsurface drainage integration for new commercial foundations. Chicago, Houston, and Toronto have adopted stringent runoff containment requirements that expand membrane specification scope to include composite protection board systems. Infrastructure and commercial basement segments are responding by bundling membrane and drainage specifications into single-source procurement packages.
General contractors are consolidating specification authority through design-build delivery models, compressing traditional architect-led membrane selection processes. Distribution channels face disintermediation pressure as direct manufacturer-to-contractor relationships capture project-level data and loyalty. This concentration is most visible in Texas and California commercial construction, where self-perform capabilities and volume purchasing agreements favor suppliers with integrated manufacturing and technical field support.
North America below Grade Waterproofing Membranes Market Segmentation
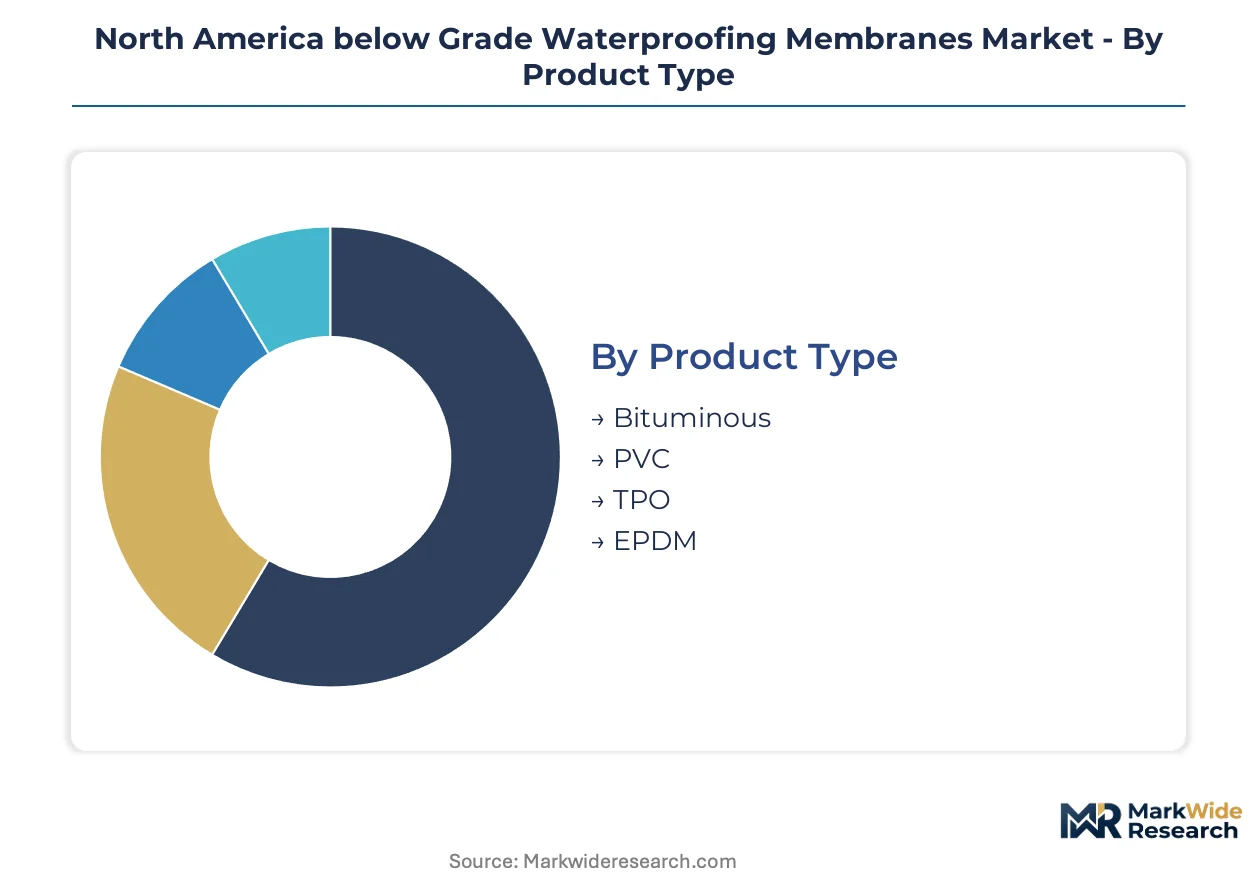
Segmentation in below grade waterproofing membranes reveals how specification authority migrates between architects, contractors, and owners based on project scale and regulatory exposure. Product chemistry, installation methodology, and end-use risk tolerance create distinct procurement patterns across commercial foundations, infrastructure tunnels, and residential basements. Understanding these divides enables suppliers to align technical service resources with decision-maker priorities.
Product Type:
Cost familiarity and contractor training density drive specification patterns across membrane chemistries, with performance premiums commanding share in green-certified and high-hydrostatic applications.
- Bituminous:Polymer-modified asphalt formulations with SBS or APP elastomers dominate installed base due to decades of contractor training infrastructure and material cost predictability. Demand concentrates in commercial foundation projects across Texas and California where self-adhered variants displace torch-applied systems under municipal fire codes.
- TPO:Thermoplastic polyolefin delivers heat-welded seam integrity and reflective surface properties that satisfy LEED performance criteria in certified commercial construction. California and Texas commercial builds are accelerating specification as general contractors consolidate design-build authority and prioritize single-source warranty coverage.
- PVC:Polyvinyl chloride membranes offer chemical resistance and dimensional stability for industrial containment applications and aggressive soil conditions. Specifications track petrochemical facility expansions and manufacturing plant foundations across the US Gulf Coast.
- EPDM:Ethylene propylene diene terpolymer provides elastomeric recovery and cold-temperature flexibility for Canadian infrastructure tunnels and retaining walls subject to freeze-thaw cycling. Toronto and Montreal transit authorities specify EPDM for below-grade transit infrastructure.
Bituminous leads on scale; TPO leads on momentum.
Installation Method:
Application speed and labor skill requirements reshape competitive positioning as metropolitan VOC restrictions and insurance liability reshape field methodology preferences.
- Self-Adhered:Peel-and-stick membranes with factory-applied adhesive layers compress installation timelines and eliminate open-flame ignition risks. Urban foundation projects in Chicago, Houston, and Toronto specify these systems under tightened fire safety ordinances and labor shortage conditions.
- Mechanically Attached:Fastener-based securing systems anchor membranes to structural substrates in high-wind and seismic zones. Commercial basement applications in California specify mechanical attachment for code compliance with structural movement tolerance requirements.
- Direct Bond:Liquid-applied or fully adhered systems create monolithic barriers without penetration points. Industrial containment and tank farm foundations specify direct bond for chemical resistance and seam elimination.
- Loose Lay:Unattached membrane placement with ballast or protection board overlay suits temporary waterproofing and accessible retrofit applications. Aging commercial stock in Toronto and Montreal deploys loose lay for phased basement remediation.
Self-adhered systems expand most quickly; mechanically attached retains structural-critical share.
End User:
Risk tolerance and warranty duration differentiate procurement patterns, with infrastructure entities demanding multi-decade performance guarantees and residential owners prioritizing first-cost containment.
- Commercial:Office, retail, and hospitality developers specify membrane systems with 20-year warranties and integrated drainage composites. Texas and California commercial construction concentrates demand for TPO and self-adhered bituminous in design-build delivery models.
- Infrastructure:Transit authorities, water treatment facilities, and highway departments mandate ASTM D6134 compliance and third-party inspection protocols. EPA stormwater mandates under the Clean Water Act expand membrane scope for Houston and Chicago municipal projects.
- Residential:Single-family and multifamily builders prioritize material cost containment and rapid installation turnover. Light commercial basement segments across secondary US metropolitan markets specify contractor-familiar bituminous systems.
- Industrial:Manufacturing, petrochemical, and power generation facilities demand chemical resistance and hydrostatic pressure ratings exceeding standard commercial specifications. US Gulf Coast industrial expansions drive specialized PVC and reinforced bituminous demand.
Commercial commands volume concentration; infrastructure delivers contract duration premiums.
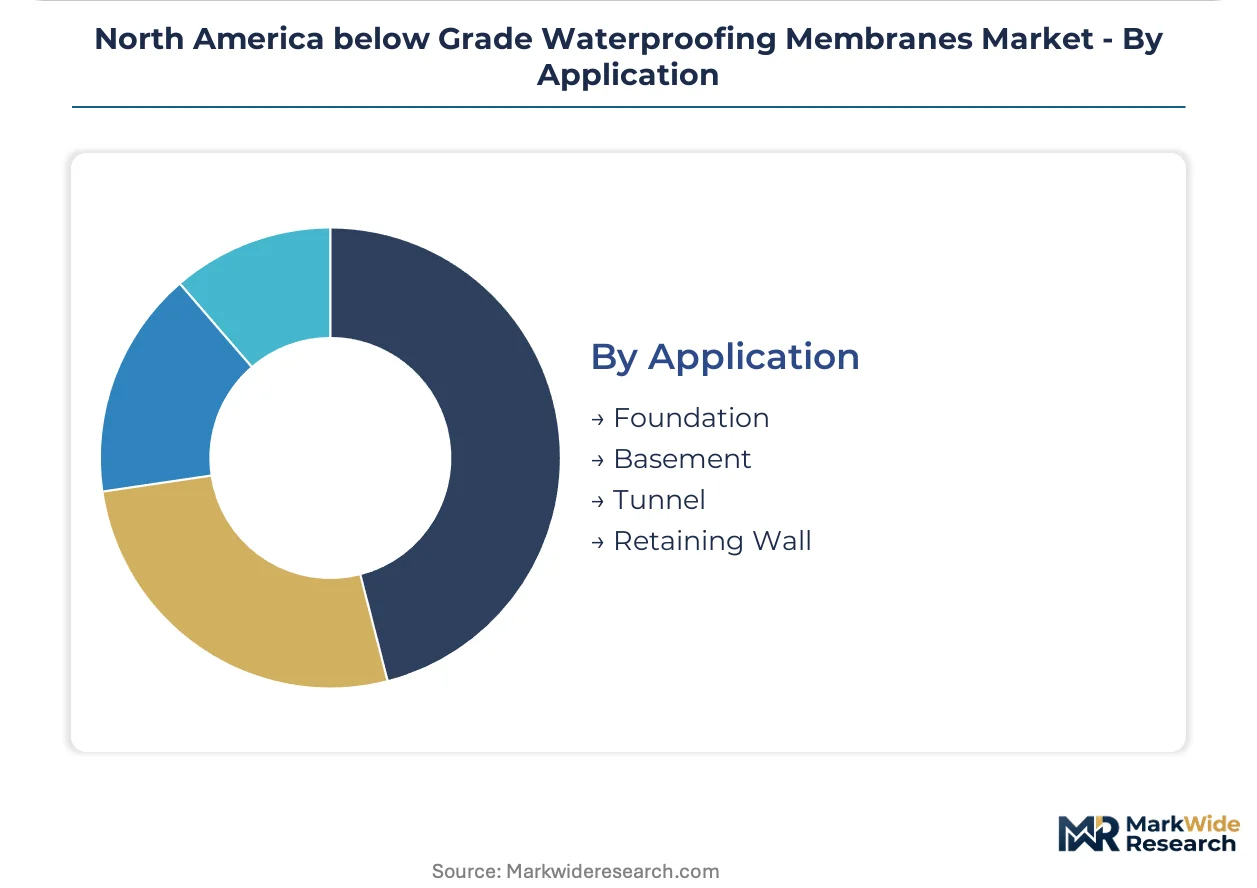
Application:
Structural exposure to hydrostatic pressure and soil chemistry dictates membrane specification thickness, reinforcement type, and drainage integration requirements.
- Foundation:Slab and footing waterproofing for commercial and residential structures requires 60 psi minimum water head resistance. Texas and California urban foundations specify self-adhered bituminous and TPO systems with composite drainage boards.
- Tunnel:Transit, utility, and vehicular tunnel linings demand elastomeric recovery and root-puncture resistance. Toronto and Montreal infrastructure authorities specify EPDM and reinforced PVC for below-grade transit corridors.
- Basement:Below-grade wall and slab protection for commercial and residential buildings balances cost with moisture intrusion risk. Chicago and Houston commercial basements respond to municipal stormwater ordinances with enhanced membrane and drainage specifications.
- Retaining Wall:Earth-retaining structures subject to lateral soil pressure and seasonal water table fluctuation require high-tensile reinforcement. Infrastructure and hillside residential applications across California and British Columbia specify heavy-duty bituminous or EPDM systems.
Foundation applications dominate unit volume; tunnel specifications command performance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American waterproofing membrane industry traces its commercial scale to post-war US infrastructure expansion and the 1970s energy crisis that drove below-grade building efficiency mandates. EPA stormwater regulations and municipal fire codes now reshape specification patterns across sub-regional markets.
United States
Commercial foundation construction in Texas and California concentrates demand for self-adhered bituminous and TPO systems. EPA Clean Water Act enforcement in Houston and Chicago mandates enhanced subsurface drainage integration for new commercial basements. General contractors in Dallas-Fort Worth and Los Angeles consolidate specification authority through design-build delivery models.
Canada
Infrastructure tunnel projects in Toronto and Montreal drive EPDM specification for freeze-thaw cycling resistance. CSA S478 guideline harmonization with US ASTM standards creates dual-certification pathways for cross-border foundation suppliers. Aging commercial building stock in Vancouver and Calgary generates below-grade retrofit membrane demand outside new construction cycles.
Mexico
Industrial manufacturing expansion across Nuevo León and the Bajío Region attracts bituminous membrane specification for plant foundations. Mexican federal environmental regulations align with NAFTA-era technical standards for commercial construction materials. Monterrey and Querétaro industrial corridors concentrate waterproofing procurement for automotive and aerospace facility builds.
North America below Grade Waterproofing Membranes Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology sophistication and certification breadth. The supplier base stratifies into three tiers: integrated chemical conglomerates with captive polymer supply, specialized construction material firms with regional manufacturing footprints, and regional distributors with installation service capabilities. Consolidation pressure intensifies as general contractors demand single-source warranty coverage spanning membrane and drainage composites.
Within the integrated chemical tier, Sika AG and BASF SE exemplify multinational positioning through North American manufacturing scale and polymer chemistry depth. RPM International Inc. occupies a specialized position serving residential and light commercial basement segments through contractor channel relationships. These three entities represent divergent strategic archetypes: chemical integration, technical specification leadership, and distribution intimacy.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| RPM International Inc. |
| MAPEI S.p.A. |
| Carlisle Companies Inc. |
| GCP Applied Technologies Inc. |
| Minerals Technologies Inc. |
| W. R. Meadows Inc. |
| Tremco Incorporated |
| Others |
Cost & Logistics Intelligence
General contractor consolidation in Texas and California commercial construction anchors the project-based pricing model, where volume purchasing agreements and design-build delivery concentrate bargaining power among large-scale foundation developers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the membrane market by certification grade and performance tier. Premium TPO systems with LEED-aligned heat-welded specifications command substantial markups over commodity bituminous alternatives. Cost compression in standard-grade bituminous membranes is intensifying because petroleum feedstock volatility compresses producer margins. Residential basement contractors exhibit highest price sensitivity, while infrastructure entities with multi-decade warranty requirements demonstrate lowest sensitivity.
Supply Chain Analysis
Skilled applicator scarcity in Houston, Chicago, and Toronto manufacturing corridors constrains membrane production scaling and drives wage premiums for certified installation technicians. Manufacturing concentrates in the United States, Canada, and Mexico under NAFTA-aligned technical standards. Production draws from asphalt, SBS/APP elastomers, and polyolefin resins as primary inputs. Single-source vulnerability in polymer modifier supply creates exposure to petrochemical price cycles. Distribution runs through specialized construction material distributors with contractor channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America below grade waterproofing membranes market represents a late-cycle quality story, with EPA stormwater mandates under the Clean Water Act shifting procurement toward high-performance membrane systems with enhanced drainage integration.
For Market Incumbents: Extend technical service capabilities into composite drainage board bundling to capture single-source procurement packages from consolidating general contractors. Deepen backward integration into polymer modifier supply to defend margins against petroleum feedstock volatility. Prioritize dual-certification investment for ASTM D6134 and CSA S478 harmonization to capture cross-border foundation projects. For New Entrants and Emerging Players: EPA stormwater mandates in Houston and Chicago open a window for specialized drainage-integrated membrane systems targeting municipal commercial basement specifications. Target below-grade retrofit demand in Toronto and Montreal aging commercial stock outside new construction cycles. Pursue direct contractor relationships through prefabricated membrane-drainage composite offerings to bypass established distribution channels. For Investors and Strategic Acquirers: Chemical conglomerates with captive polymer supply are the most active acquirer in this space, seeking membrane specialists to complete construction material portfolios. Long-term viability hinges on green building certification alignment and stormwater regulation enforcement durability. Monitor municipal stormwater ordinance adoption velocity in secondary US metropolitan markets as inflection indicator for specification demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | ASTM D6134 and CSA S478 alignment unlocks cross-border procurement from Houston to Toronto infrastructure authorities. |
| Prefabricated Drainage Integration | Composite membrane-drainage board bundling captures design-build specification authority from consolidating general contractors. |
| Self-Adhered Capacity Expansion | Peel-and-stick manufacturing scale addresses urban VOC restrictions and fire safety codes in Chicago and Houston. |
| Polymer Modifier Backward Integration | Captive SBS/APP supply insulates margin compression from crude oil derivative price volatility. |
| Technical Field Support Expansion | On-site welding certification and inspection services differentiate premium TPO positioning in LEED-certified California commercial builds. |
Research Approach
Direct dialogue with waterproofing contractors, commercial general contractors, municipal infrastructure procurement officers, and polymer R&D directors grounded the qualitative foundation. Secondary validation drew from EPA enforcement documentation, ASTM standard revision records, municipal stormwater ordinance databases, and construction material trade flow data. Bottom-up project pipeline assessment and top-down construction spend analysis were triangulated to calibrate market sizing.
Top-down macroeconomic construction indicators and bottom-up membrane specification tracking were reconciled across the analysis window. Segmentation modeling incorporated product chemistry, installation methodology, end-user risk tolerance, and application hydrostatic pressure exposure. CAGRs were derived from construction cycle phasing and regulatory enforcement timeline assumptions. Forecast inputs included municipal stormwater ordinance adoption schedules and green building certification penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA enforcement or prolonged petroleum price volatility. Forecasts reflect documented assumptions regarding contractor training density and code harmonization timelines. Material deviation in municipal stormwater ordinance adoption velocity or polymer feedstock price regimes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Nafion Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Inorganic Ion Exchange Materials Market