
 Low Temperature Laminated Glass Market | 2026-2036
Low Temperature Laminated Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Laminated Glass Market Intelligence
Automotive OEMs is bifurcating demand away from traditional construction specifiers as electric vehicle architectures require cold-bendable glazing solutions. Saint-Gobain leverages its European automotive glass R&D footprint to sustain technical leadership in ionoplast interlayer formulations. AGC Inc. anchors Asian supply through dedicated low-temperature lamination lines serving premium EV programs. Guardian Industries differentiates via vertical integration from float glass through to finished laminated assemblies.
Low temperature laminated glass bonds multiple glass plies with thermoplastic interlayers such as ionoplast or advanced PVB at processing temperatures below conventional autoclave cycles, preserving optical clarity while enabling cold-forming of complex curves for automotive and architectural applications. The product type landscape shows multi-layer configurations capturing premium margin pools as safety regulations tighten, while structural grades face slower uptake pending updated building code recognition. Application demand concentrates in automotive glass where weight reduction and aerodynamic shaping command priority, with building facades representing a mature volume base.
Europe's ECHA enforces REACH compliance on plasticizer content in interlayer films, while CE marking under the Construction Products Regulation governs structural glazing approval timelines. The US NHTSA maintains Federal Motor Vehicle Safety Standard 205 for automotive glazing optical and penetration performance. Stakeholders must monitor evolving harmonization between automotive crashworthiness standards and architectural fall-protection codes as cross-industry material specifications converge.
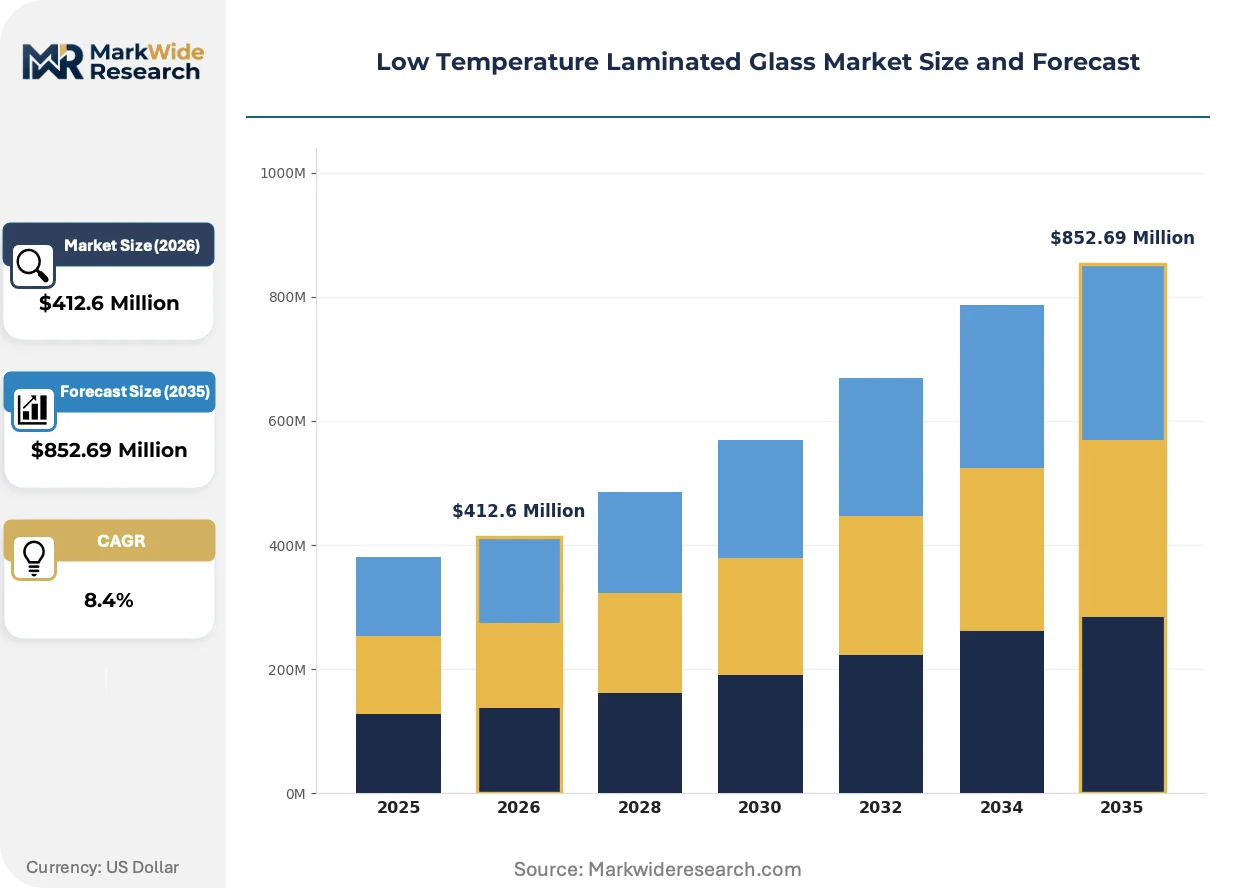
Market Dynamics
Europe's F-Gas Regulation and REACH compliance requirements are compressing traditional autoclave curing cycles, forcing manufacturers to retool interlayer bonding infrastructure toward sub-100°C processing windows that preserve ionoplast optical performance while eliminating fluorinated gas dependencies.
Growth Catalysts
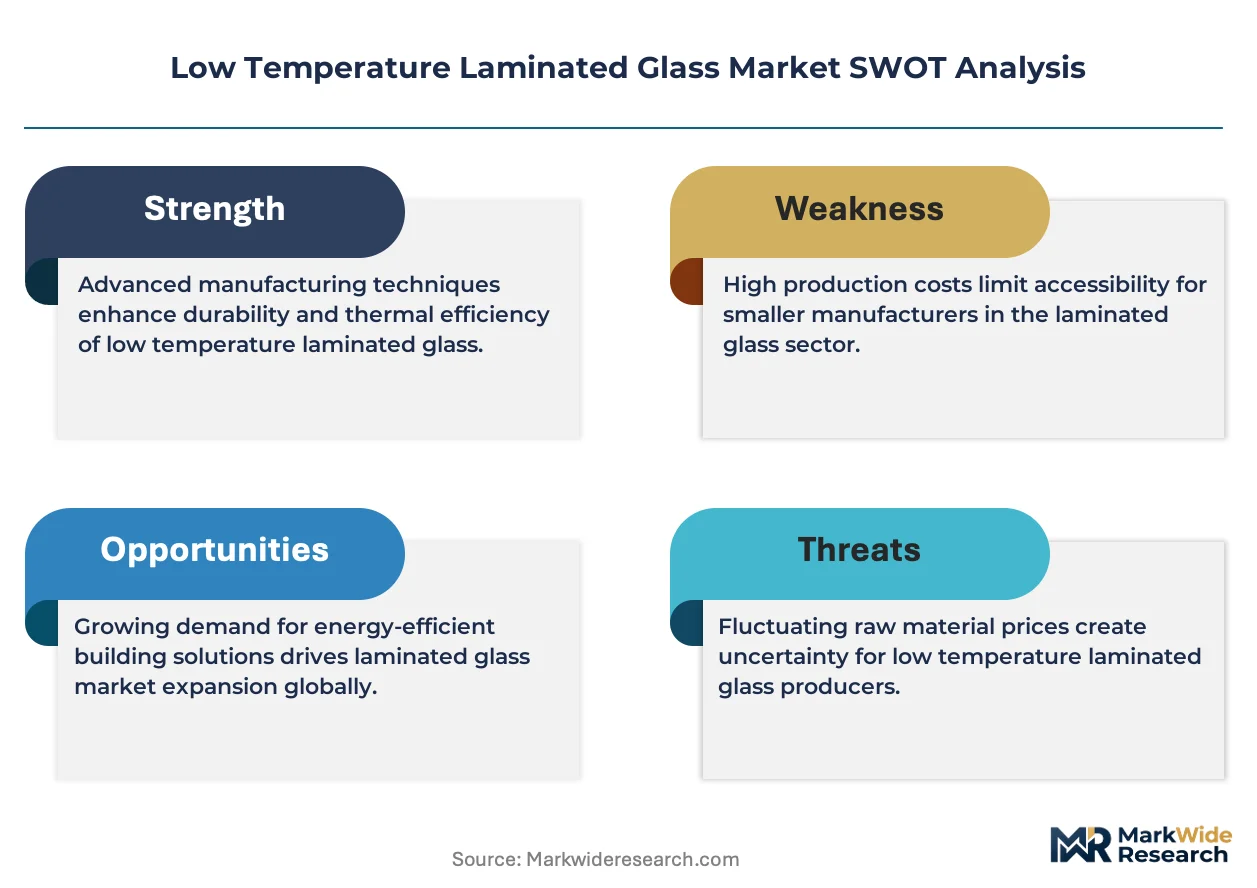
- Cold-bending compatibility:Electric vehicle architectures demand complex curvature windshields that conventional high-temperature lamination cannot achieve without optical distortion. Low-temperature ionoplast interlayers enable precise cold-forming of aerodynamic glazing profiles.
- REACH plasticizer restrictions:ECHA enforcement on phthalate content in conventional PVB films accelerates migration toward thermoplastic ionoplast formulations that cure at reduced temperatures while meeting chemical safety thresholds.
- German automotive glass cluster:Stuttgart and Munich host concentrated OEM engineering centers specifying low-temperature laminated assemblies for next-generation EV platforms, creating localized demand pull for specialized interlayer supply.
Market Restraints
- Ionomer resin supply concentration:SentryGlas Plus and comparable ionoplast feedstocks depend on limited polymerization capacity concentrated in North American and European chemical corridors, exposing laminators to input bottlenecks.
- Building code recognition lag:Structural glazing approvals under CE marking and national construction product regulations have not fully codified low-temperature cure strength equivalency, delaying architectural specification.
- Autoclave capital sunk costs:Existing high-pressure lamination infrastructure represents substantial installed base investment that owners amortize over 15-20 year cycles, retarding greenfield low-temperature line deployment.
Strategic Opportunities
- India's PLI scheme for advanced materials:Production-linked incentive frameworks for specialty chemicals and automotive components create tariff-advantaged manufacturing locations for ionoplast interlayer localization serving Asian EV programs.
- Photovoltaic-integrated facades:Building-integrated solar applications require transparent conductive oxide compatibility that low-temperature processing preserves, opening architectural volume beyond traditional safety glazing.
- CE marking harmonization:Pending Construction Products Regulation updates recognizing thermoplastic structural interlayers would unlock multi-story facade applications currently restricted to conventional PVB specifications.
Industry Challenges
- Ionomer formulation chemistry expertise:The intersection of polymer science, adhesion engineering, and optical metrology required for interlayer development exceeds available talent pools in traditional glass processing regions.
- Dual certification timelines:Automotive OEMs demand simultaneous NHTSA FMVSS 205 compliance and ECE R43 homologation, creating parallel testing burdens that extend qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Laminated Glass Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $852.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi-Layer, Composite, Structural Application: Automotive Glass, Building Facades, Interior Spaces, Furniture End User: Construction, Automotive, Furniture Manufacturing, Electronics Thickness: 3mm, 5mm, 10mm, 12mm |
| Companies Covered | CSG Holding Co., Ltd., NSG Group, Saint-Gobain, Cardinal Glass Industries, Sisecam, AGC Inc., Guardian Industries, China Glass Holdings Limited, Xinyi Glass Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Laminated Glass Market Strategic Shifts & Innovations
Active reshaping of this market centers on thermal process substitution, regulatory chemistry mandates, and procurement consolidation toward captive specification control by vehicle manufacturers.
Ionoplast interlayers are supplanting conventional plasticized PVB in premium automotive glazing applications. OEM engineering teams specify SentryGlas-equivalent formulations for panoramic roof modules and windshields requiring post-lamination cold-bending to tight radii. This substitution compresses the addressable market for legacy autoclave-dependent laminators while expanding margin pools for ionomer-capable suppliers.
REACH Annex XVII restrictions on phthalate plasticizers in polymer films entered tightened enforcement phases across EU member states. Lamination compounders reformulate interlayer stacks toward non-phthalate ionomer architectures that process at 80-90°C versus conventional 140°C cycles. German automotive glass fabricators report accelerated qualification timelines for low-temperature cure protocols to maintain CE marking compliance.
Automotive OEMs are consolidating laminated glass procurement under direct specification authority rather than tiered supplier delegation. Vehicle manufacturers now issue ionoplast interlayer technical requirements directly to laminators, compressing the role of independent glazing distributors. This concentration is most visible in Germany's Stuttgart-Munich corridor where Mercedes-Benz, BMW, and Porsche headquarters coordinate co-development programs with approved laminators.
Low Temperature Laminated Glass Market Segmentation
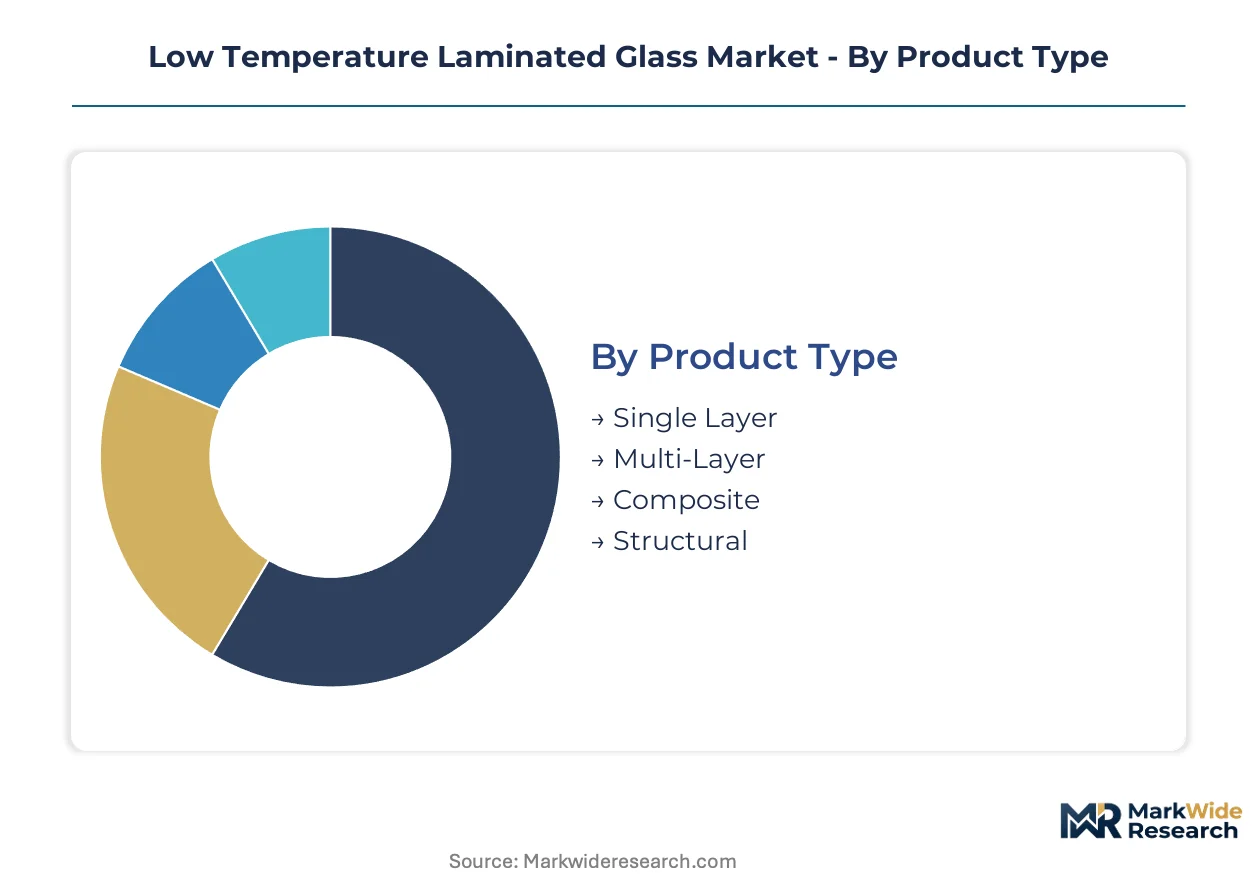
Low temperature laminated glass exhibits divergent specification requirements across automotive, architectural, and industrial end-uses. Ionoplast interlayer compatibility and cold-bending tolerance determine segment-specific procurement criteria. Manufacturers configure production lines around thickness and layer-count combinations that match dominant regional demand patterns.
Product Type:
Export-oriented laminators in Germany and Japan dominate multi-layer and structural grade supply, while single-layer and composite variants serve cost-sensitive domestic construction markets.
- Single Layer:Basic two-ply construction with standard PVB or EVA interlayer serves residential window retrofits and small-format furniture glazing. Demand concentrates in India's domestic construction sector where BIS certification requirements favor simplified lamination protocols over ionoplast complexity.
- Multi-Layer:Three-to-five ply configurations incorporating ionoplast interlayers enable post-lamination cold-bending for panoramic automotive roof modules. Stuttgart-area OEM engineering centers specify these assemblies for next-generation electric vehicle platforms requiring complex curvature without optical distortion.
- Composite:Hybrid constructions combining glass with polycarbonate or transparent conductive oxide layers serve specialized electronics and photovoltaic integration applications.
- Structural:Load-bearing interlayer formulations pending updated CE marking recognition under Construction Products Regulation amendments for multi-story facade applications.
Single Layer commands the established base. The steepest expansion runs through Multi-Layer.
Application:
Cost tier stratification separates premium automotive programs from commodity architectural volume, with thickness and interlayer chemistry driving margin differentiation.
- Automotive Glass:Windshield and panoramic roof applications demand ionoplast interlayers capable of cold-bending to tight radii after lamination. Munich-based BMW and Porsche procurement teams specify sub-90°C cure protocols to preserve optical clarity in aerodynamic glazing profiles.
- Building Facades:Curtain wall and skylight applications utilize conventional PVB at reduced temperatures where REACH plasticizer restrictions permit, serving mature replacement cycles in European commercial real estate.
- Interior Spaces:Decorative and safety partitions in hospitality and healthcare settings favor 5mm and 10mm thicknesses with standard interlayer formulations.
- Furniture:Tabletops and display cases represent price-sensitive volume with minimal technical differentiation between suppliers.
Building Facades retains the volume anchor. Automotive Glass climbs the fastest as EV platform proliferation accelerates specification upgrades.
End User:
Customer type concentration shifts procurement authority toward automotive OEMs and away from traditional construction specifier networks.
- Construction:Commercial and residential developers specify low-temperature laminated glass for fall-protection and acoustic damping where national building codes recognize thermoplastic interlayer equivalency.
- Automotive:Vehicle manufacturers now issue direct interlayer technical requirements to approved laminators, compressing tiered supplier roles. Germany's automotive glass cluster around Stuttgart and Munich hosts concentrated OEM engineering centers coordinating co-development programs.
- Furniture Manufacturing:Millwork and fixture producers source standard thicknesses through distributor channels with limited specification involvement.
- Electronics:Display and touch-panel manufacturers require ultra-thin laminates with transparent conductive oxide compatibility preserved through reduced-temperature processing.
Construction maintains the installed base. Automotive gains share fastest through procurement consolidation under direct OEM authority.
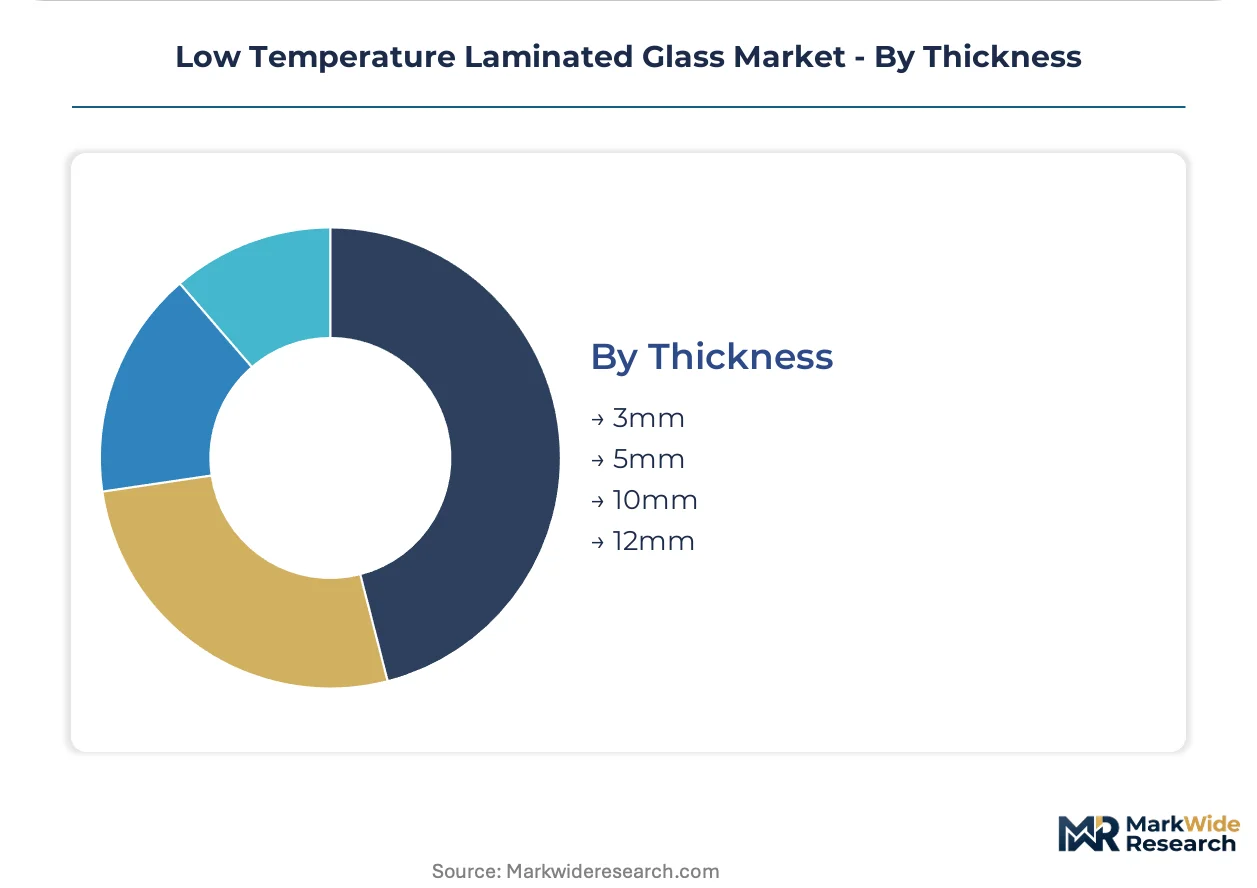
Thickness:
Volume concentration sits with mid-range specifications that balance structural performance against ionoplast interlayer cost escalation.
- 3mm:Ultra-thin laminates serve electronics and specialized automotive applications where weight minimization overrides penetration resistance requirements.
- 5mm:Standard automotive windshield and architectural glazing thickness accommodates ionoplast interlayer bonding at reduced temperatures while meeting NHTSA FMVSS 205 optical performance thresholds.
- 10mm:Heavy-duty safety and acoustic applications in commercial facades and premium furniture command margin premiums through multi-layer construction.
- 12mm:Structural and ballistic-resistant specifications pending harmonized test protocols under updated CE marking frameworks for load-bearing glazing assemblies.
5mm specifications anchor current output. 10mm grades expand most quickly as safety regulation tightening drives upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in high-value laminated glass logistics, connecting Bavarian production basins to North Sea export terminals.
Germany
Stuttgart and Munich anchor the world's densest automotive glass engineering cluster, with Mercedes-Benz, BMW, and Porsche procurement teams issuing direct ionoplast interlayer specifications to approved laminators. ECHA's REACH Annex XVII enforcement on phthalate plasticizers accelerates reformulation toward sub-90°C cure protocols. The Baden-Württemberg region hosts concentrated co-development programs between OEM engineering centers and specialized interlayer compounders.
United States
NHTSA's Federal Motor Vehicle Safety Standard 205 maintains stringent optical and penetration performance thresholds that low-temperature laminators must satisfy for windshield homologation. The Detroit-Toledo automotive corridor generates specification pull for cold-bendable glazing solutions in electric vehicle programs. Michigan-based engineering centers coordinate dual-certification testing for simultaneous FMVSS 205 and ECE R43 compliance.
China
MIIT's dual carbon goals compress energy-intensive autoclave operations, favoring reduced-temperature lamination processes in Yangtze River Delta manufacturing zones. Shanghai and Jiangsu province host expanding ionoplast interlayer compounding capacity serving domestic EV manufacturers. GB standards evolution for automotive glazing incorporates optical performance criteria compatible with low-temperature cure protocols.
Japan
METI's industrial decarbonization roadmaps incentivize thermal process substitution in glass fabrication, aligning low-temperature lamination with national emissions targets. The Nagoya-Toyota corridor concentrates automotive glazing R&D for next-generation electric platforms. Aichi prefecture fabricators report accelerated qualification timelines for ionoplast assemblies in premium vehicle programs.
India
The PLI scheme for advanced materials and automotive components creates tariff-advantaged manufacturing locations for ionoplast interlayer localization. Maharashtra and Gujarat host emerging laminator capacity targeting export markets and domestic EV supply chains. BIS certification requirements for construction glazing favor simplified lamination protocols, constraining ionoplast penetration in architectural segments.
Low Temperature Laminated Glass Market Key Industry Players
Concentration sits with integrated glass manufacturers possessing captive float glass capacity and interlayer formulation expertise. Three distinct archetypes populate the competitive landscape: diversified building materials conglomerates with automotive glass divisions, specialized automotive glazing fabricators with OEM-direct relationships, and regional laminators serving cost-sensitive construction markets. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with players securing ionomer resin supply agreements and co-development contracts with vehicle manufacturers.
Among diversified materials conglomerates, Saint-Gobain and AGC Inc. exemplify the integrated archetype combining float glass production with interlayer formulation capabilities. Guardian Industries occupies a position within the North American fabricator tier. CSG Holding Co., Ltd. and Xinyi Glass Holdings Limited represent Chinese-scale players with expanding laminated glass portfolios.
| Leading Market Players |
|---|
| CSG Holding Co., Ltd. |
| NSG Group |
| Saint-Gobain |
| Cardinal Glass Industries |
| Sisecam |
| AGC Inc. |
| Guardian Industries |
| China Glass Holdings Limited |
| Xinyi Glass Holdings Limited |
| Others |
Cost & Logistics Intelligence
NHTSA's Federal Motor Vehicle Safety Standard 205 gates both supplier qualification and price differentiation simultaneously, as laminators must satisfy optical and penetration performance thresholds before accessing premium automotive procurement tiers. CE marking under Europe's Construction Products Regulation creates parallel certification barriers that stratify pricing power between ionoplast-capable suppliers and legacy PVB-dependent fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ionoplast automotive assemblies from conventional PVB architectural glazing and basic residential retrofits. Price differentiation rests on certification grade and volume scale, with OEM-direct contracts commanding premiums over distributor-channel sales. Cost compression in standard-tier architectural segments is intensifying because REACH-compliant interlayer reformulation raises input costs without commensurate specification upgrades. Furniture manufacturers and small-scale construction developers exhibit the highest price sensitivity, while Stuttgart-Munich corridor OEMs prioritize optical performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of ionomer resin feedstocks dominates inventory strategy, as SentryGlas-equivalent polymerization capacity concentrates in North American and European chemical corridors with limited alternative sourcing. Supply draws from Germany, Japan, and China for finished laminated assemblies, with ionoplast interlayer compounding anchored in the United States and Belgium. Single-source vulnerability in ionomer resin supply exposes laminators to input bottlenecks when polymerization capacity tightens. Distribution runs through OEM-direct specification channels for automotive glass and regional distributor networks for architectural volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as automotive OEMs consolidate procurement authority under direct specification control, replacing tiered supplier delegation with captive interlayer technical requirements. This interoperability shift toward OEM-direct ecosystems compresses independent glazing distributor roles while expanding margin pools for approved laminators.
For Market Incumbents: Fortify ionoplast formulation capabilities through backward integration into ionomer resin supply or long-term offtake agreements with polymerization specialists. Defend position by accelerating qualification timelines for sub-90°C cure protocols ahead of REACH Annex XVII enforcement tightening. Capacity addition in Germany's automotive glass cluster preserves proximity to Stuttgart-Munich OEM engineering centers.
For New Entrants and Emerging Players: Lead with photovoltaic-integrated facade applications where transparent conductive oxide compatibility requirements favor low-temperature processing expertise over incumbent scale advantages. India's PLI scheme for advanced materials offers the most penetrable geography for tariff-advantaged ionoplast interlayer localization. A go-to-market angle anchored in building-integrated solar partnerships bypasses saturated automotive certification barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across low-temperature lamination equipment as vacuum-bag and nip-roll technologies displace autoclave-dependent infrastructure. Long-term viability favors laminators with demonstrated dual-certification capabilities spanning NHTSA FMVSS 205 and ECE R43 homologation. Acquisition targets should demonstrate captive OEM-direct relationships rather than distributor-channel dependence. The signal to watch is CE marking recognition of thermoplastic structural interlayers under pending Construction Products Regulation amendments.
| Strategic Initiative | Industry Significance |
|---|---|
| Ionomer Resin Supply Agreement | Secures feedstock access from DuPont or equivalent polymerization specialists for ionoplast interlayer production. |
| Dual-Certification Testing Investment | Accelerates NHTSA FMVSS 205 and ECE R43 homologation timelines for Stuttgart-Munich OEM programs. |
| Photovoltaic Integration Partnership | Opens architectural volume beyond safety glazing through transparent conductive oxide compatibility. |
| India PLI Scheme Localization | Creates tariff-advantaged manufacturing for ionoplast interlayer supply to Asian EV programs. |
| CE Marking Harmonization Advocacy | Unlocks multi-story facade applications pending Construction Products Regulation structural interlayer recognition. |
Research Approach
A standing panel of automotive glazing procurement managers, ionoplast interlayer compounders, architectural specifier consultants, and ECHA regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with OEM platform engineers and laminator operations directors combined with secondary validation from NHTSA FMVSS 205 filings, ECHA REACH Annex XVII updates, and customs trade data for laminated glass imports. Bottom-up demand modeling triangulated against top-down industry capacity assessments.
Consistency checks validated volume and value outputs against external benchmarks including vehicle production databases and construction product registration statistics. Segmentation dimensions spanned product type, application, end user, thickness, and regional production cluster across the projection horizon. CAGRs derived from fitted growth curves incorporating EV platform proliferation rates and building code amendment timelines. Forecast inputs included ionomer resin capacity expansion announcements and OEM co-development program disclosures.
Forecasts assume regulatory continuity in NHTSA FMVSS 205, ECHA REACH enforcement, and CE marking frameworks; material policy shifts would require re-modeling. Specific risks include accelerated F-Gas Regulation phase-outs compressing autoclave viability faster than low-temperature line deployment, and ionomer resin supply disruptions from polymerization facility outages. Revision becomes warranted when CE marking recognition of thermoplastic structural interlayers crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Foam Glass Market
Glass
Decorative Glass Market
Glass
Fiberglass Window Market
Glass
Optical Lens Material Market
Glass
Global Flat Glass Market
Glass
Laboratory Glass Container Market
Glass
Global Anti-Reflective Glass Market
Glass
Spherical Silica Market
Glass
North America Flat Glass Market
Glass
China Flat Glass Market
Glass
Glass Recycling Market
Glass
Heat Resistant Glass Market
Glass
Glass Product Market
Glass
Solar PV Glass Market
Glass
India Flat Glass Market
Glass
Float Glass Market