
 Fiberglass Window Market | 2026-2036
Fiberglass Window Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Window Market Analysis
Pultruded fiberglass is decoupling from premium-niche positioning as manufacturing scale reduces unit costs. Owens Corning leverages its glass-fiber supply chain to control raw-material quality from resin formulation through finished profile. Andersen Corporation anchors its market presence through a dealer-network model that limits price transparency. Milgard Windows & Doors specializes in Western US production with regional fabrication plants that compress lead times for custom sizing.
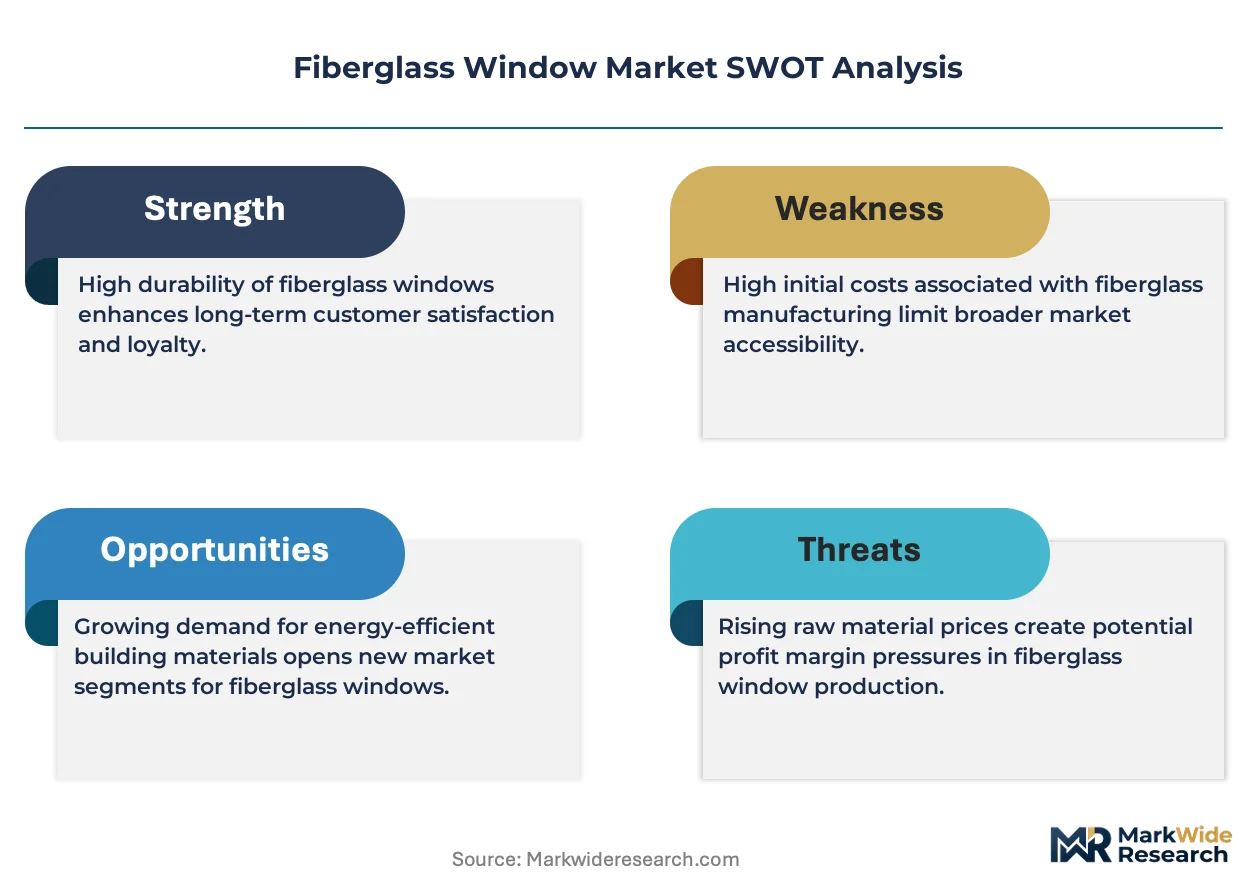
Fiberglass windows consist of thermoset polymer matrices reinforced with continuous glass-fiber strands, extruded through heated dies in a pultrusion process yielding tensile strengths exceeding 30,000 psi and thermal conductivity below 0.35 W/m·K, serving primarily as high-durability fenestration for structures facing thermal cycling or chemical exposure. The residential end-user segment leads volume as homeowners replace failed vinyl units in humid climates, while the replacement installation type captures margin pools from retrofit demand in aging housing stock. Casement product types grow fastest among operable formats due to superior sealing performance against stringent air-infiltration codes.
The EPA Energy Star program and the International Energy Conservation Code shape product specifications by mandating U-factor and solar heat gain coefficient thresholds that fiberglass frames satisfy more readily than thermally unbroken aluminum. The NFRC certification process adds testing-cost barriers that favor established manufacturers with in-house laboratories over import entrants. Stakeholders must monitor evolving IECC adoption cycles across municipal jurisdictions to anticipate specification shifts before code compliance deadlines compress bidding windows.
Market Dynamics
Pultrusion manufacturing scale is compressing unit economics and eroding the premium-price barrier that historically confined fiberglass to coastal luxury construction. Owens Corning's captive glass-fiber supply and Andersen's dealer-network control exemplify how raw-material security and channel capture now determine competitive viability more than product differentiation alone.
Growth Catalysts
- EPA Energy Star 7.0 thermal thresholds:Tighter U-factor mandates in Florida, Texas, and California accelerate vinyl-to-fiberglass replacement cycles as builders seek frames that exceed code without thermal breaks.
- Salt-air degradation in Gulf Coast housing stock:Coastal homeowners facing accelerated aluminum corrosion are specifying pultruded fiberglass for 30-year service life in humid, chemically aggressive environments.
- Casement operable formats:Superior compression-sealing performance against IECC air-infiltration codes positions casement windows as the fastest-growing product type in code-compliant new construction.
Market Restraints
- Resin and glass-fiber input cost volatility:Thermoset polymer matrices and continuous E-glass strands expose manufacturers to petrochemical and energy price swings that compress margin predictability.
- Fabrication plant geographic concentration:Western US production clustering around Milgard's regional plants creates lead-time vulnerability for Eastern and Midwestern contractors requiring custom sizing.
- Thermally broken aluminum substitution:Improved aluminum frame technology with polyamide thermal breaks offers competitive durability at lower installed cost in non-coastal climates.
Strategic Opportunities
- Midwestern retrofit underpenetration:Aging vinyl window failures in humid continental climates present replacement volume pools that coastal-focused manufacturers have not systematically targeted.
- NFRC certification in-house laboratory investment:Testing-cost barriers favor established manufacturers who can internalize certification workflows and compress bidding windows against import entrants.
- Smart glass convergence with low-conductivity frames:Integration of electrochromic glazing with fiberglass substrates creates premium system offerings for net-zero building specifications.
Industry Challenges
- Pultrusion die engineering talent scarcity:Specialized thermoset process engineering expertise concentrates among aging workforce cohorts, constraining capacity expansion timelines.
- IECC adoption cycle monitoring burden:Municipal jurisdiction-level code compliance deadlines compress specification windows and demand continuous regulatory intelligence investment.
- Custom sizing fabrication complexity:Regional plant networks must balance SKU proliferation against batch efficiency, creating working capital intensity for made-to-order operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Window Market |
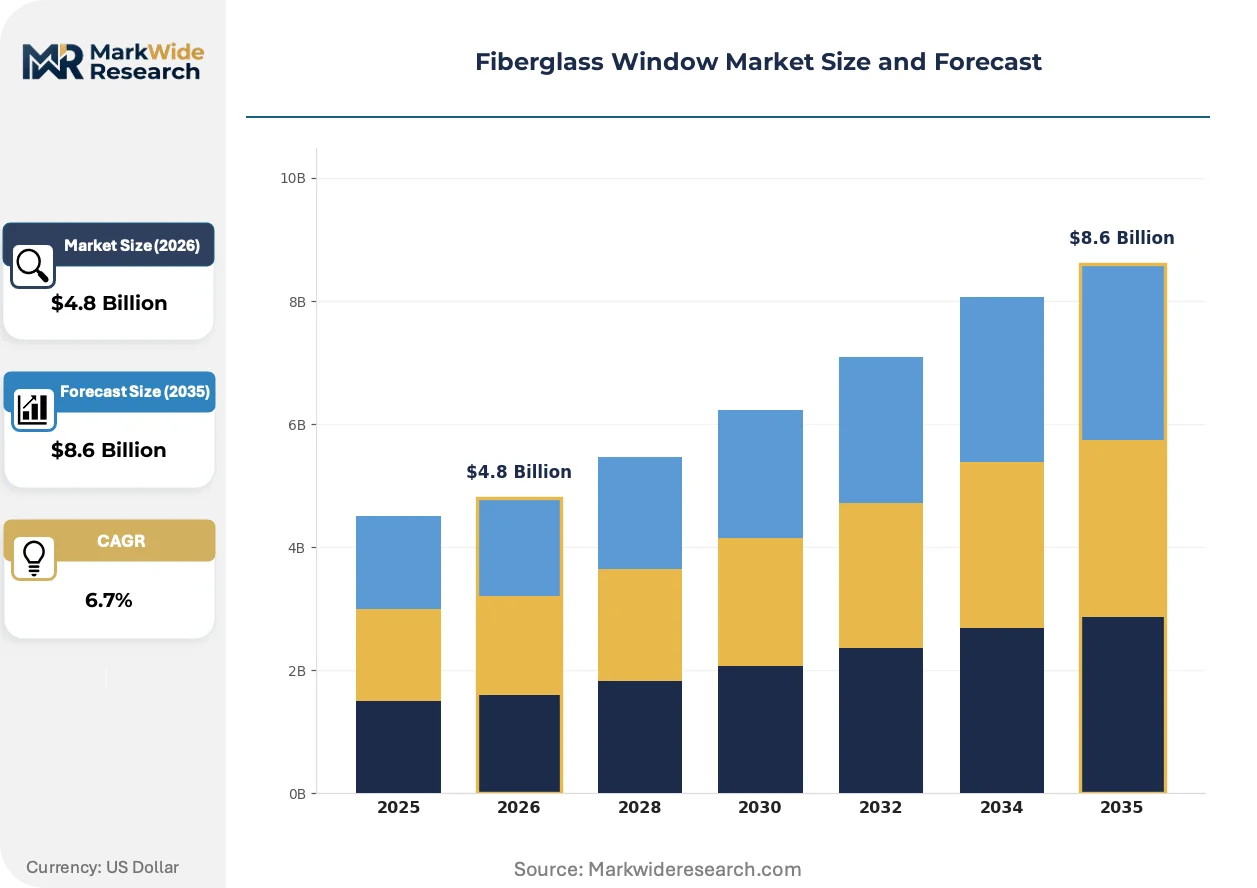
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Hung, Double-Hung, Casement, Sliding End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Replacement, Remodel, Retrofit Frame Design: Vinyl Clad, Wood Laminated, Aluminum Reinforced, Others |
| Companies Covered | Milgard Windows & Doors, Owens Corning, Andersen Corporation, Vetrotech Saint-Gobain, Guardian Industries, Marvin, JELD-WEN, Alpen High Performance Products, Pella Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Window Market Emerging Trajectories
Automation of pultrusion lines is compressing labor content and enabling dimensional precision that manual processes cannot replicate. Regulatory tightening on thermal performance is forcing frame redesign cycles. Procurement behavior is shifting toward specification-grade certification as a non-negotiable qualifier.
Robotic pull-and-cut systems are automating the post-pultrusion processing of fiberglass profiles to millimeter tolerances for multi-point locking hardware integration. Large regional fabricators in Florida and California are adopting these lines fastest to serve custom commercial glazing contracts. The technology is automating quality consistency that previously required skilled manual inspection, reducing defect rates and warranty exposure.
The International Energy Conservation Code's 2024 cycle is mandating U-factor thresholds below 0.30 in climate zones 4 through 8, forcing frame manufacturers to redesign profiles or risk specification exclusion. Fiberglass's intrinsic thermal conductivity below 0.35 W/m·K positions it advantageously against thermally unbroken aluminum. Multi-family developers in IECC-adopting municipalities are responding by elevating fiberglass to standard specification rather than upgrade option.
Architects and contractors are bundling window procurement with whole-building energy modeling services, unbundling the traditional distributor role. Engineering firms in Texas and California are displacing dealer networks by specifying direct-to-fabricator relationships that compress markups and align liability. This reconfiguration is most visible in commercial retrofit projects where performance guarantees override brand preference.
Fiberglass Window Market Segmentation
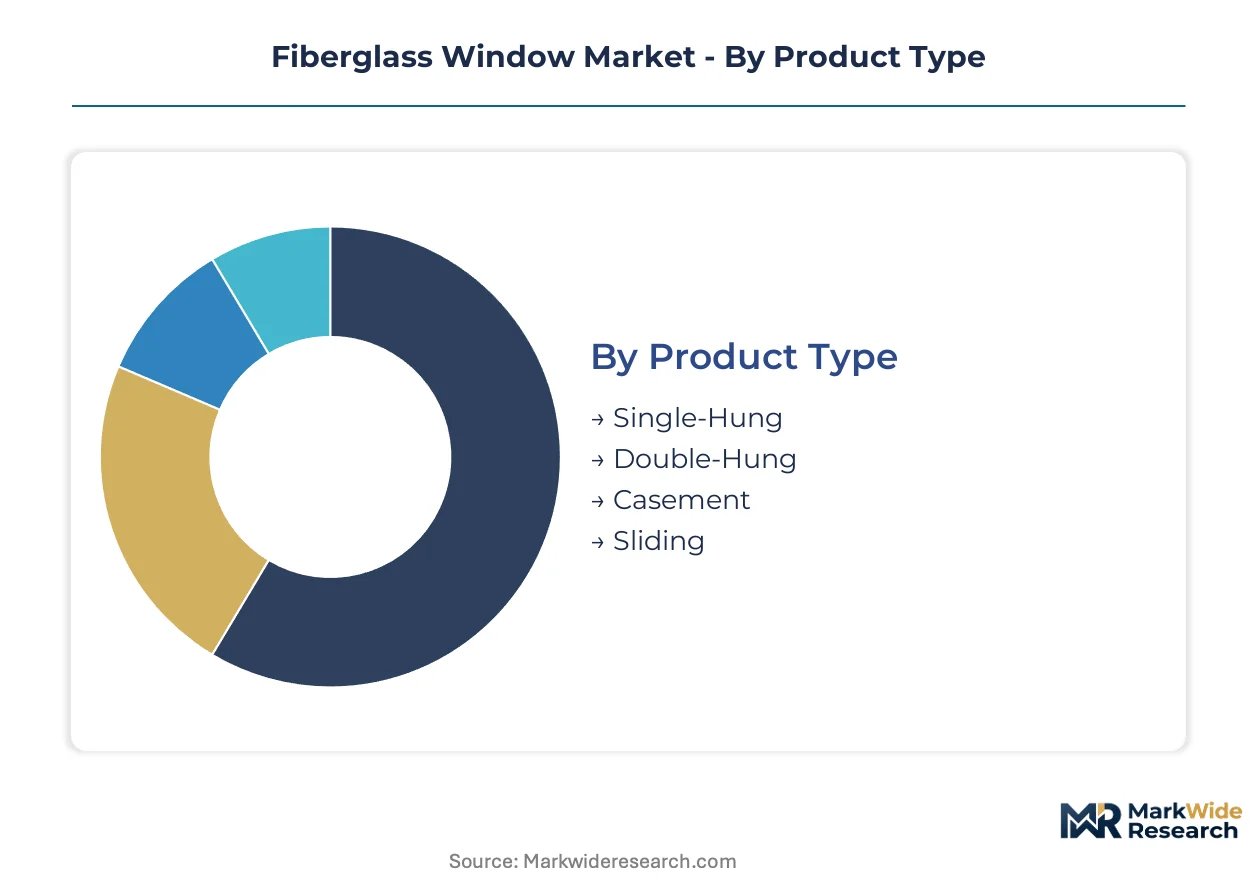
Fiberglass window specifications diverge sharply across building codes and climate zones, with each segment carrying distinct certification burdens from the EPA Energy Star program and the NFRC rating protocol. Understanding these segmentation boundaries allows manufacturers to align pultrusion capacity with the precise thermal performance and structural load requirements of each application category.
Product Type:
EPA Energy Star 7.0 thermal thresholds and IECC air-infiltration codes impose divergent testing burdens across operable formats, with compression-sealing designs facing stricter validation protocols than sliding mechanisms.
- Single-Hung:Fixed upper sash with vertically sliding lower panel, constructed through pultrusion of continuous glass-fiber strands in thermoset polymer matrices. Demand concentrates in Southern US residential retrofits where cost-conscious homeowners prioritize replacement of failed vinyl units without complex hardware.
- Double-Hung:Dual operable sashes enabling ventilation from top or bottom, requiring reinforced pultruded profiles to manage structural loads from dual moving panels. Coastal Florida and Texas builders specify these for multi-story residential construction where egress requirements intersect with salt-air durability mandates.
- Casement:Hinged sash projecting outward with multi-point locking compression seals, delivering superior air-infiltration performance against stringent IECC codes. Fastest-growing format among operable types.
- Sliding:Horizontal track-mounted panels optimized for wide rough openings in commercial glazing, with thermal breaks less critical than in compression-seal designs.
Single-Hung sits at the top of the volume ranking, with Casement climbing the fastest.
End User:
Cost tier stratification separates specification-grade commercial projects from mass-market residential procurement, with institutional buyers occupying a middle band defined by public-bid compliance rather than performance optimization.
- Residential:Single-family and multi-family homeowners replacing failed vinyl windows in humid continental and coastal climates, where pultruded fiberglass offers 30-year service life against thermal cycling and moisture ingress. Volume leader driven by aging housing stock in Florida, Texas, and California.
- Commercial:Office, retail, and hospitality developers pursuing net-zero building certifications through high-performance fenestration systems. Projects in California and New York integrate electrochromic glazing with low-conductivity fiberglass substrates to satisfy Title 24 and Local Law 97 carbon mandates.
- Industrial:Manufacturing facilities and warehouses requiring chemical-resistant fenestration for aggressive process environments.
- Institutional:Schools, hospitals, and government buildings procuring through public bidding processes that prioritize NFRC certification and warranty terms over thermal performance margins.
Residential dominates absolute volume, with Commercial expanding most quickly on net-zero building specifications.
Installation Type:
Application timing determines margin structure, with replacement and retrofit capturing premium pricing from custom sizing while new construction competes on standard-dimension volume efficiency.
- New Construction:Standard-dimension windows installed during primary building envelope assembly, competing on unit cost and lead-time reliability. Multi-family developers in IECC-adopting municipalities are elevating fiberglass to standard specification.
- Replacement:Retrofit installation into existing rough openings, capturing margin pools from custom sizing and expedited fabrication. Fastest-expanding category as coastal homeowners accelerate vinyl-to-fiberglass upgrade cycles.
- Remodel:Partial envelope renovation projects combining window replacement with siding or insulation upgrades.
- Retrofit:Deep energy retrofits targeting whole-building performance improvements, often bundled with energy modeling services that displace traditional dealer networks.
Replacement commands the highest margin tier, with Retrofit gaining share fastest through performance-guarantee procurement models.
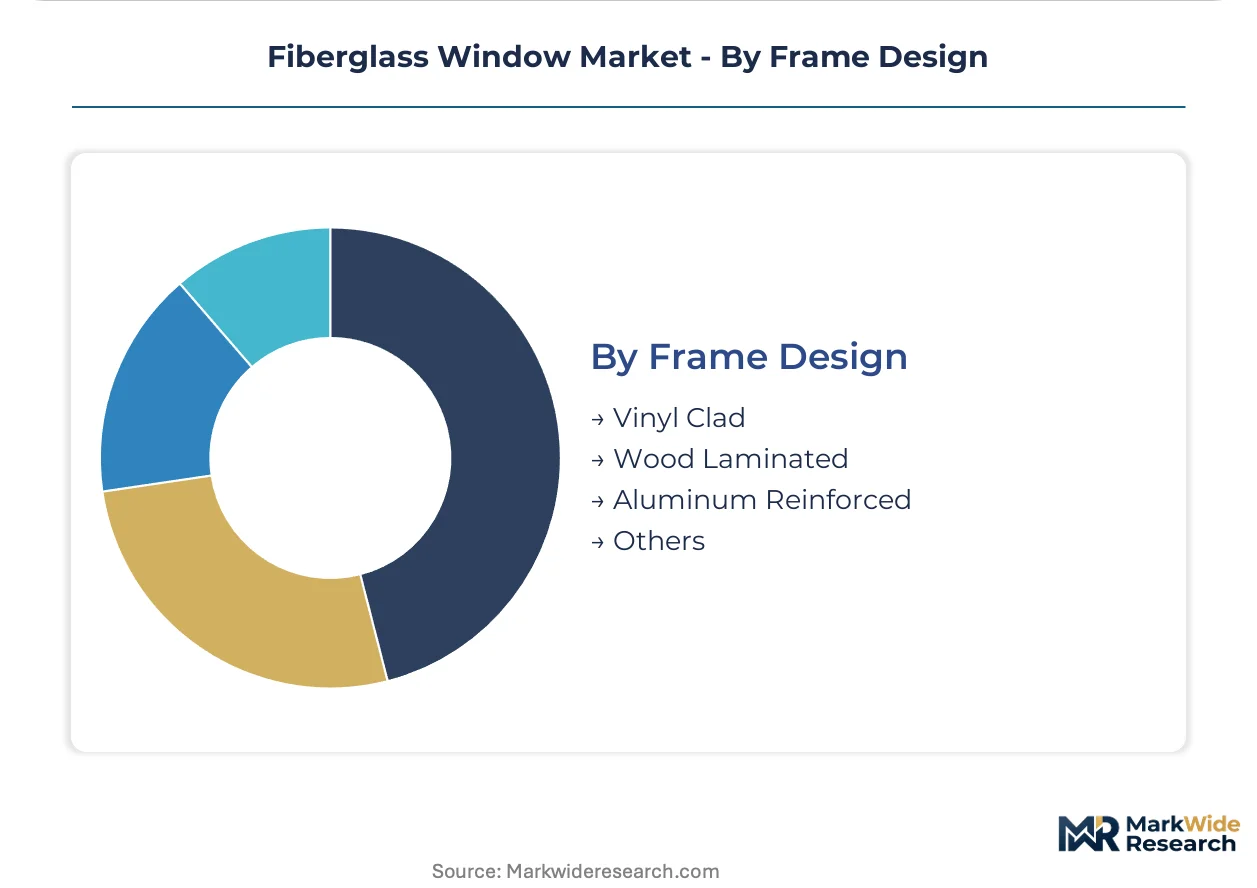
Frame Design:
Supply concentration in glass-fiber and resin formulation creates tiered material strategies, with captive supply chains favoring integrated manufacturers over assembly-only fabricators.
- Vinyl Clad:Pultruded fiberglass core with exterior vinyl weathering surface, balancing thermal performance against cost constraints in mid-market residential applications. Owens Corning leverages captive glass-fiber supply to control quality from resin formulation through finished profile.
- Wood Laminated:Interior wood veneer bonded to pultruded fiberglass structural core, serving premium residential segments where aesthetic warmth intersects with durability requirements. Western US production clusters around regional fabrication plants serving custom sizing demand.
- Aluminum Reinforced:Pultruded profiles with aluminum structural inserts for commercial applications requiring enhanced wind-load resistance.
- Others:Hybrid configurations including bare fiberglass and specialty coatings for chemical-process environments.
Vinyl Clad leads volume rankings, with Wood Laminated ascending fastest on premium coastal construction demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Florida Gulf Coast anchors fiberglass window demand through salt-air degradation cycles that accelerate vinyl and aluminum replacement. Coastal municipalities from Tampa to Naples specify pultruded profiles for 30-year service life in humid, chemically aggressive environments. This regional concentration shapes national manufacturing footprints and distribution logistics.
United States
Florida, Texas, and California drive replacement volume as coastal homeowners abandon corroded aluminum frames. The EPA Energy Star 7.0 program tightens thermal performance thresholds that fiberglass satisfies without thermal breaks. Regional fabrication plants in California compress lead times for Western US custom sizing demand.
Canada
Provincial energy codes in British Columbia and Ontario mandate U-factors below 0.30, favoring low-conductivity frame materials. Natural Resources Canada's ENERGY STAR initiative aligns with US thermal thresholds. Vancouver and Toronto metropolitan areas concentrate specification-grade procurement for multi-family net-zero construction.
Germany
The EU Green Deal and national Building Energy Act (GEG) drive fenestration upgrades in aging housing stock. REACH regulations constrain resin formulation chemistry for pultruded profiles. Industrial clusters in North Rhine-Westphalia host compounders supplying thermoset matrices to window fabricators.
China
Dual carbon goals and GB standards for building energy efficiency expand high-performance fenestration demand. The Ministry of Ecology and Environment tightens industrial emissions controls on pultrusion operations. Yangtze River Delta manufacturing bases scale automated profile production for domestic and export markets.
Australia
Coastal corrosion in Queensland and New South Wales accelerates aluminum-to-fiberglass substitution cycles. The Nationwide House Energy Rating Scheme (NatHERS) elevates thermal performance specifications. Sydney and Melbourne architectural practices specify pultruded frames for waterfront residential developments.
Fiberglass Window Market Vendor Landscape
Global majors compete with regional champions across raw-material security and distribution control dimensions. The market exhibits tiered concentration with integrated glass-fiber producers, specialized window fabricators, and building-material conglomerates occupying distinct strategic positions. Three archetypes dominate: captive supply-chain operators, dealer-network controllers, and regional custom-fabrication specialists. Competitive moves center on backward integration into resin formulation and geographic expansion of fabrication plant networks.
Among integrated material suppliers, Owens Corning exemplifies the captive supply-chain archetype through glass-fiber production control. Andersen Corporation occupies the dealer-network control position. Milgard Windows & Doors represents regional fabrication specialization with Western US plant concentration. These three anchors illustrate how raw-material security, channel capture, and geographic proximity to demand clusters now determine competitive viability.
| Leading Market Players |
|---|
| Milgard Windows & Doors |
| Owens Corning |
| Andersen Corporation |
| Vetrotech Saint-Gobain |
| Guardian Industries |
| Marvin |
| JELD-WEN |
| Alpen High Performance Products |
| Pella Corporation |
| Others |
Supply Flow & Price Mechanics
Resin and E-glass strand costs cascade through pultrusion economics to stratify fiberglass window pricing across three performance tiers, with petrochemical volatility compressing margins at the standard-grade level while premium specifications retain pricing power through NFRC certification bundling.
Pricing Analysis
Input-cost pass-through from thermoset polymer matrices and continuous glass-fiber strands operates on a contract-plus-spot hybrid model, with quarterly resin price adjustments flowing to OEM fabricators within 60 days. Price differentiation hinges on NFRC certification tier and customization depth, with certified-lab manufacturers commanding 15-20% premiums over import-assembled alternatives. Pricing pressure intensifies in the standard residential tier as thermally broken aluminum narrows the installed-cost gap in non-coastal markets. Commercial developers exhibit lowest price sensitivity due to net-zero compliance mandates, while mass-market replacement homeowners in Florida and Texas drive volume through cost-conscious procurement.
Supply Chain Analysis
Domestic-content thresholds in California's Title 24 and New York's Local Law 97 compliance pathways are reshaping sourcing patterns toward North American resin compounders and glass-fiber producers. Supply concentrates in the United States, China, and Germany, with Owens Corning's captive glass-fiber production anchoring US cost positions against Yangtze River Delta manufacturing bases. Raw material dependencies center on epoxy and polyester thermoset formulations, continuous E-glass rovings, and pultrusion die tooling. Single-source vulnerability concentrates in specialized die engineering talent pools constraining capacity expansion. Distribution runs through dealer-network hierarchies in residential segments and direct-to-fabricator relationships in commercial retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pultrusion automation and coastal specification upgrading are expanding margin pools for manufacturers who capture scale economies before thermally broken aluminum closes the durability-cost gap.
For Market Incumbents: Hedge against resin price volatility through backward integration into resin formulation or long-term offtake agreements with North American compounders. Defend dealer-network control in Florida and Texas against engineering firms bundling procurement with energy modeling services by embedding performance guarantees into standard warranty terms. For New Entrants and Emerging Players: Capture underpenetrated Midwestern retrofit volume in humid continental climate zones where aging vinyl failures outpace coastal-focused manufacturer coverage. Enter through NFRC certification investment that compresses bidding windows against import competitors, targeting custom sizing demand from regional contractors excluded from Western US plant networks. For Investors and Strategic Acquirers: Consolidation pressure builds where regional fabrication specialists lack captive glass-fiber supply and face working capital intensity from made-to-order operations. Long-term viability favors integrated manufacturers with in-house pultrusion capacity and certification infrastructure. Watch IECC adoption acceleration in climate zones 4 through 8 as the signal for specification-grade demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Owens Corning's glass-fiber supply chain control demonstrates margin protection against petrochemical volatility. |
| NFRC In-House Laboratory Investment | Testing-cost barriers favor established manufacturers with certification workflows against import entrants. |
| Regional Fabrication Plant Expansion | Milgard's Western US concentration creates lead-time vulnerability that Eastern plant networks can exploit. |
| Smart Glass System Integration | Electrochromic glazing convergence with fiberglass substrates opens premium net-zero building specifications. |
| Dealer-Network Channel Control | Andersen's distribution hierarchy limits price transparency and protects margin pools in residential replacement. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined through structured interviews with pultrusion plant managers, window fabricator procurement leads, commercial glazing contractors, and municipal code officials. Secondary validation draws from EPA Energy Star certification databases, IECC adoption tracking, NFRC rating protocols, and customs trade data for glass-fiber and resin imports. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, end user, installation timing, and frame design, with climate-zone regulatory adoption patterns as a cross-cutting variable. CAGRs derive from regression analysis against housing stock age, coastal corrosion indices, and code compliance deadlines. Industry-specific inputs incorporate pultrusion line automation rates and die engineering workforce demographics.
Resin price volatility, municipal code adoption timing, and aluminum substitution technology advancement are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Shatterproof Glass Market
Glass
Tinted Glass Market
Glass
Latin America Flat Glass Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Paper Glass Maker Market
Glass
Global Vacuum Insulated Glass Market
Glass
Double Glazing Glass Market
Glass
Recycled Glass Aggregates Market
Glass
Asia-Pacific Glassware Market
Glass
Glass Mat Market
Glass
Flexible Glass Market
Glass
Metallic Glass Market
Glass
North America and Australia Silica Market
Glass
Middle-East and Africa Flat Glass Market
Glass
3D Glass Market
Glass
China Flat Glass Market