
 Optical Lens Material Market | 2026-2036
Optical Lens Material Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Lens Material Market Analysis
Market Context
Specialty distributor networks for ophthalmic and industrial optics is tilting toward direct material partnerships with polymer compounders. Carl Zeiss AG leverages its captive grinding and polishing infrastructure to control premium glass and resin supply chains. Sunny Optical Technology anchors high-volume smartphone lens assembly through backward integration into molding operations. EssilorLuxottica dominates retail channel access, sustaining margin capture across prescription and sunglass segments.
Technical Definition and Segment Structure
Optical lens material encompasses transparent substrates engineered to precise refractive indices, Abbe numbers, and density specifications for light manipulation in vision correction, imaging, and protection applications. Polycarbonate leads volume in safety and sports applications due to impact resistance and low specific gravity, while CR-39 sustains cost-sensitive prescription markets through cast molding economics. Anti-reflective coating commands premium positioning across prescription lenses and industrial optics where transmittance thresholds determine performance. Blue light filtering segments expand fastest in e-commerce channels targeting prolonged screen exposure among knowledge workers.
Regulatory Framework and Outlook
FDA 21 CFR Part 801 governs impact resistance and labeling for prescription and non-prescription lenses in the United States, while ECHA REACH restricts phthalate plasticizers and unreacted monomers in EU-sold optical polymers. China's NMPA and GB standards enforce biocompatibility testing for contact-adjacent lens materials, tightening market access for uncertified imports. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as fluorinated coatings face phasedown pressure that could force reformulation of premium hydrophobic lens treatments.
Market Dynamics
Smartphone camera module suppliers are consolidating procurement around high-index resin specifications, compressing supplier tiers and forcing compounders to certify refractive precision at wafer-scale volumes. This demand concentration is restructuring molding capacity allocation across East Asian manufacturing clusters.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating reformulation of hydrophobic lens coatings toward silicone-based alternatives, opening substitution markets for specialty chemical suppliers.
- Blue light filtering:Knowledge workers purchasing prescription lenses through e-commerce channels are demanding integrated photoprotection, expanding value capture in ophthalmic resin formulations.
- Shenzhen-Dongguan cluster:Dense concentration of precision molding and coating facilities serving export markets is attracting captive resin compounding investments from global smartphone brands.
Market Restraints
- Monomer supply concentration:Thiourethane and episulfide precursors for high-index lenses depend on Japanese and Korean chemical suppliers, creating vulnerability to shipping disruptions.
- ECHA REACH disclosure:Tightening chemical registration requirements for unreacted monomers and phthalate plasticizers is extending compliance timelines for EU market entry.
- Glass substitution:Advanced polycarbonate formulations with Abbe number improvements above 35 are displacing crown glass in mid-tier imaging applications.
Strategic Opportunities
- India ophthalmic retail:Organized optical chains in Mumbai and Delhi are consolidating supplier relationships, creating entry points for certified resin compounders.
- AR/VR waveguide integration:Convergence of precision injection molding with lithographic patterning is enabling resin-based diffractive optics for near-eye displays.
- China NMPA biocompatibility:Accelerated certification pathways for silicone hydrogel contact-adjacent materials are shortening time-to-market for compliant imports.
Industry Challenges
- Metrology talent scarcity:Interferometric testing and refractive index mapping at sub-nanometer precision requires specialized technicians concentrated in German and Japanese optics hubs.
- Coating line capex:Vacuum deposition systems for anti-reflective multi-layer stacks require capital commitments exceeding mid-tier compounder balance sheet capacity.
- ISO 8980-1 harmonization:Divergent national implementations of spectacle lens power tolerance standards are forcing redundant testing protocols for multi-market certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Lens Material Market |
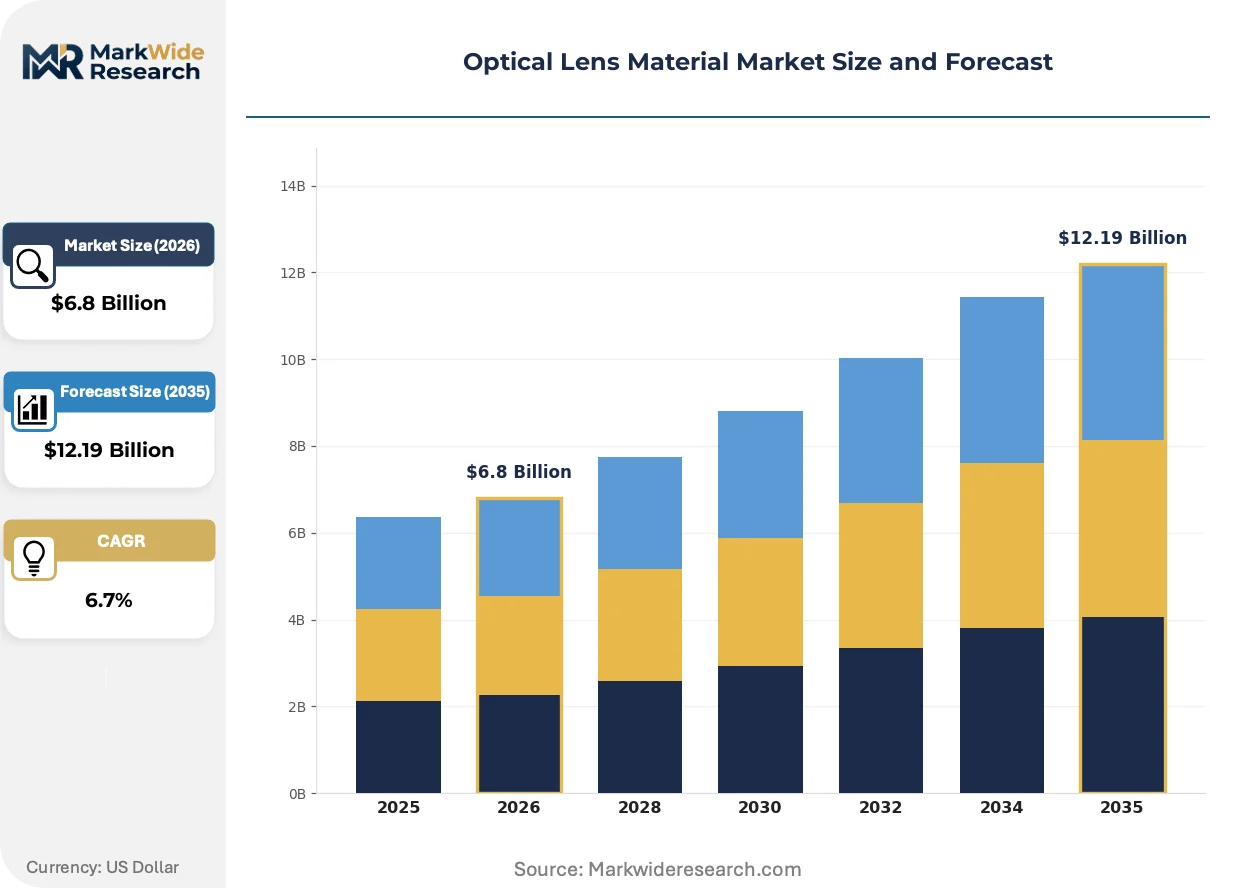
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polycarbonate, Trivex, CR-39, Glass Coating Type: Anti-Reflective, Scratch-Resistant, UV Protection, Blue Light Filtering End User: Optical Stores, Healthcare Facilities, E-Commerce Platforms, Sports Retailers Application: Prescription Lenses, Sunglasses, Industrial Lenses, Safety Glasses |
| Companies Covered | FUJIFILM Corporation, Sony Electronics Inc., Tamron Co., Ltd., Carl Zeiss AG, Largan Precision Co., Ltd., Sunny Optical Technology (Group) Company Limited, Nikon Corporation, EssilorLuxottica SA, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Lens Material Market Emerging Trajectories
Computational design tools and additive manufacturing are compressing prototyping cycles for aspheric and freeform lens geometries, enabling mass customization at previously unattainable volume economics.
Freeform lens surfacing technology is virtualizing traditional grinding and polishing workflows by replacing mechanical material removal with precision polymer deposition and UV-cured layer stacking. Smartphone camera module suppliers are adopting these processes for folded-optics periscope lenses. This is virtualizing the capital intensity of legacy glassworking infrastructure.
ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of oleophobic and hydrophobic lens coatings across EU-sold products. Fluorinated surface treatments face phasedown pressure, compelling coating houses to validate silicone and hydrocarbon alternatives. Premium sunglass and industrial optics segments are absorbing extended qualification timelines.
Direct material partnerships between smartphone OEMs and resin compounders are disintermediating traditional distributor networks. Procurement teams at major camera module suppliers are establishing long-term supply agreements with polymer formulators capable of refractive index customization. This pattern concentrates most visibly in China, where backward integration into molding operations anchors volume commitments.
Optical Lens Material Market Segmentation
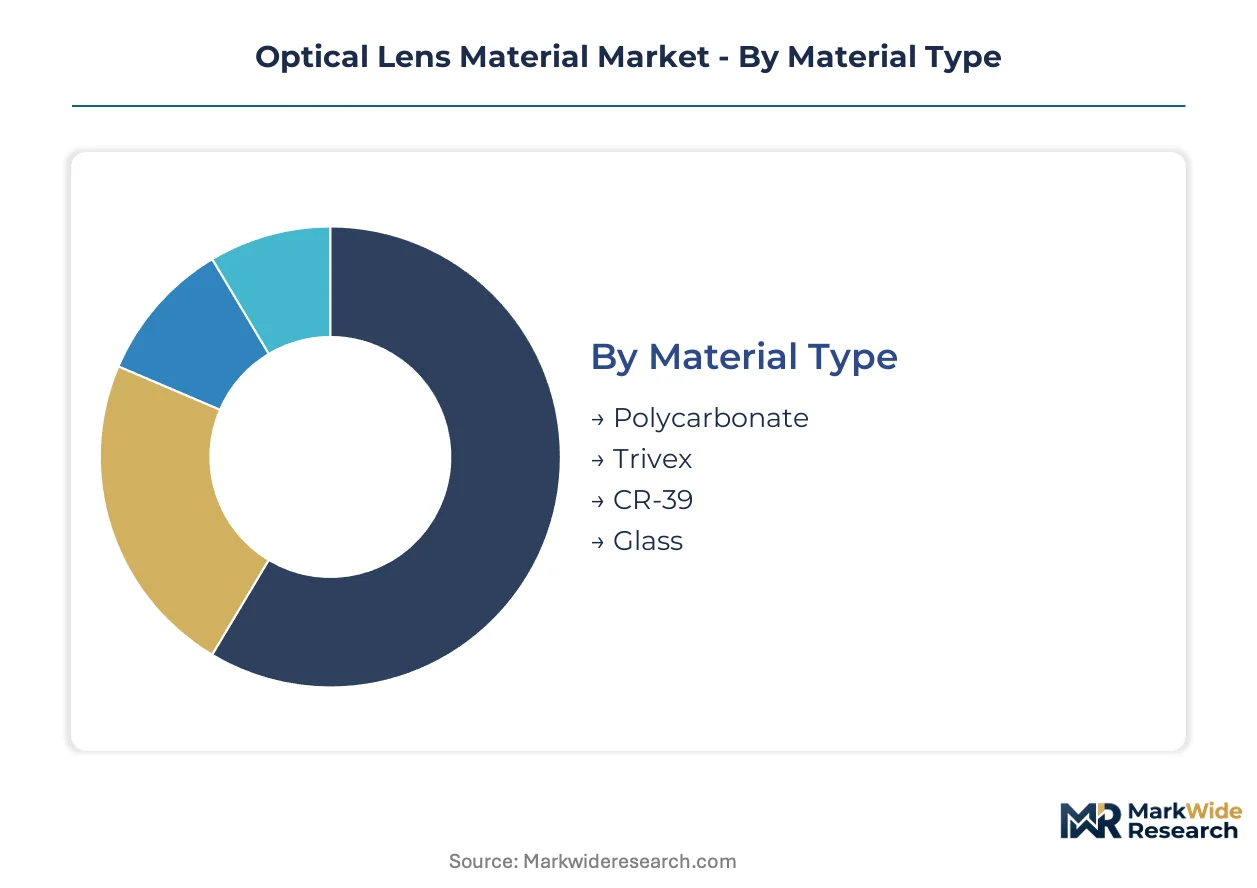
Material specifications, coating functionality, and distribution channel economics create distinct value pools across the optical lens material supply chain. Each segmentation dimension reveals divergent margin structures and technical qualification barriers that shape supplier competitive positioning.
Material Type:
Mature commodity resins coexist with emerging high-index formulations, creating a bifurcated supply landscape where volume and premium applications follow separate procurement logics.
- Polycarbonate:Thermoplastic polymer with impact resistance exceeding FDA 21 CFR Part 801 drop-ball test requirements and specific gravity of 1.20 g/cm³. Demand concentrates in safety eyewear manufacturing serving OSHA-regulated industrial workplaces across the United States, where impact certification mandates eliminate glass alternatives. Mass-market sports retailers in China specify polycarbonate for price-sensitive sunglass production.
- Trivex:Urethane-based monomer with Abbe number of 45 and the lightest density among mainstream optical polymers at 1.11 g/cm³. Premium prescription lens laboratories in Germany and Japan specify Trivex for rimless mountings where drill strength and chromatic aberration control justify 40-60% material cost premiums over polycarbonate.
- CR-39:Allyl diglycol carbonate thermoset resin dominating cast-molded prescription production through low capital equipment requirements and refractive index of 1.498. Cost-sensitive optical retail chains in India standardize on CR-39 for economy-tier single-vision lenses.
- Glass:Crown and flint optical glass formulations with refractive indices spanning 1.523 to 1.805 and unmatched scratch resistance. Precision imaging applications in Japanese machine vision systems and luxury Swiss watch crystals sustain niche demand despite weight and fragility constraints.
CR-39 retains volume leadership in prescription markets; Trivex holds the steepest expansion curve among premium material categories.
Coating Type:
Coating value capture escalates with functional complexity, creating margin tiers that separate commodity surface protection from integrated optical performance stacks.
- Anti-Reflective:Multi-layer vacuum-deposited interference coatings reducing surface reflectance below 1% across visible spectrum. Smartphone camera module suppliers in Shenzhen-Dongguan clusters demand anti-reflective precision at wafer-scale volumes, forcing coating houses to qualify ion-assisted deposition systems capable of sub-nanometer thickness control.
- Blue Light Filtering:Absorptive or reflective coatings targeting 415-455 nm wavelength suppression for digital eye strain mitigation. E-commerce prescription lens platforms targeting knowledge workers in South Korea and urban China integrate blue light filtration as standard configuration, expanding value capture in ophthalmic resin formulations.
- Scratch-Resistant:Hardcoat lacquers based on siloxane or acrylic-urethane chemistries applied via dip or spin coating. Mandatory for polycarbonate and Trivex substrates where base material softness compromises durability.
- UV Protection:Absorptive additives or surface treatments blocking UVA and UVB transmission below 400 nm. Regulatory baseline in EU CE-marked sunglasses and Australian TGA-registered prescription products.
Anti-reflective coatings command the highest unit economics; blue light filtering is expanding most quickly as a share of premium prescription transactions.
End User:
Channel structure determines pricing power and technical specification authority, with consolidated retail chains extracting material customization commitments from compounders.
- Optical Stores:Independent and chain retail operations prescribing and dispensing finished eyewear. Organized optical chains in Mumbai and Delhi consolidate supplier relationships, creating entry points for certified resin compounders seeking volume commitments.
- E-Commerce Platforms:Direct-to-consumer lens retailers virtualizing prescription verification and frame selection. Knowledge workers purchasing through these channels in Germany and the United Kingdom drive specification of integrated photo-protection and freeform surfacing.
- Healthcare Facilities:Hospital-affiliated ophthalmology clinics and vision centers. China's NMPA biocompatibility enforcement tightens material certification requirements for contact-adjacent lens dispensing.
- Sports Retailers:Mass-market and specialty athletic equipment channels. Impact-rated polycarbonate dominates procurement specifications for cycling, skiing, and ballistic protection segments.
Optical stores retain the largest transaction volume; e-commerce platforms are gaining share fastest in premium prescription categories.
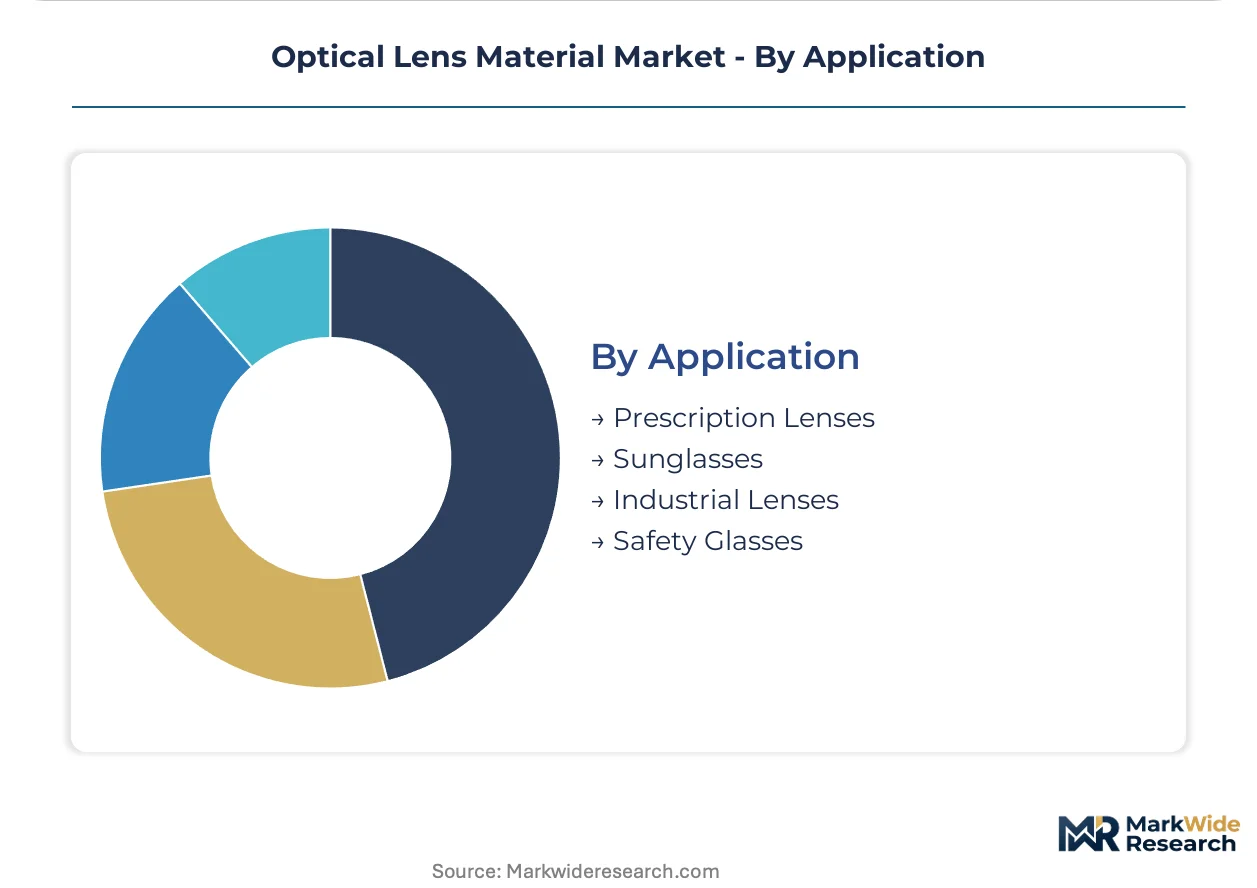
Application:
Application requirements span from regulated medical devices to fashion accessories, creating divergent compliance burdens and performance validation protocols.
- Prescription Lenses:Corrective optics manufactured to individualized diopter, cylinder, and axis specifications. Freeform lens surfacing technology virtualizes traditional grinding workflows, enabling mass customization through precision polymer deposition and UV-cured layer stacking.
- Sunglasses:Non-prescription and plano sun protective eyewear. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of oleophobic and hydrophobic lens coatings across EU-sold products, extending qualification timelines for premium segments.
- Industrial Lenses:Machine vision, laser safety, and inspection system optics. German and Japanese metrology hubs concentrate interferometric testing talent for sub-nanometer precision refractive index mapping.
- Safety Glasses:Impact-rated protective eyewear for occupational hazards. FDA and OSHA dual compliance requirements sustain polycarbonate dominance despite Abbe number limitations.
Prescription lenses anchor revenue concentration; industrial optics applications are climbing the fastest as machine vision deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision optics hubs while Chinese manufacturing clusters compete on wafer-scale volume throughput. This asymmetry shapes material procurement patterns across smartphone camera modules and prescription lens markets.
China
Smartphone OEMs drive procurement consolidation around high-index resin specifications. NMPA biocompatibility enforcement tightens certification timelines for contact-adjacent silicone hydrogel imports. Shenzhen and Dongguan host dense concentrations of precision molding and coating facilities serving export markets.
Germany
Premium prescription laboratories specify Trivex for rimless mountings where drill strength justifies material cost premiums. ECHA REACH disclosure requirements extend compliance timelines for unreacted monomers and phthalate plasticizers. Optical metrology talent concentrates in German hubs performing interferometric testing at sub-nanometer precision.
United States
OSHA-regulated industrial workplaces sustain polycarbonate demand through impact certification mandates eliminating glass alternatives. FDA 21 CFR Part 801 governs drop-ball testing and labeling requirements for prescription and non-prescription lenses. Knowledge workers purchasing through e-commerce channels drive blue light filtering specification in premium ophthalmic transactions.
Japan
Machine vision systems and luxury watch crystals sustain niche demand for crown and flint optical glass formulations. METI industrial policy supports precision optics manufacturing infrastructure. Thiourethane and episulfide precursor supply from Japanese chemical suppliers creates vulnerability to shipping disruptions for high-index lens compounders.
South Korea
E-commerce prescription lens platforms target urban knowledge workers demanding integrated photoprotection and freeform surfacing. MFDS regulates medical device classifications for corrective optics and contact-adjacent materials. Seoul-based smartphone camera module suppliers consolidate procurement tiers around refractive precision requirements.
Optical Lens Material Market Vendor Landscape
Captive supply chains and independent material compounders split the market into distinct procurement ecosystems. Consolidation concentrates around smartphone OEMs establishing direct resin partnerships while fragmentation persists among ophthalmic distributors serving independent optical retail. Three archetypes dominate: vertically integrated imaging system manufacturers, specialty polymer compounders with refractive customization capabilities, and retail-channel-integrated lens finishers. Competitive moves center on backward integration into molding operations and strategic partnerships bypassing traditional distributor networks.
Among Asia-Pacific-based fabricators, Sunny Optical Technology anchors high-volume smartphone lens assembly through in-house molding capacity, while Largan Precision occupies a position within the precision optics component tier. Carl Zeiss AG exemplifies the captive supply chain archetype through controlled premium glass and resin sourcing. These three represent divergent strategic positions without implying specific market share claims.
| Leading Market Players |
|---|
| FUJIFILM Corporation |
| Sony Electronics Inc. |
| Tamron Co., Ltd. |
| Carl Zeiss AG |
| Largan Precision Co., Ltd. |
| Sunny Optical Technology (Group) Company Limited |
| Nikon Corporation |
| EssilorLuxottica SA |
| Canon Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese molding clusters is compressing resin compounder margins while concentrating pricing power among smartphone OEMs with direct procurement leverage. This utilization asymmetry forces specialty distributors to absorb cost pressure or exit wafer-scale volume tiers entirely.
Pricing Analysis
The customization-premium spread separates configured-to-order high-index formulations from standard polycarbonate and CR-39 grades. Pricing stratifies across premium, standard, and economy tiers based on refractive index precision and certification grade. Cost compression in commodity resins is intensifying because smartphone OEMs consolidate procurement tiers around direct material partnerships. Independent optical retail chains exhibit highest price sensitivity, while German precision laboratories show lowest sensitivity due to performance-driven specification authority.
Supply Chain Analysis
Upstream thiourethane and episulfide precursor supply draws from Japanese and Korean chemical suppliers, creating single-source vulnerability for high-index lens compounders. Raw material dependencies center on allyl diglycol carbonate monomers, polycarbonate pellets, and specialty coating lacquers. Distribution runs through Shenzhen-Dongguan precision molding clusters serving export markets, with secondary hubs in Germany and the United States for prescription laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated smartphone OEMs and organized optical retail chains, fragmenting supplier pricing leverage across material tiers.
For Market Incumbents: Pre-empt coating formulation obsolescence by accelerating silicone-based hydrophobic alternatives ahead of EU F-Gas phasedown deadlines. Anchor capacity in NMPA-certified Chinese facilities to capture biocompatibility-driven import substitution. Defensive consolidation through backward integration into molding operations secures volume commitments against direct OEM-compounder partnerships. For New Entrants and Emerging Players: Establish a beachhead in India's organized optical retail consolidation wave, where Mumbai and Delhi chains seek certified resin suppliers. Target AR/VR waveguide integration as the most penetrable application, leveraging precision injection molding convergence with lithographic patterning. A go-to-market angle centered on accelerated NMPA certification pathways shortens time-to-market for compliant silicone hydrogel imports. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum deposition coating lines, where ion-assisted deposition systems exceed mid-tier compounder balance sheet capacity. Long-term viability favors acquisition targets with captive metrology talent and ISO 8980-1 harmonization capabilities spanning multiple regulatory jurisdictions. The signal to watch is smartphone OEM direct procurement announcements bypassing traditional distributor networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molding Operations | Sunny Optical Technology anchors high-volume smartphone lens assembly through in-house molding capacity. |
| Direct Material Partnership Establishment | Smartphone OEMs consolidate procurement tiers around refractive precision requirements in Shenzhen-Dongguan clusters. |
| Silicone-Based Coating Reformulation | ECHA REACH Annex XVII restrictions force substitution of fluorinated hydrophobic treatments ahead of phasedown deadlines. |
| NMPA Biocompatibility Certification Acceleration | China's tightened enforcement creates entry barriers for uncertified silicone hydrogel imports. |
| Freeform Lens Surfacing Technology Deployment | Precision polymer deposition and UV-cured layer stacking virtualize traditional grinding workflows for mass customization. |
Methodological Framework
The analysis maps ophthalmic resin formulations, smartphone camera module specifications, and industrial optics grades, each validated through compounder technical directors, optical retail procurement heads, and smartphone OEM supply chain managers. Primary interviews with coating house operations leaders and metrology laboratory supervisors combined with secondary validation from ECHA REACH registration databases, NMPA certification filings, and FDA 21 CFR Part 801 guidance documents. Bottom-up volume modeling across material type and coating functionality segments triangulated against top-down value estimates from trade flow analysis.
Assumptions held fixed include current regulatory enforcement trajectories for EU F-Gas phasedown and NMPA biocompatibility timelines, while variables included smartphone camera module specification evolution and AR/VR waveguide adoption curves. The analytical framework segments by material type, coating functionality, end-user channel, and application requirement across the projection horizon. CAGR derivation incorporated refractive index customization premiums, coating stack complexity economics, and regional certification cost differentials.
Stress conditions across thiourethane precursor supply disruptions, ECHA REACH disclosure timeline extensions, and polycarbonate Abbe number improvement trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledged sensitivity to fluorinated coating reformulation costs and metrology talent scarcity. Cross-checking against customs trade data for high-index resin imports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Laboratory Glassware Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Global Vitrification Market
Glass
3D Glass Substrate Market
Glass
Optical Glass Market
Glass
Glass Substrate Market
Glass
Global Laminated Glass Market
Glass
United States Flat Glass Market
Glass
North America Glass Insulators Market
Glass
Glass Manufacturing Market
Glass
Asia-Pacific Flat Glass Market
Glass
Dynamic Glazing Market
Glass
Glass Mat Thermoplastic Market
Glass
Cellular Glass Market
Glass
Europe Glassware Market
Glass
Glass Prepreg Market