
 Laboratory Glassware Market | 2026-2036
Laboratory Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Glassware Market Intelligence
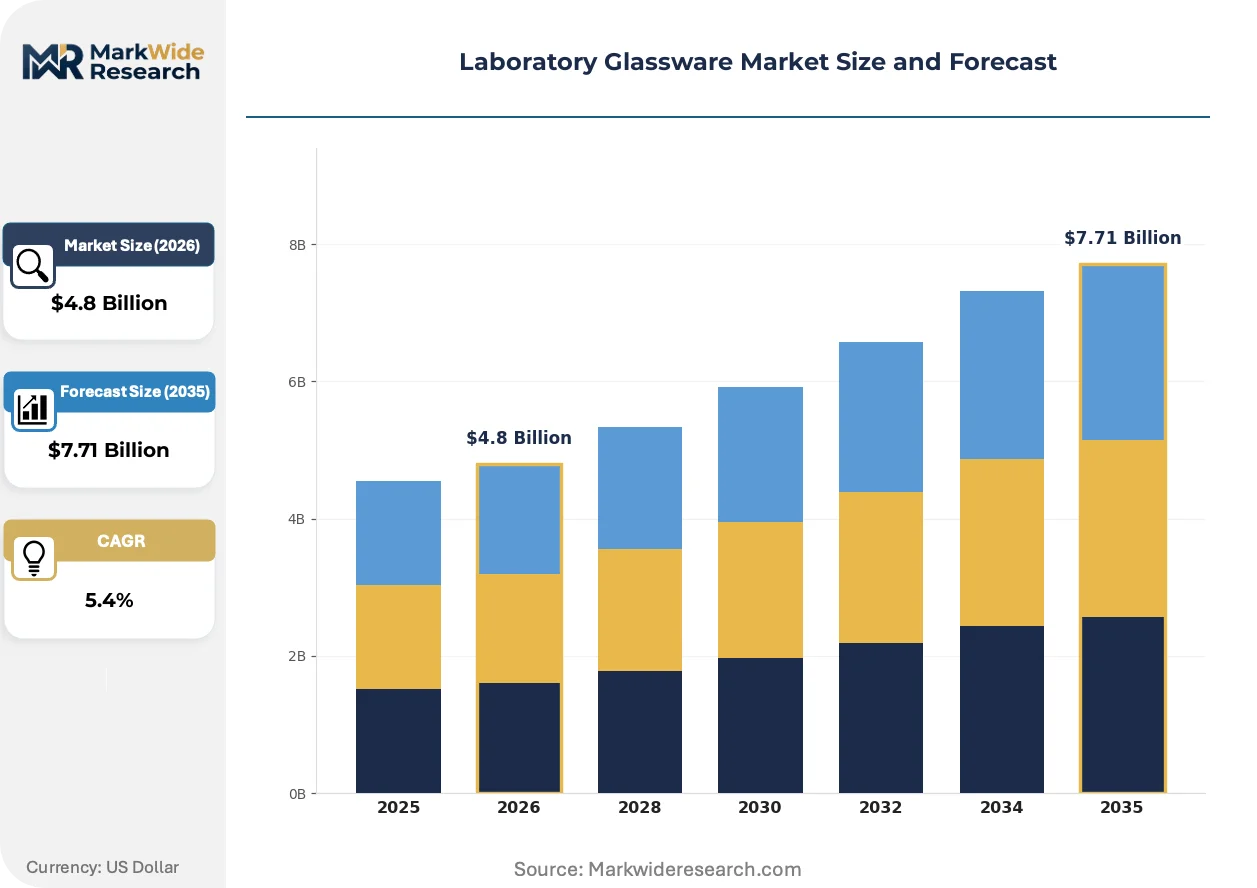
The performance gap between high-purity, certified borosilicate products and lower-grade, commodity soda lime glassware is expanding. This divergence creates distinct market tiers for precision and general-purpose applications. Corning Incorporated specializes in advanced glass formulations, including its well-known PYREX brand, for demanding scientific environments. Schott AG leverages its expertise in specialty glass manufacturing to supply pharmaceutical and industrial labs, while Borosil Limited competes effectively by offering a broad portfolio that serves both academic and industrial research needs.
Laboratory glassware comprises a range of vessels and instruments manufactured primarily from borosilicate glass, which offers low thermal expansion and high chemical resistance. These products are engineered for precision, containment, and measurement in controlled scientific settings. Demand from the pharmaceutical and biotechnology end-user segments drives the market for high-precision flasks and burettes used in chemical analysis and quality control. Beakers and test tubes remain foundational products, with significant volume originating from academic institutions and environmental testing labs.
Product quality and calibration are governed by international and national standards. ISO standards, such as ISO 4787 for volumetric instruments, provide a global benchmark for manufacturing consistency. In the United States, the FDA's Good Laboratory Practice regulations implicitly require calibrated equipment, while China's NMPA has similar requirements for drug development. Stakeholders must now decide whether to invest in premium, compliant materials or risk using lower-cost alternatives that may not meet future regulatory stringency.
Market Dynamics
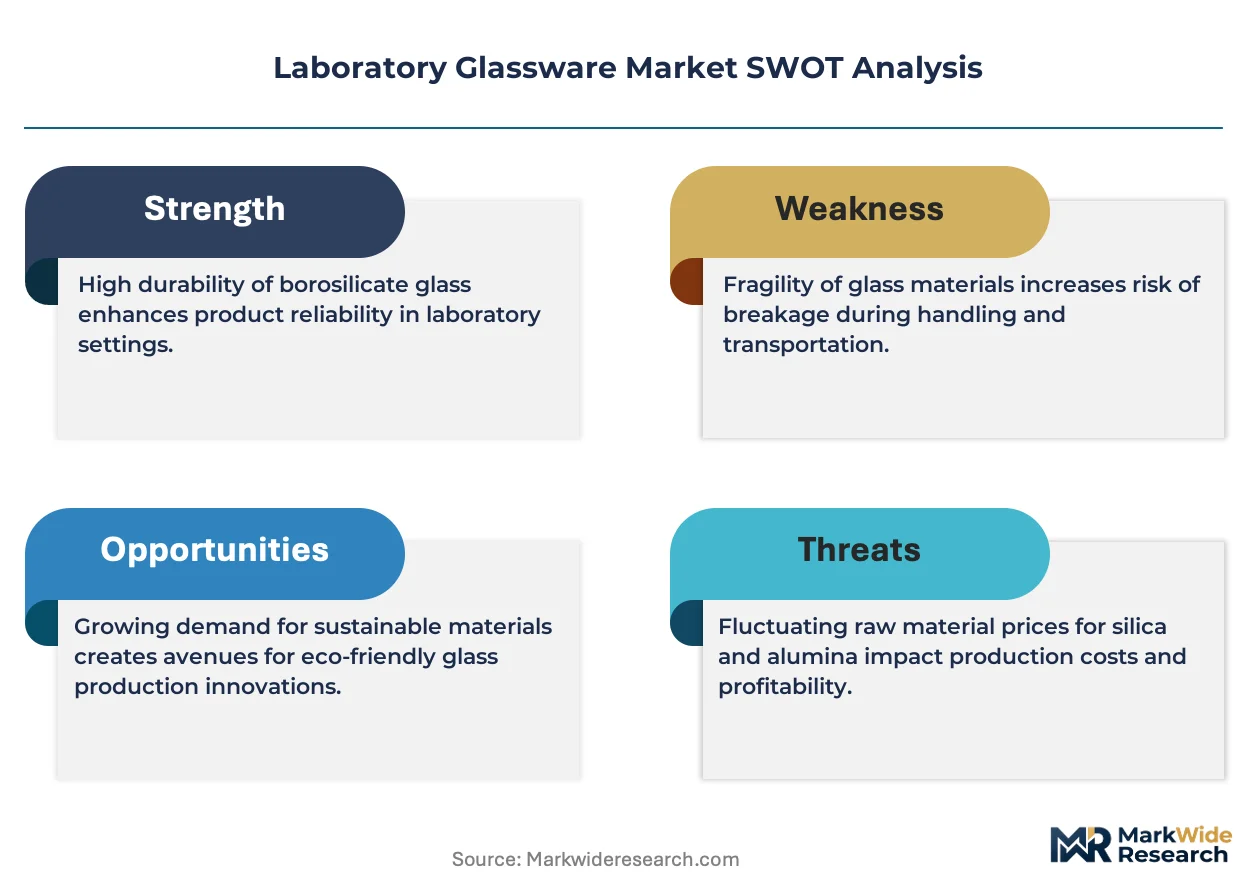
The primary structural force shaping the laboratory glassware market is the widening performance and quality gap between certified borosilicate glass and commodity soda-lime glass, driven by increasingly stringent regulatory frameworks and the sophisticated demands of biotechnology research.
Growth Catalysts
- Biotechnology Expansion:Demand from the biotechnology sector for sterile, high-purity flasks, pipettes, and cell culture vessels is escalating to support research and manufacturing of complex biologics and cell-based therapies.
- Regulatory Stringency:Global standards like ISO 4787 and national regulations such as the FDA's Good Laboratory Practice (GLP) mandate the use of accurately calibrated volumetric glassware, compelling labs to invest in compliant products.
- Pharmaceutical R&D in Asia:Expanding pharmaceutical research and manufacturing hubs in China and India are generating significant volume demand for a wide range of laboratory glassware, from basic beakers to specialized reaction vessels.
Market Restraints
- Substitution by Plasticware:Disposable plastic labware, particularly in high-throughput screening and molecular biology applications, presents a significant substitution threat due to its break resistance, sterility, and convenience.
- Energy and Material Cost Volatility:The production of borosilicate glass is an energy-intensive process, making manufacturers' profit margins vulnerable to fluctuations in natural gas and electricity prices, as well as boric oxide costs.
- End-User Purchasing Power:Consolidation among large pharmaceutical companies and contract research organizations (CROs) increases their bargaining power, enabling them to exert significant downward price pressure on glassware suppliers.
Strategic Opportunities
- Advanced Surface Treatments:Developing glassware with specialized surface coatings, such as hydrophobic or low-protein-binding layers, creates value for sensitive applications in proteomics, genomics, and high-performance chromatography.
- Environmental Testing Expansion:Stricter global environmental monitoring for contaminants like PFAS and microplastics creates new demand for certified, ultra-clean glassware for sample collection, preparation, and analysis.
- Digital Integration for Traceability:Embedding glassware with unique identifiers like QR codes or RFID tags enables seamless integration with Laboratory Information Management Systems (LIMS) for automated inventory and workflow tracking.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of scientific glassblowers with the expertise to create and repair complex, custom-designed apparatus poses a challenge for academic research and specialized industrial processes.
- Compliance and Certification Burden:The time and expense required to obtain and maintain accreditations, such as ISO 17025 for calibration, represent a significant operational hurdle, particularly for smaller manufacturers and distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Glassware Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beakers, Flasks, Test Tubes, Burettes Material: Borosilicate Glass, Soda Lime Glass, Quartz Glass, Plastic End User: Pharmaceuticals, Biotechnology, Academic Institutions, Environmental Testing Application: Chemical Analysis, Biological Research, Quality Control, Education |
| Companies Covered | DWK Life Sciences GmbH, Schott AG, Thermo Fisher Scientific Inc., Borosil Limited, Bellco Glass Inc., Corning Incorporated, Avantor Inc., Gerresheimer AG, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Glassware Market Strategic Shifts & Innovations
The role of laboratory glassware is evolving from a simple container to an integrated component of the digital, data-driven laboratory. This transformation is driven by innovations in material science, enhanced traceability requirements, and a greater focus on analytical precision.
Advanced borosilicate glass formulations provide superior thermal shock resistance and chemical inertness. Pharmaceutical and specialty chemical labs are adopting these enhanced materials for process chemistry and quality assurance functions where aggressive reagents and temperature gradients are common. This advanced material science is converging with microfluidics technology, allowing the fabrication of custom glass-based chips for complex, miniaturized analytical procedures.
The European Union's In Vitro Diagnostic Regulation (IVDR) places more stringent demands on the entire supply chain for diagnostic products. This policy elevates quality expectations for all components, including the glassware used for reagent handling and sample containment. Consequently, diagnostic kit producers are increasingly sourcing higher-grade, certified glassware to ensure their final products meet the IVDR's rigorous performance and safety standards.
End-users in regulated GxP environments are shifting procurement criteria beyond price to prioritize lifecycle traceability and data integrity. This behavioral change is displacing the purchase of generic, uncertified glassware with products that feature unique serial numbers or accessible batch-specific certificates of analysis. This trend is most visible within pharmaceutical quality control laboratories in North America and Europe, where regulators like the FDA and EMA heavily scrutinize data authenticity.
Laboratory Glassware Market Segmentation
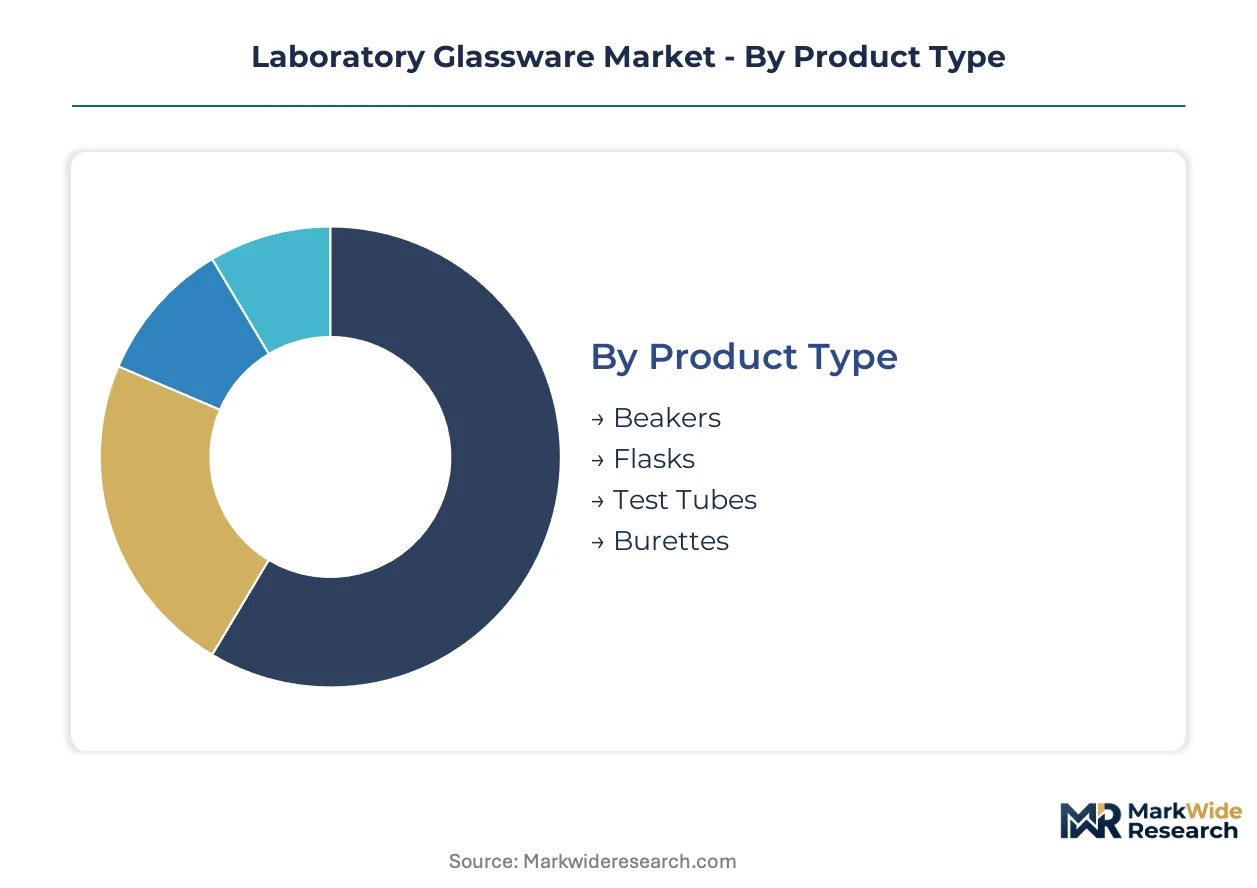
The laboratory glassware market's segmentation reveals the diverse requirements across scientific disciplines, influencing manufacturing specialization and procurement strategies. Understanding these distinct categories helps stakeholders identify areas of concentrated demand and emerging technological preferences. This granular view highlights the evolving landscape from basic labware to highly specialized, certified instruments.
Product Type:
The supply of laboratory glassware products is increasingly concentrating on specialized items that cater to advanced research, while foundational pieces remain widely available.
- Flasks:These vessels, often made from borosilicate glass, feature narrow necks for controlled pouring and mixing, essential for solution preparation and chemical reactions. Demand for high-precision volumetric flasks is significant in pharmaceutical quality control laboratories in Europe and North America.
- Beakers:Characterized by their cylindrical shape and pouring spout, beakers are fundamental for general mixing, heating, and holding liquids in academic institutions. Volume demand remains high in environmental testing labs across India and China for routine sample processing.
- Test Tubes:Small, cylindrical glass tubes with a rounded bottom, primarily used for qualitative experiments and culturing small samples.
- Burettes:Calibrated glass tubes with a stopcock at the bottom, used for precise liquid dispensing in titrations and quantitative chemical analysis.
Today's leader: Beakers. Tomorrow's challenger: Flasks.
Material:
Material choice often dictates the cost tier of laboratory glassware, with premium options offering superior performance for demanding applications.
- Borosilicate Glass:Known for its low thermal expansion and high chemical resistance, this material is preferred for applications involving heating, aggressive chemicals, and sterilization. The biotechnology sector drives demand for advanced borosilicate formulations in sterile cell culture and complex biological assays.
- Plastic:Offering break resistance, light weight, and disposability, plastic labware serves as a cost-effective alternative for high-throughput screening and molecular biology. Its convenience and sterility are displacing traditional glass in many routine diagnostic and research applications.
- Soda Lime Glass:A more economical option, soda lime glass is suitable for general-purpose applications where high thermal or chemical resistance is not critical.
- Quartz Glass:Valued for its transparency to UV light and extreme thermal stability, quartz glass is used in specialized spectroscopic applications and high-temperature processes.
Borosilicate glass maintains market dominance, while plastic labware is expanding most quickly due to its convenience and cost-effectiveness.
End User:
End-user segments are defined by their specific application needs, which in turn dictate the type and quality of glassware procured.
- Biotechnology:This sector requires high-purity, sterile, and often custom-designed glassware for cell culture, fermentation, and complex biologics research and manufacturing. Demand from biotechnology companies in the United States is escalating for specialized flasks and pipettes.
- Pharmaceuticals:Pharmaceutical companies utilize a wide array of calibrated glassware for drug discovery, process development, quality control, and manufacturing. Expanding R&D activities in China and India are driving significant demand for volumetric instruments and reaction vessels.
- Academic Institutions:Universities and research centers use foundational glassware for educational purposes and basic scientific exploration.
- Environmental Testing:Labs involved in environmental monitoring require certified, ultra-clean glassware for sample collection and analysis of contaminants.
The pharmaceutical sector remains a foundational end-user, with biotechnology gaining share fastest due to its complex research demands.
Application:
Applications for laboratory glassware vary significantly based on the customer type, ranging from fundamental education to highly regulated industrial processes.
- Chemical Analysis:This application demands high-precision volumetric glassware, such as burettes and pipettes, for accurate measurement and titration in analytical chemistry. Quality control laboratories in Germany and Japan rely on certified glassware for precise chemical assays.
- Biological Research:Requiring sterile and often specialized glassware, biological research applications include cell culture, microbiology, and molecular biology experiments. The growing field of cell-based therapies in the US drives demand for advanced culture flasks.
- Quality Control:Industrial and pharmaceutical quality control departments use calibrated glassware to ensure product consistency and compliance with regulatory standards.
- Education:Basic laboratory glassware like beakers and test tubes are essential for teaching fundamental scientific principles in schools and universities.
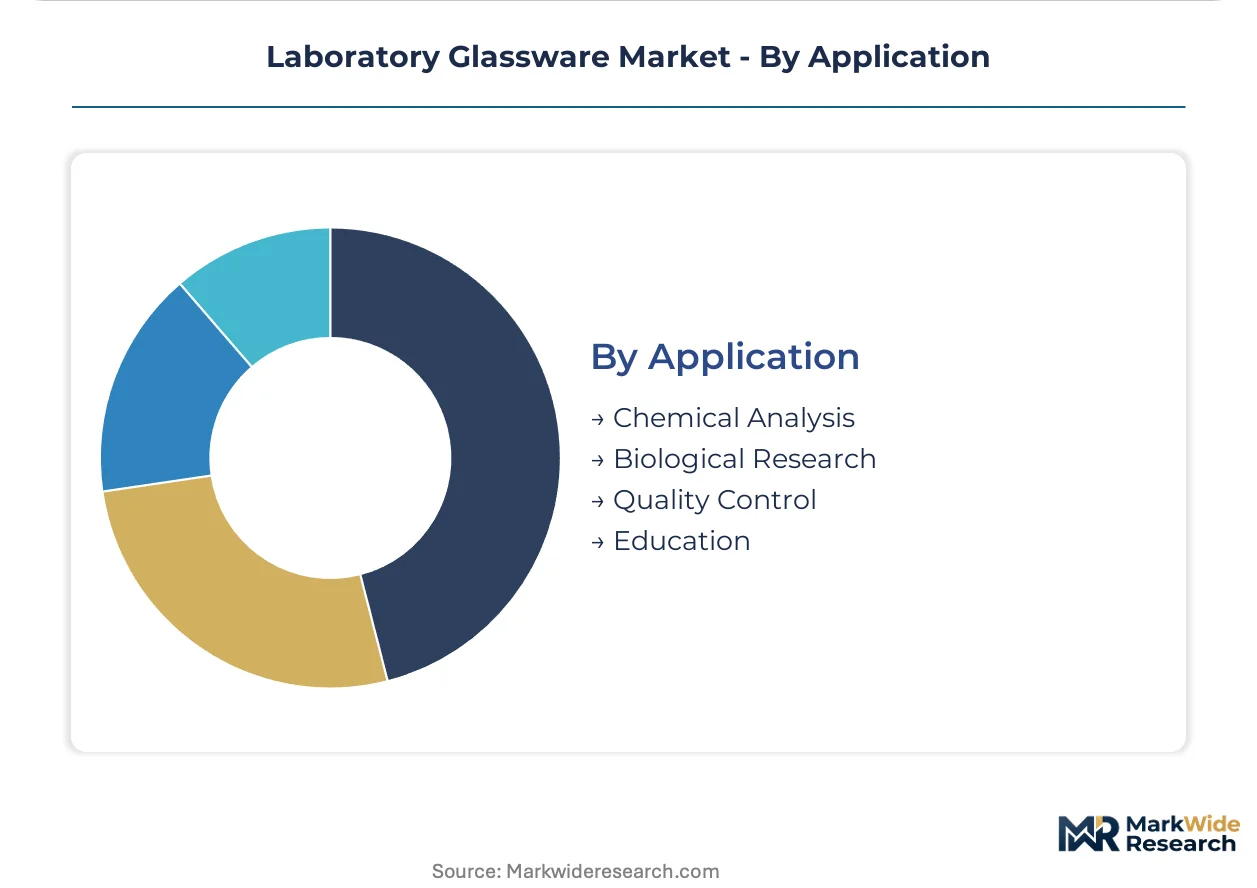
Quality control applications provide consistent demand, while biological research is on the steepest expansion trajectory due to innovation in life sciences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India drive significant volume demand for laboratory glassware due to expanding pharmaceutical research and manufacturing. Meanwhile, the United States focuses on high-purity, specialized products for its burgeoning biotechnology sector. This regional divergence shapes global market dynamics for scientific instrumentation.
United States
Demand for advanced borosilicate glassware in the United States stems from complex biological research and cell-based therapies. The FDA's Good Laboratory Practice (GLP) regulations implicitly require calibrated equipment for drug development. Biotechnology clusters in Boston and San Francisco actively procure specialized flasks and pipettes.
China
Chinese pharmaceutical research and manufacturing expansion generates substantial demand for a wide range of laboratory glassware. The NMPA imposes stringent quality requirements for drug development processes, impacting procurement decisions. Shanghai's biopharmaceutical hubs are rapidly increasing their consumption of reaction vessels and volumetric instruments.
India
India's growing pharmaceutical sector and academic institutions fuel significant volume demand for foundational labware. The BIS standards for laboratory equipment promote quality and consistency across the scientific community. Hyderabad's thriving pharmaceutical manufacturing zone actively procures beakers and test tubes for routine analysis.
Germany
German quality control laboratories and specialty chemical industries require high-precision volumetric glassware for chemical analysis. ISO 4787 standards for volumetric instruments provide a crucial benchmark for manufacturing consistency. The Rhine-Main region, a hub for chemical companies, consistently invests in certified laboratory equipment.
Japan
Japanese analytical chemistry applications and advanced material science research drive demand for specialized quartz and borosilicate glass. The PMDA's regulatory oversight ensures high standards for pharmaceutical and medical device components. Tokyo's research institutions are increasing their procurement of ultra-clean glassware for environmental testing.
Laboratory Glassware Market Key Industry Players
Top-tier vendors anchor the premium segment, while smaller manufacturers often serve the general-purpose and academic markets. The market exhibits a tiered structure, with a clear distinction between suppliers of certified, high-purity borosilicate products and those offering commodity soda-lime glassware. Strategic archetypes include advanced material innovators, specialized industrial suppliers, and broad-portfolio providers catering to diverse research needs. Companies are increasingly pursuing portfolio diversification and geographic expansion, alongside strategic partnerships, to capture new opportunities and enhance their market reach.
On the premium-tier vector, Corning Incorporated, a US-based company, anchors the advanced glass formulations segment, representing innovation for demanding scientific environments. Schott AG, a German AG, exemplifies specialty glass manufacturing, supplying pharmaceutical and industrial laboratories globally with its specialized products. Borosil Limited, an India-based company, occupies a position as a broad-portfolio provider, effectively serving both academic and industrial research needs across diverse regions. These companies collectively illustrate the diverse strategies employed to address the widening performance gap and meet evolving regulatory demands in laboratory glassware. Their distinct approaches highlight the competitive dynamics within different market tiers.
| Leading Market Players |
|---|
| DWK Life Sciences GmbH |
| Schott AG |
| Thermo Fisher Scientific Inc. |
| Borosil Limited |
| Bellco Glass Inc. |
| Corning Incorporated |
| Avantor Inc. |
| Gerresheimer AG |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Skilled scientific glassblowers represent a concentrated workforce, and labor-cost differentials directly influence the pricing tiers for custom and specialized laboratory glassware across global markets.
Pricing Analysis
The market primarily operates on a per-unit transactional pricing model for commodity items, transitioning to contract-based long-term offtake for specialized, high-volume products. Price differentiation hinges on material quality, with certified borosilicate glass commanding a premium over soda-lime alternatives, alongside brand reputation and the level of regulatory compliance (e.g., ISO 4787 calibration). Pricing pressure stems from the consolidated purchasing power of large pharmaceutical companies and contract research organizations. Academic institutions and environmental testing labs often exhibit higher price sensitivity compared to pharmaceutical and biotechnology end-users requiring certified products.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for laboratory glassware, ensuring efficient delivery to diverse end-users. Geographic supply concentration for high-volume, foundational labware centers in China and India, while Germany and the United States specialize in advanced borosilicate formulations. The industry draws from raw materials such as silica and boric oxide, alongside significant energy inputs like natural gas for glass production. Energy and material cost volatility represents a structural supply chain risk. Distribution runs through a hybrid model, combining direct sales to large industrial clients with a network of scientific distributors serving academic and smaller research facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory glassware market functions as a stable compounder, with biotechnology expansion consistently fueling demand for specialized, high-purity products.
For Market Incumbents:Anticipate the continued substitution threat from disposable plasticware by focusing on areas where glass superiority is non-negotiable. Invest in advanced surface treatments for specialized applications like genomics and proteomics, enhancing material performance. Pursue strategic acquisitions of niche glassblowing expertise to address the skilled labor scarcity. Strengthen certification programs for volumetric instruments, leveraging ISO 17025 accreditation as a competitive lever against lower-grade alternatives.
For New Entrants and Emerging Players:The European Union's In Vitro Diagnostic Regulation (IVDR) in Europe opens a window for certified, high-quality glassware components. Target the expanding environmental testing segment for contaminants like PFAS, which requires ultra-clean, certified glassware. Focus on developing integrated digital traceability solutions, such as QR codes, for seamless LIMS integration. A go-to-market angle could involve offering bundled solutions of certified glassware with data management services for regulated labs.
For Investors and Strategic Acquirers:Valuations sit cheapest among smaller, specialized manufacturers providing custom apparatus or unique material formulations. The market exhibits long-term viability over a 5-10 year window, driven by sustained growth in life sciences and increasing regulatory stringency. Identify acquisition targets with strong intellectual property in advanced glass science or established customer bases in high-growth biotechnology clusters. The signal to watch is the adoption rate of digital traceability features and advanced surface-treated products in regulated environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Surface Treatment R&D | Developing hydrophobic or low-protein-binding layers creates value for sensitive biological research applications. |
| Investment in Digital Traceability | Embedding glassware with unique identifiers enables seamless integration with Laboratory Information Management Systems (LIMS). |
| Geographic Expansion in Asia | Establishing stronger sales and distribution networks captures significant volume demand from China and India. |
| Strategic Acquisition of Glassblowing Expertise | Securing specialized talent addresses the persistent scarcity of scientific glassblowers for complex apparatus. |
| ISO 17025 Certification Program | Obtaining and maintaining this accreditation provides a global benchmark for calibration consistency and quality assurance. |
Research Approach
Coverage spans North America, Europe, and Asia, with primary inputs from each region informing the market's dynamics. This analysis combines in-depth primary interviews with industry stakeholders, including lab managers, procurement officers, R&D scientists, and regulatory compliance specialists. Secondary validation leverages NMPA guidelines, FDA GLP regulations, ISO standards, and relevant industry association reports. Bottom-up data aggregation and top-down market sizing ensure comprehensive triangulation.
The analytical framework decomposes the rate of change across the modeling period, projecting market evolution over the projection horizon. Segmentation dimensions modeled include product type, material, end-user, application, and regulatory compliance level. Compound annual growth rates were derived from historical data analysis and future trend projections. Biotechnology R&D spending and pharmaceutical manufacturing output serve as key industry-specific forecast inputs.
Revisions become necessary when significant shifts in raw material costs or major regulatory changes materialize, impacting market fundamentals. Forecasts reflect assumptions regarding technological stability and sustained research investment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Polishing Powder Market
Glass
Laboratory Glass Container Market
Glass
Glass Mat Market
Glass
Technical Glass Market
Glass
Crystalware and Glassware Market
Glass
Coated Solar Control Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Europe Glass Insulators Market
Glass
India Flat Glass Market
Glass
Silica Market
Glass
Tinted Glass Market
Glass
Glazing Gel Market
Glass
Silica Sol Market
Glass
United States Flat Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Solar Control Glass Market