
 Middle-East and Africa Flat Glass Market | 2026-2036
Middle-East and Africa Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Flat Glass Market Foresight
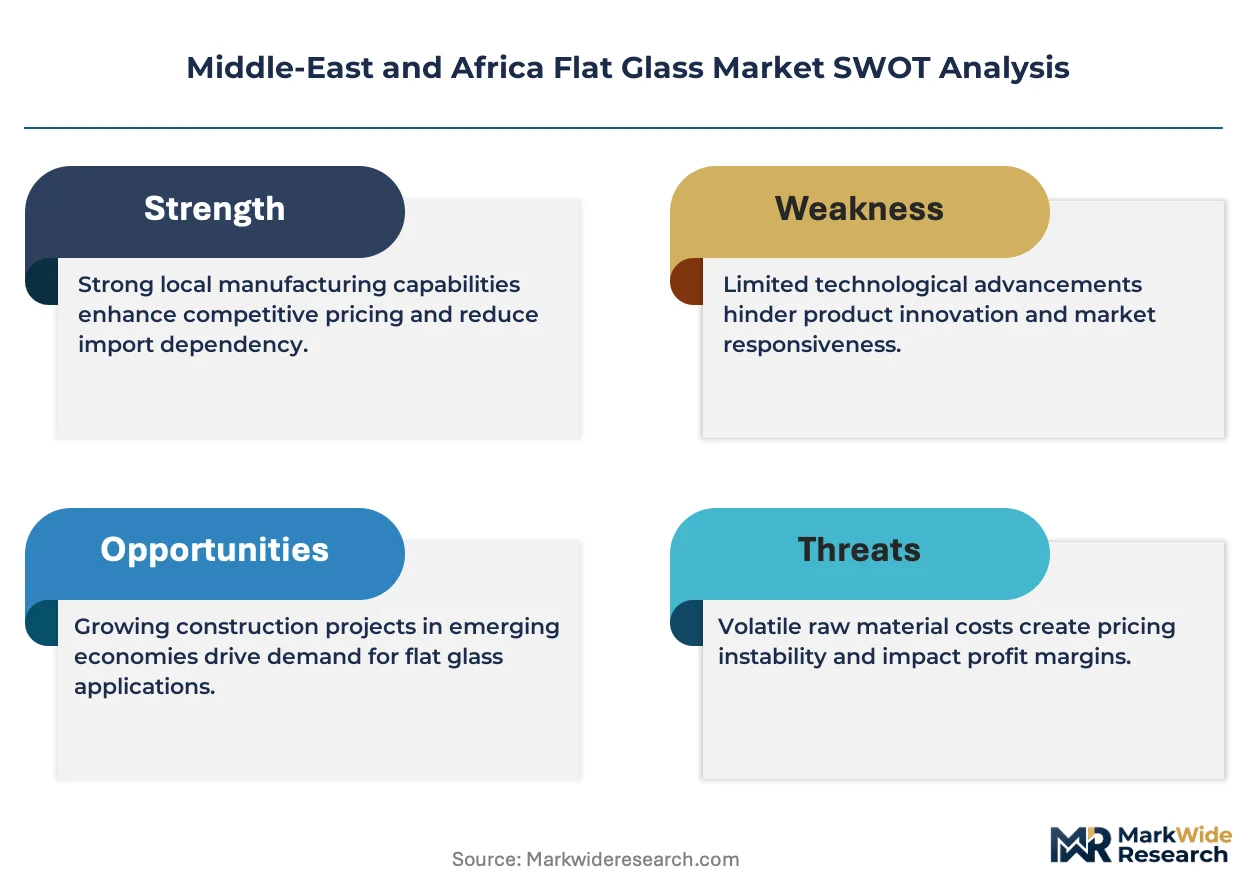
A widening capital-intensity gap between integrated float-glass producers and downstream fabricators is reorganizing competitive hierarchies across the Middle-East and Africa. Saint-Gobain leverages its Egyptian and UAE manufacturing bases to supply coated architectural glass across North Africa and the Levant. Guardian Glass LLC anchors its regional position through float-glass production in Saudi Arabia, sustaining volume commitments to domestic construction procurement.
Flat glass comprises silica-sand-based soda-lime sheets formed through the float process on molten tin baths, yielding thicknesses from two to twenty-five millimeters for structural and optical applications. Architectural applications dominate regional consumption, with float glass occupying the core volume position while low-E and smart glass technologies command expanding specification in premium commercial developments. Solar energy applications represent the fastest-growing segment, as photovoltaic project pipelines in Morocco and South Africa multiply tempered glass procurement requirements.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization building codes, South Africa's National Regulator for Compulsory Specifications energy-performance requirements, and UAE green building regulations such as Estidama collectively mandate higher thermal-performance glazing in new construction. These frameworks compel manufacturers to certify low-E and multi-layer products while restricting market access for uncertified imports. Stakeholders must monitor evolving energy-code harmonization between Gulf Cooperation Council states to anticipate specification shifts and inventory positioning requirements.
Market Dynamics
The enforcement of mandatory building energy codes across Gulf Cooperation Council states is compressing specification timelines and forcing fabricators to certify low-emissivity and multi-layer glazing products before market entry.
Growth Catalysts
- Estidama and UAE green building regulations:These frameworks mandate higher thermal-performance glazing in new commercial developments, compelling developers to specify certified low-E products for Pearl-rated buildings.
- Solar photovoltaic deployment:Tempered glass procurement is accelerating across Morocco and South Africa as utility-scale PV project pipelines multiply, creating dedicated demand channels for solar-grade flat glass.
- Saudi Standards, Metrology and Quality Organization codes:Stricter enforcement across the Kingdom's construction sector is eliminating uncertified imports and redirecting procurement toward compliant domestic and regional suppliers.
Market Restraints
- Silica sand and soda ash input volatility:Energy-intensive raw material processing faces cost pressure from natural gas pricing fluctuations, compressing margins for non-integrated float-glass producers.
- Float-glass capacity concentration:Production gravity centers on Egypt, Saudi Arabia, and the UAE, creating supply vulnerability for East African and Levant markets dependent on long-haul logistics.
- Technical limitation in smart glass manufacturing:Electrochromic and thermochromic coating capabilities remain concentrated among a limited supplier base, restricting specification access for mid-market commercial projects.
Strategic Opportunities
- East African construction markets:Kenya and Ethiopia exhibit underpenetrated specification of low-E glazing despite accelerating commercial development, presenting first-mover positioning for certified suppliers.
- Building-integrated photovoltaics:The convergence of architectural glazing and solar energy generation is opening specification channels for transparent photovoltaic glass in premium commercial facades.
- Gulf Cooperation Council energy-code harmonization:Coordinated tightening of thermal-performance standards across member states is creating cross-border procurement efficiencies for manufacturers with multi-country certification.
Industry Challenges
- Coating technician skill scarcity:The specialized workforce for magnetron sputtering and chemical vapor deposition remains limited across the region, constraining capacity expansion for value-added products.
- Product certification timeline compression:Accelerating regulatory deadlines in Saudi Arabia and the UAE are forcing fabricators to compress testing and approval cycles, straining quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Flat Glass Market |
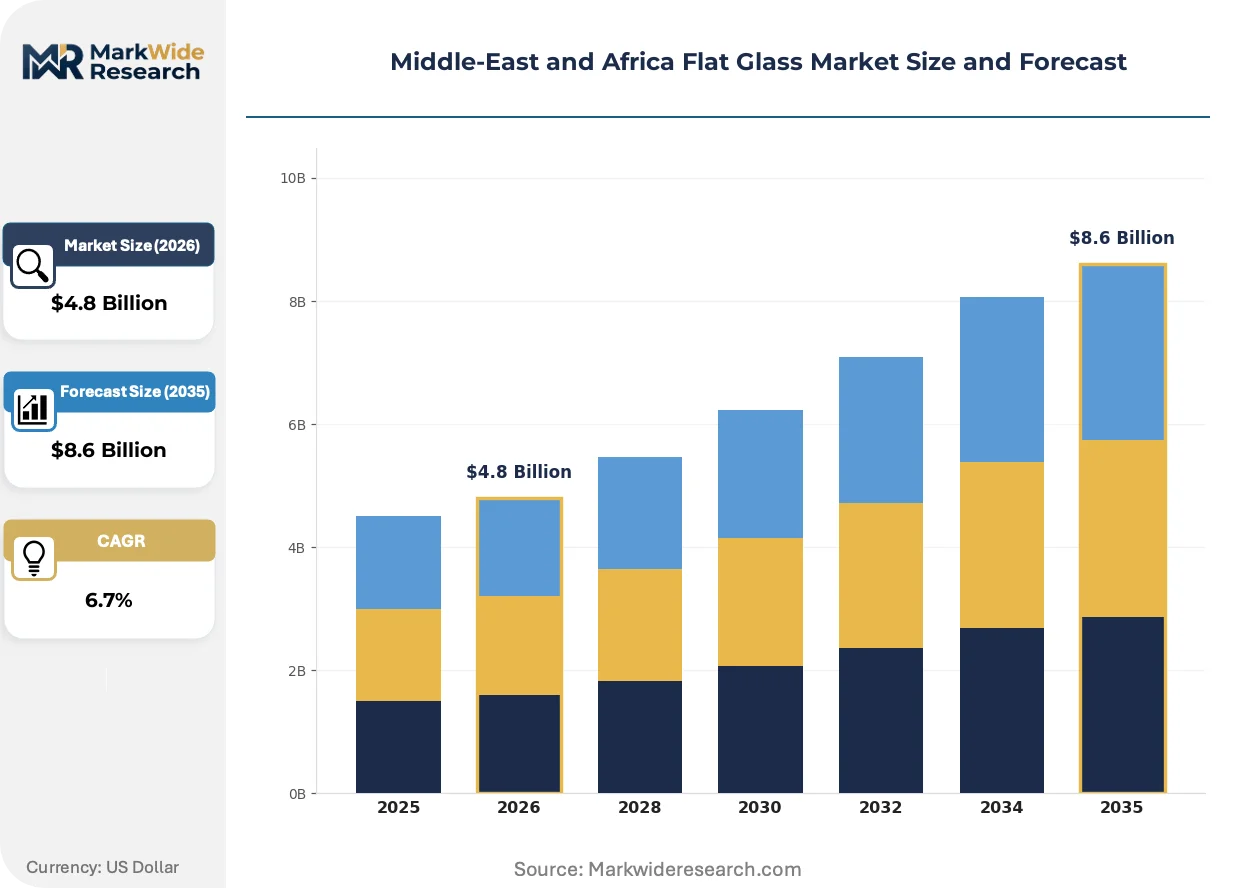
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Laminated Glass, Tempered Glass, Coated Glass Application: Architectural, Automotive, Furniture, Solar Energy End User: Construction, Transportation, Retail, Manufacturing Technology: Smart Glass, Low-E Glass, UV Blocking Glass, Multi-Layer Glass |
| Companies Covered | Saint-Gobain, AGC Inc., Guardian Glass LLC, Sisecam Group, Nippon Sheet Glass Co. Ltd, Emirates Glass LLC, Saudi American Glass, Obeikan Glass Company, Misr Glass Manufacturing Co., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Flat Glass Market Shifts & Advancements
Active coating technologies and digital specification platforms are restructuring how architectural glazing is procured and performance-validated across Middle-East and Africa construction markets.
Electrochromic and thermochromic smart glass is displacing conventional static low-E products in premium commercial developments. Dubai and Riyadh developers are specifying dynamic glazing for high-performance facades at accelerating rates. This technology is displacing fixed-performance coatings by enabling real-time solar heat gain coefficient adjustment, compressing demand for traditional multi-layer low-E configurations.
Saudi Standards, Metrology and Quality Organization building codes and UAE Estidama regulations are mandating pre-installation thermal performance verification. Fabricators must now submit third-party test reports before project approval, extending sales cycles but locking out uncertified competitors. Saudi Arabia's construction procurement is most affected, with developers now requiring factory production control documentation for all glazed envelope components.
Direct specification between glass fabricators and project developers is shortening traditional distributor channels. Large-scale megaproject procurement teams in the UAE and Saudi Arabia are engaging manufacturers for volume commitments, bypassing regional stockists. This pattern is most visible across Gulf Cooperation Council commercial tower developments, where single-source supply agreements are replacing fragmented multi-supplier arrangements.
Middle-East and Africa Flat Glass Market Segmentation
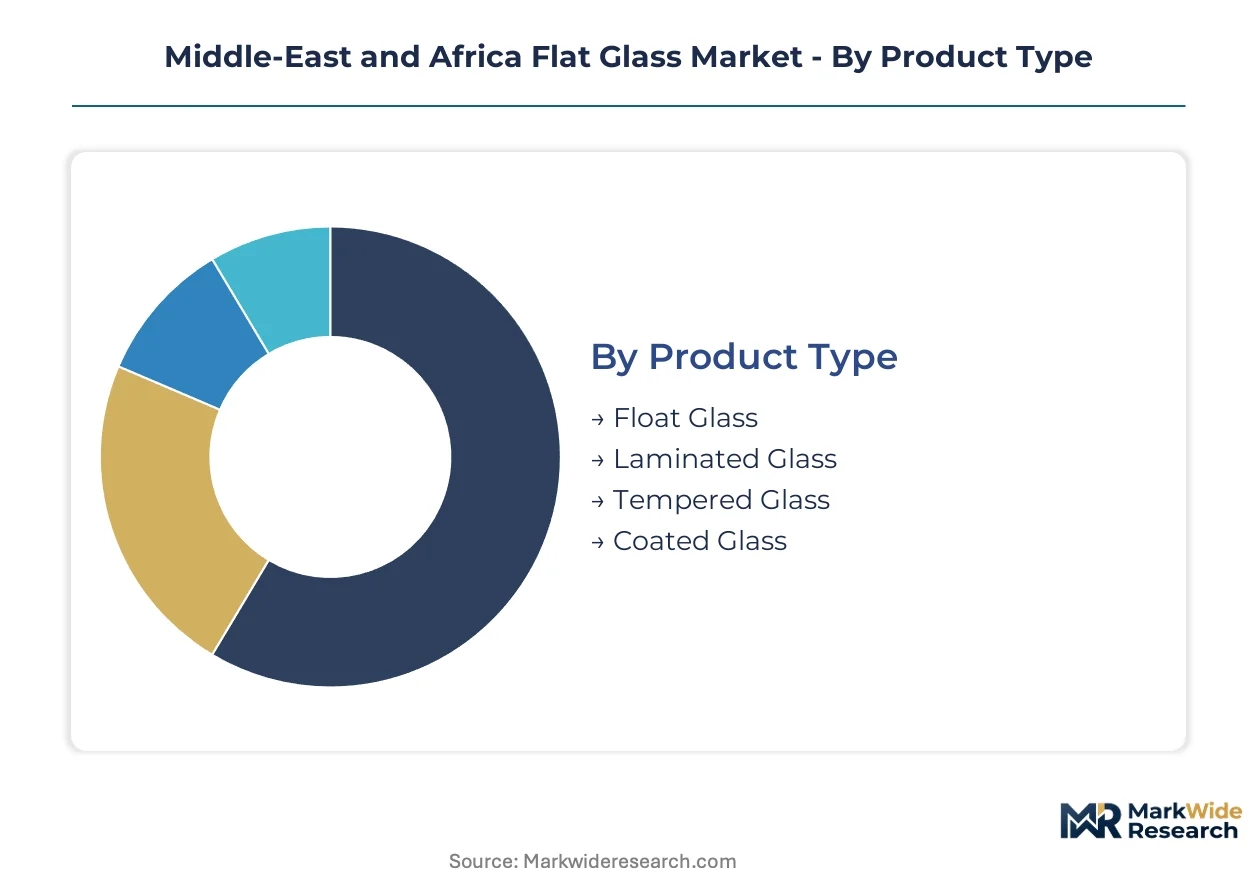
Flat glass procurement across the Middle-East and Africa fragments across four distinct classification axes. Specification requirements diverge sharply between Gulf Cooperation Council megaprojects and East African commercial developments, forcing suppliers to maintain parallel product portfolios.
Product Type:
Margin pools concentrate in coated and tempered value-add processing rather than commodity float production.
- Float Glass:Molten silica-sand-soda-lime sheets formed on molten tin baths deliver base substrates for downstream fabrication. Saudi Arabia and Egypt host the region's dominant float capacity, supplying raw stock to Levant and East African fabricators facing logistics cost penalties.
- Tempered Glass:Thermal or chemical strengthening creates safety glass with four-to-five-times mechanical resistance for structural applications. Solar photovoltaic deployment in Morocco and South Africa is accelerating tempered procurement for module encapsulation, outpacing architectural demand growth.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for post-breakage retention in hurricane and blast-rated facades.
- Coated Glass:Magnetron-sputtered metal oxide layers deliver low-emissivity performance for Saudi and UAE energy-code compliance.
Float glass holds installed capacity. Tempered glass is rotating up the share rankings.
Application:
Volume concentration tracks construction cycle intensity across Gulf Cooperation Council states.
- Architectural:Curtain wall, storefront, and interior partition glazing consumes the regional volume base. UAE megaproject pipelines in Dubai and Abu Dhabi specify substantial tempered and laminated volumes for commercial tower envelopes.
- Solar Energy:Photovoltaic module encapsulation demands high-transmission tempered glass with anti-reflective surface treatment. Morocco's Noor Ouarzazate complex and South Africa's Renewable Energy Independent Power Producer Procurement Programme multiply procurement channels.
- Automotive:OEM and aftermarket windscreen, sidelite, and backlite replacement serves North African assembly plants.
- Furniture:Tabletop, shelving, and decorative applications consume smaller-format processed glass.
Architectural applications anchor current procurement. Solar energy is climbing the fastest.
End User:
Customer concentration favors construction procurement teams with direct manufacturer engagement.
- Construction:General contractors and glazing subcontractors specify flat glass for building envelope completion. Saudi Arabia's contracting sector is redirecting procurement toward Saudi Standards, Metrology and Quality Organization-certified suppliers, eliminating uncertified import channels.
- Transportation:Bus, rail, and marine glazing requirements serve state infrastructure procurement.
- Retail:Fixture and display case manufacturers consume processed glass in smaller lot sizes.
- Manufacturing:Appliance, electronics, and industrial equipment OEMs source specialty glass components.
Construction commands procurement scale. Transportation is gaining specification share.
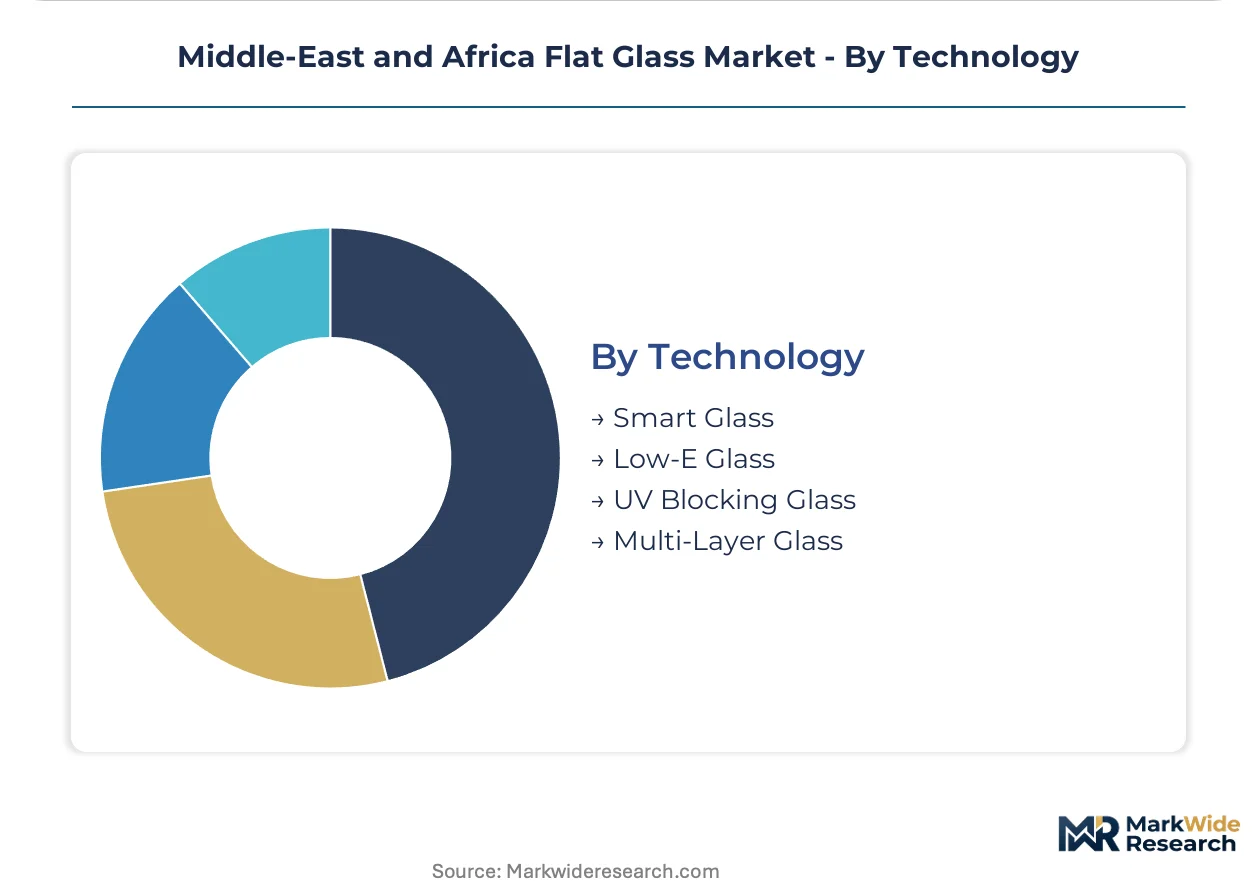
Technology:
Technology tiering separates premium specification from code-minimum compliance.
- Low-E Glass:Microscopically thin metallic coatings reduce thermal emissivity for building energy-code compliance. UAE Estidama Pearl ratings and Saudi building codes mandate low-E specification for commercial developments, creating baseline demand.
- Smart Glass:Electrochromic and thermochromic active coatings enable dynamic solar heat gain coefficient adjustment. Dubai and Riyadh premium commercial towers are specifying dynamic glazing at accelerating rates, displacing static low-E in high-performance facades.
- UV Blocking Glass:Absorptive or reflective treatments protect interior finishes and occupants from ultraviolet degradation.
- Multi-Layer Glass:Insulating glass units with multiple lites and gas fills deliver enhanced thermal performance for stringent energy targets.
Low-E glass holds specification ubiquity. Smart glass is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Middle-East and Africa. Gulf Cooperation Council buyers prioritize certified performance over price, while East African procurement remains acutely cost-sensitive, forcing suppliers to maintain divergent product portfolios.
United Arab Emirates
Dubai's megaproject pipeline consumes substantial tempered and laminated glass volumes for commercial tower envelopes. Estidama Pearl rating mandates compel developers to specify low-emissivity glazing for new construction. Abu Dhabi's manufacturing zone hosts integrated float-glass capacity serving regional export markets.
Saudi Arabia
Riyadh's contracting sector is redirecting procurement toward Saudi Standards, Metrology and Quality Organization-certified suppliers, eliminating uncertified import channels. The Kingdom's stricter building energy codes accelerate specification of low-emissivity products across commercial developments. Jeddah's industrial corridor concentrates domestic float-glass production serving domestic and Levant markets.
Egypt
Cairo-based integrated producers supply coated architectural glass across North Africa and the Levant, leveraging proximity to European export routes. The country's silica sand reserves anchor regional float-glass cost competitiveness. Alexandria's port infrastructure enables bulk raw material imports and finished product distribution.
South Africa
The National Regulator for Compulsory Specifications energy-performance requirements mandate higher thermal-performance glazing in new construction. Johannesburg's procurement teams specify certified products for commercial developments, compressing timelines for fabricator certification. Cape Town's renewable energy procurement channels multiply tempered glass demand for photovoltaic module encapsulation.
Morocco
The Noor Ouarzazate solar complex and utility-scale photovoltaic deployment accelerate tempered glass procurement for module encapsulation. Casablanca serves as a logistics hub for North African solar glass distribution. Domestic energy-code adoption lags Gulf standards, preserving price-sensitive procurement patterns in commercial construction.
Middle-East and Africa Flat Glass Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa flat glass market. Integrated float-glass producers with captive raw material supply command cost advantages in commodity substrates, while downstream fabricators with magnetron sputtering capabilities capture margin in coated value-add products. The competitive structure separates three archetypes: multinational integrated producers, regional float specialists, and downstream coating fabricators. Capacity expansion and certification-driven customer lock-in represent the dominant competitive moves as energy-code enforcement tightens.
Among multinational integrated producers, Saint-Gobain and Guardian Glass LLC occupy positions exemplifying scale-driven regional supply. Saint-Gobain leverages Egyptian and UAE manufacturing bases to serve North African and Levant markets. Guardian Glass LLC anchors its regional presence through Saudi Arabian float-glass production. These producers represent the archetype of backward-integrated supply serving code-compliant procurement channels.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Guardian Glass LLC |
| Sisecam Group |
| Nippon Sheet Glass Co. Ltd |
| Emirates Glass LLC |
| Saudi American Glass |
| Obeikan Glass Company |
| Misr Glass Manufacturing Co. |
| Others |
Supply & Pricing Matrix
Saudi Standards, Metrology and Quality Organization certification gates both supply qualification and price differentiation simultaneously, compressing uncertified imports into discount tiers while elevating compliant domestic and regional producers to premium positioning across Gulf Cooperation Council procurement channels.
Pricing Analysis
After-sales service contracts and extended warranty bundling drive lifetime value for coated glass fabricators serving megaproject developers. Three-tier pricing structure across premium certified, standard compliant, and economy import levels stratifies the market, with Estidama Pearl rating requirements and Saudi energy-code enforcement as the primary price differentiation drivers. Cost compression in economy float imports is intensifying because of raw material energy intensity and logistics penalties. East African commercial developers exhibit acute price sensitivity, while UAE megaproject procurement teams prioritize certified performance over unit cost.
Supply Chain Analysis
Port congestion at Jeddah and container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for Levant and East African markets dependent on Egyptian and Saudi float-glass output. Supply concentrates in Egypt, Saudi Arabia, and the United Arab Emirates, drawing from silica sand reserves, soda ash imports, and natural gas feedstock. Single-source vulnerability runs through the concentrated float-glass capacity base, with limited alternative supply for tempered and coated value-add processing. Distribution runs through direct manufacturer engagement with megaproject procurement teams, shortening traditional regional stockist channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart glass electrochromic technology and Gulf Cooperation Council energy-code harmonization constitute a high-growth disruption reshaping specification patterns and procurement timelines across Middle-East and Africa construction markets.
For Market Incumbents: Fortify certification portfolios across Saudi Standards, Metrology and Quality Organization and UAE Estidama frameworks to lock out uncertified import competition. Expand magnetron sputtering capacity in Saudi Arabia and the United Arab Emirates to capture premium coated glass margins threatened by coating technician skill scarcity. Deepen backward integration into silica sand processing to offset soda ash input volatility.
For New Entrants and Emerging Players: Certification fast-track partnerships with Saudi Standards, Metrology and Quality Organization and UAE green building regulators enable rapid market entry before enforcement timelines compress further. East African construction markets in Kenya and Ethiopia present the most penetrable geography, with undercertified low-E glazing specification creating first-mover positioning. Solar photovoltaic module encapsulation offers a specialized go-to-market angle bypassing architectural procurement concentration.
For Investors and Strategic Acquirers: Gulf Cooperation Council energy-code harmonization reshapes the acquisition landscape toward multi-country certified fabricators with captive coating capabilities. Long-term viability centers on players with demonstrated regulatory navigation capacity and established relationships with megaproject developers. Watch for Saudi Standards, Metrology and Quality Organization enforcement acceleration as the signal indicating certification-premium expansion and import-discount compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetron Sputtering Capacity Expansion | Captures premium low-E margins as Saudi and UAE energy-code enforcement tightens. |
| Multi-Country Certification Investment | Positions fabricators for Gulf Cooperation Council cross-border procurement efficiencies. |
| Backward Integration into Silica Sand | Offsets natural gas pricing volatility compressing non-integrated float-glass margins. |
| Solar-Grade Tempered Glass Line Addition | Accesses Morocco Noor Ouarzazate and South Africa PV pipeline demand channels. |
| Direct Developer Engagement Programs | Bypasses regional stockists as UAE and Saudi megaproject procurement consolidates supply sources. |
Research Methodology
Operator-level perspectives from float-glass plant managers, glazing subcontractor procurement leads, megaproject developer specification teams, and coating technician training directors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, Gulf Cooperation Council building code documentation, Saudi Standards, Metrology and Quality Organization certification registries, and utility-scale photovoltaic project databases. Bottom-up capacity and demand modeling triangulated against top-down construction spend and energy-code adoption trajectories.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement timelines and raw material pricing scenarios throughout the projection horizon. Segmentation dimensions modeled encompass product type, application, end user, and technology tier, with regional regulatory cluster and certification status as cross-cutting variables. CAGRs derived from fitted growth curves applied to base-year market sizing, with solar photovoltaic deployment intensity and commercial construction cycle timing as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained Gulf Cooperation Council energy-code enforcement and silica sand supply stability; material deviation would warrant model refresh. Forecasts reflect assumptions around certification timeline compression and megaproject pipeline continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Vitrification Market
Glass
Shatterproof Glass Market
Glass
Heat Resistant Glass Market
Glass
Technical Glass Market
Glass
Float Glass Market
Glass
Glass Substrate Market
Glass
Silica Sol Market
Glass
Global Glass Tempering System Market
Glass
Glass Insulator Market
Glass
Borosilicate Glass Market
Glass
Asia-Pacific Silica Sand Market
Glass
Glass Manufacturing Market
Glass
Coated Glass Market
Glass
Tempered Glass Market
Glass
Solar Control Glass Market
Glass
United States Flat Glass Market